
 Banking-As-A-Service (Baas) Platform Market | 2026-2036
Banking-As-A-Service (Baas) Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Banking-As-A-Service (Baas) Platform Market Outlook
PSD2 and its open-banking successor frameworks are repositioning the competitive threshold for payment initiation and account information services across Europe. Solaris SE leverages its full German banking license to sustain regulatory credibility with enterprise clients. Treasury Prime anchors its position through deep compliance tooling designed specifically for US charter requirements. Stripe Treasury competes by extending its existing merchant relationships into embedded financial products.
A Banking-As-A-Service platform delivers licensed banking infrastructure—spanning account provisioning, payment rails, and regulatory compliance—through API-accessible or white-label arrangements, enabling non-bank entities to embed financial services without obtaining charters themselves. The primary commercial purpose is decoupling financial product distribution from balance-sheet ownership, allowing technology firms to monetize deposits, lending, and payments under their own brands while the underlying bank manages capital requirements and supervision. API Integration occupies the dominant structural position due to developer-centric procurement patterns among fintech startups, though Embedded Banking represents the fastest-expanding margin pool as e-commerce platforms and software vendors seek native financial experiences. White-Label Solutions remain mature in the credit union segment, where member trust depends on institutional branding rather than third-party disclosure.
The European Banking Authority enforces strict technical standards for strong customer authentication and API performance, directly shaping product development roadmaps for platforms seeking passport rights across member states. In the United States, the Office of the Comptroller of the Currency and state regulators maintain fragmented charter requirements that force BaaS providers to navigate multi-jurisdictional compliance architectures. The Federal Reserve's FedNow instant payment network is forcing infrastructure upgrades that will separate platforms with real-time ledger capabilities from batch-dependent competitors. Stakeholders must monitor how divergence between EU payment service directives and US fintech charter experiments reshapes cross-border platform economics.
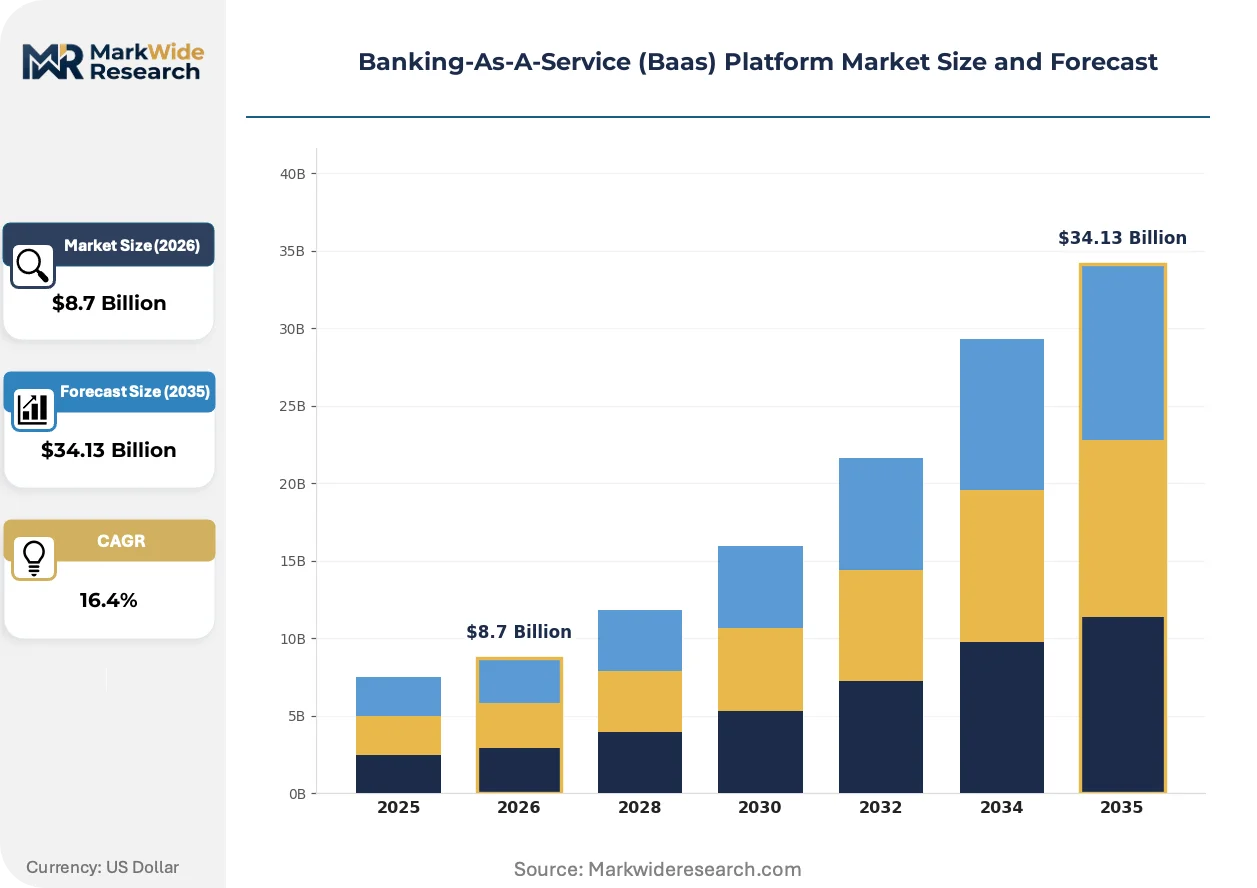
Market Dynamics
Embedded finance adoption among e-commerce platforms is forcing Banking-As-A-Service providers to rebuild core infrastructure around real-time ledger capabilities rather than batch processing systems.
Growth Catalysts
- PSD2 Technical Standards:The European Banking Authority's strong customer authentication mandates have standardized API performance benchmarks across member states, lowering integration friction for fintech entrants seeking passport rights.
- FedNow Instant Payments:The Federal Reserve's real-time settlement network is compelling infrastructure upgrades that separate platforms with native instant capabilities from legacy batch-dependent competitors.
- E-commerce Embedded Finance:Merchants on digital marketplaces now demand integrated payment initiation and lending capabilities as standard checkout features, pulling BaaS functionality deeper into retail software stacks.
Market Restraints
- Multi-jurisdictional Compliance Costs:Fragmented charter requirements across US state regulators and federal agencies force providers to maintain parallel compliance architectures, inflating operational overhead.
- Core Banking System Lock-in:Legacy ledger infrastructure at sponsor banks creates technical debt that slows API modernization and limits real-time product development.
- Balance Sheet Concentration Risk:Deposit aggregation at a limited pool of licensed sponsor banks exposes fintech clients to single-counterparty failure modes during supervisory enforcement actions.
Strategic Opportunities
- Credit Union White-Label Expansion:Member-owned institutions in the United States seek third-party banking infrastructure to deploy digital-first products without sacrificing institutional branding trust.
- AI-Enhanced Compliance Automation:Convergence of machine learning with regulatory reporting tools offers pathways to reduce Know-Your-Customer verification latency and transaction monitoring false positives.
- Cross-Border SME Banking:Small and medium enterprises operating across Germany, the Netherlands, and France require unified multi-currency accounts that domestic retail banks rarely provision.
Industry Challenges
- Embedded API Talent Scarcity:Engineering teams with combined expertise in financial services regulation and cloud-native architecture command premium compensation, constraining platform scaling velocity.
- Sponsor Bank Due Diligence Compression:Heightened supervisory scrutiny of Banking-As-A-Service relationships has elongated partner onboarding timelines from months to quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking-As-A-Service (Baas) Platform Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Account Management, Payment Processing, Compliance Tools, Customer Onboarding Integration Level: API Integration, White-Label Solutions, Embedded Banking, Customizable Platforms End User: Fintech Startups, Traditional Banks, E-commerce Platforms, Credit Unions Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Managed Services |
| Companies Covered | Solaris SE, Unit, Stripe Treasury, Treasury Prime, Synctera, Railsr, 10x Banking, Mambu, Marqeta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking-As-A-Service (Baas) Platform Market Strategic Shifts
Real-time payment infrastructure is expanding into embedded financial products, reshaping how software platforms monetize customer relationships.
Ledger-as-a-service technology is expanding into vertical SaaS applications, enabling property management systems and healthcare practice software to provision branded deposit accounts and payment cards. Mid-market software vendors with 10,000-plus customer bases are adopting these capabilities fastest, compressing the traditional separation between business operations and financial services.
The European Union's Digital Operational Resilience Act is imposing strict ICT risk management requirements on financial entities and their critical third-party providers. BaaS platforms serving EU-domiciled fintechs must now demonstrate end-to-end service continuity testing and incident reporting protocols. German-licensed infrastructure providers are responding by hardening multi-tenant architectures against systemic operational failures.
Enterprise procurement of banking infrastructure is consolidating around outcome-based commercial models rather than per-API call pricing. Large fintechs now demand guaranteed uptime service level agreements with penalty clauses, displacing usage-based contracts that dominated early-stage vendor relationships. This shift is most visible among payment processors in the United Kingdom and Ireland seeking predictable cost structures at scale.
Banking-As-A-Service (Baas) Platform Market Segmentation
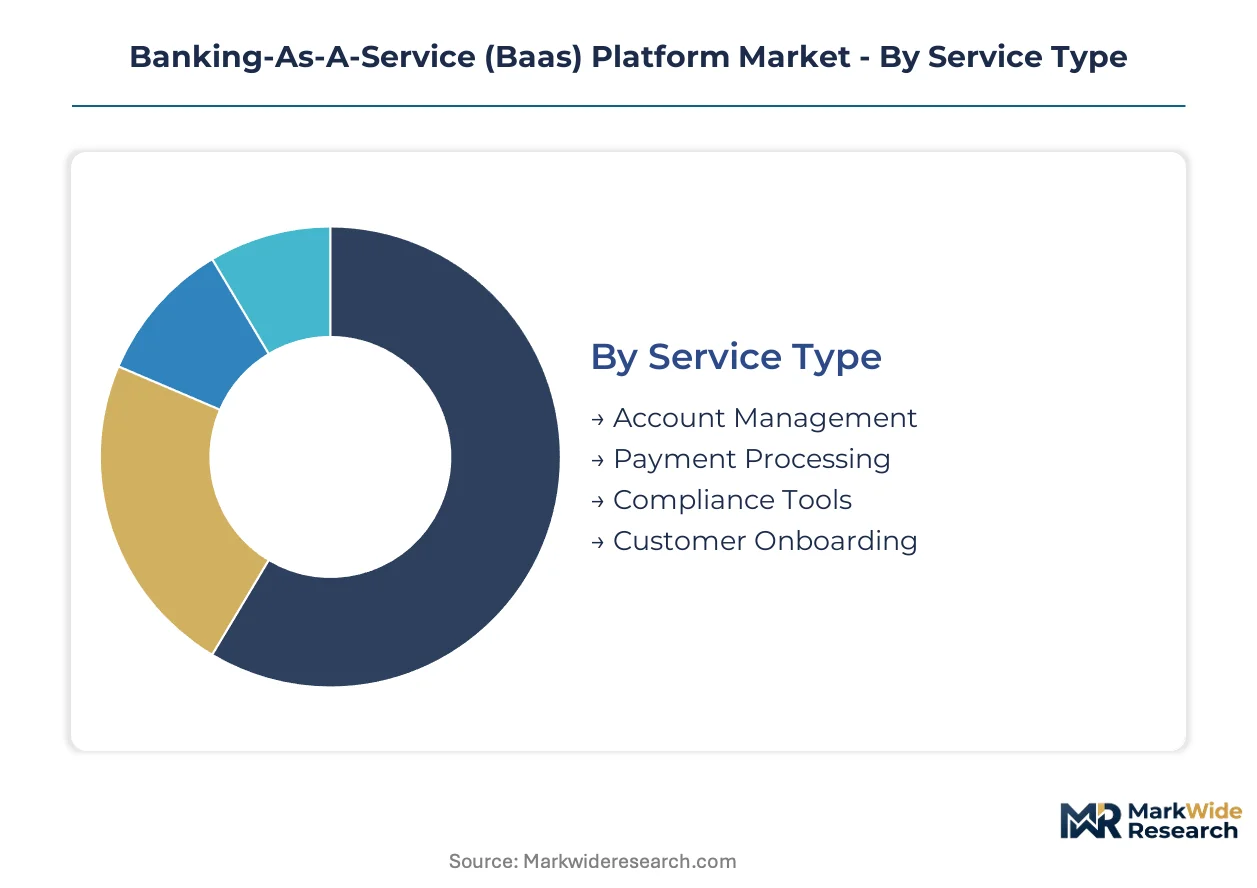
Banking-as-a-Service procurement patterns diverge sharply across buyer sophistication and regulatory exposure. Platform selection hinges on whether the client seeks developer-centric speed, brand-controlled experiences, or turnkey compliance outsourcing.
Service Type:
Buyers prioritize functional depth based on their regulatory maturity and product roadmap velocity.
- Account Management:Core ledger infrastructure provisions multi-currency accounts, virtual IBAN generation, and sub-account hierarchies through RESTful APIs. Demand concentrates among German and Dutch neobanks expanding into pan-European deposit-taking, driven by passporting rights under ECB supervision.
- Payment Processing:Real-time rail connectivity spans SEPA Instant, FedNow, and Faster Payments with automated reconciliation engines. E-commerce marketplaces in the United Kingdom and Ireland embed these capabilities at checkout, pulled by merchant demands for instant settlement and reduced chargeback exposure.
- Compliance Tools:Automated KYC/AML orchestration with configurable risk scoring rules.
- Customer Onboarding:Identity verification workflows with document liveness detection and biometric matching.
Account Management leads on scale; Payment Processing leads on momentum.
Integration Level:
Technical architecture choices reflect trade-offs between time-to-market and brand control.
- API Integration:Direct developer access to banking primitives through documented endpoints with sandbox environments. Fintech startups in Berlin and London procurement teams favor this model for its iteration speed and minimal vendor lock-in.
- Embedded Banking:Native financial products surfaced within third-party software interfaces without redirecting users. Vertical SaaS vendors serving US property management and healthcare practice segments adopt this fastest, monetizing captive customer bases through interchange revenue sharing.
- White-Label Solutions:Fully branded banking experiences with hidden infrastructure provider attribution.
- Customizable Platforms:Modular component libraries allowing selective feature activation.
API Integration dominates current deployment volumes; Embedded Banking exhibits the steepest expansion trajectory.
End User:
Buyer category determines pricing tolerance and contractual complexity.
- Fintech Startups:Venture-backed entrants seeking licensed infrastructure without charter acquisition costs. Concentrated in Paris and Madrid accelerators, these buyers prioritize sandbox speed and per-transaction pricing over enterprise service levels.
- E-commerce Platforms:Digital marketplaces integrating payment initiation and lending at checkout. German and French merchant aggregators drive demand for unified multi-currency capabilities spanning domestic and cross-border transactions.
- Traditional Banks:Incumbent institutions modernizing legacy cores through partnership models.
- Credit Unions:Member-owned US institutions deploying digital channels while preserving institutional identity.
Fintech Startups anchor volume concentration; E-commerce Platforms command the fastest contract value growth.
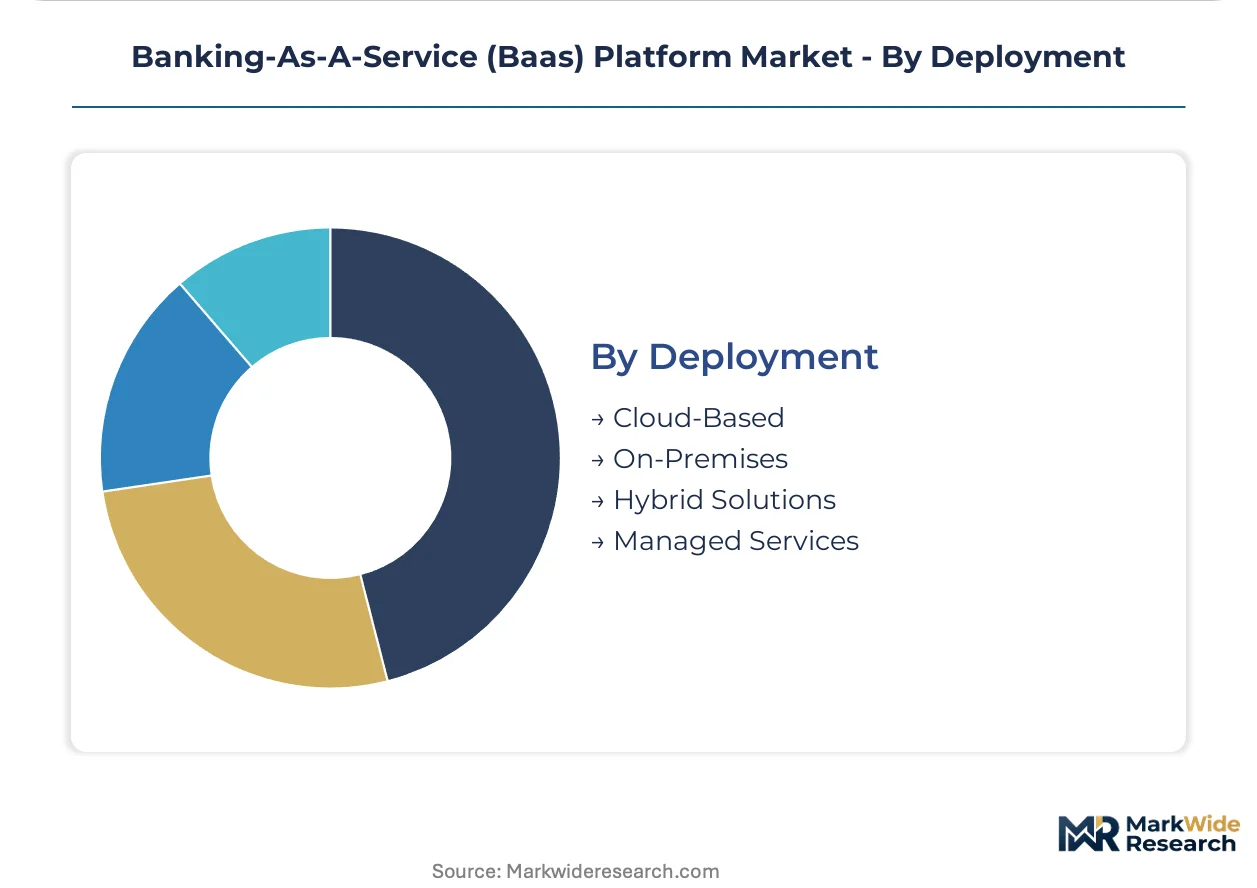
Deployment:
Infrastructure location decisions balance latency requirements against data sovereignty constraints.
- Cloud-Based:Multi-tenant architectures with elastic scaling across AWS, Azure, or GCP regions. Preferred by UK and Irish payment processors seeking FedNow and SEPA Instant connectivity without capital-intensive hardware procurement.
- Hybrid Solutions:Sensitive data residency on-premises with compute bursting to public cloud. German-licensed providers serving EU-domiciled fintechs adopt this model to satisfy Digital Operational Resilience Act requirements while maintaining API performance.
- On-Premises:Dedicated hardware installations with full operational control.
- Managed Services:Outsourced infrastructure operations with guaranteed uptime commitments.
Cloud-Based deployments capture the majority of new contracts; Hybrid Solutions are gaining share fastest among regulated EU entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Berlin, London, and San Francisco anchor Banking-As-A-Service platform development. Regulatory divergence between jurisdictions creates distinct competitive moats for locally licensed providers.
United States
Venture-backed fintechs in San Francisco and New York drive API procurement volumes. The Federal Reserve's FedNow instant payment network forces infrastructure upgrades that separate real-time capable platforms from batch-dependent competitors. Treasury Prime and Synctera anchor compliance-focused offerings targeting multi-state charter complexity.
Germany
ECB-supervised passporting rights attract cross-border fintech clients seeking unified European coverage. The Digital Operational Resilience Act imposes strict ICT risk management requirements on critical third-party providers. Solaris SE and Railsr in Berlin sustain dense clusters of licensed banking infrastructure serving pan-European neobanks.
United Kingdom
Payment processors in London demand guaranteed uptime service level agreements with penalty clauses. The Financial Conduct Authority's operational resilience rules shape vendor selection criteria for e-commerce platforms. Embedded banking adoption concentrates among vertical SaaS vendors serving property management and healthcare segments.
Netherlands
Amsterdam-based fintechs prioritize multi-currency account provisioning for SME cross-border trade. Dutch central bank supervision aligns with ECB technical standards for strong customer authentication. Payment processing capabilities concentrate around SEPA Instant connectivity for merchant aggregators.
France
Paris accelerator networks incubate early-stage entrants seeking sandbox speed over enterprise service levels. Autorité de Contrôle Prudentiel et de Résolution oversight shapes compliance tool procurement for payment initiation services. E-commerce platforms in Île-de-France embed lending capabilities at checkout as standard features.
Banking-As-A-Service (Baas) Platform Market Competitive Environment
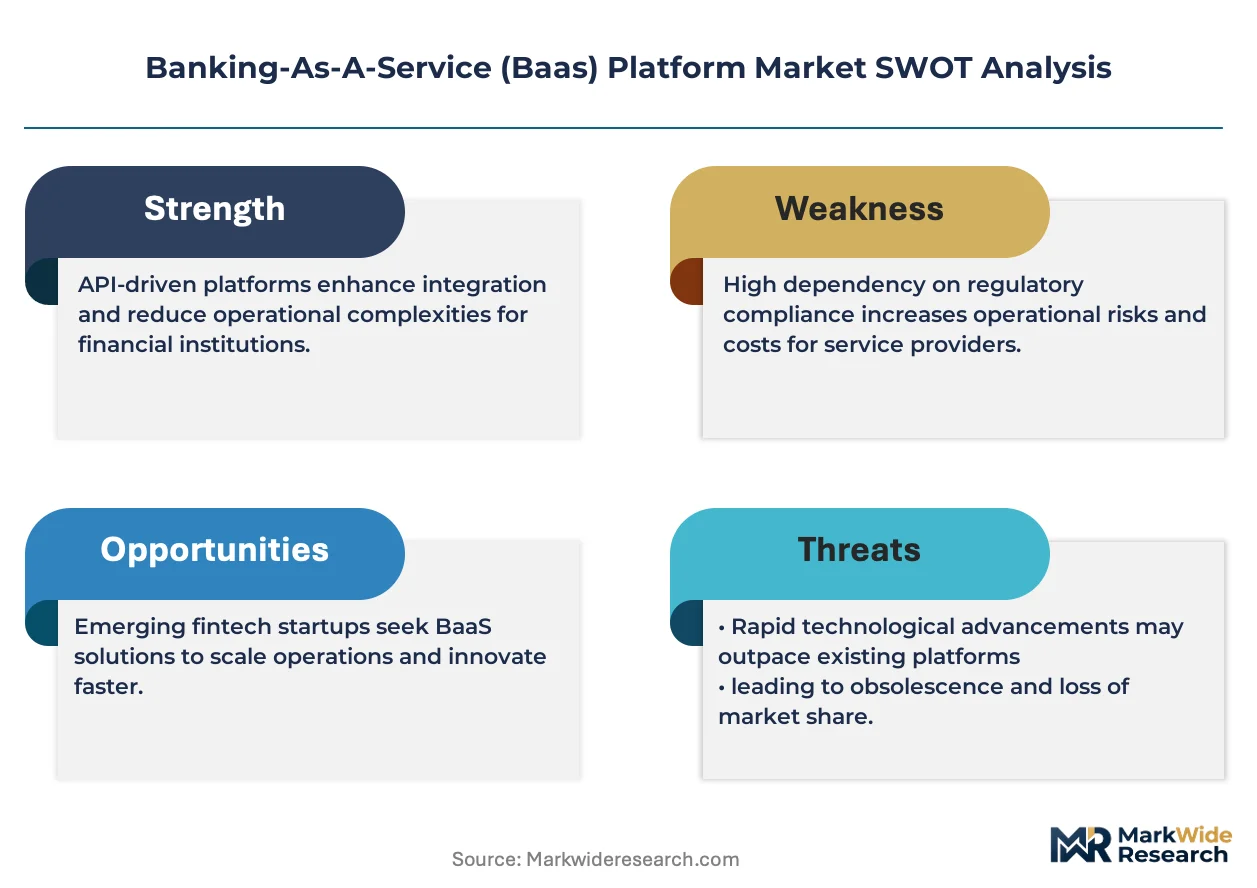
The competitive structure tilts toward licensed infrastructure specialists with regulatory credibility in multiple jurisdictions. Sponsor bank relationships and compliance automation depth determine tier placement. Three archetypes dominate: full-stack German banks with ECB passports, US-focused compliance tooling specialists, and merchant-relationship extenders from payments incumbents. M&A activity concentrates on acquiring charter capabilities, while strategic partnerships address multi-jurisdictional coverage gaps.
Among German-licensed full-stack providers, Solaris SE and Railsr exemplify the regulatory credibility archetype, leveraging ECB supervision to serve cross-border fintech clients. Stripe Treasury occupies a position as the merchant-relationship extender, building on existing payment processing relationships to embed financial products. Treasury Prime represents the compliance-first US specialist, targeting fragmented charter requirements across state and federal regulators.
| Leading Market Players |
|---|
| Solaris SE |
| Unit |
| Stripe Treasury |
| Treasury Prime |
| Synctera |
| Railsr |
| 10x Banking |
| Mambu |
| Marqeta |
| Others |
Value Chain & Pricing Dynamics
E-commerce platform procurement teams in Germany and the United Kingdom anchor demand concentration for Banking-As-A-Service infrastructure, pulling contract structures toward outcome-based commercial models with guaranteed uptime service level agreements rather than per-API call pricing.
Pricing Analysis
Bundled compliance-automation suites command premium positioning against unbundled API-access tiers. Three-tier pricing structure across enterprise, growth-stage, and startup levels separates clients by regulatory exposure and transaction volume. Pricing pressure stems from FedNow infrastructure upgrade costs compressing margins for batch-dependent providers. Fintech startups in Paris and Madrid accelerators exhibit highest price sensitivity; pan-European neobanks with passporting rights show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German-licensed sponsor banks holding ECB passport rights for cross-border coverage. Core banking infrastructure draws from Germany, the United Kingdom, and the United States. Critical dependencies span real-time ledger technology, strong customer authentication modules, and cloud compute capacity. Tariff exposure on cross-border data flows threatens multi-jurisdictional architectures. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Banking-As-A-Service market functions as a regulatory compounder where PSD2 technical standards and FedNow instant payment mandates continuously expand compliant infrastructure demand.
For Market Incumbents: Hedge sponsor bank concentration risk by diversifying across at least three licensed jurisdictions. Deepen API performance benchmarking against ECB strong customer authentication requirements. Acquire embedded banking specialists before vertical SaaS vendors internalize financial product development. For New Entrants and Emerging Players: AI-enhanced compliance automation offers the most penetrable wedge for unseating established KYC/AML orchestration providers. Target credit union white-label segments in the United States where member trust barriers protect institutional branding. Lead with sandbox speed and per-transaction pricing against enterprise incumbents. For Investors and Strategic Acquirers: Payment processors with existing merchant relationships are the most active acquirer in this space, seeking to extend interchange revenue into deposit-taking. Charter capabilities in Germany or the United Kingdom represent the scarcest acquisition target archetype. Watch for elongated sponsor bank due diligence timelines as an inflection indicator for regulatory tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Charter Capability Acquisition | German ECB passport rights unlock pan-European deposit-taking without multiple national licenses. |
| Real-Time Ledger Modernization | FedNow native capabilities separate platforms from batch-dependent competitors in US procurement. |
| Vertical SaaS Partnership | Property management and healthcare software vendors monetize captive bases through interchange sharing. |
| AI Compliance Automation | Machine learning reduces KYC verification latency and transaction monitoring false positives. |
| Cross-Border SME Banking | Multi-currency accounts for German-Dutch-French trade corridors address unmet demand from domestic retail banks. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each combining structured interviews with BaaS platform executives, sponsor bank compliance officers, fintech CTOs, and vertical SaaS procurement leads alongside secondary validation through ECB regulatory filings, Federal Reserve payment system disclosures, and cloud provider infrastructure reports. Bottom-up transaction volume estimates triangulate against top-down market sizing.
Granularity-level modeling addresses service type, integration level, end user category, and deployment architecture across the projection horizon. CAGRs derive from segment-level growth rate blending. Forecast inputs include embedded finance adoption curves among e-commerce platforms and real-time payment infrastructure upgrade timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sponsor bank supervisory enforcement actions and divergent fintech charter experiments between EU and US jurisdictions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Virtual Teller Machine (VTM) Market
Banking
North America Data Analytics in Banking Market
Banking
Global Retail Core Banking Systems Market
Banking
Cloud Billing in Banking Market
Banking
Global IoT in Banking and Financial Services Market
Banking
Voice Banking Market
Banking
Corporate Banking Market
Banking
Merchant Banking Services Market
Banking
South Korea Data Analytics in Banking Market
Banking
Banking ERP Software Market
Banking
UK Banking as a Service Market
Banking
Retail Banking IT Spending Market
Banking
Asia-Pacific Challenger Banks Market
Banking
Bank Guarantee Market
Banking
Canada Data Analytics in Banking Market
Banking
Core Banking Solutions Market