
 Global Automated Hospital Beds Market | 2026-2036
Global Automated Hospital Beds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Hospital Beds Market Foresight
CE marking under the EU Medical Device Regulation is bifurcating the competitive landscape into qualified incumbents and excluded challengers. Stryker Corporation leverages its vertically integrated manufacturing footprint across North America and Europe to sustain compliance leadership. Getinge AB anchors its position through specialized critical care configurations that dominate the intensive care application segment. Hill-Rom Holdings differentiates via channel control in integrated delivery networks, occupying preferred supplier status with major hospital systems.
Automated hospital beds are electromechanical patient support platforms incorporating motorized height adjustment, trendelenburg positioning, and integrated scale systems for continuous weight monitoring. These beds serve primarily to reduce caregiver injury, prevent pressure ulcers, and enable rapid patient repositioning in acute and post-acute settings. Electric beds command the dominant product type position due to reimbursement alignment and nursing workflow efficiency. Smart beds and telemetry systems within the technology dimension represent the fastest-expanding margin pool as hospitals prioritize fall prevention and remote monitoring integration. The long-term care application segment matures comparatively as budget constraints limit capital replacement cycles in nursing facilities.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development timelines and market access costs for automated bed manufacturers. ISO 13485 quality management certification functions as a baseline qualifier for contract eligibility with large health systems and group purchasing organizations. Stakeholders must monitor evolving cybersecurity standards for connected bed platforms as IoT-enabled devices proliferate in hospital networks.
Market Dynamics
EU MDR compliance compression is forcing accelerated vendor consolidation as smaller manufacturers face insurmountable technical documentation costs and notified body capacity constraints. The regulatory barrier is restructuring competitive access before product differentiation even enters procurement discussions.
Growth Catalysts
- EU MDR CE marking mandates:Tertiary hospitals in Germany and France now require certified automated beds for intensive care unit accreditation, eliminating non-compliant suppliers from tender eligibility.
- Pressure ulcer prevention protocols:Motorized repositioning systems reduce HAPI incidence in acute care settings, aligning with CMS quality metrics and Japanese Ministry of Health reimbursement incentives.
- Japan's super-aging trajectory:Patient acuity in Tokyo and Osaka metropolitan hospitals drives replacement of manual beds with electromechanical platforms supporting bariatric and critical care loads.
Market Restraints
- Steel and linear actuator cost volatility:Input material fluctuations compress margin stability for mid-tier manufacturers dependent on outsourced electromechanical components.
- Notified body concentration in EU:Only twelve designated bodies handle MDR technical file reviews, creating 14-18 month clearance bottlenecks for new market entrants.
- Refurbished bed substitution:Secondary market reconditioning extends asset life in budget-constrained long-term care facilities, displacing new unit demand in nursing homes.
Strategic Opportunities
- India's hospital infrastructure expansion:PLI scheme incentives for medical device manufacturing attract automated bed assembly investments serving Delhi-Mumbai corridor demand.
- IoT-telemetry convergence:Integration of continuous weight monitoring with EMR systems creates premium positioning for smart bed platforms in integrated delivery networks.
- US IRA domestic production credits:Nearshoring incentives support North American manufacturing footprint expansion for vendors serving Veterans Health Administration and military hospital systems.
Industry Challenges
- Cybersecurity engineering talent scarcity:ISO 27001 and FDA cybersecurity guidance compliance requires embedded systems expertise that competes with automotive and aerospace sectors for limited personnel pools.
- Legacy fleet integration complexity:Telemetry-enabled beds must interface with heterogeneous nurse call and building management systems across hospital campuses, extending deployment timelines and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Hospital Beds Market |
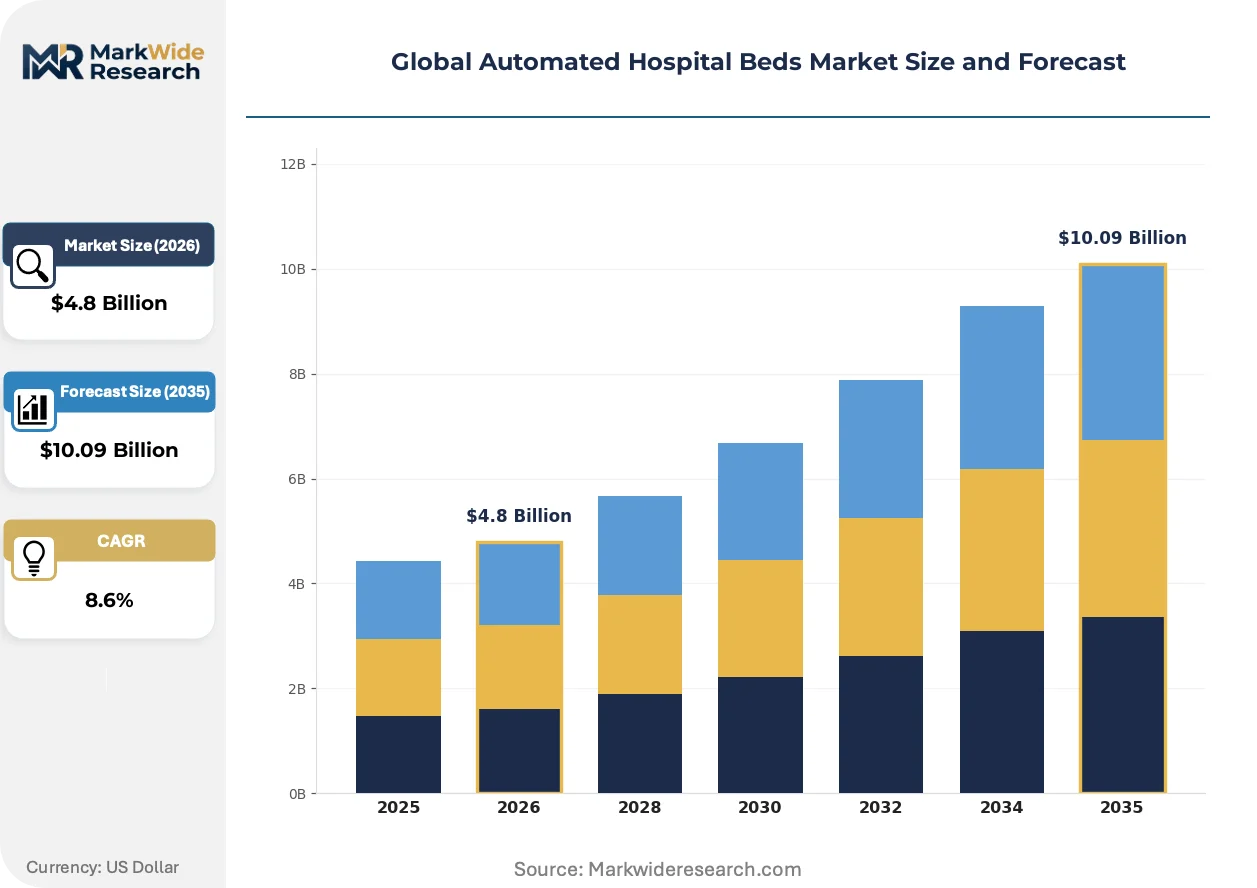
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Beds, Manual Beds, Adjustable Beds, Low Beds End User: Hospitals, Clinics, Nursing Homes, Home Care Technology: Smart Beds, Pressure Relief Systems, Telemetry Systems, IoT-Enabled Beds Application: Intensive Care, Surgical, Rehabilitation, Long-Term Care |
| Companies Covered | Stryker Corporation, Hill-Rom Holdings, Getinge AB, Invacare Corporation, Paramount Bed Holdings, Arjo, Medline Industries, LINET Group SE, Joerns Healthcare LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Hospital Beds Market Shifts & Advancements
Electromechanical patient support platforms are converging with digital health infrastructure, transforming beds from passive furniture into active clinical data nodes. This integration is compressing traditional equipment procurement cycles and reshaping vendor-hospital relationships around continuous service rather than discrete capital transactions.
Predictive fall detection algorithms using load cell arrays and machine learning classification are supplanting conventional bed exit alarms in tertiary care settings. Intensive care units at Johns Hopkins and Charité Berlin have piloted these systems, reducing unassisted patient falls by enabling preemptive nursing intervention before vertical displacement occurs. The technology is compressing liability exposure and malpractice premium structures for early adopters.
FDA's 2023 cybersecurity guidance for connected medical devices mandates SBOM documentation and vulnerability disclosure protocols for networked hospital beds. Manufacturers must now embed software update mechanisms and incident response capabilities into product architectures, elevating development costs but creating compliance-based segmentation between resourced incumbents and capital-constrained challengers. Pediatric and psychiatric bed categories face the steepest adaptation curves due to specialized restraint and safety interlock requirements.
Hospital capital committees are unbundling equipment acquisition from full-service maintenance contracts, shifting toward third-party ISO 13485-certified service providers for post-warranty support. This disintermediation pressures OEMs to defend recurring revenue through proprietary telemetry subscriptions rather than captive service agreements. The pattern is most pronounced in Texas and Florida health systems where independent service organizations have captured 30-40% of preventive maintenance volume for beds outside manufacturer warranty periods.
Global Automated Hospital Beds Market Segmentation
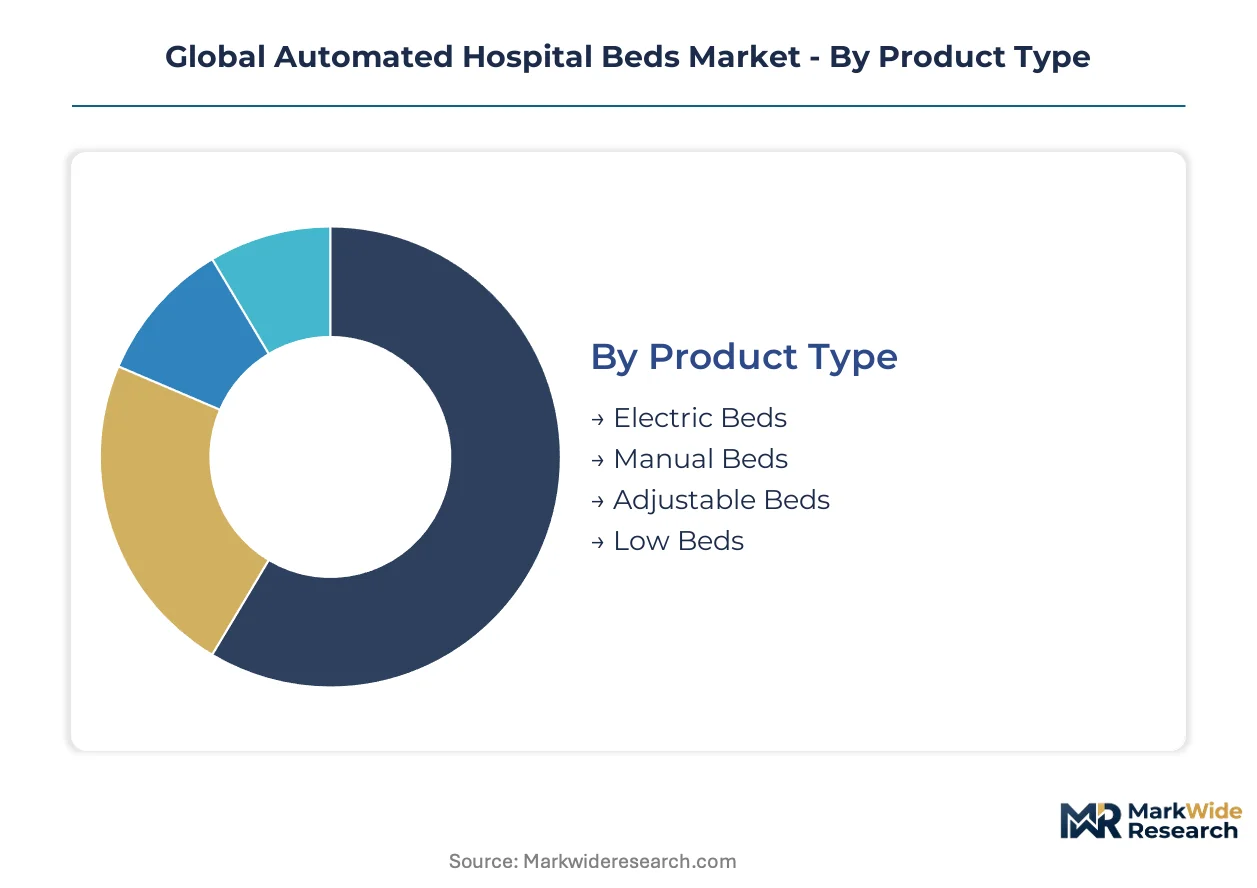
Automated hospital beds segment across multiple dimensions that determine procurement criteria, reimbursement pathways, and technology integration requirements. Product type and technology classifications shape capital allocation decisions in acute care facilities, while end-user and application segments dictate regulatory compliance burdens and service intensity.
Product Type:
Electric beds dominate domestic manufacturing footprints in the United States and Germany, while manual and low-bed variants sustain export-led production from India and Turkey serving price-sensitive markets.
- Electric Beds:Fully motorized platforms with integrated height adjustment, trendelenburg positioning, and battery backup systems. Demand concentrates in tertiary hospitals across the United States, Germany, and Japan where CMS and EU reimbursement frameworks favor electromechanical solutions over manual alternatives.
- Manual Beds:Hand-crank operated frames with mechanical height and head/foot section adjustment. Procurement persists in rural Indian and Southeast Asian facilities where capital constraints and unreliable electrical infrastructure limit electromechanical adoption.
- Adjustable Beds:Hybrid platforms combining powered positioning with manual backup systems for emergency scenarios. Brazilian and Mexican hospitals favor these configurations for their resilience in grid-unstable environments.
- Low Beds:Deck-height-minimized designs for fall-risk populations in geriatric and psychiatric wards. Japanese long-term care facilities specify these units under METI safety guidelines for super-aging patient populations.
Electric beds command the established base. The steepest expansion runs through low-bed configurations for fall-prevention protocols.
End User:
Cost tier stratification separates capital-rich acute care institutions from budget-constrained post-acute and residential settings, with reimbursement eligibility driving technology tier selection.
- Hospitals:Tertiary and secondary acute care facilities requiring full-featured platforms with telemetry integration and EMR connectivity. German university hospitals and US integrated delivery networks specify FDA 510(k) and EU MDR-compliant units for intensive care accreditation.
- Clinics:Ambulatory surgical and specialty diagnostic centers with lower bed utilization rates and reduced acuity requirements. Day-surgery centers in France and Italy prioritize compact electric models with rapid turnover features.
- Nursing Homes:Skilled nursing facilities facing Medicaid reimbursement compression and extended asset replacement cycles. Refurbished electric beds displace new units in Texas and Florida facilities where independent service organizations capture maintenance volume.
- Home Care:Residential settings with informal caregiver support and limited clinical oversight. Japan's Ministry of Health rental subsidy programs and German long-term care insurance drive demand for lightweight, transportable electric models.
Hospitals absorb the premium technology tiers. Home care represents the fastest-climbing volume segment as aging-in-place policies expand.
Technology:
Volume concentration sits with established electromechanical platforms, while margin expansion concentrates in connected and sensor-integrated systems requiring specialized engineering talent.
- Smart Beds:AI-enabled platforms with predictive analytics for fall prevention, pressure ulcer risk scoring, and automated repositioning schedules. Johns Hopkins and Charité Berlin have deployed these systems, reducing unassisted falls through preemptive nursing alerts.
- Pressure Relief Systems:Alternating air mattress surfaces and low-air-loss technologies for HAPI prevention. CMS quality metrics and Japanese reimbursement incentives accelerate specification in US and Japanese acute care settings.
- Telemetry Systems:Continuous weight monitoring and vital sign transmission integrated with nurse call infrastructure. Deployment complexity extends timelines in heterogeneous hospital campuses with legacy building management systems.
- IoT-Enabled Beds:Networked platforms with SBOM documentation, vulnerability disclosure protocols, and over-the-air update capabilities per FDA cybersecurity guidance. Development costs elevate for pediatric and psychiatric variants with specialized safety interlocks.
Pressure relief systems anchor current installed base. Smart beds are gaining share fastest through predictive analytics differentiation.
Application:
Maturity gradients separate high-acuity segments with compressed replacement cycles from long-term care applications where budget constraints extend asset lifespans.
- Intensive Care:Critical care units requiring bariatric load capacity, radiolucent deck surfaces, and integrated patient lifting. Stryker and Getinge dominate German and French tertiary hospital tenders where EU MDR CE marking is mandatory for accreditation eligibility.
- Surgical:Operating room and post-anesthesia care units needing rapid position changes and C-arm compatibility. US ambulatory surgery centers specify these units for same-day discharge workflows.
- Rehabilitation:Physical therapy and stroke recovery settings emphasizing early mobilization features and standing assist functions. Veterans Health Administration facilities prioritize domestic-manufactured units under IRA production credit incentives.
- Long-Term Care:Skilled nursing and assisted living environments with lower technology requirements and extended depreciation schedules. Secondary market reconditioning displaces new unit demand in budget-constrained facilities.
Intensive care holds the premium positioning. Rehabilitation is expanding most quickly through early mobilization protocol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in tertiary acute care facilities drive regional demand concentration. Integrated delivery networks in the United States and university hospital systems in Germany command premium electromechanical platforms. Japan's super-aging metropolitan corridors accelerate replacement cycles for bariatric and critical care configurations.
United States
Veterans Health Administration and military hospital systems anchor federal procurement volume. IRA domestic production credits incentivize North American manufacturing footprint expansion. Texas and Florida health systems concentrate third-party service organization activity for post-warranty maintenance.
Germany
Charité Berlin and university hospital networks mandate EU MDR CE marking for intensive care unit accreditation eligibility. BfArM and notified body oversight compress vendor qualification timelines to fourteen-month windows. Bavaria and North Rhine-Westphalia cluster domestic electromechanical bed assembly serving French and Benelux export demand.
Japan
Tokyo and Osaka metropolitan hospitals face acute patient acuity escalation from super-aging demographics. METI safety guidelines specify low-bed configurations for geriatric fall prevention. Ministry of Health reimbursement incentives accelerate motorized repositioning system adoption in acute care wards.
India
Delhi-Mumbai corridor hospital infrastructure expansion drives automated bed demand from private tertiary chains. PLI scheme incentives attract medical device manufacturing investments for domestic assembly. CDSCO regulatory alignment with ISO 13485 standards shapes contract eligibility for large health system procurement.
France
ANSM oversight converges with EU MDR technical documentation requirements for connected bed platforms. Île-de-France and Auvergne-Rhône-Alpes regions concentrate public hospital tender activity for intensive care configurations. Day-surgery centers prioritize compact electric models with rapid turnover features for ambulatory workflows.
Global Automated Hospital Beds Market Competitive Landscape
Player mix skews toward vertically integrated electromechanical specialists and diversified medical technology conglomerates. Three to five incumbent manufacturers control premium tier access through FDA 510(k) and EU MDR certification portfolios. Market structure bifurcates between compliance-resourced leaders and capital-constrained challengers facing notified body bottlenecks. Dominant competitive moves center on M&A for regulatory capacity acquisition and strategic partnerships for telemetry-EMR integration.
Within the diversified medical technology tier, Stryker Corporation and Hill-Rom Holdings occupy positions exemplifying vertically integrated manufacturing footprints across North America and Europe. Getinge AB represents the specialized critical care archetype with concentrated intensive care application focus. These three entities anchor the premium segment through compliance leadership and channel control in integrated delivery networks.
| Leading Market Players |
|---|
| Stryker Corporation |
| Hill-Rom Holdings |
| Getinge AB |
| Invacare Corporation |
| Paramount Bed Holdings |
| Arjo |
| Medline Industries |
| LINET Group SE |
| Joerns Healthcare LLC |
| Others |
Supply & Pricing Matrix
EU MDR CE marking gates both supplier qualification and price differentiation simultaneously, compressing vendor pools to certified incumbents while elevating compliance premiums for intensive care configurations. Steel and linear actuator cost volatility feeds directly into contract indexation clauses, reshaping procurement negotiations across German and Japanese hospital systems.
Pricing Analysis
Cost-plus contracts with steel and electronics indexation dominate long-term supply agreements for integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared telemetry platforms from basic electric configurations and manual alternatives. Pricing pressure stems from refurbished bed substitution in nursing home segments. Budget-constrained long-term care facilities exhibit highest price sensitivity, while tertiary ICU procurement committees prioritize compliance certification over unit cost.
Supply Chain Analysis
Inventory buffers for linear actuators and control systems now stretch to 16-20 weeks as notified body bottlenecks compress order-to-delivery windows. Manufacturing concentrates in the United States, Germany, and China, with Bavaria and North Rhine-Westphalia clustering electromechanical assembly for French and Benelux export demand. Supply chains rest on cold-rolled steel, precision motors, and medical-grade polymers. Single-source vulnerability concentrates in semiconductor components for IoT-enabled platforms. Distribution runs through group purchasing organizations and direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance compression constitutes a high-growth disruption, eliminating non-certified challengers while expanding premium addressable market for qualified incumbents serving tertiary ICU accreditation requirements.
For Market Incumbents: Shield market position through accelerated notified body capacity acquisition and backward integration into linear actuator production. Consolidate service infrastructure in Texas and Florida where independent service organizations have captured post-warranty maintenance volume. Prioritize embedded cybersecurity engineering to defend telemetry-enabled platforms against capital-constrained competitors.
For New Entrants and Emerging Players: Anchor in India's Delhi-Mumbai corridor hospital infrastructure expansion, where PLI scheme incentives reduce capital barriers for domestic assembly. Target compact electric configurations for ambulatory surgical centers in France and Italy. Pursue ISO 13485 certification as baseline qualifier for GPO contract eligibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core bed manufacturing units. Long-term viability centers on telemetry-EMR integration capabilities across the analysis window. Monitor notified body designation expansion as inflection indicator for competitive access relaxation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Notified body designation unlocks German and French tertiary hospital tender eligibility. |
| Hospital System Partnership | Preferred supplier status with integrated delivery networks secures multi-year contract visibility. |
| Software Companion Development | Predictive fall detection algorithms differentiate smart bed platforms at Johns Hopkins and Charité Berlin. |
| Reimbursement Strategy | CMS quality metrics alignment accelerates motorized repositioning specification in US acute care. |
| Backward Integration | In-house linear actuator production insulates margin stability from steel cost volatility. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions. Primary fieldwork with clinicians and procurement officers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up unit demand modeling and top-down market sizing triangulated on segment-level outputs.
Segmentation dimensions modeled span product type, technology tier, end-user facility, and application acuity across the projection horizon. CAGRs derive from patient admission growth, replacement cycle compression, and regulatory-driven upgrade mandates. Forecast inputs incorporate steel price trajectories, notified body capacity constraints, and super-aging demographic curves in Japan.
Material uncertainties — notified body designation delays, steel cost spikes, cybersecurity incident responses — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and reimbursement continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Furniture
Clinical Chairs Market
Medical Furniture
Intensive Care Beds Market
Medical Furniture
Global Smart Hospital Bed Market
Medical Furniture
Healthcare Smart Beds Market
Medical Furniture
Global Stretcher Chairs Market
Medical Furniture
Healthcare Flooring Market
Medical Furniture
Medical Walker Market
Medical Furniture
Global Chemotherapy Chairs Market
Medical Furniture
Medicine Cabinets Market
Medical Furniture
Medical Commodes Market
Medical Furniture
Asia-Pacific Hospital Furniture Market
Medical Furniture
Electrical Hospital Beds Market
Medical Furniture
Hospital Beds Market
Medical Furniture
Medical Mattress Market
Medical Furniture
North America Hospital Furniture Market
Medical Furniture
Asia-Pacific Hospital Bed Market