
 Qatar Hair Care Market | 2026-2036
Qatar Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Hair Care Market Analytics
Buyer concentration among salon professionals is restructuring Qatar's hair care procurement patterns, with independent stylists and franchise chains fragmenting historically brand-loyal consumer flows. L'Oréal S.A. leverages its professional division to anchor salon-exclusive distribution across Doha and Al Rayyan. Henkel AG & Co. KGaA competes through Schwarzkopf-branded technical color systems positioned for high-temperature climate performance. Unilever PLC sustains mass-market penetration via supermarket and hypermarket shelf dominance.
Hair care encompasses formulations designed to cleanse, condition, protect, or style human hair, typically incorporating surfactant bases at pH 4.5–5.5 alongside silicones, proteins, or botanical extracts to manage keratin integrity in arid conditions. Shampoo and conditioner categories command the largest volume share, though hair oil segments exhibit the fastest growth trajectory as consumers seek thermal and UV protection suited to Gulf climates. Salon professionals represent the highest-margin end-user channel, while online retail is displacing traditional beauty stores among younger demographics seeking international niche brands.
Qatar's Ministry of Public Health (MoPH) mandates cosmetic product registration with full ingredient disclosure, while the Qatar General Organization for Standardization (QS) enforces labeling and safety standards aligned with Gulf Cooperation Council technical regulations. These frameworks elevate compliance costs for new entrants but simultaneously reinforce consumer trust in verified formulations. Stakeholders must monitor evolving MoPH registration timelines and QS harmonization with Saudi SFDA standards, as regulatory convergence across GCC markets will determine which suppliers can scale efficiently without duplicative certification burdens.
Market Dynamics
Qatar's hair care sector is restructuring around salon professional procurement dominance, as independent stylists and franchise chains fragment historically brand-loyal consumer flows and elevate technical-grade product demand across Doha and Al Wakrah.
Growth Catalysts
- MoPH Registration Standards:Qatar's Ministry of Public Health tightening ingredient disclosure requirements reinforces consumer trust in verified formulations and accelerates formal channel migration.
- High-Temperature Climate Performance:Technical color systems engineered for Gulf heat stress are expanding professional service attach rates in salon environments.
- Al Wakrah Corridor Expansion:Beauty retail footprint growth in Qatar's secondary metropolitan zone is extending premium product access beyond Doha's traditional concentration.
Market Restraints
- Silicone Import Concentration:Reliance on specialty silicone suppliers concentrated in Northeast Asian manufacturing clusters exposes formulation costs to shipping volatility and currency fluctuation.
- MoPH Timeline Friction:Extended cosmetic registration review periods at Qatar's Ministry of Public Health delay new entrant market access and compress launch windows for seasonal formulations.
- Waterless Shampoo Substitution:Powder and aerosol dry shampoo formats are eroding conventional liquid shampoo frequency-of-use in water-conscious consumer segments.
Strategic Opportunities
- Al Rayyan Professional Density:Underserved salon clusters in Qatar's western municipality offer whitespace for technical color system distribution partnerships.
- QS-GCC Harmonization:Convergence between Qatar General Organization for Standardization and Saudi SFDA technical regulations promises streamlined multi-market certification pathways.
- Online Niche Brand Displacement:Direct-to-consumer platforms are capturing younger demographics seeking international specialty formulations unavailable through traditional beauty retail.
Industry Challenges
- Trichology Skill Scarcity:Shortage of certified scalp diagnostic specialists limits salon upselling of treatment-grade product protocols.
- MoPH Documentation Burden:Full ingredient disclosure requirements demand reformulation of legacy portfolios and compress R&D-to-market timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Hair Care Market |
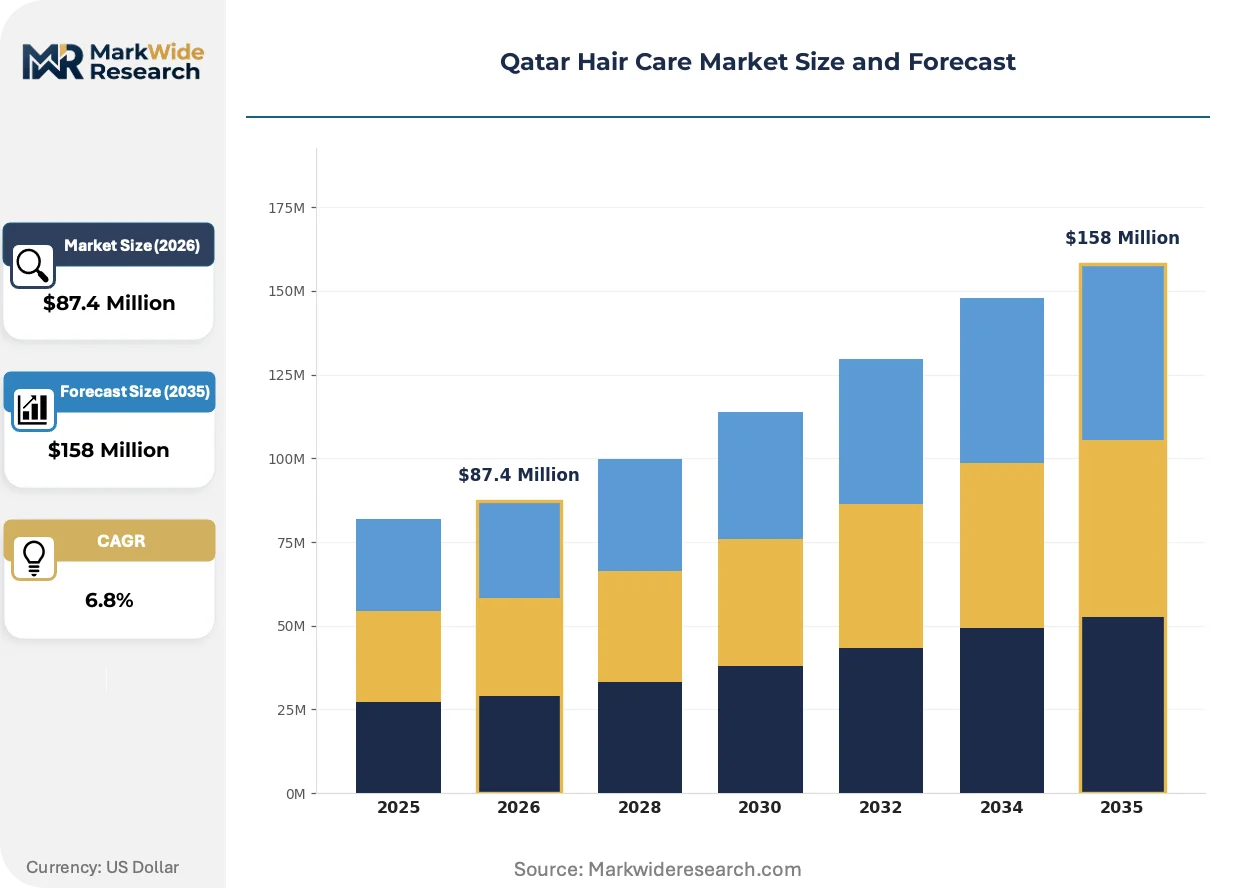
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Styling Gel End User: Men, Women, Children, Salon Professionals Distribution Channel: Supermarkets, Online Retail, Beauty Stores, Pharmacies Ingredient Type: Organic, Synthetic, Herbal, Chemical |
| Companies Covered | Henkel AG & Co. KGaA, Redken, L'Oréal S.A., Oribe Hair Care LLC, Pierre Fabre Group, Procter & Gamble Company, Dabur India Limited, Dr Organic Ltd, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Hair Care Market Evolving Landscape
Formulation science and channel architecture are converging to reshape Qatar's hair care competitive terrain, with climate-adaptive chemistry and professional procurement consolidation driving structural change.
Heat-activated protein bonding technology is modularizing repair treatment protocols in Qatari salons. High-temperature climate stress degrades keratin integrity faster than temperate-zone equivalents, prompting rapid adoption among Doha franchise chains. This modularization is compressing the traditional separate-treatment-service model into integrated color-and-care single appointments.
Qatar's Ministry of Public Health is tightening cosmetic registration documentation requirements ahead of anticipated GCC regulatory convergence. Industrial consequence falls heaviest on import-dependent distributors facing extended review timelines for novel active ingredients. Professional-grade colorant suppliers are responding by pre-positioning formulation dossiers to capture seasonal salon restocking cycles.
Younger demographics are displacing traditional beauty store discovery with algorithm-driven online niche brand exploration. International direct-to-consumer platforms are capturing share from Doha's upscale retail corridors among consumers seeking clean-label formulations unavailable through conventional distribution. This channel rotation is most visible among twenty-five to thirty-five-year-old professionals in Doha's West Bay commercial district.
Qatar Hair Care Market Segmentation
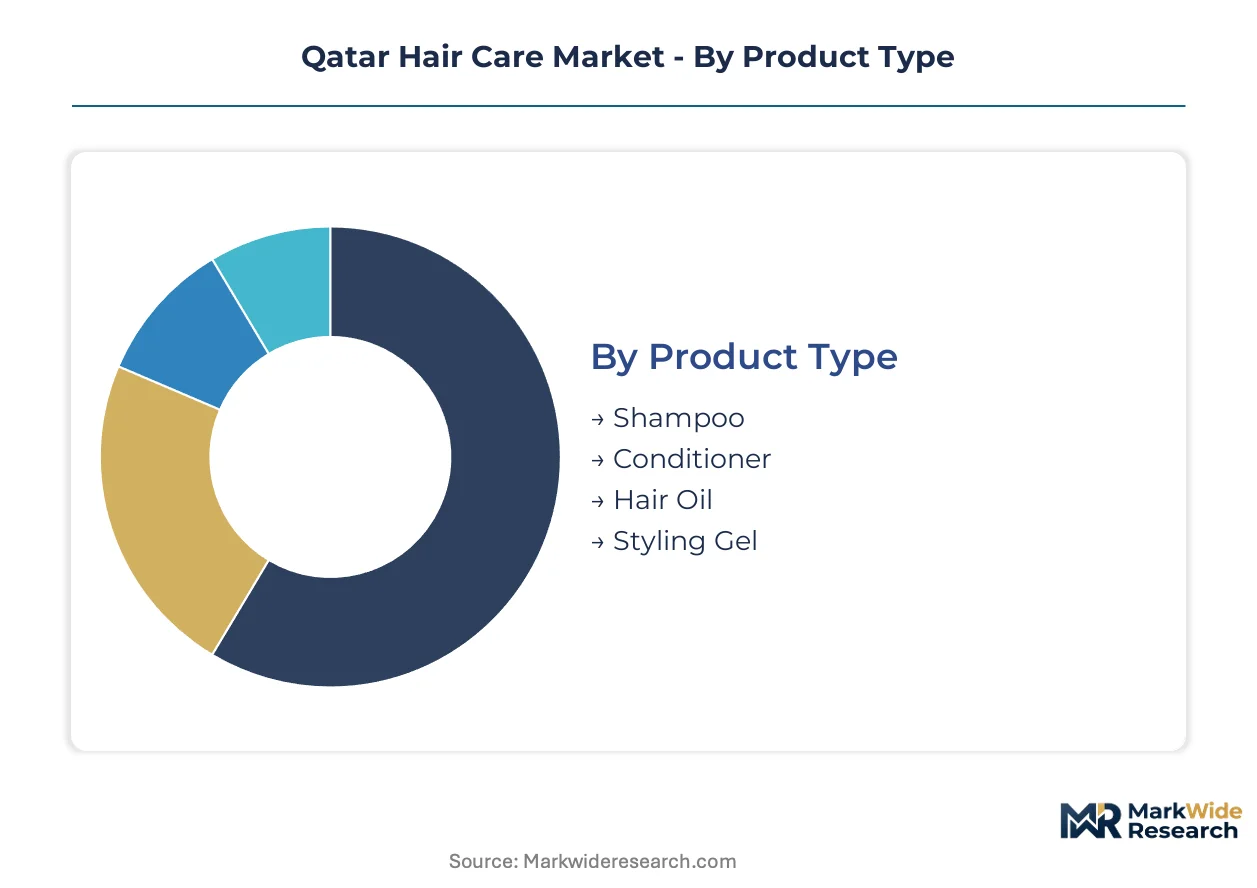
Qatar's hair care market segments reflect distinct procurement behaviors across product formats, user demographics, and channel architectures. Understanding these divisions reveals where margin concentrates and which trajectories are restructuring competitive positioning in Doha and Al Wakrah.
Product Type:
Standalone cleansing and conditioning formats dominate household consumption, while embedded treatment systems penetrate salon service protocols most deeply.
- Shampoo:Surfactant-based formulations at pH 4.5–5.5 manage keratin integrity in arid Gulf conditions. Volume concentrates in Doha's supermarket and hypermarket channels where mass-market brands sustain shelf dominance.
- Conditioner:Silicone and protein-enriched variants restore moisture stripped by high-temperature climate stress. Salon professionals in Al Rayyan and Al Wakrah drive premium attach rates as technical service protocols expand.
- Hair Oil:Thermal and UV protective formulations address Gulf-specific environmental degradation. Demand clusters among women seeking pre-styling protection.
- Styling Gel:Polymer-based hold systems target men's grooming segments in urban professional demographics.
Shampoo leads volumes today; hair oil is gaining share fastest.
End User:
Cost tier stratification separates mass household purchasers from high-margin professional procurement channels.
- Men:Grooming routines concentrate on cleansing and styling efficiency. Supermarket channels capture this segment through bundled value formats.
- Women:Multi-step regimens spanning cleansing, conditioning, treatment, and styling drive category breadth. Doha's beauty store expansion targets this demographic with premium positioning.
- Children:Mild formulation demand prioritizes tear-free and hypoallergenic specifications. Pharmacy channels anchor trust-based purchasing for this safety-conscious segment.
- Salon Professionals:Technical-grade color systems and treatment protocols command the highest per-unit margins. Independent stylists and franchise chains across Doha and Al Wakrah are fragmenting historically brand-loyal consumer flows.
Women anchor volume concentration; salon professionals are expanding most quickly.
Distribution Channel:
Geographic reach and customer acquisition cost diverge sharply between physical footprint expansion and digital platform penetration.
- Supermarkets:High-frequency traffic drives mass-market shampoo and conditioner velocity. Shelf space competition intensifies as multinational suppliers defend position.
- Online Retail:Algorithm-driven discovery platforms capture younger demographics seeking international niche brands unavailable through conventional distribution. West Bay professionals exhibit the strongest channel migration.
- Beauty Stores:Premium brand curation and consultation services justify higher price positioning. Footprint expansion in Al Wakrah extends access beyond Doha's traditional concentration.
- Pharmacies:Regulatory trust and healthcare adjacency support sensitive scalp and pediatric formulations. MoPH registration requirements reinforce channel credibility.
Supermarkets maintain volume leadership; online retail is climbing the fastest.
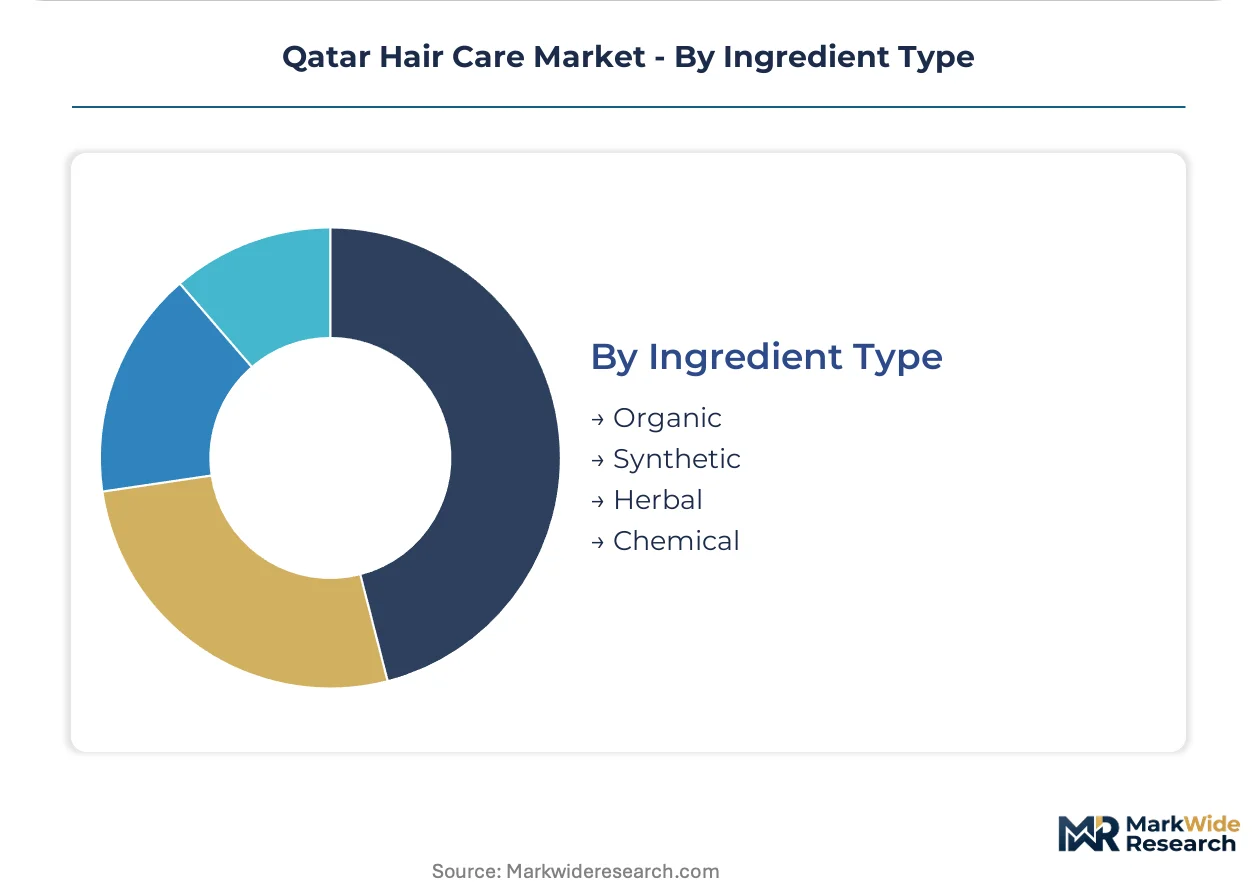
Ingredient Type:
Supply concentration and certification burden separate legacy synthetic supply chains from emerging clean-label alternatives.
- Organic:Plant-derived actives with certified sourcing protocols command price premiums. MoPH tightening ingredient disclosure standards accelerates formal verification demand.
- Synthetic:Silicones and petrochemical surfactants deliver performance consistency at scale. Import concentration from Northeast Asian manufacturing clusters exposes formulation costs to shipping volatility.
- Herbal:Traditional botanical extracts target Gulf consumers seeking culturally familiar ingredients. Niche positioning limits mass penetration.
- Chemical:Technical colorants and permanent treatments require professional application expertise. Salon channel concentration dominates this segment.
Synthetic formulations lead volumes today; organic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed cosmetologists and trichology specialists concentrate most heavily in Doha's West Bay and Al Rayyan, anchoring Qatar's professional hair care demand. These practitioners drive technical-grade product procurement across salon chains and independent studios. Municipal variation in retail density and service culture creates distinct sub-market dynamics.
Doha
High-income expatriate households and luxury salon chains dominate consumption patterns in Qatar's capital. MoPH cosmetic registration requirements elevate compliance costs for new entrants, favoring established suppliers with dossier-ready portfolios. The West Bay commercial corridor hosts the densest concentration of premium beauty retail and professional training academies.
Al Rayyan
Rapid residential expansion west of Doha is outpacing professional salon infrastructure, creating procurement whitespace for technical color system distributors. QS labeling standards enforcement remains consistent with national frameworks, though local municipality permitting affects storefront establishment timelines. Independent stylists in the Mesaieed cluster are fragmenting historically brand-loyal consumer flows through personalized service protocols.
Al Wakrah
Secondary metropolitan status is attracting beauty retail footprint expansion as operators seek lower rent structures than Doha premiums. The country's national pharmaceutical regulator maintains equivalent MoPH registration standards across all municipalities, preventing regulatory arbitrage. New mall developments near the Al Wakrah Souq are anchoring first-to-market premium brand presence.
Al Khor
Industrial zone adjacency and compressed household density limit mass-market shampoo velocity relative to southern municipalities. Central bank monetary policy transmission affects consumer discretionary spending on non-essential beauty categories in this northern municipality. Pharmacy channels retain stronger relative share due to limited dedicated beauty retail infrastructure.
Umm Salal
Commuter residential patterns concentrate demand in supermarket and hypermarket channels rather than salon professional procurement. MoPH ingredient disclosure timelines apply uniformly, though distributor logistics networks face longer last-mile configurations. The Umm Salal Mohammed commercial strip is emerging as a mid-tier service corridor between Doha and northern zones.
Qatar Hair Care Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Qatar's hair care procurement channels, creating a tiered competitive structure. Mass-market shelf space concentrates among consumer goods conglomerates with established GCC distribution networks, while professional-grade color and treatment systems favor suppliers with dedicated salon education infrastructure. Three archetypes dominate: multinational beauty conglomerates with professional divisions, regional distributors with MoPH registration expertise, and niche direct-to-consumer platforms capturing algorithm-driven discovery. Dominant competitive moves include salon-exclusive distribution partnerships and pre-positioned regulatory dossiers to compress MoPH review timelines.
Among multinational beauty conglomerates, L'Oréal S.A., Henkel AG & Co. KGaA, and Unilever PLC occupy positions spanning mass-market and professional channels. L'Oréal S.A. exemplifies the salon-anchored archetype through professional division infrastructure, while Henkel AG & Co. KGaA represents technical color system specialization. Unilever PLC anchors mass-market penetration through supermarket and hypermarket shelf dominance. These three entities collectively illustrate the strategic divergence between professional-grade and household consumption procurement patterns.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Redken |
| L'Oréal S.A. |
| Oribe Hair Care LLC |
| Pierre Fabre Group |
| Procter & Gamble Company |
| Dabur India Limited |
| Dr Organic Ltd |
| Unilever PLC |
| Others |
Value Network & Pricing Analysis
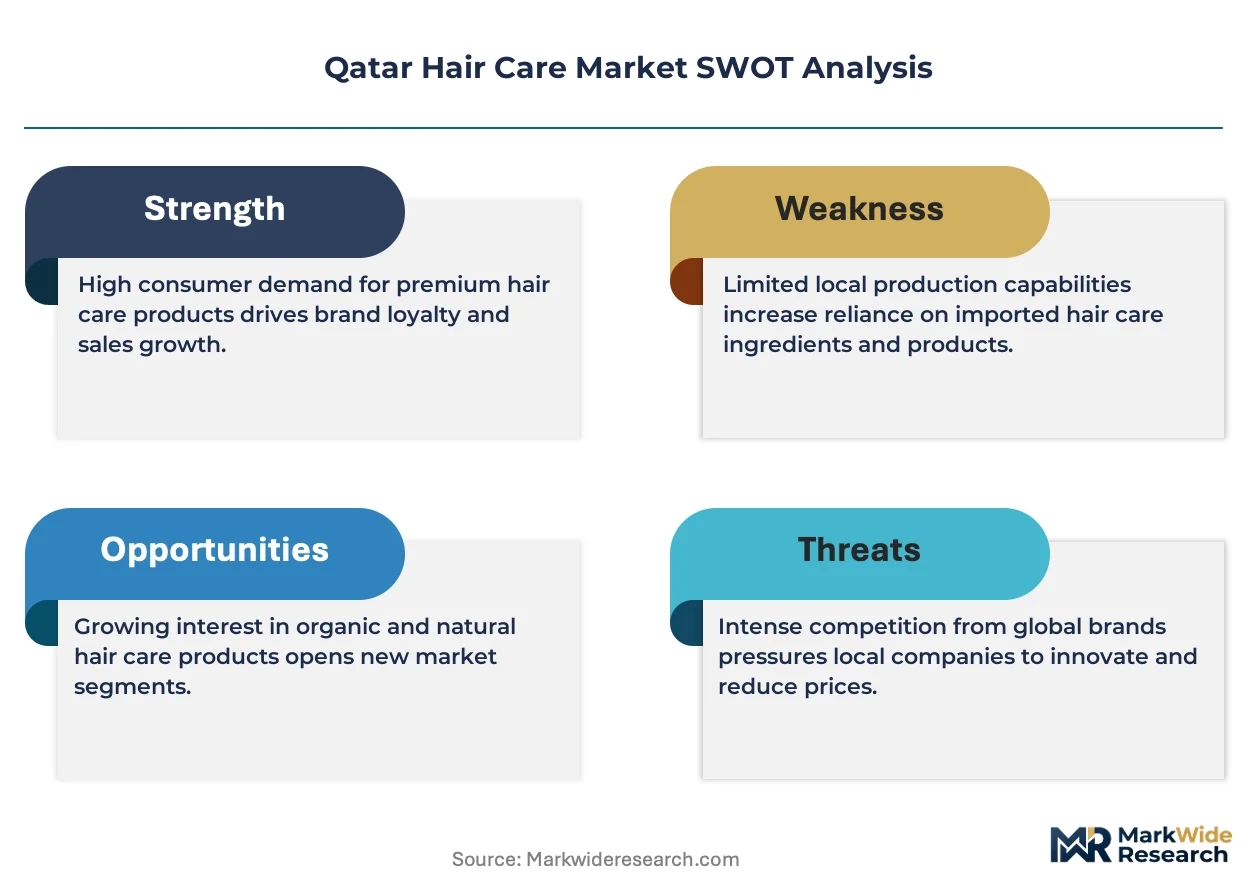
Professional-grade versus mass-market formulation tiers diverge sharply in Qatar's hair care sector, with salon-exclusive technical color systems commanding substantial premiums over supermarket shampoo lines while silicone import concentration from Northeast Asian clusters constrains margin flexibility across both tiers.
Pricing Analysis
Capacity additions in Southeast Asian silicone manufacturing are reshaping price floors for conditioning formulations, though currency hedging costs partially offset raw material relief. Three-tier pricing structure across premium salon-exclusive, standard beauty retail, and economy mass-market levels stratifies Qatar's procurement landscape. Price differentiation hinges on MoPH registration certification status and climate-adaptive performance claims. Cost compression in mass-market shampoo tiers is intensifying because waterless dry shampoo substitutes erode liquid format frequency-of-use. Independent stylists in Al Rayyan exhibit the highest price sensitivity, while Doha franchise chains prioritize performance guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing qualification requirements from Qatar's leading salon chains are fragmenting historical single-supplier relationships among professional-grade distributors. Specialty silicone feedstocks draw from South Korea, Japan, and China, while botanical extract supply rests on Indian and Egyptian cultivation networks. Import dependency on Northeast Asian manufacturing clusters exposes formulation costs to Red Sea shipping volatility and currency fluctuation. Distribution runs through Doha-based import distributors with MoPH registration expertise, extending last-mile coverage to Al Wakrah and Al Rayyan through sub-distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's hair care sector functions as a regulatory-arbitrage corridor where MoPH registration timelines lag Saudi SFDA processing by several months, creating temporary market access advantages for dossier-ready suppliers willing to absorb extended review periods.
For Market Incumbents: Anticipate accelerated online niche brand displacement by pre-positioning salon-exclusive distribution partnerships in Al Rayyan's underserved clusters. Defensive consolidation of professional education infrastructure counters emerging direct-to-consumer platforms capturing West Bay professionals. Vertical integration into heat-activated protein bonding technology R&D addresses trichology skill scarcity limiting treatment-grade upselling.
For New Entrants and Emerging Players: Direct-to-consumer algorithmic discovery platforms offer the most penetrable route for international clean-label formulations unavailable through Doha's conventional beauty retail. Al Rayyan's rapid residential expansion presents whitespace for technical color system distribution partnerships. Target pharmacy channels for pediatric and sensitive scalp formulations where MoPH registration credibility anchors trust-based purchasing.
For Investors and Strategic Acquirers: Consolidation pressure builds where MoPH documentation burdens compress R&D-to-market timelines for import-dependent distributors. Mid-term viability through the projection horizon favors acquisition targets with pre-positioned regulatory dossiers and existing salon education infrastructure. Monitor QS-GCC harmonization progress as the critical inflection signal determining which suppliers can scale across Gulf markets without duplicative certification burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Exclusive Distribution Partnership | Professional channel capture in Al Rayran and Al Wakrah extends beyond Doha concentration. |
| MoPH Dossier Pre-Positioning | Compressed review timelines enable seasonal formulation launches ahead of competitor access. |
| Heat-Activated Protein Bonding R&D | Modular repair protocols address Gulf-specific keratin degradation from climate stress. |
| Direct-to-Consumer Platform Launch | Algorithm-driven discovery captures West Bay professionals seeking unavailable international niche brands. |
| QS-GCC Harmonization Compliance Investment | Streamlined multi-market certification reduces duplicative regulatory burden across Gulf Cooperation Council. |
Research Methodology
Coverage spans Qatar's five municipalities with primary inputs from each, combining structured interviews with salon chain procurement directors, independent stylist operators, MoPH regulatory affairs specialists, and beauty retail category managers with secondary validation from QS technical regulations, MoPH cosmetic registration databases, customs import records, and GCC trade flow disclosures. Bottom-up demand modeling triangulates against top-down market sizing approaches.
Rate-of-change decomposition separates volume growth from value expansion across product type, end-user demographic, distribution channel, and ingredient certification tier dimensions throughout the forecast period. CAGRs derive from segment-level trajectory analysis incorporating salon professional density expansion, online retail penetration curves, and MoPH registration timeline elasticity. Climate-adaptive formulation adoption rates and waterless shampoo substitution patterns constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for heat-activated protein bonding modularization would alter the outlook for salon service attach rates. Forecasts reflect assumptions regarding QS-GCC regulatory convergence timing and silicone supply chain stabilization. Deviation in MoPH review period duration or Red Sea logistics disruption severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Plant-Based Hair Dye Market
Hair Care
India Hair Care Market
Hair Care
China Hair Care Market
Hair Care
United States Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Relaxer Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Anti Pollution Hair Care Products Market
Hair Care
Hair Tonic Market
Hair Care
Artificial Hair Integration Market
Hair Care
Russia Hair Care Market
Hair Care
Hair Dye Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Care Market
Hair Care
South Korea Hair Care Market