

Rice Water Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Water Shampoo Market Insights
The capability gap between mass-market manufacturers and heritage-focused specialists is rotating competitive investment toward in-house fermentation labs and controlled supply chains. Procter & Gamble leverages its global distribution infrastructure to secure shelf space across conventional retail channels. Viori anchors its brand identity around direct-to-consumer storytelling tied to ethnic sourcing traditions. Amorepacific sustains leadership in fermented botanical R&D through dedicated facilities in South Korea.
Rice water shampoo denotes a hair cleansing formulation incorporating fermented or unfermented Oryza sativa extract, typically containing inositol, amino acids, and starch derivatives that coat and strengthen hair cuticles. The manufacturing process involves controlled fermentation at specific temperatures to preserve bioactive compounds before pH stabilization and surfactant integration. The repairing segment leads volume due to damage-conscious consumers seeking protein-alternative treatments, while sulfate-free formulation technology captures the fastest expansion as scalp-sensitivity awareness spreads. Botanical infusion approaches occupy the premium tier, where margin pools concentrate around certified organic ingredient sourcing and limited-batch positioning.
The EU Green Deal and REACH frameworks mandate granular ingredient traceability for cosmetic imports into Europe, elevating compliance costs for smaller fermenters. The FDA's cosmetic labeling requirements in the US push brands toward substantiated claims rather than traditional remedy positioning. South Korea's MFDS maintains active oversight of fermented cosmetic safety profiles, creating a quality benchmark that export-oriented brands must satisfy. Stakeholders should monitor how evolving preservative restrictions reshape formulation economics across their target geographies.
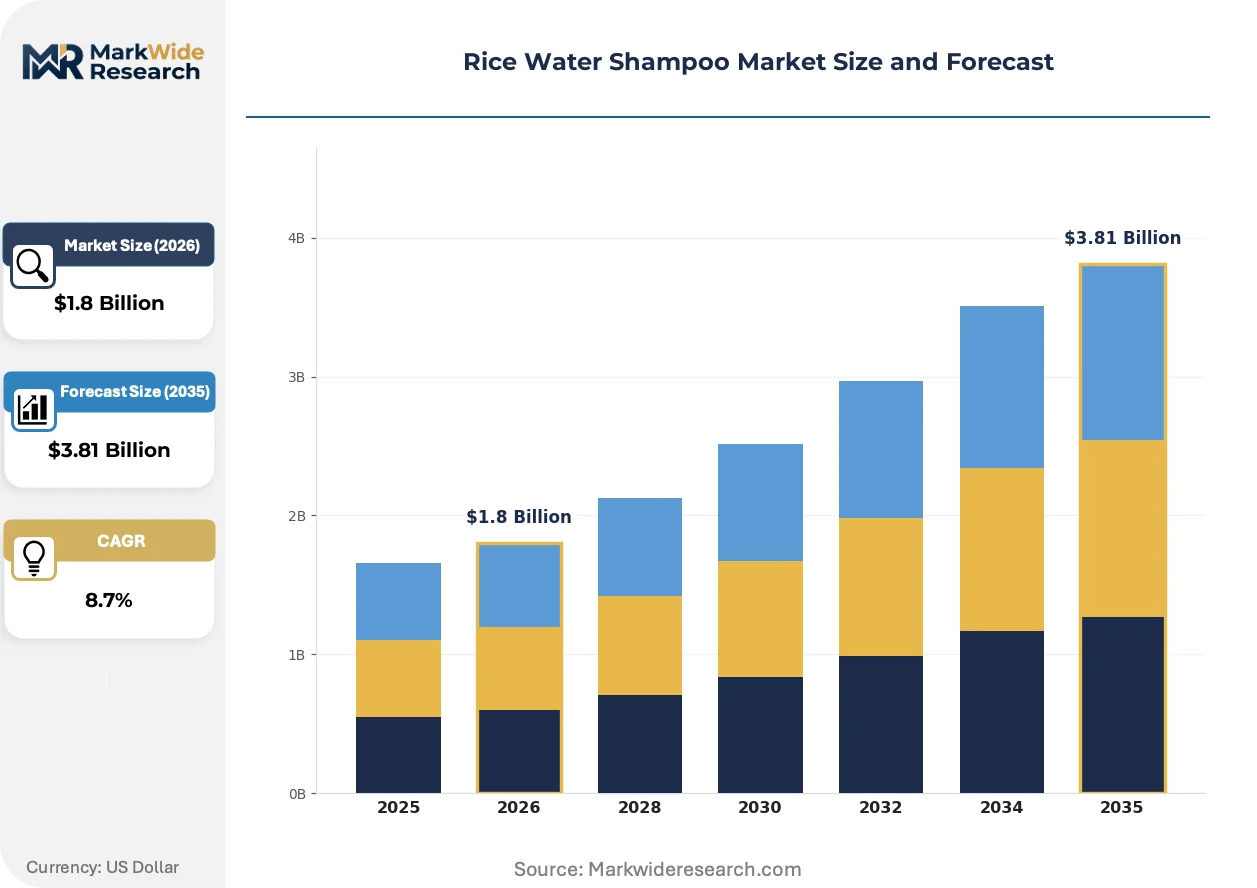
Market Dynamics
Fermentation biotechnology patents are concentrating among heritage specialists, forcing mass-market manufacturers to choose between licensing fees and multi-year R&D programs to replicate bioactive compound stability.
Growth Catalysts
- EU Green Deal compliance:The framework's granular ingredient traceability mandates are accelerating clean-label investments among European import brands, creating first-mover advantages for compliant formulators.
- Salon channel recovery:Post-pandemic professional service expansion is pulling premium rice water formulations into back-bar protocols and retail partnerships across South Korea and the United States.
- Fermented botanical R&D:Dedicated biotechnology facilities in Seoul and Busan are shortening innovation cycles for stabilized inositol delivery systems.
Market Restraints
- Raw material concentration:Premium Oryza sativa sourcing clusters in Vietnam's Mekong Delta and Thailand's central plains, exposing brands to climate volatility and regional harvest fluctuations.
- REACH registration costs:The European Chemicals Agency's expanded substance notification requirements for fermented cosmetic imports are elevating compliance expenditures for mid-scale fermenters without dedicated regulatory teams.
- Synthetic peptide substitution:Laboratory-engineered keratin alternatives are capturing repair-seeking consumers through faster visible results and standardized performance claims.
Strategic Opportunities
- India's Ayurveda convergence:The country's PLI scheme for personal care manufacturing is attracting co-investment for rice water formulations positioned alongside traditional hair oiling rituals.
- Direct-to-consumer subscription:Replenishment models with customizable fermentation intensity levels are capturing high-lifetime-value segments in North American urban markets.
- Scalp microbiome positioning:Prebiotic rice water variants addressing fungal balance are opening white space between medicated and cosmetic shampoo categories.
Industry Challenges
- Bioprocess engineering talent scarcity:Formulators with simultaneous expertise in cosmetic stability testing and controlled fermentation protocols command premium compensation, constraining scale-up timelines.
- Batch-to-batch variance:Natural fermentation cycles produce inconsistent amino acid profiles, requiring expensive quality-control infrastructure to meet MFDS export specifications.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Water Shampoo Market Trends and Innovations
Biotechnology integration is compressing traditional remedy positioning into clinically substantiated claims, while regulatory transparency mandates and channel fragmentation are forcing simultaneous investment in compliance infrastructure and direct relationship-building.
Cold-fermentation extraction systems are miniaturizing. These temperature-controlled bioreactors preserve heat-sensitive inositol compounds that degrade in conventional processing. Boutique manufacturers in Jeonju and specialized contract labs in California are installing pilot-scale units for limited-batch positioning. The technology is miniaturizing production minimums, enabling regional fermenters to compete with industrial-scale suppliers on freshness claims rather than unit economics.
REACH framework amendments are tightening preservative restrictions for cosmetic imports into Europe. The European Chemicals Agency's expanded candidate list is forcing reformulation of traditional rice water shampoos relying on phenoxyethanol stabilization. Premium organic-certified lines are responding fastest, accelerating natural preservation system R&D while mass-market brands delay portfolio transitions pending cost-impact clarity.
Subscription-based replenishment is displacing conventional retail stocking patterns among damage-conscious consumers. Direct channels with customizable fermentation intensity tiers are capturing high-frequency purchasers who previously cycled between salon and mass retail. This behavioral pivot concentrates most visibly in Seoul's metropolitan area and coastal US cities where digital-native beauty consumers dominate.
Rice Water Shampoo Market Segmentation
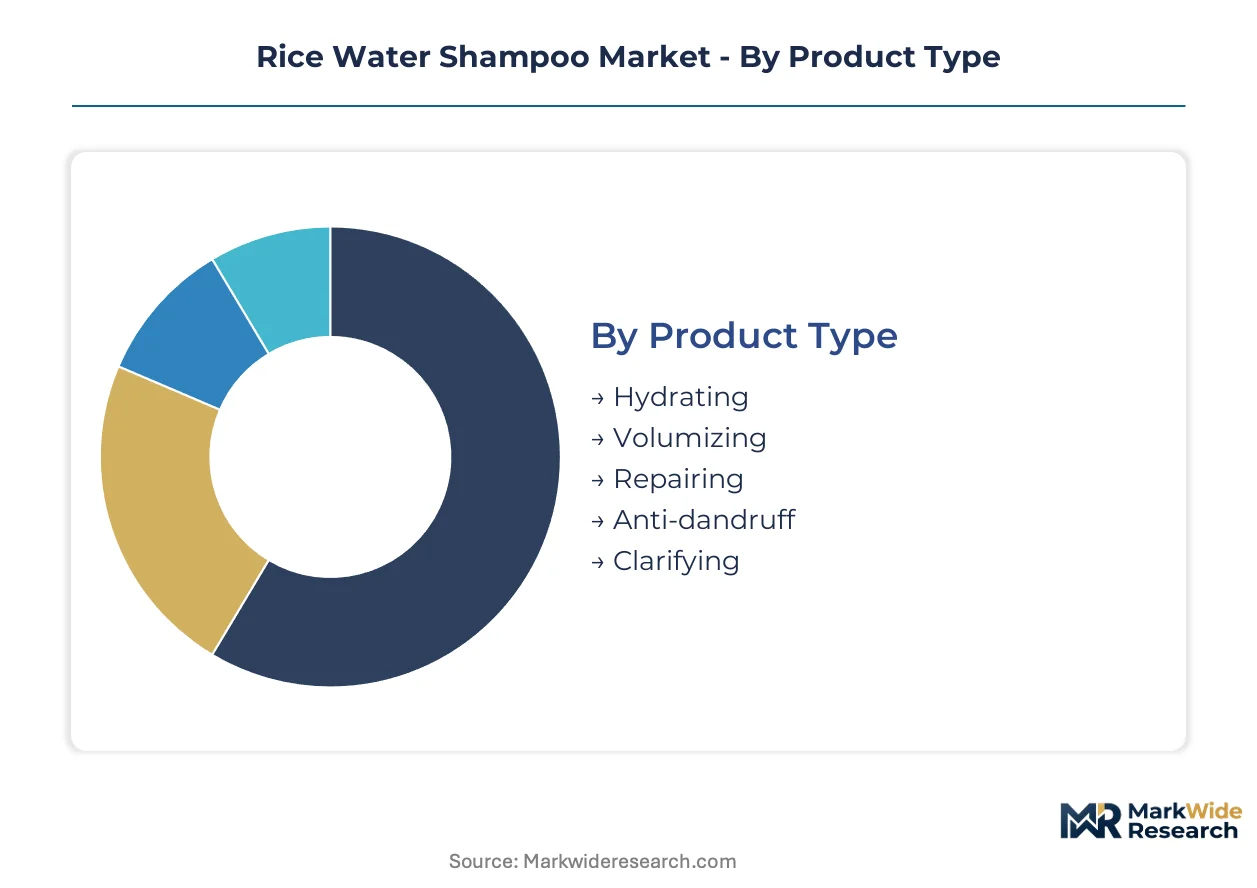
Rice water shampoo segmentation reveals how formulation complexity and channel positioning split manufacturing investment across distinct capability tiers. Product type and formulation technology categories capture the steepest R&D differentiation, while end-user segmentation dictates distribution infrastructure requirements.
Product Type:
Repairing formulations anchor South Korea's export engine, while hydrating variants serve price-sensitive domestic markets across Southeast Asia.
- Repairing:Protein-alternative formulations leverage inositol and amino acid concentrations for structural hair shaft reinforcement. Salon professionals in Seoul and Los Angeles metropolitan areas drive premium procurement, prioritizing visible damage reversal over daily maintenance protocols.
- Volumizing:Lightweight starch derivative coatings create temporary cuticle lift without silicone buildup. Demand clusters among beauty enthusiasts in urban North American markets seeking Instagram-visible results between professional appointments.
- Hydrating:Glycerin-inositol matrices target routine moisture replenishment for non-damaged hair types.
- Anti-dandruff:Zinc pyrithione or tea tree oil combinations address fungal scalp conditions in tropical climate zones.
- Clarifying:Higher surfactant ratios remove product buildup for weekly deep-cleansing routines.
Repairing commands the established base. The steepest expansion runs through volumizing.
Formulation Technology:
Cost tier stratification separates artisan fermentation labs from industrial surfactant houses, with certification premiums widening margin spreads.
- Sulfate-Free:Mild cleansing base alternatives preserve scalp microbiome integrity while maintaining foaming performance through glucoside surfactants. Sensitive scalp users in Germany and California drive fastest category growth, rejecting traditional sodium lauryl sulfate systems.
- Botanical Infusions:Limited-batch positioning with certified organic ingredient sourcing captures premium tier margins. Amorepacific's dedicated Seoul facilities and Jeonju boutique fermenters supply this segment through controlled supply chain partnerships.
- Organic Extracts:Standardized Oryza sativa concentrate formulations without synthetic additives.
- Enzyme-Enhanced:Protease and lipase additions accelerate bioactive compound release during fermentation.
- pH Balanced:Citric acid or sodium hydroxide adjusted systems targeting scalp acid mantle compatibility.
Sulfate-free captures volume momentum. Botanical infusions concentrate margin pools.
Application:
Volume concentration favors daily use formats, while specialized protocols command per-unit premiums through professional channel anchoring.
- Daily Hair Care:Standardized inositol concentrations for routine cleansing without treatment intensity. Mass retail distribution across Vietnam and Thailand supports this segment's unit economics through high-turnover shelf placement.
- Hair Growth Stimulation:Fermented rice water with elevated amino acid profiles targets follicular health positioning. Wellness seekers in Seoul and New York subscribe to direct-to-consumer replenishment models with customizable fermentation intensity tiers.
- Scalp Treatment:Weekly intensive protocols for inflammatory or flaky conditions.
- Color Protection:UV filter and antioxidant additions for dyed hair maintenance.
- Sun Damage Repair:Post-exposure restorative formulations for high-UV climate users.
Daily hair care sustains baseline manufacturing throughput. Hair growth stimulation climbs the fastest through subscription channel expansion.
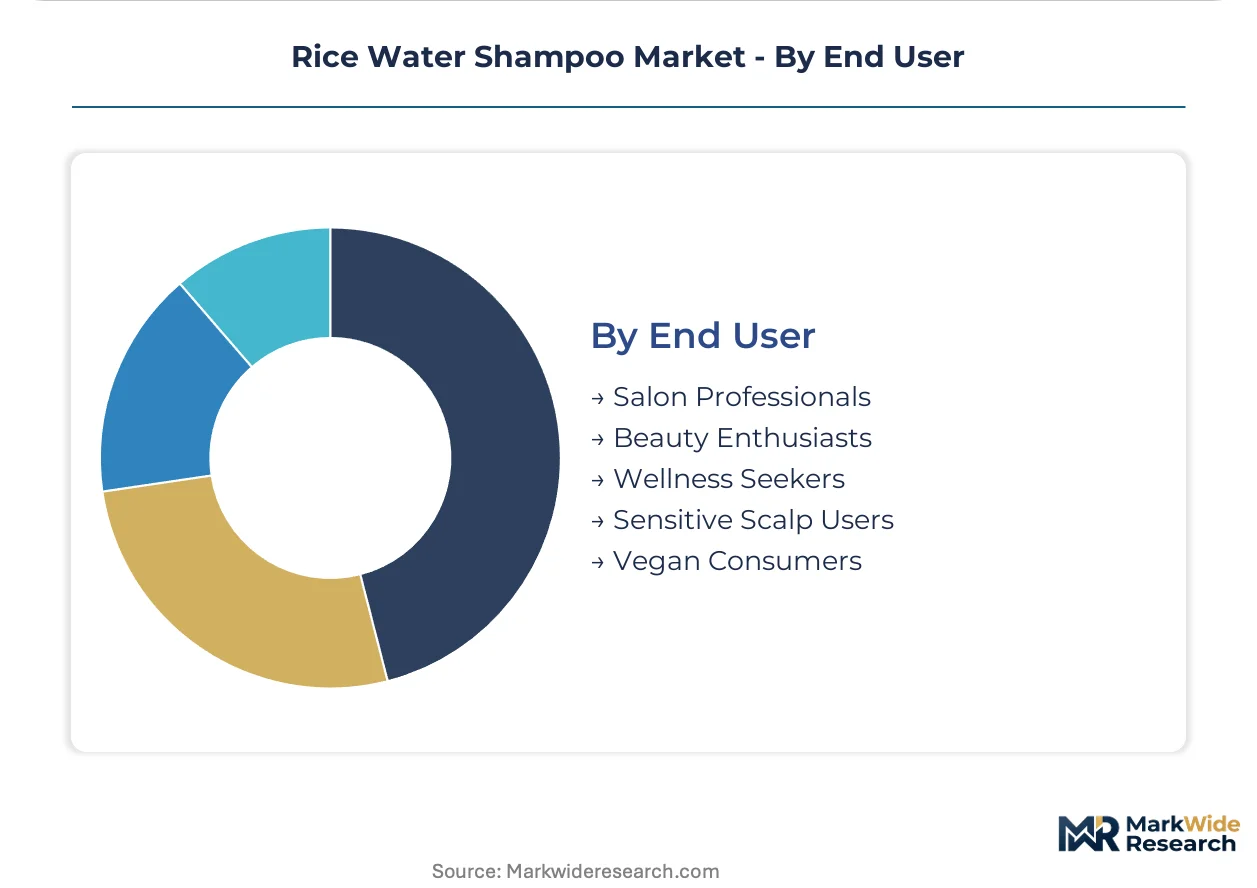
End User:
Customer type determines regulatory compliance burden and marketing claim substantiation requirements across jurisdictions.
- Salon Professionals:Back-bar formulations with higher active concentrations and technical training support requirements. Post-pandemic service channel recovery in South Korea and the United States pulls premium rice water into professional retail partnerships.
- Vegan Consumers:Plant-derived preservation systems and cruelty-free certification protocols. EU Green Deal disclosure mandates and MFDS export specifications from South Korea shape formulation transparency investments for this segment.
- Beauty Enthusiasts:Trend-responsive purchasers cycling between viral product formats.
- Wellness Seekers:Holistic health positioning with traditional remedy storytelling.
- Sensitive Scalp Users:Hypoallergenic certification and minimal ingredient list requirements.
Salon professionals anchor premium pricing architecture. Vegan consumers gain share fastest through regulatory transparency tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consumption zones. Vietnamese and Thai buyers prioritize volume-priced daily formats, while South Korean and US metropolitan consumers absorb premium positioning for fermented, salon-grade protocols.
South Korea
Seoul's metropolitan beauty consumers drive premium fermented rice water procurement through professional salon channels and direct-to-subscription models. MFDS maintains stringent safety oversight of fermented cosmetic exports, establishing quality benchmarks that domestic brands must satisfy for international expansion. Biotech R&D clusters in Seoul and Busan specialize in stabilized inositol delivery systems, shortening innovation cycles for heritage-positioned formulators.
United States
Coastal urban markets in California and New York concentrate demand for sulfate-free, scalp-sensitive formulations through digital-native subscription channels. FDA cosmetic labeling requirements push brands toward substantiated claims rather than traditional remedy positioning. Los Angeles anchors professional back-bar adoption, where salon retail partnerships pull premium rice water into post-pandemic service recovery.
Vietnam
Mekong Delta rice cultivation clusters supply premium Oryza sativa raw material to regional formulators, though climate volatility exposes brands to harvest fluctuations. Domestic consumers favor mass-priced hydrating variants through high-turnover retail placement in Ho Chi Minh City and Hanoi. The country's personal care manufacturing sector attracts co-investment for export-oriented fermentation capacity.
Germany
EU Green Deal disclosure mandates accelerate clean-label investments among import brands serving sensitive-scalp consumers in Berlin and Munich. ECHA's REACH framework elevates compliance expenditures for fermented cosmetic imports, favoring established players with dedicated regulatory teams. Natural preservation system R&D concentrates among organic-certified lines responding fastest to tightening preservative restrictions.
India
Ayurveda-convergent positioning attracts PLI scheme co-investment for rice water formulations alongside traditional hair oiling rituals in Maharashtra and Karnataka. Domestic demand clusters in Mumbai and Bangalore for mid-tier daily care formats. The country's central pharmaceutical regulator maintains oversight of cosmetic safety profiles, shaping formulation transparency investments for export-oriented brands.
Rice Water Shampoo Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Heritage fermentation specialists command premium positioning through controlled supply chains and biotechnology patents, while mass-market manufacturers leverage global distribution infrastructure for volume penetration. Three archetypes dominate: multinational consumer goods conglomerates with shelf-space dominance, direct-to-consumer heritage storytellers with ethnic sourcing traditions, and dedicated biotechnology facilities with fermented botanical R&D capabilities. Competitive moves concentrate on strategic partnerships for raw material security and portfolio diversification into scalp microbiome positioning.
Within the heritage-specialist tier, Amorepacific and Viori exemplify divergent go-to-market architectures. Amorepacific occupies a position anchored in dedicated Seoul biotechnology facilities, representing the vertically integrated fermentation R&D archetype. Viori exemplifies direct-to-consumer ethnic storytelling, sitting within the controlled supply chain tradition-based positioning segment. Among multinational conglomerates, Procter & Gamble represents scale-driven distribution infrastructure, anchoring conventional retail channel penetration across multiple geographies.
| Leading Market Players |
|---|
| Shiseido |
| Amorepacific |
| Procter & Gamble |
| L'Oréal |
| Unilever |
| Kao Corporation |
| The Face Shop |
| Innisfree |
| Viori |
| Others |
Pricing and Supply Chain Analysis
Industrial-scale fermentation capacity utilization in South Korea and Vietnam establishes asymmetric cost structures that compress price floors for artisan producers while elevating margin capture for vertically integrated heritage specialists. This scale concentration simultaneously anchors supply security for premium Oryza sativa extract and creates tiered pricing stratification across salon-grade, retail-premium, and mass-market channels.
Pricing Analysis
Subscription replenishment revenue drives lifetime value concentration among direct-to-consumer heritage brands with customizable fermentation intensity tiers. Three-tier pricing structure across premium, standard, and economy levels separates botanical-infusion salon protocols from sulfate-free retail formats and basic hydrating variants. Cost compression in mass-market tiers intensifies as private-label entrants replicate standardized inositol formulations. Salon professionals demonstrate lowest price sensitivity, absorbing per-unit premiums for back-bar exclusivity and technical training support.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European import brands sourcing fermented rice water concentrates from Seoul and Busan facilities. Premium Oryza sativa sourcing clusters in Vietnam's Mekong Delta and Thailand's central plains, with secondary fermentation capacity concentrating in South Korea and California contract labs. Single-source vulnerability runs through Mekong Delta harvest exposure to monsoon volatility. Distribution runs through professional salon partnerships for premium tiers and mass retail shelf placement for daily-care formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates multiple viable entry points as channel specialization splinters demand across professional back-bar, direct-to-consumer subscription, and clean-label retail segments. Scalp microbiome positioning and Ayurveda-convergent formulations represent underserved niches with limited incumbent saturation.
For Market Incumbents: Shield premium positioning by accelerating in-house fermentation lab investment before patent-protected biotechnology consolidates among heritage specialists. Capture raw material security through controlled supply chain partnerships in Vietnam's Mekong Delta. Counter synthetic peptide substitution threats with clinically substantiated inositol delivery claims backed by MFDS-compliant safety profiles. For New Entrants and Emerging Players: EU organic certification fast-tracks unlock first-mover positioning among German and French sensitive-scalp consumers facing REACH compliance barriers for mid-scale competitors. India's PLI scheme co-investment offers the most penetrable geography for Ayurveda-convergent rice water formulations alongside traditional hair oiling rituals. Launch through direct-to-consumer subscription with customizable fermentation intensity tiers to bypass retail slotting fee disadvantages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer heritage brands with ethnic sourcing storytelling and controlled supply chain transparency. Long-term viability over the medium-term horizon favors acquisition targets with dedicated fermentation R&D facilities and MFDS export certification infrastructure. Monitor ECHA preservative restriction amendments as inflection indicators for natural preservation system R&D investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| In-House Fermentation Lab Investment | Amorepacific's Seoul biotechnology facilities demonstrate vertical R&D control over stabilized inositol delivery systems. |
| Controlled Supply Chain Partnership | Mekong Delta Oryza sativa sourcing agreements secure premium raw material access against climate volatility exposure. |
| EU Organic Certification Fast-Track | ECHA REACH compliance creates first-mover advantage for natural preservation system R&D among import brands. |
| Direct-to-Consumer Subscription Launch | Seoul and coastal US metropolitan consumers drive high-frequency replenishment through customizable fermentation tiers. |
| Scalp Microbiome Positioning | Prebiotic rice water variants open white space between medicated and cosmetic shampoo categories for premium margin capture. |
Research Methodology
Cross-validation between primary interviews with salon professionals, cosmetic formulators, and regulatory affairs specialists and secondary validation through MFDS export filings, ECHA REACH substance notifications, and customs trade data anchors the qualitative findings. Bottom-up triangulation across fermentation facility capacity assessments and top-down reconciliation against retail audit data from Nielsen and Circana sources ensures dimensional consistency.
Sensitivity analysis around raw material harvest volatility and regulatory amendment timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation technology tiers, end-user archetypes, application protocols, and regional regulatory clusters. CAGRs derive from weighted average growth assumptions across premium salon-grade, mid-tier retail, and mass-market volume segments, with specific inputs for fermentation biotechnology patent expiration cycles and EU Green Deal compliance cost trajectories.
Underlying assumptions cover sustained salon channel recovery and stable Mekong Delta agricultural output, with deviation risk concentrated in ECHA preservative restriction amendments and synthetic peptide substitution acceleration. Recalibration cycles align with material shifts in MFDS safety profile updates and REACH framework substance list expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.