
 Israel Hair Care Market | 2026-2036
Israel Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Hair Care Market Foresight
The capability gap between mass-market manufacturing scale and boutique ingredient sourcing is reorganizing competitive dynamics within Israeli hair care. L'Oréal S.A. leverages its global R&D infrastructure to anchor premium positioning in Tel Aviv's salon channel. Moroccanoil Inc differentiates through argan-oil specialization that commands shelf space in specialty retailers. Kao Corporation competes via disciplined distribution partnerships with Israeli pharmacy networks.
Hair care encompasses formulations designed to cleanse, condition, protect, or style human hair, typically incorporating surfactant bases, emollients, and active ingredients such as keratin or botanical extracts at specified pH ranges compatible with scalp biology. Shampoos and conditioners constitute the volume core of the Israeli market, while styling products capture disproportionate margin pools among professional end users. Online retail channels expand fastest among distribution pathways, though supermarkets sustain the broadest consumer reach across Israeli households. Salons and individual consumers split demand structurally, with the former driving premium-brand trial and the latter sustaining replenishment cycles.
The Ministry of Health enforces cosmetic safety regulations that mandate ingredient disclosure and prohibit specified substances, directly elevating compliance costs for imported brands. BIS-equivalent standards for product labeling and the EU-aligned REACH framework for chemical safety influence formulation decisions by manufacturers seeking Israeli market access. Stakeholders must monitor evolving clean-beauty certification requirements and digital commerce regulations that reshape how brands build direct consumer relationships.
Market Dynamics
Professional salon networks in Tel Aviv and Jerusalem are consolidating purchasing power, forcing manufacturers to choose between volume commitments and margin preservation in Israel's concentrated urban corridor.
Growth Catalysts
- Ministry of Health cosmetic safety standards:Mandatory ingredient disclosure elevates consumer trust and drives premium-brand trial among safety-conscious Israeli households seeking verified formulations.
- Argan oil and botanical extract specialization:Boutique ingredient sourcing creates differentiation opportunities for domestic formulators targeting specialty retail channels with provenance narratives.
- Professional salon channel expansion:Urban styling establishments in Haifa and Rishon LeZion accelerate product uptake through stylist recommendations and in-salon retail displays.
Market Restraints
- EU-aligned REACH compliance costs:Chemical safety documentation requirements impose disproportionate burdens on small importers seeking Israeli market access, consolidating entry barriers.
- Surfactant and emollient input volatility:Petroleum-derived base ingredient price fluctuations compress formulation margins for mass-market shampoo producers.
- Supermarket channel concentration:Three retail chains control shelf space allocation in Israel's grocery sector, extracting listing fees that disadvantage emerging brands.
Strategic Opportunities
- Clean-beauty certification acceleration:Evolving domestic standards for natural and organic claims create first-mover advantages for compliant brands in Tel Aviv's premium segment.
- Direct-to-consumer digital commerce:E-commerce platform growth enables bypass of traditional pharmacy and supermarket gatekeepers for subscription-based hair care models.
- Keratin treatment and scalp care convergence:Hybrid formulations addressing both aesthetic and dermatological needs capture margin pools from Israel's medical aesthetics crossover demand.
Industry Challenges
- Cosmetic chemist talent scarcity:Specialized formulation expertise for pH-balanced scalp-compatible products remains concentrated among veteran practitioners near Rehovot's research corridor.
- Dual regulatory timeline pressure:Simultaneous Ministry of Health cosmetic registration and EU export compliance creates product launch delays for Israeli manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Hair Care Market |
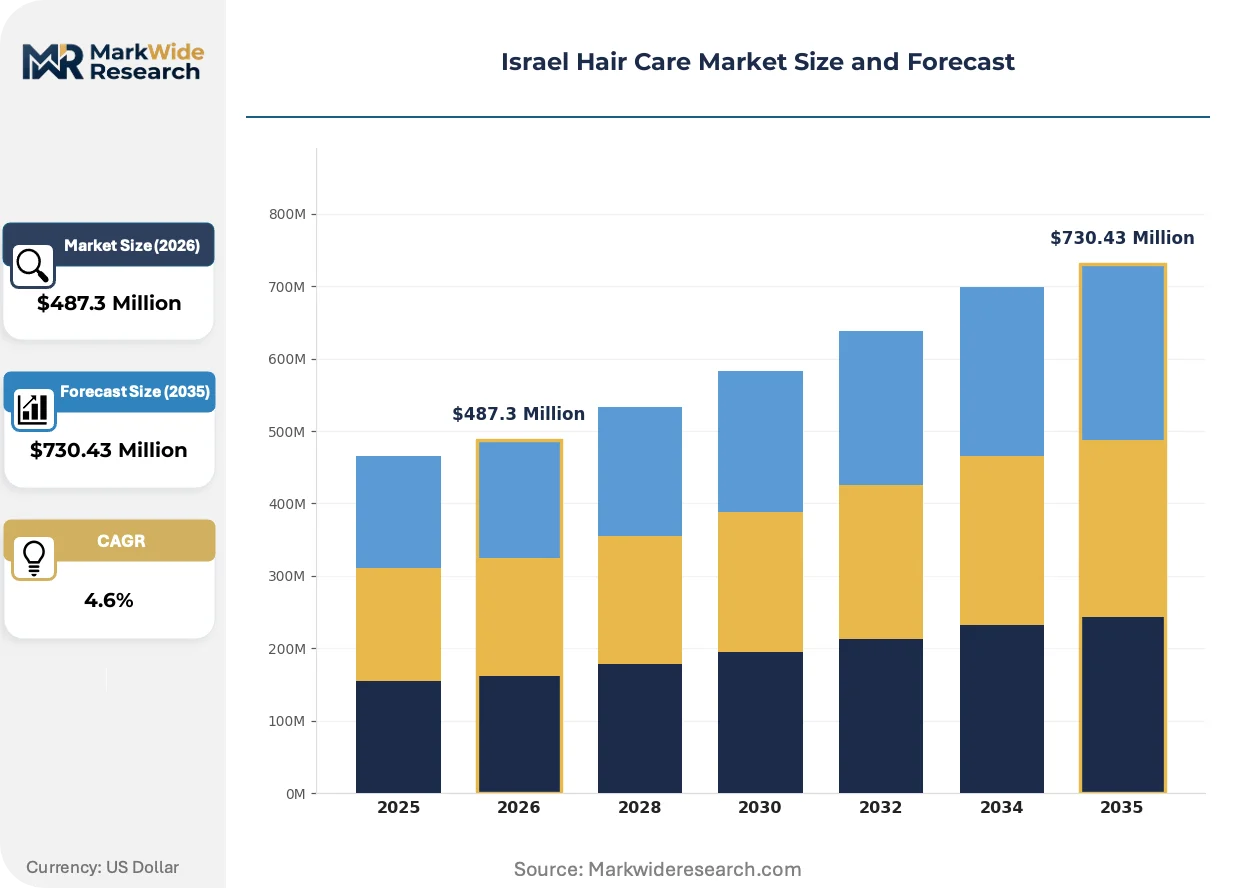
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products End User: Salons, Individual Consumers, Beauty Schools, Distributors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Hair Type: Curly, Straight, Wavy, Coily |
| Companies Covered | Henkel AG & Co. KGaA, Moroccanoil Inc, L'Oréal S.A., Shiseido Company Limited, Pierre Fabre Group (Klorane), The Procter & Gamble Company, Kao Corporation, Revlon Inc, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Hair Care Market Shifts & Advancements
Biotechnology-derived actives and digital channel restructuring are compressing traditional competitive advantages in Israel's hair care sector, rewarding agile formulation and direct consumer engagement.
Synthetic peptide complexes targeting follicle stimulation are displacing conventional keratin treatments in Tel Aviv's high-end salon segment. Trichology clinics and medical aesthetics providers adopt these bioengineered solutions at accelerating rates. The shift is displacing commodity conditioning agents from premium service menus and redirecting R&D investment toward patent-protected molecular delivery systems.
Israel's Ministry of Health is tightening cosmetic safety documentation requirements aligned with EU REACH chemical hazard classifications. Manufacturers must now submit expanded toxicological data for preservative systems and fragrance compounds. Imported brands face extended registration timelines, while domestic producers with established compliance infrastructure capture shelf space from delayed entrants.
Subscription-based replenishment models are fragmenting traditional supermarket and pharmacy purchasing patterns among Israeli millennials and urban professionals. Direct brand websites and specialized e-commerce platforms capture recurring revenue from conditioner and treatment categories. Tel Aviv's dense digital-native population exhibits the highest conversion rates for automated delivery schedules replacing episodic retail trips.
Israel Hair Care Market Segmentation
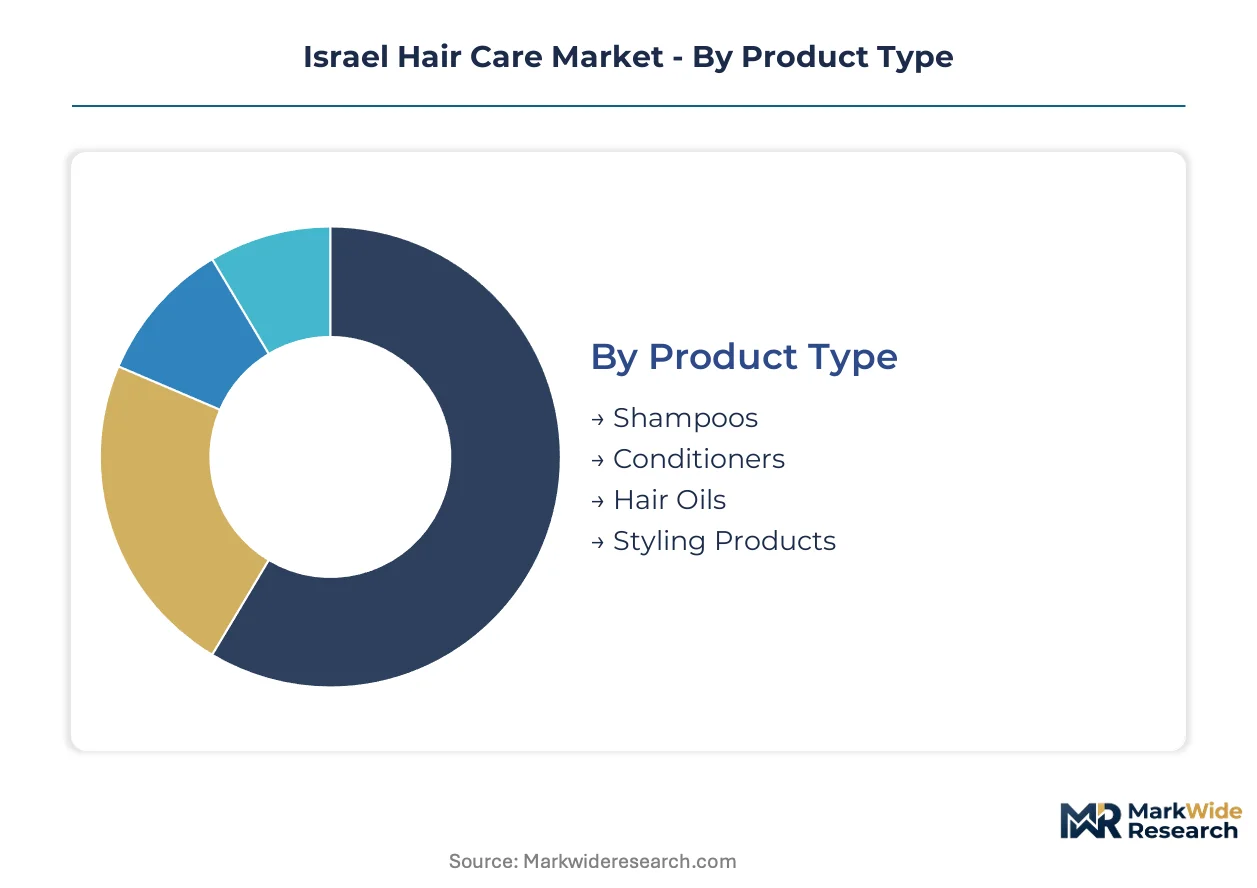
Segmentation in Israel's hair care market reveals how regulatory requirements, channel concentration, and specialized demand reshape competitive positioning across product categories and customer groups.
Product Type:
Israel's Ministry of Health cosmetic safety standards create divergent compliance burdens across formulation categories, favoring established domestic producers with registration infrastructure.
- Shampoos:Surfactant-based cleansing formulations typically operate at pH 4.5-6.5 to maintain scalp barrier integrity. Mass-market shampoo demand concentrates in Tel Aviv's supermarket channels, where private-label competition from Shufersal and Rami Levy squeezes branded margin pools.
- Conditioners:Cationic surfactant and emollient blends deposit conditioning agents onto hair cuticles. Salon-exclusive conditioner lines in Jerusalem's styling establishments command premium positioning through stylist recommendation networks that bypass retail price transparency.
- Hair Oils:Silicone-free botanical formulations, particularly argan-derived products, target heat-damaged hair repair in Haifa's coastal climate exposure zones.
- Styling Products:Polymer-based hold formulations face volatile alcohol content restrictions under evolving Ministry of Health labeling requirements.
Established volume favors Shampoos; emerging adoption favors Hair Oils.
End User:
Professional versus household purchasing patterns split procurement economics, with salon networks consolidating collective bargaining power in Israel's concentrated urban corridor.
- Salons:Licensed styling establishments in Tel Aviv and Jerusalem purchase through professional distributors with volume-tiered pricing structures. These operators drive premium-brand trial through in-service product demonstrations that convert clients to take-home retail purchases.
- Individual Consumers:Household replenishment cycles sustain supermarket and pharmacy channel volumes across Israeli cities. Subscription model adoption among Tel Aviv millennials is fragmenting traditional episodic purchasing patterns.
- Beauty Schools:Training institutions in Rehovot's educational corridor generate bulk demand for practice-grade formulations at cost-sensitive price points.
- Distributors:Wholesale intermediaries control pharmacy network access, extracting slotting fees that disadvantage emerging import brands seeking Israeli market entry.
Volume concentration sits with Individual Consumers; margin expansion favors Salons.
Distribution Channel:
Channel gatekeeper power varies sharply, with supermarket chains and pharmacy networks imposing divergent cost structures on brand economics.
- Online Retail:Direct-to-consumer platforms enable subscription-based replenishment models that bypass traditional retail markups. Tel Aviv's dense digital-native population exhibits conversion rates for automated delivery schedules that outpace national averages.
- Specialty Stores:Curated beauty retailers in Jerusalem's Mamilla district and Tel Aviv's Dizengoff Center stock boutique ingredient lines with provenance narratives that justify premium positioning.
- Supermarkets:Shufersal, Rami Levy, and Victory chains control shelf space allocation, extracting listing fees that consolidate advantages for multinational brands with marketing budgets.
- Pharmacies:Super-Pharm and private pharmacy networks emphasize dermatologist-recommended scalp care formulations, creating crossover positioning between cosmetic and quasi-medical categories.
Broadest reach belongs to Supermarkets; steepest expansion trajectory belongs to Online Retail.
Hair Type:
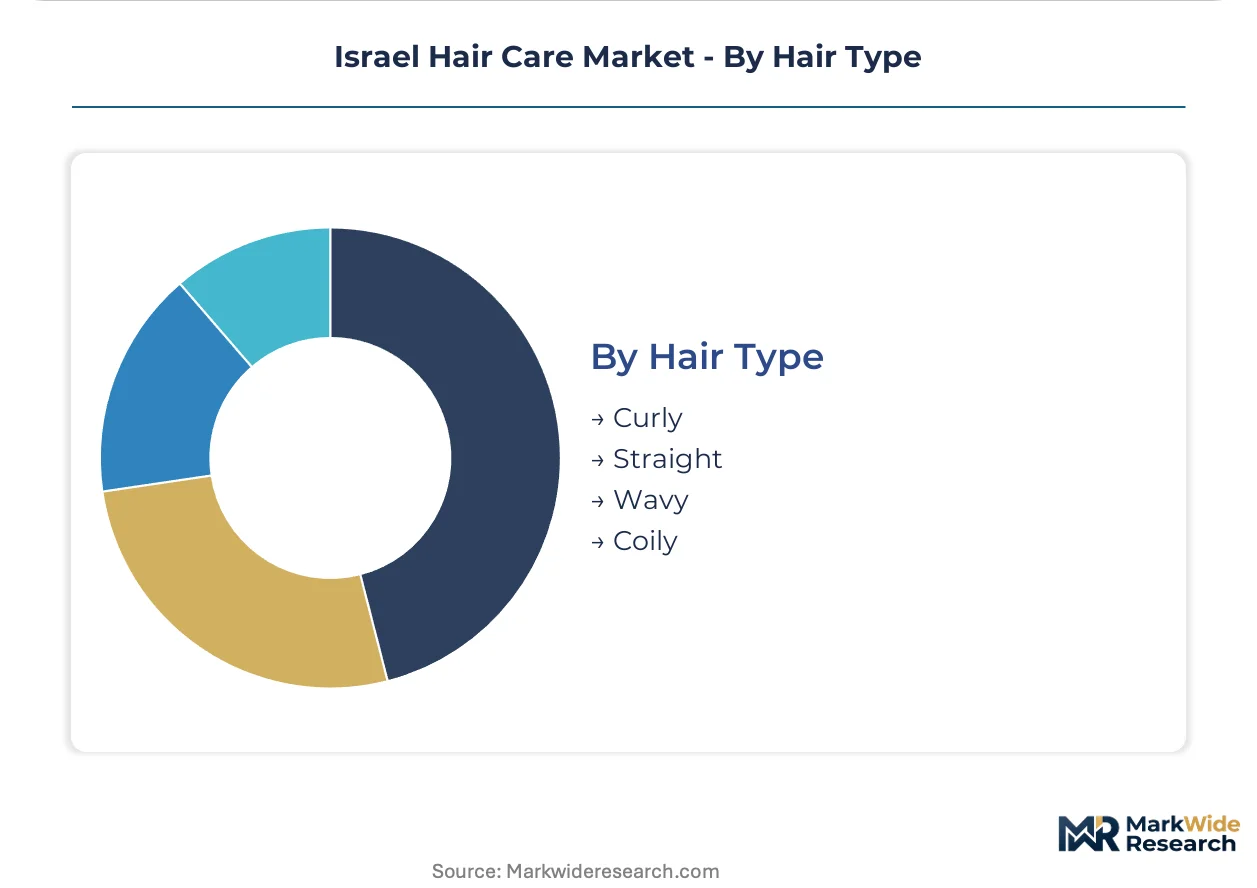
Texture-specific formulation requirements create niche specialization opportunities for domestic chemists with pH-balancing expertise.
- Curly:High-moisture, sulfate-free formulations address curl pattern definition and frizz control in Israel's humid coastal zones around Haifa.
- Straight:Lightweight conditioning systems avoid weighing down fine hair textures prevalent in Ashkenazi demographic concentrations.
- Wavy:Hybrid products balancing moisture and volume target Israel's largest texture segment with multi-benefit positioning.
- Coily:Intensive oil-based treatments serve smaller but underserved demand pockets with limited domestic formulation options.
Mass-market scale favors Wavy; unmet need concentration favors Coily.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's hair care consumption patterns diverge sharply from neighboring Middle Eastern markets, with Tel Aviv and Jerusalem driving premium salon-channel uptake while peripheral cities sustain mass-market supermarket volumes. The Ministry of Health's EU-aligned cosmetic regulations create compliance thresholds that reshape competitive access across the country's urban corridor.
Tel Aviv Metropolitan Area
Professional salon networks in Tel Aviv concentrate Israel's highest per-capita spending on premium styling products and keratin treatments. The Ministry of Health's cosmetic registration requirements filter imported formulations through extended documentation timelines. Dizengoff Center and Rothschild Boulevard retail clusters host specialty beauty retailers curating boutique ingredient lines with provenance narratives.
Jerusalem
Jerusalem's styling establishments emphasize salon-exclusive conditioner lines distributed through professional networks that bypass retail price transparency. Municipal business licensing intersects with national cosmetic safety standards to shape establishment density in the Mamilla district. Ultra-Orthodox demographic concentrations create distinct demand pockets for modesty-aligned hair care procurement patterns.
Haifa Coastal Zone
Haifa's humid Mediterranean climate drives specialized demand for frizz-control formulations and silicone-free botanical hair oils. The Ministry of Health's labeling requirements for alcohol content in styling products affect polymer-based hold formulation availability. Coastal exposure zones around the port city accelerate heat-damage repair product turnover among professional end users.
Central District (Rehovot Corridor)
Rehovot's research corridor concentrates Israel's scarce cosmetic chemist talent for pH-balanced scalp-compatible formulation development. Dual regulatory pressure from Ministry of Health registration and EU export compliance creates product launch delays for domestic manufacturers. Beauty schools in the educational corridor generate bulk demand for practice-grade formulations at cost-sensitive price points.
Southern District (Beersheba)
Beersheba's emerging urban center exhibits growing pharmacy-network penetration for dermatologist-recommended scalp care formulations. Super-Pharm and private pharmacy chains emphasize crossover positioning between cosmetic and quasi-medical categories. The city's distance from Tel Aviv's salon density sustains stronger individual consumer replenishment cycles through supermarket channels.
Israel Hair Care Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Israel's hair care structure, with multinational R&D infrastructure commanding salon-channel positioning while boutique ingredient specialists capture specialty retail margins. The market organizes around three strategic archetypes: global beauty conglomerates leveraging compliance scale, argan-oil and botanical provenance specialists, and pharmacy-network distributors with disciplined channel partnerships. Competitive moves concentrate on portfolio diversification into scalp-dermatology hybrids and direct-to-consumer digital bypass of traditional retail gatekeepers.
Among the integrated multinational tier, L'Oréal S.A. and Henkel AG & Co. KGaA exemplify archetypes built on global formulation libraries and professional salon anchoring. Moroccanoil Inc occupies a specialist position derived from single-ingredient provenance narratives that command premium shelf space in curated retail environments. Kao Corporation represents the pharmacy-network distribution model, with disciplined partnerships navigating Israel's concentrated Super-Pharm and private pharmacy channels.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Moroccanoil Inc |
| L'Oréal S.A. |
| Shiseido Company Limited |
| Pierre Fabre Group (Klorane) |
| The Procter & Gamble Company |
| Kao Corporation |
| Revlon Inc |
| Unilever PLC |
| Others |
Supply & Pricing Matrix
Synthetic peptide complexes replacing conventional keratin treatments are simultaneously relocating formulation sourcing toward Rehovot's research corridor and compressing margin structures for petroleum-derived conditioning agents. This substitution dynamic concentrates premium pricing power among biotechnology-enabled domestic producers while squeezing commodity shampoo margins.
Pricing Analysis
Contract structures in Israel's hair care sector favor annual volume commitments between salon distributors and multinational manufacturers, with spot purchasing limited to raw material inputs. Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive peptide formulations from mass-market supermarket lines and private-label alternatives. Price differentiation stems from Ministry of Health registration tier and stylist recommendation network depth. Pricing pressure intensifies in supermarket channels as Shufersal and Rami Levy expand private-label shelf space. Individual consumers exhibit highest price sensitivity, while professional salons absorb premium markups for provenance-narrative products.
Supply Chain Analysis
France and Japan anchor premium active ingredient supply for peptide complexes and botanical extracts serving Tel Aviv's salon segment. Morocco and Argentina provide argan oil feedstock for specialty hair oil formulations. Israel's domestic production draws from petroleum-derived surfactant bases sourced from regional refineries. Single-source vulnerability concentrates in Rehovot's limited cosmetic chemist talent pool for pH-balanced formulation development. Distribution runs through professional salon distributors, pharmacy networks, and direct-to-consumer platforms with divergent margin extraction profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Israel's hair care sector sits in early-cycle expansion as clean-beauty certification requirements accelerate premium-brand adoption among safety-conscious urban households. Subscription-based digital commerce penetration remains below saturation thresholds in peripheral districts.
For Market Incumbents: Fortify salon-channel positioning through exclusive peptide formulation partnerships that preempt biotechnology entrant disruption. Deepen backward integration into Rehovot research corridor talent pools to secure scarce pH-balancing expertise. Expand Ministry of Health compliance infrastructure to capture shelf space from delayed import registrations. For New Entrants and Emerging Players: Ministry of Health clean-beauty certification fast-track enables premium positioning in Tel Aviv's specialty retail corridor with abbreviated registration timelines. Target coily hair texture segments with intensive oil-based treatments where domestic formulation options remain limited. Deploy direct-to-consumer subscription models to bypass supermarket listing fee barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of boutique ingredient specialists with established provenance narratives. Long-term viability hinges on regulatory compliance infrastructure and digital-native customer acquisition capabilities. Monitor Ministry of Health documentation requirement tightening as inflection signal for import brand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Beauty Certification Acceleration | Ministry of Health alignment creates first-mover shelf access in Tel Aviv premium segment. |
| Direct-to-Consumer Platform Launch | Subscription models bypass Shufersal and Rami Levy listing fee extraction. |
| Peptide Formulation R&D Investment | Biotechnology-derived actives displace commodity keratin in salon service menus. |
| Professional Salon Distribution Partnership | Stylist recommendation networks convert in-service demonstrations to retail purchases. |
| Scalp-Dermatology Hybrid Development | Crossover positioning captures medical aesthetics demand from Super-Pharm channels. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulators, professional salon owners, pharmacy category managers, and Ministry of Health regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain stakeholders and observational analysis of retail channel dynamics. Secondary sources encompassed Ministry of Health cosmetic registration databases, Super-Pharm and Shufersal shelf-space audit data, and EU REACH chemical safety documentation. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers by product category, end-user segment, and distribution channel. Segmentation dimensions modeled include formulation type, professional versus household procurement pattern, and regional urban density cluster. CAGRs derive from fitted growth curves calibrated to historical adoption patterns and regulatory milestone impacts. Forecast inputs incorporate Ministry of Health registration timeline assumptions and salon network expansion rates in Haifa and Rishon LeZion.
Underlying assumptions cover stable EU-Israel regulatory alignment and sustained petroleum-derived surfactant price volatility, with deviation risk concentrated in Ministry of Health documentation requirement acceleration and digital commerce regulatory intervention. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Sweden Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Men's Hairspray Market
Hair Care
Global Premium Hair Care Market
Hair Care
Italy Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
China Hair Care Products Market
Hair Care
Hair Care Market
Hair Care
Protein Shampoo Market
Hair Care
Brazil Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Anti Pollution Hair Care Products Market
Hair Care
Asia Pacific Hair Care Market
Hair Care
Canada Hair Care Market
Hair Care
Hair Clay Market