
 Fruit Punnet Market | 2026-2036
Fruit Punnet Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Punnet Market Foresight
European molded fiber capacity is hardening as converters respond to supermarket sustainability mandates. Smurfit Kappa Group plc leverages its integrated pulp-to-packaging network across Ireland and continental Europe to secure long-term produce supply contracts. Groupe Guillin SA anchors its position through deep specialization in thermoformed PET and rPET punnets for soft-fruit categories. INFIA srl competes via advanced hinged-lid designs that reduce film sealing requirements while maintaining shelf life.
A fruit punnet is a shallow, open-topped container, typically 150–500 grams in nominal capacity, designed to protect, display, and ventilate fresh fruit through engineered perforation patterns or micro-perforated film lids. It serves the dual commercial purpose of reducing mechanical damage during cold-chain distribution and enabling brand differentiation at the retail shelf. PET and rPET punnets currently dominate volume in berry and grape applications where optical clarity drives consumer purchase decisions, while molded fiber and wood pulp alternatives are capturing the fastest growth in organic and premium produce segments where plastic-free claims command shelf space. Clamshell and hinged-lid formats hold the deepest margin pools due to their theft-deterrence properties and reduced secondary wrapping needs.
EU REACH regulations and the Single-Use Plastics Directive constrain virgin plastic incorporation, while FDA food-contact material standards govern export-bound production from European converters supplying US retailers. EFSA migration limits for recycled content in food contact are tightening testing protocols and favoring suppliers with certified closed-loop rPET streams. Stakeholders must monitor evolving Extended Producer Responsibility fee structures and decide whether to invest in captive pulp molding capacity or secure multi-year supply agreements with emerging fiber converters.
Market Dynamics
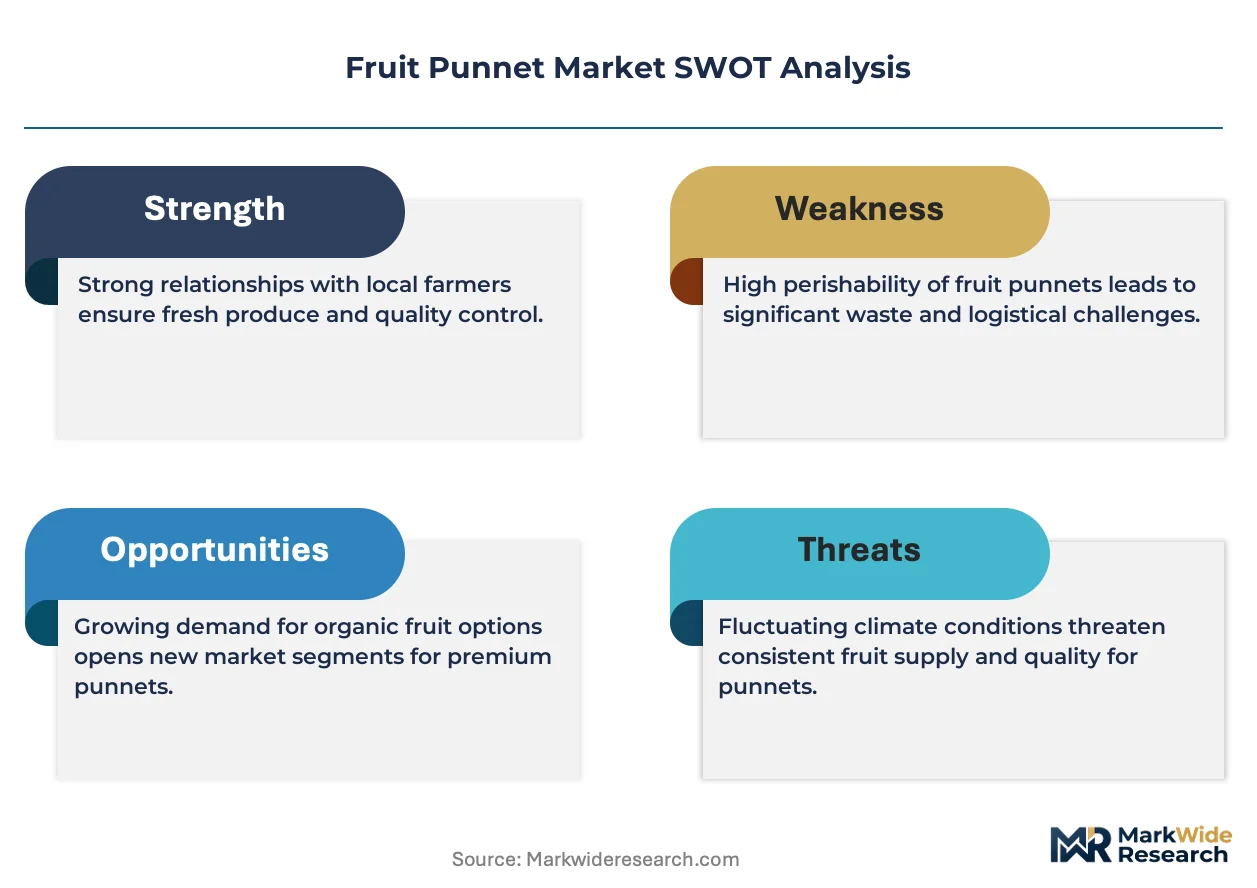
The EU Single-Use Plastics Directive is compressing virgin PET demand while forcing converters to requalify entire product lines for molded fiber and rPET alternatives within compressed timelines.
Growth Catalysts
- Supermarket consolidation:German, French, and British retail chains are mandating shelf-ready packaging formats that reduce in-store labor. This standardization favors punnet suppliers with automated packing line integration.
- REACH compliance deadlines:ECHA restrictions on intentionally added microplastics are accelerating migration toward wood pulp and molded fiber substrates in organic produce segments.
- Cold-chain expansion:Berry and grape exporters in Spain and Italy are adopting hinged-lid punnets with micro-perforated films to extend shelf life during extended distribution.
Market Restraints
- Pulp input volatility:Nordic softwood pulp prices fluctuate with energy costs, squeezing molded fiber converter margins when oil markets spike.
- rPET supply concentration:Food-grade recycled flake availability clusters in Germany and the Netherlands, creating geographic dependency for converters outside these zones.
- Migration testing bottlenecks:EFSA protocols for recycled content in food contact extend certification timelines by 8-14 months, delaying product launches.
Strategic Opportunities
- Portuguese market penetration:Modern retail formats remain underdeveloped in Portugal relative to Spain, creating first-mover advantage for standardized punnet suppliers.
- Reusable crate pooling:Dutch supermarket trials of returnable fiber punnets could displace single-use formats if logistics networks achieve critical density.
- Digital watermark integration:Combined printed electronics and molded fiber substrates enable item-level traceability for premium berry categories.
Industry Challenges
- Thermoforming tool reconfiguration:Shifting from PET to fiber requires complete mold redesigns, straining converter engineering capacity.
- Multi-material separation:Film-lid removal from fiber bases complicates consumer recycling behavior and contaminates pulp waste streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Punnet Market |
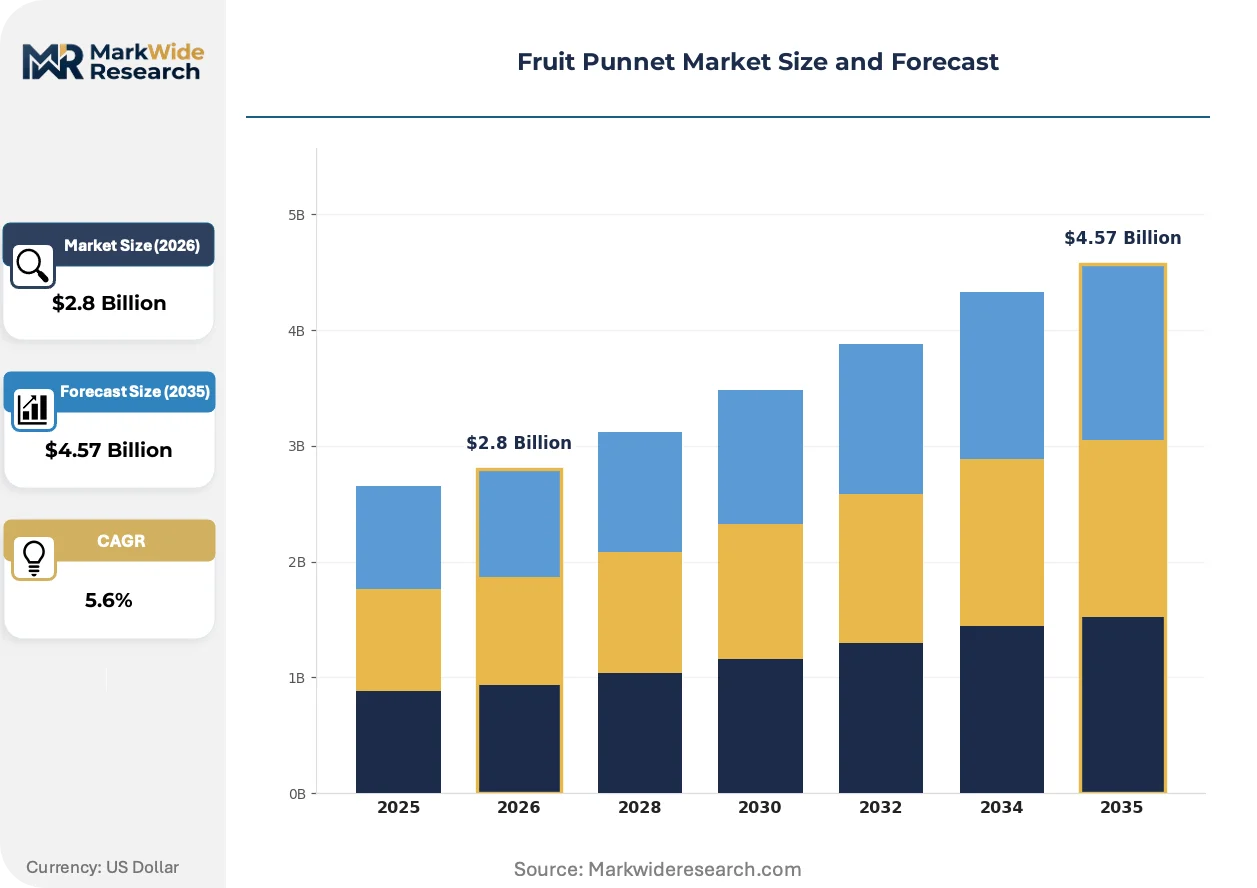
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood Pulp, Corrugated Fiberboard, PET, PLA, Paperboard End Use/Application: Fresh Produce Packaging, Ready-to-Eat Fruits, Organic Fruits, Bulk Fruit Packaging, Display Packaging Packaging Style: Clamshell, Tray, Sleeve, Sleeve with Handle, Hinged Lid Distribution Channel: Supermarkets, Grocery Stores, Farmer Markets, Online Retail, Wholesale Distributors |
| Companies Covered | Smurfit Kappa Group plc, LC Packaging International BV, AVI Global Plast Pvt Ltd, Ilip s.r.l., INFIA srl, Van Der Windt Packaging Ltd, T&B Containers Ltd, Coveris Holding SA, Groupe Guillin SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Punnet Market Shifts & Advancements
Active barrier coatings and fiber molding advances are collapsing the performance gap between plastic and plant-based alternatives. These shifts are redrawing competitive boundaries across material supply chains.
Barrier-coated molded fiber is electrifying moisture resistance in berry applications. Dutch and Belgian organic retailers are specifying these punnets for private-label lines. The technology is compressing the premium pricing differential that previously protected PET in soft-fruit categories.
EFSA migration limits for recycled polymers are tightening testing burdens on rPET converters. Suppliers with certified closed-loop flake streams gain preferential qualification status. Berry packers in Germany and the United Kingdom are consolidating purchases around these pre-qualified supply bases.
Retailers are unbundling secondary wrapping from primary punnet functions. French supermarket chains now specify hinged-lid formats with integrated theft deterrence, eliminating shrink-wrap stations. This specification shift is most visible in urban convenience formats across Paris and Lyon.
Fruit Punnet Market Segmentation
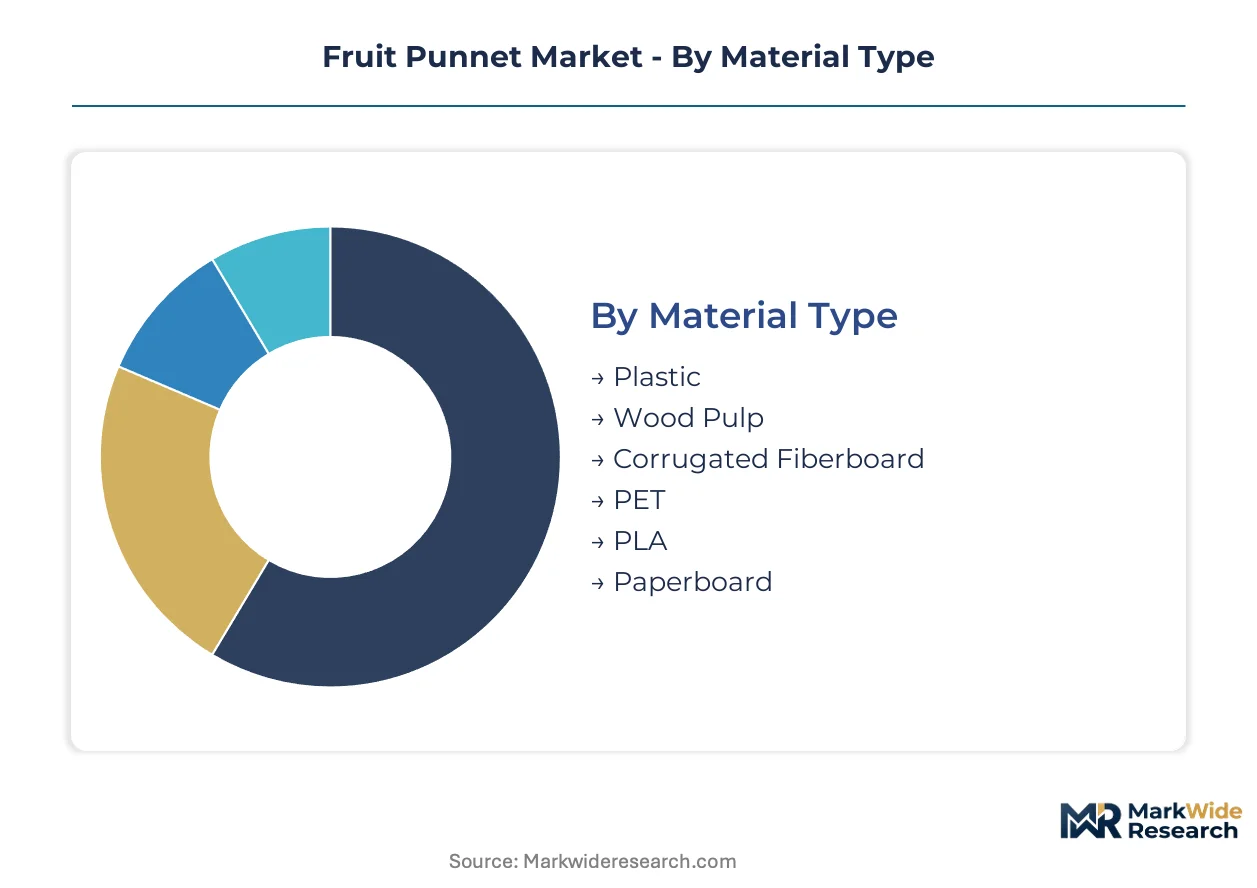
Fruit punnet segmentation reveals how material choices, packaging formats, and channel requirements fragment procurement decisions across European retail. Understanding these divides exposes where converters can defend margin pools and where substrate substitution threatens incumbent positions.
Material Type:
Technical specifications around barrier performance, optical clarity, and regulatory compliance differentiate material selection across produce categories and retail tiers.
- PET:Virgin and recycled polyethylene terephthalate delivers the optical transparency that berry and grape merchandising demands in German and British supermarkets. EFSA migration testing protocols favor converters with certified closed-loop rPET streams, consolidating procurement around pre-qualified suppliers.
- Wood Pulp:Molded fiber substrates from Nordic softwood sources are capturing organic produce shelf space as French and Dutch retailers enforce plastic-free private-label mandates. Barrier coating advances are collapsing the moisture-resistance gap that previously protected plastic in soft-fruit applications.
- Corrugated Fiberboard:Secondary containment for bulk distribution and club-store formats where stacking strength outweighs retail presentation requirements.
- PLA:Polylactic acid from agricultural feedstocks serves compostable claims in Belgian and Austrian organic retail channels with industrial composting infrastructure.
- Paperboard:Flat blanks and folding cartons for sleeve-style applications with minimal moisture exposure, common in dry-husk fruits.
- Plastic:Polypropylene and polystyrene legacy formats in price-sensitive Eastern European markets where EU Single-Use Plastics Directive enforcement remains phased.
PET leads on scale; wood pulp leads on momentum.
End Use/Application:
Application-driven segmentation tracks how shelf-life extension, theft deterrence, and brand differentiation reshape format specifications.
- Fresh Produce Packaging:Standard berry, grape, and cherry tomato punnets where ventilation engineering and cold-chain compatibility determine converter qualification. German retail consolidation favors automated packing line integration.
- Organic Fruits:Plastic-free claims command premium shelf positioning in French and Dutch organic specialists, driving specification shifts toward molded fiber with barrier coatings.
- Ready-to-Eat Fruits:Cut-fruit and convenience formats requiring modified atmosphere packaging and extended shelf-life validation for urban convenience stores.
- Display Packaging:Shelf-ready presentation formats with integrated branding and theft-deterrence features for high-traffic urban formats.
- Bulk Fruit Packaging:Large-capacity formats for club stores and foodservice where unit economics prioritize material efficiency over unit presentation.
Fresh produce packaging anchors volume concentration; organic fruits expand most quickly.
Packaging Style:
Structural format selection balances labor reduction, product protection, and retail presentation requirements across distribution contexts.
- Clamshell:Two-piece hinged designs dominate berry categories where theft deterrence and reduced secondary wrapping compress total packaging cost. French supermarket chains now specify these formats for urban convenience stores.
- Hinged Lid:Integrated lid designs with micro-perforated film compatibility extend shelf life for Spanish and Italian exporters operating extended cold-chain distribution.
- Tray:Open-topped formats for film-sealed applications where optical clarity and top-seal integrity drive purchase decisions.
- Sleeve:Paperboard wraps for netted or loose produce where ventilation and material cost minimization outweigh structural protection.
- Sleeve with Handle:Carrying convenience for gift and premium formats in seasonal stone-fruit categories.
Clamshell formats hold the deepest margin pools; hinged-lid designs gain share fastest.
Distribution Channel:
Channel-specific requirements fragment demand between standardized retail formats and fragmented wholesale and direct-to-consumer pathways.
- Supermarkets:Shelf-ready packaging mandates from German, French, and British chains drive standardization toward automated packing line compatibility and reduced in-store labor.
- Online Retail:E-commerce fulfillment demands damage resistance and temperature stability for last-mile delivery, favoring sturdier clamshell formats over film-sealed trays.
- Grocery Stores:Smaller-format independents with mixed manual and semi-automated packing operations.
- Farmer Markets:Low-volume, high-variety demand with minimal standardization and price-sensitive material selection.
- Wholesale Distributors:Bulk-focused procurement prioritizing unit cost and stacking efficiency over retail presentation.
Supermarkets concentrate procurement volume; online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as converters seek cost-of-compliance advantages. The EU Single-Use Plastics Directive creates divergent compliance burdens that favor fiber-molding investments in Nordic pulp regions while pressuring legacy PET capacity in Southern Europe.
Germany
Retail consolidation at Aldi Süd and REWE Group is standardizing shelf-ready specifications across berry and grape categories. EFSA migration testing protocols for recycled content favor converters with certified closed-loop rPET streams in the Rhine-Ruhr industrial belt. Bavarian packaging clusters near Nuremberg are expanding molded fiber capacity to serve organic private-label mandates from Munich-based retailers.
France
Carrefour and Intermarché chains are mandating hinged-lid formats with integrated theft deterrence for urban convenience stores in Paris and Lyon. ANSM food-contact material standards align with EU REACH frameworks, streamlining qualification for domestic converters. The Auvergne-Rhône-Alpes region hosts specialized thermoforming operations supplying soft-fruit packers in the Drôme Valley.
United Kingdom
Tesco and Sainsbury's procurement teams are consolidating purchases around automated packing line compatibility, favoring standardized punnet dimensions. The UK's post-Brexit regulatory divergence from EU EFSA protocols is extending certification timelines for recycled content imports. Packaging engineering clusters in the West Midlands are developing barrier-coated fiber alternatives for premium berry categories.
Italy
Extended cold-chain distribution from Sicilian and Puglian berry exporters is driving hinged-lid adoption with micro-perforated film compatibility. CE marking requirements govern intra-EU shipments, while national compostability certifications support PLA formats in Northern organic retail channels. Emilia-Romagna converters specialize in rPET qualification for export-bound production.
Netherlands
Albert Heijn and Jumbo supermarket trials of returnable fiber punnet pooling systems could displace single-use formats if logistics networks achieve critical density. ECHA restrictions on intentionally added microplastics are accelerating specification shifts toward wood pulp substrates in organic produce segments. Rotterdam-area converters leverage port proximity for Nordic pulp supply security.
Fruit Punnet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue barrier-coated fiber and digital traceability integration. The market structure consolidates around integrated pulp-to-packaging networks, specialized thermoforming operations, and format-specific engineering houses. Three archetypes dominate: Nordic pulp-integrated conglomerates, Southern European rPET specialists, and hinged-lid design innovators. Competitive moves center on captive pulp molding capacity investments and multi-year supply agreements with retail chains.
Among Ireland and continental Europe-based integrated producers, Smurfit Kappa Group plc exemplifies the pulp-network archetype. Groupe Guillin SA occupies a position representing thermoformed PET specialization for optical clarity applications. INFIA srl anchors the hinged-lid engineering tier with format innovations reducing secondary wrapping requirements.
| Leading Market Players |
|---|
| Smurfit Kappa Group plc |
| LC Packaging International BV |
| AVI Global Plast Pvt Ltd |
| Ilip s.r.l. |
| INFIA srl |
| Van Der Windt Packaging Ltd |
| T&B Containers Ltd |
| Coveris Holding SA |
| Groupe Guillin SA |
| Others |
Supply & Pricing Matrix
German supermarket consolidation around shelf-ready packaging formats is forcing converters to absorb automation costs while defending margin pools in premium berry segments. This demand-side pressure reshapes supply economics across Nordic pulp networks and Rhine-Ruhr thermoforming clusters.
Pricing Analysis
Retailer markup layers dominate final landed cost structures, with German and British chains extracting compliance premiums for EFSA-certified rPET streams. Three-tier pricing structure across premium barrier-coated fiber, standard rPET, and economy virgin PET reflects certification grade and volume scale differentiation. Pricing pressure stems from pulp input volatility tied to Nordic energy markets, squeezing molded fiber converter margins. Price-sensitive Eastern European independents favor legacy PP formats, while Dutch organic specialists absorb premium fiber costs.
Supply Chain Analysis
Skilled thermoforming engineer shortages in Emilia-Romagna and Auvergne-Rhône-Alpes constrain mold reconfiguration capacity as converters shift from PET to fiber. Geographic supply concentration centers on Germany for food-grade rPET flake, the Netherlands for barrier coating innovation, and Portugal for underdeveloped retail penetration. Raw material dependencies rest on Nordic softwood pulp, German recycled PET streams, and Belgian coating chemistry. Single-source vulnerability clusters around German rPET qualification bottlenecks. Distribution runs through centralized supermarket procurement hubs in Düsseldorf, Paris, and London.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through barrier-coated fiber adoption displacing PET in premium organic tiers, while automation investments compress unit labor costs for shelf-ready formats.
For Market Incumbents: Extend barrier-coated fiber capacity in Bavarian and Dutch clusters to capture French organic retail mandates before rPET specialists requalify. Deepen captive pulp supply agreements with Nordic producers to offset energy-linked input volatility. Lock in multi-year automated packing line integration contracts with REWE and Carrefour to entrench switching costs against hinged-lid engineering entrants. For New Entrants and Emerging Players: Launch via Portuguese modern retail expansion where standardized punnet specifications remain unsettled and incumbent presence is thin. Target hinged-lid formats with micro-perforated film compatibility for Spanish berry exporters extending cold-chain reach. Pursue digital watermark integration partnerships with Dutch supermarket pooling trials to differentiate beyond material substitution. For Investors and Strategic Acquirers: Asymmetric upside sits with barrier-coated fiber converters possessing certified closed-loop pulp streams and pre-qualified supermarket supply agreements. Long-term viability favors integrated pulp-to-packaging networks over standalone thermoforming operations exposed to EFSA migration testing delays. Watch for Dutch returnable crate pooling trials achieving critical logistics density as the inflection signal for single-use displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Pulp Supply | Captive softwood sourcing insulates converters from energy-driven input cost spikes. |
| Barrier Coating Technology Licensing | Dutch and Belgian coating specialists unlock moisture resistance parity with PET in berry applications. |
| Automated Packing Line Partnership | German retail consolidation rewards converters with pre-integrated shelf-ready format capabilities. |
| EFSA Pre-Qualified rPET Stream Acquisition | Certified closed-loop flake access compresses migration testing timelines for berry packers. |
| Digital Watermark Integration Development | Item-level traceability meets French and Dutch premium retail provenance requirements. |
Research Methodology
Multiple input streams — converter production data, supermarket procurement specifications, and regulatory filing trajectories — were reconciled across primary interviews with packaging engineers, category buyers at German and French retail chains, molded fiber plant managers, and EFSA compliance consultants. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, REACH restriction updates, Nordic pulp trade statistics, and supermarket sustainability disclosure filings. Bottom-up capacity assessments and top-down retail spend estimates were triangulated to anchor volume and value figures.
Historical capacity utilization and panel-based demand projections were cross-referenced to build the analytical framework across the analysis window. Segmentation dimensions modeled include material substrate, packaging format, produce category, retail channel tier, and regional regulatory cluster. CAGRs were derived from slope consensus across converter expansion announcements and retail shelf-space allocation trends. Industry-specific inputs incorporated EFSA migration testing queue lengths and barrier coating performance validation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp price volatility spikes or accelerated Dutch reusable crate scaling. Material deviation in EFSA protocol tightening, German retail merger clearance, or Nordic energy market disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Spain Table Grape Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Europe Dried Mushroom Market