
 Singapore Data Center Cooling Market | 2026-2036
Singapore Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Cooling Market Insights
Modular rack-level cooling is pivoting buyer procurement toward prefabricated, factory-integrated thermal units that slash on-site commissioning time. Schneider Electric SE leverages its EcoStruxure platform to anchor integrated power and cooling architectures across Southeast Asian deployments. Vertiv Group Corp competes through its Liebert liquid cooling portfolio, while STULZ GmbH specializes in precision air conditioning systems engineered for tropical humidity regimes.
Singapore data center cooling encompasses engineered thermal management systems—precision air handlers, chilled water loops, direct-to-chip cold plates, and evaporative heat rejection—designed to maintain server inlet temperatures between 18°C and 27°C per ASHRAE guidelines while minimizing energy use in equatorial climates. Liquid cooling is displacing legacy air systems in high-density artificial intelligence clusters where rack loads exceed 30 kilowatts, while hybrid cooling configurations serve colocation facilities balancing legacy enterprise tenants against emerging GPU-intensive workloads. Managed services are capturing margin pools as operators outsource thermal optimization to vendors with predictive analytics capabilities.
IMDA's Green Mark for Data Centres and the Building and Construction Authority's Green Mark certification mandate power usage effectiveness thresholds and water efficiency standards that filter market access for cooling equipment suppliers. PUB, Singapore's national water agency, restricts potable water use in evaporative systems, pushing adoption of seawater-cooled and closed-loop designs. Stakeholders must monitor how MAS climate risk guidelines for financial institutions redirect capital toward thermally efficient facilities as lending standards tighten.
Market Dynamics
Liquid cooling architectures are compressing deployment timelines across Singapore's data center corridors, as operators race to accommodate GPU-intensive artificial intelligence workloads within strict thermal and water efficiency mandates.
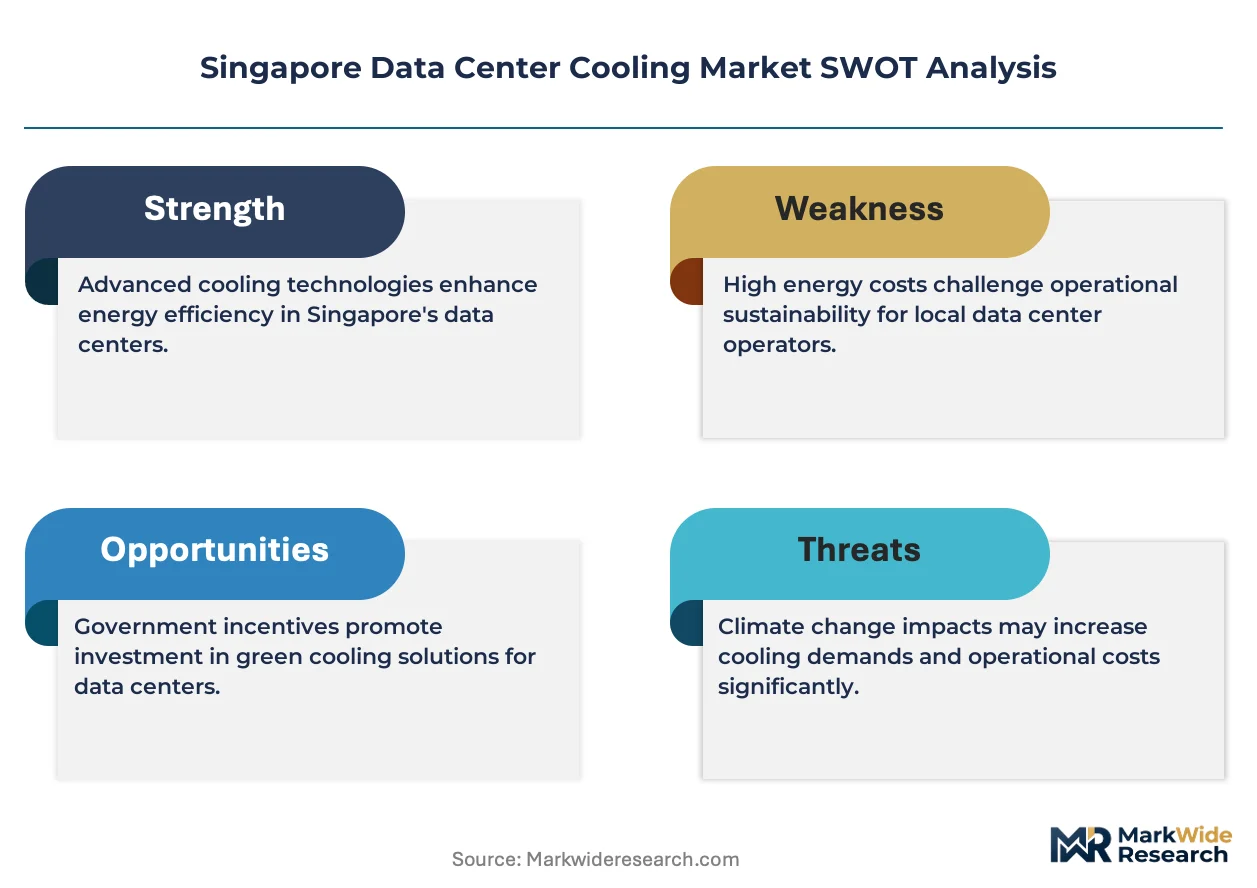
Growth Catalysts
- IMDA Green Mark for Data Centres:Certification thresholds for power usage effectiveness are accelerating equipment refresh cycles among colocation operators in Jurong and Tuas.
- Artificial intelligence training clusters:Hyperscale deployments exceeding 30 kilowatts per rack are mandating direct-to-chip liquid cooling adoption at scale.
- Tuas industrial zone expansion:Seawater cooling access is enabling closed-loop thermal designs that bypass PUB potable water restrictions.
Market Restraints
- Copper and aluminum price volatility:Cold plate and heat exchanger fabrication costs fluctuate with commodity metal markets, squeezing equipment margins.
- Specialized contractor concentration:Precision pipefitting and dielectric fluid handling expertise concentrates among a limited pool of Singapore-based mechanical contractors.
- Seawater corrosion engineering:Titanium alloy requirements for coastal heat rejection systems add material cost premiums versus inland freshwater designs.
Strategic Opportunities
- Managed thermal services:Predictive analytics contracts for cooling optimization represent recurring revenue streams beyond equipment sales.
- Hybrid air-liquid retrofit kits:Colocation facilities serving mixed legacy and AI workloads need modular upgrades without full infrastructure replacement.
- BCA Green Mark Platinum certification:Premium efficiency ratings command rental rate premiums from financial services tenants under MAS climate risk guidelines.
Industry Challenges
- Dielectric fluid chemist scarcity:Formulation expertise for engineered cooling fluids remains concentrated among a handful of regional specialists.
- ASHRAE compliance testing bottlenecks:Thermal validation for tropical humidity regimes extends product qualification timelines.
- Legacy chiller integration:Hybrid deployments require synchronization between new liquid loops and existing chilled water infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Cooling Market |
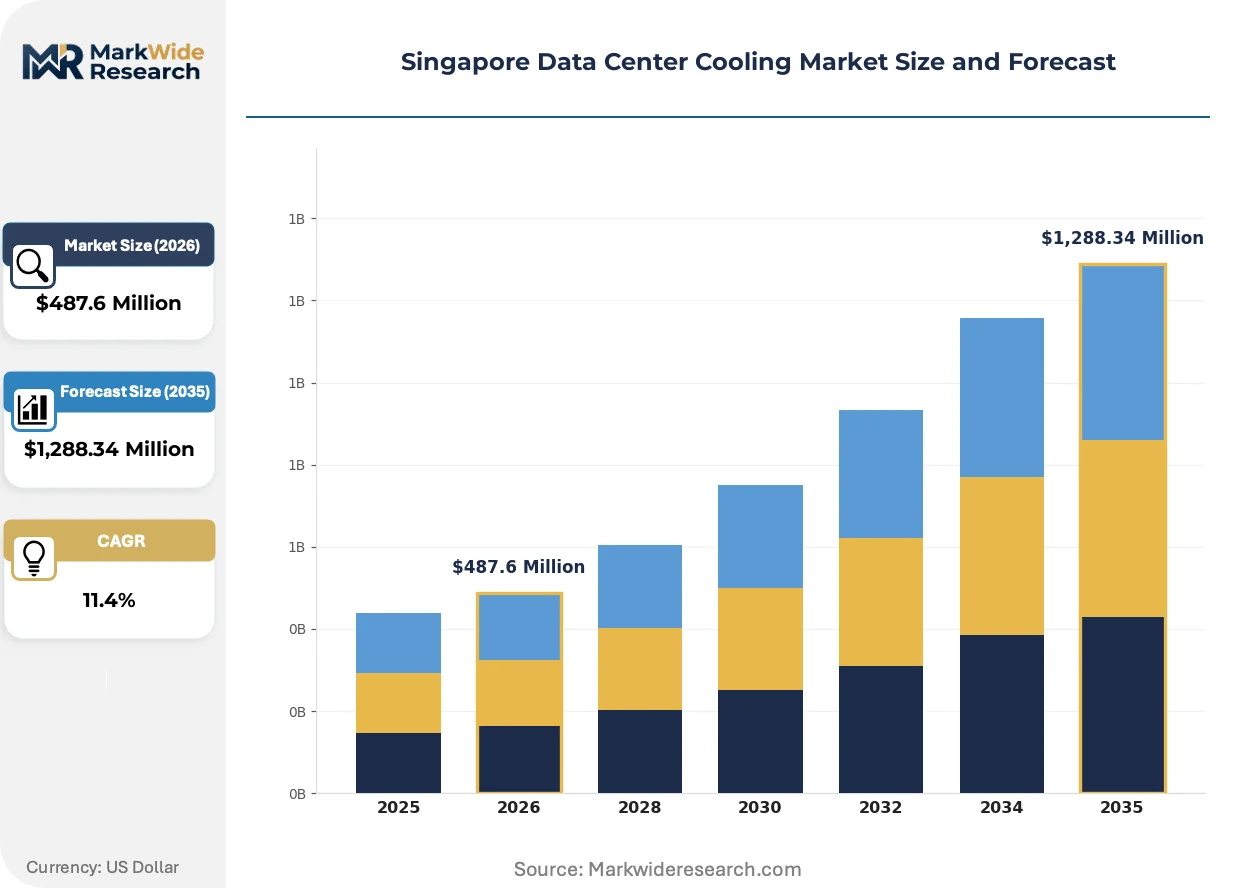
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Evaporative Cooling, Hybrid Cooling Service Type: Installation, Maintenance, Consulting, Managed Services End User: Cloud Providers, Enterprises, Colocation Facilities, Telecommunications Deployment Model: On-Premises, Off-Premises, Edge Computing, Modular Systems |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, STULZ GmbH, Rittal GmbH & Co. KG, Johnson Controls International PLC, Mitsubishi Electric Corporation, Daikin Industries Ltd, Carrier, Danfoss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Cooling Market Trends and Innovations
Thermal management architectures are pivoting from facility-scale engineering to rack-integrated systems, compressing commissioning cycles and reshaping vendor-customer relationships across Singapore's data center ecosystem.
Direct-to-chip liquid cooling is consolidating supplier ecosystems around integrated cold plate, manifold, and coolant distribution unit packages. Hyperscale operators are specifying factory-tested rack assemblies to minimize on-site integration risk. This consolidation is compressing the addressable market for standalone component vendors while elevating system integrators with thermal-fluid engineering capabilities.
PUB water use restrictions are forcing evaporative cooling designers toward seawater-compatible and adiabatic dry cooler alternatives. Equipment suppliers must now certify corrosion resistance for saline environments alongside tropical humidity performance. Colocation operators in Tuas are responding with closed-loop designs that eliminate once-through cooling water entirely.
Buyers are unbundling thermal optimization from capital equipment procurement, contracting managed services for predictive maintenance and energy performance guarantees. Colocation facilities serving financial services tenants are outsourcing cooling operations to vendors with real-time analytics platforms. This behavioral shift is most pronounced among operators seeking BCA Green Mark certification to satisfy MAS climate risk disclosure requirements.
Singapore Data Center Cooling Market Segmentation
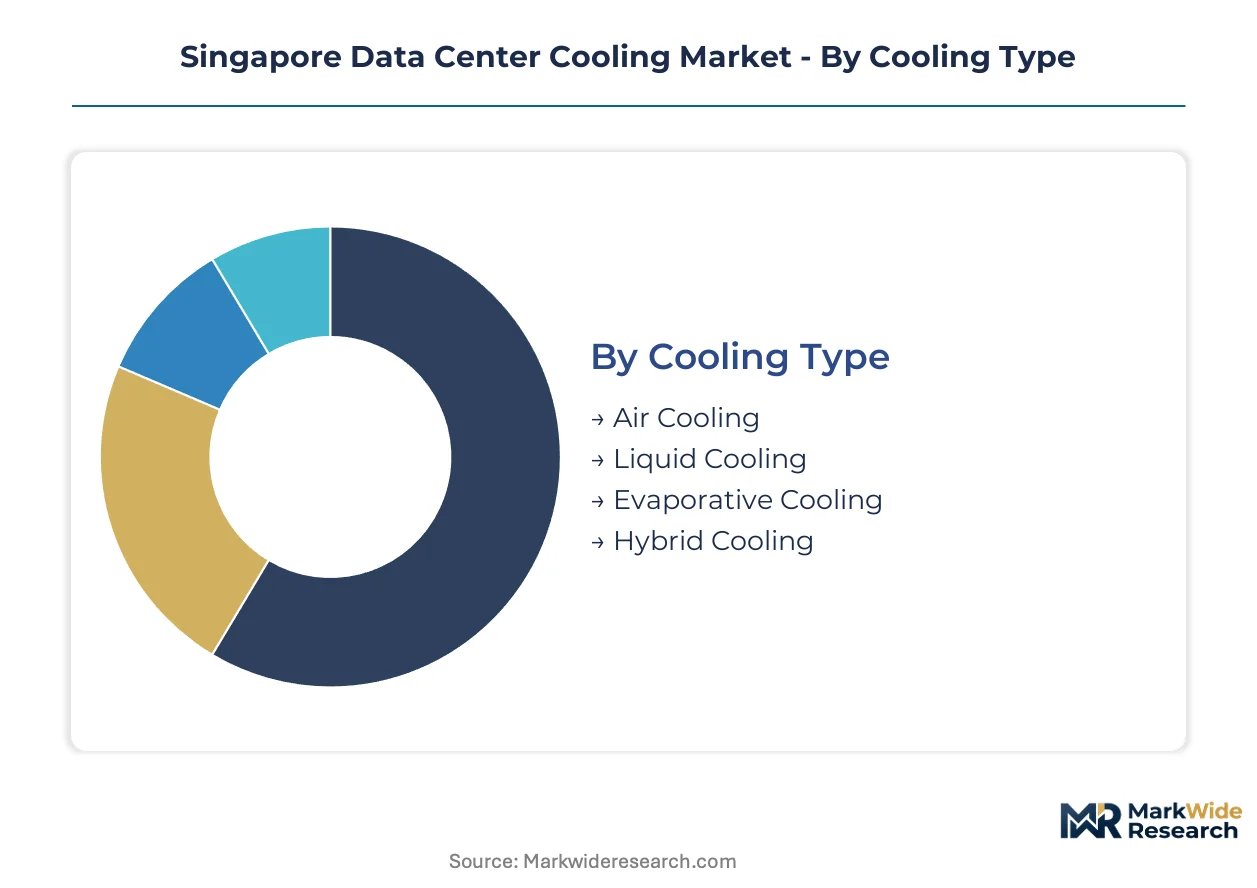
Singapore's data center cooling market fragments across thermal technology, service delivery, customer archetype, and infrastructure deployment models. Each dimension carries distinct procurement patterns shaped by IMDA sustainability mandates and hyperscale capacity expansion in Jurong and Tuas corridors.
Cooling Type:
Buyers differentiate primarily by rack power density and water efficiency constraints imposed by PUB regulations.
- Liquid Cooling:Direct-to-chip cold plates and immersion systems handle GPU-intensive AI clusters exceeding 30 kilowatts per rack. Hyperscale operators in Tuas specify factory-integrated rack assemblies to compress commissioning timelines for training workloads.
- Air Cooling:Precision air handlers with variable speed drives serve legacy enterprise colocation tenants below 15 kilowatts per rack. Jurong facilities retain these systems for mixed-density halls balancing refresh cycles against capital constraints.
- Hybrid Cooling:Configurations blend liquid loops for high-density zones with air handlers for standard racks, enabling colocation operators to serve diverse tenant profiles without full infrastructure replacement.
- Evaporative Cooling:Adiabatic and seawater-compatible designs address PUB potable water restrictions through closed-loop heat rejection, concentrating in Tuas coastal deployments with direct seawater access.
Air cooling leads volumes today; liquid cooling is gaining share fastest.
Service Type:
Procurement patterns split between capital-intensive installation contracts and recurring operational expenditures.
- Managed Services:Predictive analytics platforms for thermal optimization command multi-year contracts from financial services tenants seeking BCA Green Mark certification. Vendors guarantee energy performance thresholds while operators outsource operational risk.
- Maintenance:Preventive service agreements cover dielectric fluid monitoring, cold plate integrity testing, and chiller synchronization for hybrid architectures. Concentrated contractor expertise in Singapore limits vendor selection pools.
- Installation:Factory-integrated rack assemblies reduce on-site mechanical work, though precision pipefitting for liquid cooling manifolds requires specialized Singapore-based contractors.
- Consulting:Thermal design advisory supports BCA Green Mark Platinum pursuit and MAS climate risk disclosure preparation for financial institution tenants.
Installation commands the largest contract values; managed services shows the steepest expansion trajectory.
End User:
Customer scale determines technology specification, with hyperscale cloud operators driving liquid cooling standardization.
- Cloud Providers:Hyperscale operators specify direct-to-chip systems at rack scale, consolidating supplier ecosystems around integrated thermal-fluid packages for AI training clusters in Jurong and Tuas.
- Colocation Facilities:Multi-tenant operators balance legacy air-cooled enterprise demand against emerging GPU-intensive workloads, favoring hybrid retrofit strategies over full infrastructure replacement.
- Enterprises:Captive data centers in financial services prioritize BCA Green Mark certification to satisfy MAS climate risk guidelines, outsourcing thermal operations to managed service vendors.
- Telecommunications:Edge and central office facilities deploy modular cooling units for 5G infrastructure, with lower power densities sustaining air-cooled architectures.
Cloud providers dominate absolute capacity additions; colocation facilities are expanding most quickly.
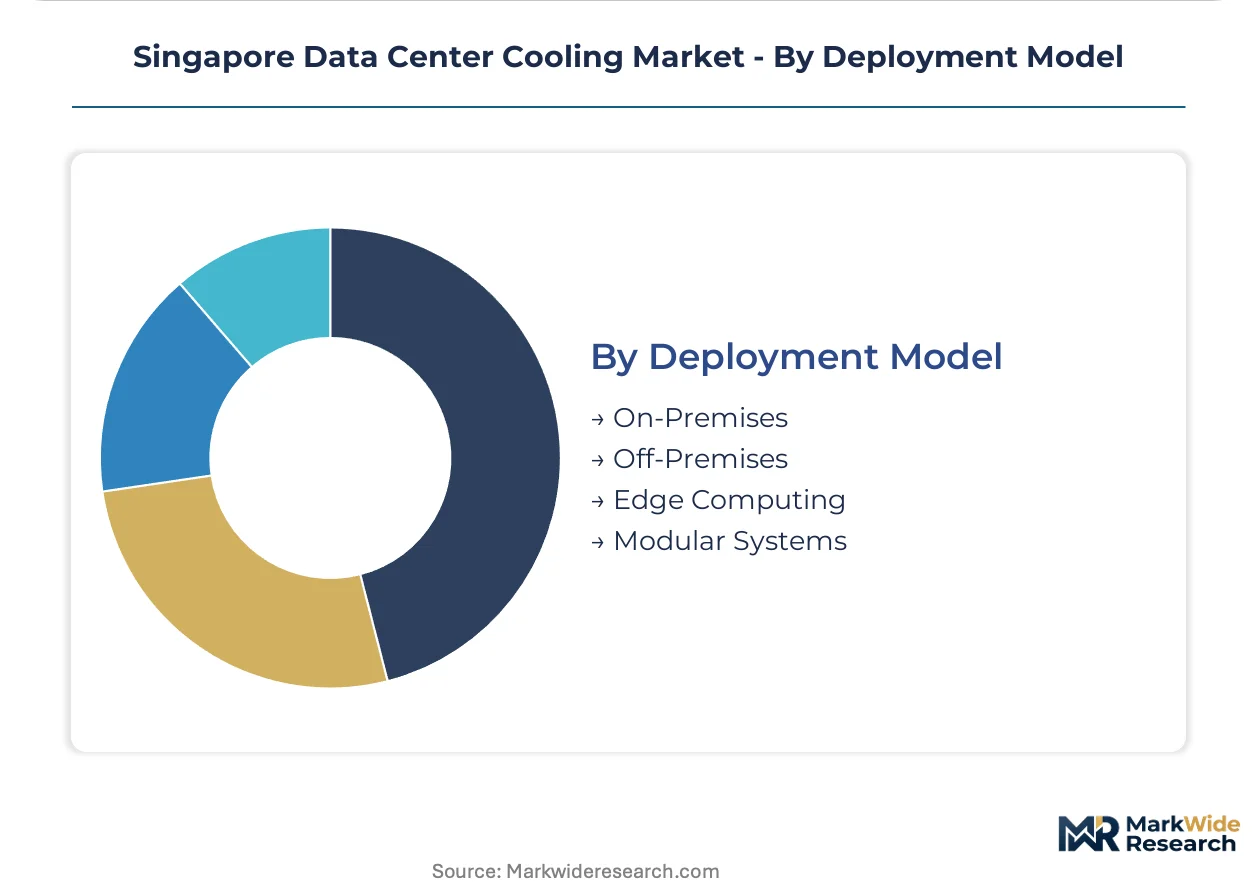
Deployment Model:
Infrastructure location and modularity shape thermal system selection against land scarcity and speed-to-market pressures.
- Modular Systems:Prefabricated, factory-integrated thermal units slash on-site commissioning time for hyperscale expansions. Singapore's limited construction labor pools amplify the value of plug-and-play rack-level cooling.
- On-Premises:Captive enterprise facilities in central business districts face space constraints that favor high-density liquid cooling over air-handling footprints.
- Off-Premises:Third-party colocation and cloud regions concentrate in Jurong and Tuas, with seawater cooling access enabling closed-loop designs that bypass PUB restrictions.
- Edge Computing:Distributed micro data centers for latency-sensitive applications deploy compact air-cooled or thermosiphon units, with lower thermal loads than centralized facilities.
Off-premises deployment leads installed base; modular systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore pioneered tropical data center engineering in Southeast Asia, establishing cooling protocols that now propagate across equatorial zones from Indonesia to Malaysia.
Indonesia
Hyperscale operators are scouting Batam and Jakarta for secondary sites outside Singapore's land-constrained perimeter. The Ministry of Communication and Informatics issued Ministerial Regulation No. 5 of 2021 on data center certification, mandating energy efficiency disclosures. Batam's Nongsa Digital Park is attracting liquid-cooled deployments for AI training clusters serving Indonesian fintech platforms.
Malaysia
Iskandar Puteri and Cyberjaya corridors are absorbing spillover demand from Singapore's capacity moratorium periods. The Malaysian Communications and Multimedia Commission enforces mandatory reporting standards for data center power usage. Johor's Sedenak Tech Park is emerging as a liquid cooling hub with direct seawater access mimicking Tuas configurations.
Thailand
Digital infrastructure investment zones in Chonburi and Bangkok are targeting regional cloud latency requirements. The National Broadcasting and Telecommunications Commission regulates data center licensing with emerging sustainability criteria. Eastern Economic Corridor developers are negotiating with Singapore-based operators for cooling technology transfer agreements.
Vietnam
Ho Chi Minh City and Hanoi data center pipelines are accelerating on foreign direct investment inflows. The Ministry of Information and Communications issued Circular 09/2022/TT-BTTTT on data center service management, establishing operational standards. Thu Duc City is piloting hybrid cooling architectures for tropical humidity regimes adapted from Singaporean designs.
Philippines
Manila and Cavite data center zones are expanding submarine cable landing capacity. The Department of Information and Communications Technology promotes data center investment through fiscal incentive packages. Clark Freeport Zone is attracting modular cooling deployments for disaster-resilient infrastructure serving regional financial services.
Singapore Data Center Cooling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across integration depth, with factory-tested rack assemblies commanding price premiums over component sales. The vendor base clusters around three strategic archetypes: integrated platform providers bundling power and thermal management, liquid cooling specialists focusing on high-density AI workloads, and precision air conditioning engineers optimizing for tropical humidity regimes. Competitive moves concentrate on vertical integration into predictive analytics services and geographic expansion through local contractor partnerships.
Among European-headquartered industrial conglomerates, Schneider Electric SE and STULZ GmbH exemplify contrasting archetypes within thermal management. Vertiv Group Corp, a US-incorporated entity, occupies a specialist position in liquid cooling portfolios. These three companies represent the tiered competitive structure: platform-integrated providers, precision environmental specialists, and direct-to-chip engineering houses.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| STULZ GmbH |
| Rittal GmbH & Co. KG |
| Johnson Controls International PLC |
| Mitsubishi Electric Corporation |
| Daikin Industries Ltd |
| Carrier |
| Danfoss |
| Others |
Pricing and Supply Chain Analysis
Precision pipefitting and dielectric fluid handling expertise concentrates among Singapore-based mechanical contractors, creating labor-cost differentials that widen pricing spreads between factory-integrated rack assemblies and field-commissioned liquid cooling installations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with BCA Green Mark Platinum certification and factory-tested thermal-fluid packages commanding premiums over uncertified field-integrated alternatives. Price differentiation hinges on ASHRAE compliance validation for tropical humidity regimes and bundled predictive analytics service contracts. Cost compression in economy-tier air-cooled systems is intensifying because Jurong colocation operators prioritize capital efficiency over liquid cooling refresh cycles. Financial services tenants seeking MAS climate risk disclosure compliance exhibit lowest price sensitivity, while telecommunications edge deployments show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Singapore, Malaysia, and Germany anchor hub-and-spoke patterns for precision air handlers and liquid cooling manifolds serving Southeast Asian deployments. Cold plate fabrication draws from Taiwanese semiconductor equipment suppliers and Japanese titanium alloy processors for seawater corrosion resistance. Single-source vulnerability concentrates in dielectric fluid chemist expertise, with formulation knowledge tethered to regional specialists in South Korea and Japan. Distribution runs through factory-integrated rack assemblers compressing on-site commissioning requirements for hyperscale operators in Tuas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center cooling market functions as a stable compounder, with IMDA sustainability mandates and hyperscale AI capacity expansion generating predictable equipment refresh demand across Jurong and Tuas corridors.
For Market Incumbents: Hedge against margin erosion in precision air conditioning by deepening captive supply of liquid cooling manifolds and cold plate assemblies. Secure exclusive partnerships with Singapore-based mechanical contractors holding PUB-certified seawater cooling expertise to lock out competitors from Tuas coastal deployments. Invest in predictive analytics platform development to capture recurring managed services revenue from financial services tenants facing MAS climate risk disclosure deadlines. For New Entrants and Emerging Players: The mid-tier pricing gap between Schneider Electric's EcoStruxure-integrated premium offerings and commodity air handler suppliers presents white-space opportunity for hybrid retrofit kit specialists targeting Jurong colocation facilities. Target colocation operators serving mixed legacy enterprise and emerging GPU-intensive tenants with modular liquid-to-air upgrade systems requiring minimal infrastructure replacement. Pursue go-to-market partnerships with BCA Green Mark consultants to embed thermal optimization services into certification pursuit workflows. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking captive thermal engineering capabilities to compress AI training cluster deployment timelines. The five-to-ten-year viability window favors platform-integrated providers with predictive analytics service arms over standalone component vendors facing supplier ecosystem consolidation. Monitor PUB regulatory amendments on seawater cooling permissions as the critical inflection signal for Tuas corridor expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Integrated Rack Assembly Standardization | Hyperscale operators in Tuas specify pre-tested thermal-fluid packages to minimize on-site integration risk. |
| Predictive Analytics Platform Development | Managed service contracts for thermal optimization capture recurring revenue from BCA Green Mark-seeking colocation facilities. |
| Seawater Cooling Engineering Certification | PUB-compliant closed-loop designs bypass potable water restrictions and command rental rate premiums in Tuas. |
| Dielectric Fluid Formulation Partnership | Exclusive supply agreements with regional chemists lock in critical input access for direct-to-chip liquid cooling systems. |
| Hybrid Retrofit Kit Commercialization | Modular air-liquid upgrade systems enable Jurong colocation operators to serve mixed-density tenant profiles without full infrastructure replacement. |
Research Methodology
Multiple input streams — hyperscale operator capex disclosures, IMDA certification registries, and PUB water use permit records — were reconciled against primary interviews with data center engineering directors, thermal systems procurement managers, and BCA Green Mark assessors. Secondary validation incorporated Building and Construction Authority efficiency benchmarking reports, Infocomm Media Development Authority sustainability standard filings, and regional mechanical contractor licensing databases. Bottom-up equipment shipment tallies and top-down facility capacity buildouts were triangulated to anchor market sizing.
Historical deployment patterns across the analysis window were cross-referenced against panel input from colocation operators and cloud provider infrastructure planners to construct projection scenarios. Segmentation modeling spanned cooling technology type, service delivery mode, end-user scale archetype, and deployment modularity. CAGRs were derived from fitted growth curves calibrated to IMDA mandate implementation timelines and hyperscale AI cluster commissioning schedules. Forecast inputs incorporated PUB regulatory amendment probabilities and titanium alloy price volatility assumptions.
The model assumes a particular technology adoption path; alternative pathways for immersion cooling would alter the outlook if dielectric fluid safety certifications accelerate beyond current trajectories. Forecasts reflect documented assumptions regarding IMDA enforcement consistency and MAS climate risk guideline adoption rates among financial institution tenants. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market