
 Europe CMMS Software Market | 2026-2036
Europe CMMS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe CMMS Software Market Foresight
Direct enterprise sales through systems integrators is rewriting how CMMS vendors reach asset-heavy buyers across Europe. Spacewell leverages its building-management heritage to dominate facility-centric deployments in Northern Europe. MaintainX competes aggressively on mobile-first work order execution, while eMaint CMMS anchors its position through deep maintenance management specialization and extensive partner certification programs.
Computerized maintenance management systems (CMMS) are software platforms that centralize asset registers, schedule preventive maintenance, track work orders, and manage spare parts inventory through digital workflows. Cloud-based deployment leads European adoption as GDPR-compliant sovereign hosting options mature, while on-premise installations retain share among defense and critical infrastructure operators with air-gapped security requirements. The solution dimension shows maintenance management and asset tracking capturing the deepest margin pools, whereas inventory control modules are accelerating fastest as supply chain resilience becomes a board-level priority for manufacturing facilities.
The EU AI Act, GDPR, and CE marking requirements for industrial software collectively shape product roadmaps and procurement criteria across European CMMS vendors. ECHA chemical facility regulations and the EU Green Deal's asset-efficiency mandates further tighten compliance-linked maintenance documentation standards. Stakeholders must monitor how emerging EU cybersecurity certification schemes for critical infrastructure software reshape vendor qualification and deployment architecture decisions.
Market Dynamics
The EU AI Act and GDPR compliance frameworks are forcing CMMS vendors to rearchitect cloud deployments around sovereign data residency, while predictive maintenance modules displace scheduled preventive workflows in German and French manufacturing facilities.
Growth Catalysts
- EU Green Deal asset-efficiency mandates:Industrial facilities in the Benelux region must document energy performance improvements through digitized maintenance records, accelerating CMMS procurement for compliance automation.
- Predictive analytics convergence:Vibration sensors and thermal imaging hardware now feed directly into maintenance platforms, collapsing downtime windows for process manufacturers.
- France:Nuclear power operators and chemical processors face intensified ECHA documentation requirements, driving demand for integrated spare parts traceability modules.
Market Restraints
- GDPR sovereign hosting premiums:Cloud deployments restricted to EU-based data centers carry 15-25% infrastructure cost penalties versus global hyperscale alternatives.
- Defense sector air-gapping:Critical infrastructure operators in Germany and Poland reject SaaS architectures entirely, capping addressable market share for cloud-native vendors.
- Legacy ERP integration debt:SAP-dominated industrial IT stacks impose custom API development costs that extend sales cycles by 8-14 months.
Strategic Opportunities
- Spain and Italy:Food and beverage processing clusters remain underpenetrated relative to Northern Europe, with family-owned mid-caps showing accelerating CMMS trial rates.
- Mobile-first work order execution:Field technician smartphone penetration exceeds 94% across European utilities, enabling displacement of ruggedized handheld hardware.
- CSRD sustainability reporting:Maintenance activity data becomes auditable ESG input, positioning CMMS platforms as mandatory infrastructure for listed industrial enterprises.
Industry Challenges
- OT-IT cybersecurity certification:Emerging EU schemes for critical infrastructure software impose 18-24 month validation timelines that stall procurement decisions.
- Maintenance engineer digital literacy gaps:Veteran technicians at Eastern European steel and mining operations resist mobile interface adoption, requiring parallel paper workflow support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe CMMS Software Market |
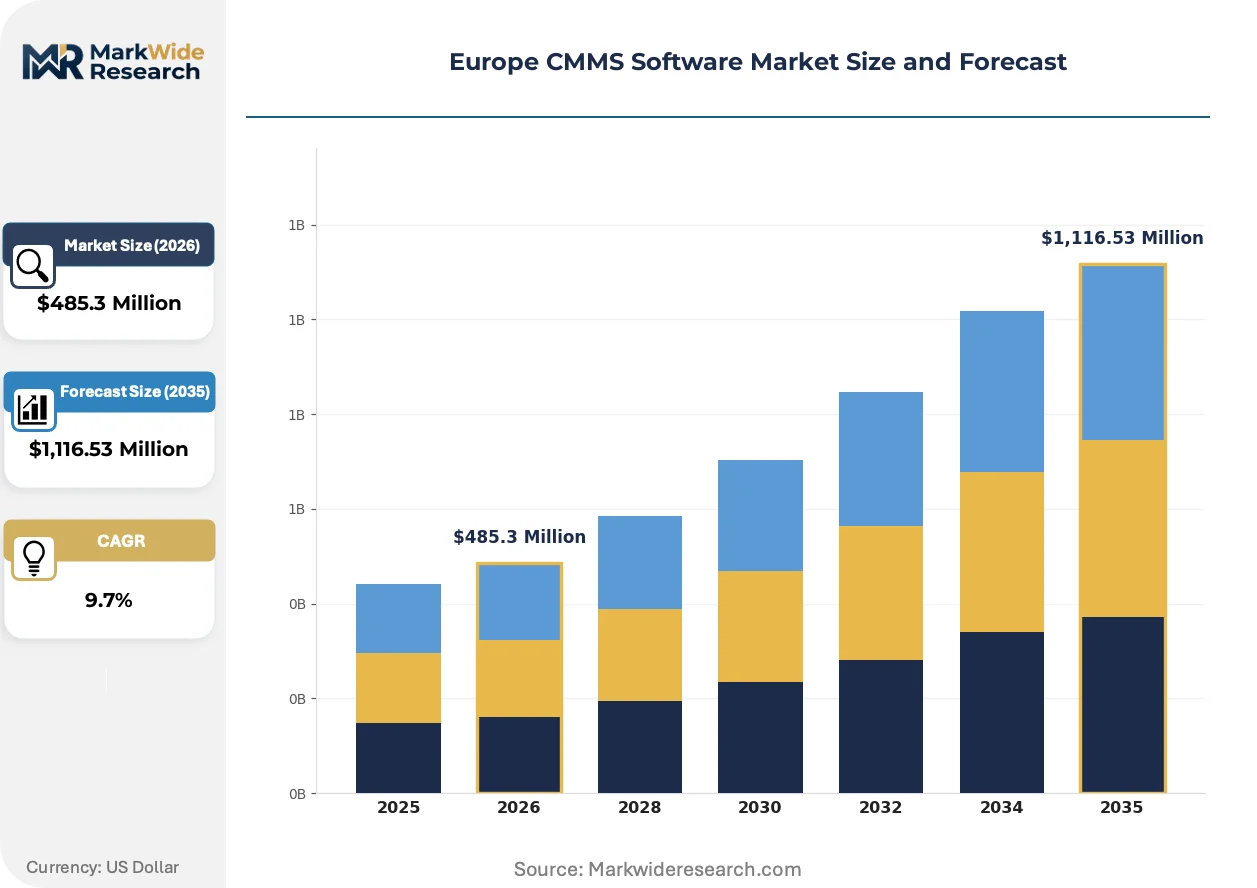
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,116.53 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Manufacturing Facilities, Healthcare Institutions, Educational Organizations, Retail Outlets Solution: Maintenance Management, Asset Tracking, Work Order Management, Inventory Control Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Spacewell, ARC Facilities, MaintainX, Maxpanda Software, ManWinWin Software, Quickbase, Snapfix, Click Maint, eMaint CMMS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe CMMS Software Market Shifts & Advancements
Edge computing architectures and generative AI assistants are collapsing traditional boundaries between condition monitoring, work order generation, and spare parts procurement across European industrial operations.
Digital twin technology is collapsing the distinction between physical asset simulation and live maintenance scheduling. German automotive and aerospace suppliers now deploy physics-based degradation models that synchronize directly with CMMS work order queues. This convergence compresses mean-time-to-repair by pre-positioning technicians and components before failure events trigger alerts.
REACH chemical facility regulations and the EU AI Act collectively mandate explainable maintenance recommendations for high-risk industrial equipment. French and Dutch process manufacturers must now document algorithmic decision trails for regulatory inspectors, forcing vendors to retrofit black-box predictive models with interpretable output layers. This compliance burden advantages established platforms with dedicated compliance engineering teams.
Buyer committees at asset-intensive enterprises now unbundle CMMS procurement from broader ERP refresh cycles. Maintenance directors in Belgium and Germany negotiate standalone SaaS contracts with 12-month pilot terms rather than accepting IT-mandated suite bundles. This fragmentation creates direct vendor relationships that bypass traditional systems integrator channels.
Europe CMMS Software Market Segmentation
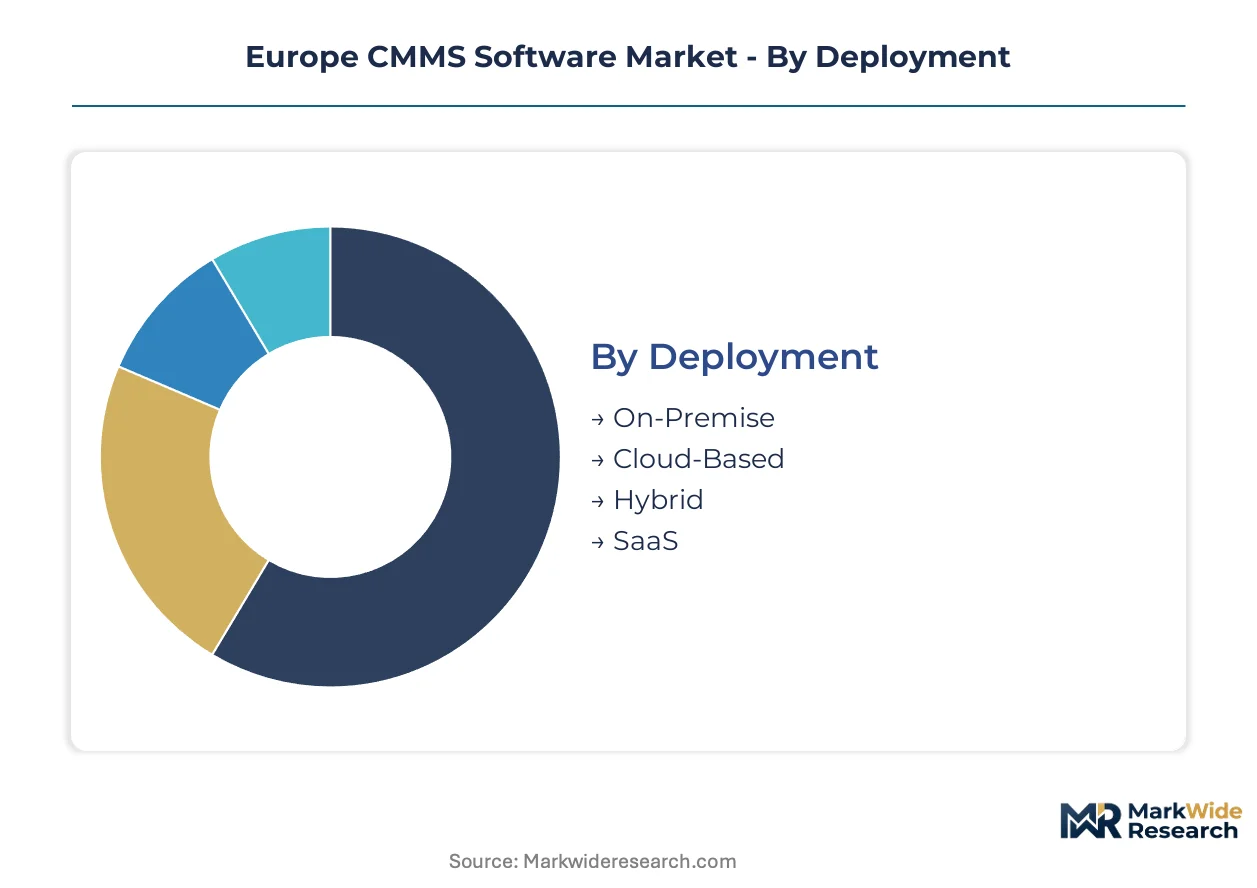
Segmentation across deployment models, end users, solutions, and services reveals divergent margin profiles and compliance requirements across European CMMS procurement. Vendors must architect distinct go-to-market motions for sovereign-hosted cloud deployments versus air-gapped on-premise installations, while solution modules face uneven adoption intensity across asset-heavy verticals.
Deployment:
Mature sovereign hosting options now compete with emerging edge-native architectures across European industrial deployments.
- Cloud-Based:GDPR-compliant EU data residency configurations dominate new procurement in France and Germany. Sovereign hosting premiums of 15-25% over global hyperscale alternatives persist, yet regulatory mandates leave facilities with limited vendor choice. Manufacturing plants in the Benelux region prioritize these deployments for Green Deal documentation automation.
- SaaS:Subscription models with monthly work-order pricing attract mid-cap food processors in Spain and Italy. Mobile-first field technician interfaces drive trial-to-conversion rates above legacy perpetual license alternatives, though defense sector buyers remain inaccessible due to air-gapping requirements.
- On-Premise:Critical infrastructure operators in Poland and Germany mandate offline installations with zero external connectivity.
- Hybrid:Sensitive asset data remains local while spare parts procurement modules sync to cloud marketplaces.
Cloud-Based handles the majority of throughput; SaaS is expanding most quickly on share.
End User:
Cost tier segmentation separates enterprise-scale deployments from mid-cap pilot programs with diverging integration complexity.
- Manufacturing Facilities:German automotive suppliers deploy predictive maintenance modules with vibration sensor integration. ECHA chemical documentation requirements and EU AI Act explainability mandates drive integrated spare parts traceability investments at French and Dutch process plants.
- Healthcare Institutions:Hospital networks in Belgium and the Netherlands prioritize asset uptime for diagnostic imaging equipment. GDPR patient data proximity restrictions force sovereign-hosted CMMS architectures even for non-clinical maintenance workflows.
- Educational Organizations:University campuses across Northern Europe leverage building-management heritage platforms for multi-site facility portfolios.
- Retail Outlets:Franchise-operated convenience store chains in Italy trial mobile-first work order execution for HVAC refrigeration assets.
Manufacturing Facilities commands the deepest maintenance budgets; Healthcare Institutions is gaining share fastest on regulatory compulsion.
Solution:
Application focus varies from mature maintenance scheduling to emerging inventory resilience modules.
- Maintenance Management:Core preventive and predictive scheduling functionality anchors CMMS value propositions. German facilities displace time-based intervals with condition-monitoring triggers, compressing mean-time-to-repair through pre-positioned technician dispatch.
- Inventory Control:Supply chain resilience priorities elevate spare parts procurement modules to board-level visibility. REACH chemical facility regulations mandate lot-level traceability for replacement components at French nuclear and petrochemical operators.
- Asset Tracking:RFID and barcode-enabled register maintenance supports audit readiness for CSRD sustainability reporting.
- Work Order Management:Mobile execution interfaces displace ruggedized handheld hardware as field technician smartphone penetration exceeds 94% across European utilities.
Maintenance Management captures the established revenue base; Inventory Control is climbing the fastest on supply chain risk prioritization.
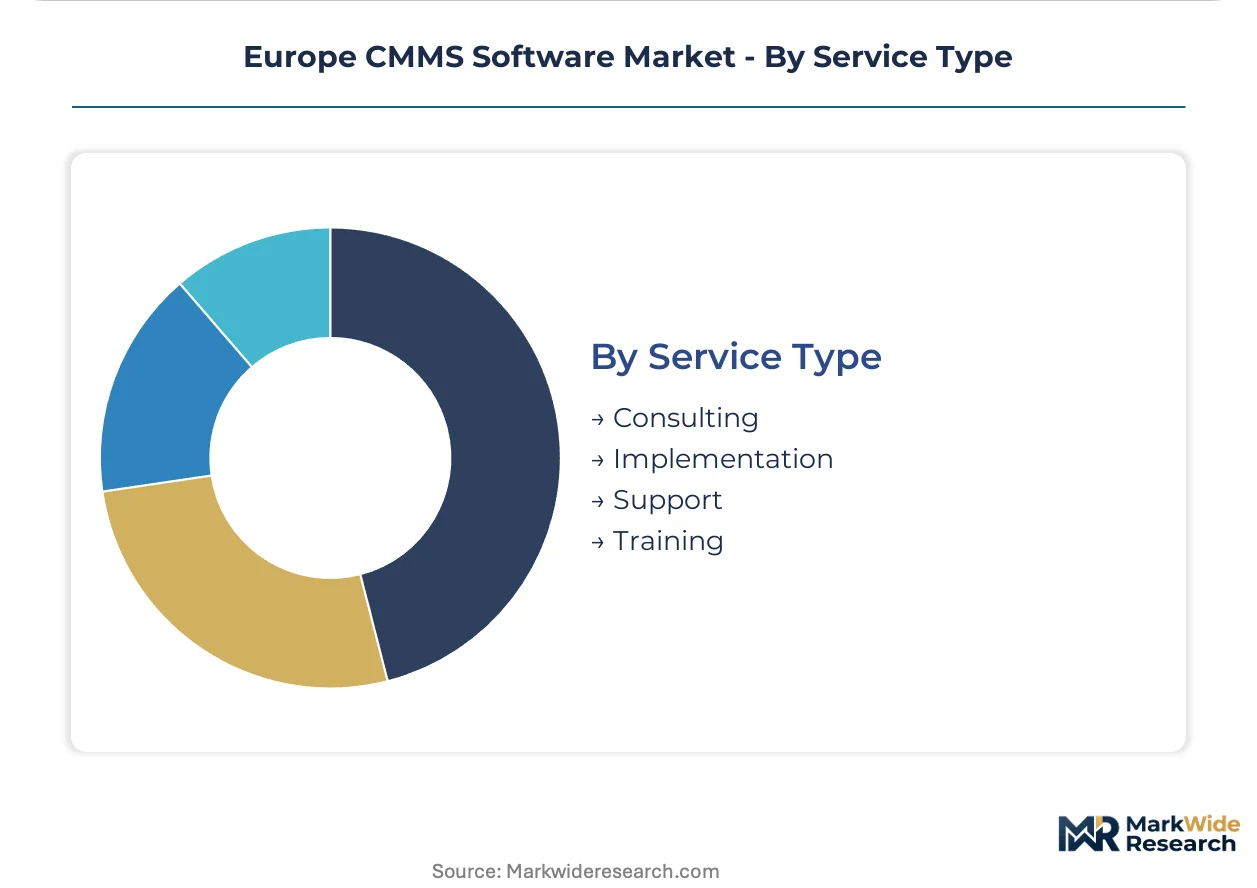
Service Type:
Customer type segmentation separates self-sufficient enterprise IT functions from service-dependent mid-cap buyers.
- Implementation:SAP-dominated industrial IT stacks in Germany impose custom API development extending deployment timelines. Systems integrator partnerships dominate enterprise delivery, while direct vendor relationships accelerate mid-cap pilot-to-production transitions.
- Support:24/7 critical asset coverage commands premium pricing at nuclear and chemical facilities in France. Eastern European steel and mining operations require parallel paper workflow support during digital literacy transition periods.
- Consulting:Change management services assist maintenance director-led procurement committees unbundling CMMS from ERP refresh cycles.
- Training:Mobile interface certification programs address veteran technician resistance in Polish and Romanian industrial clusters.
Implementation absorbs the largest service expenditure; Support is the fastest mover on critical infrastructure uptime requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor and its connecting industrial corridors anchor Europe's CMMS software demand, linking manufacturing clusters across Germany, France, and the Benelux region through dense logistics and energy infrastructure networks.
Germany
Automotive suppliers in Stuttgart and Wolfsburg deploy predictive maintenance modules with vibration sensor integration. The EU AI Act and GDPR sovereign hosting requirements force rearchitecting of cloud deployments around domestic data centers. Chemical processors in Ludwigshafen face intensified ECHA documentation mandates, driving integrated spare parts traceability investments.
France
Nuclear power operators at Flamanville and chemical processors in Lyon demand explainable maintenance recommendations under EU AI Act high-risk equipment rules. ECHA REACH regulations mandate lot-level traceability for replacement components. The Paris-Saclay research cluster incubates physics-based degradation models that synchronize with CMMS work order queues.
Belgium and Netherlands
Process industries in the Port of Antwerp and Rotterdam chemical clusters must document energy performance improvements through digitized maintenance records under EU Green Deal mandates. GDPR patient data proximity restrictions force sovereign-hosted CMMS architectures even for non-clinical maintenance workflows at Leuven and Utrecht hospital networks.
Spain
Food and beverage processing clusters in Barcelona and Valencia remain underpenetrated relative to Northern Europe, with family-owned mid-caps showing accelerating CMMS trial rates. Mobile-first work order execution attracts subscription models with monthly pricing. The Spanish national cybersecurity framework imposes certification timelines that extend procurement decisions.
Poland
Critical infrastructure operators in the Silesian mining basin and Warsaw defense sector mandate offline installations with zero external connectivity. Veteran technicians at Katowice steel operations resist mobile interface adoption, requiring parallel paper workflow support. OT-IT cybersecurity certification schemes impose validation timelines that stall procurement decisions.
Europe CMMS Software Market Competitive Landscape
On the supply side, the industry is consolidating around specialized maintenance platforms and building-management heritage systems with divergent geographic footprints. Established vendors anchor positions through deep ERP integration partnerships, while cloud-native entrants compete on mobile-first field execution. Three strategic archetypes dominate: facility-centric building management platforms, asset-heavy industrial specialists, and mid-market SaaS disruptors. Competitive moves center on systems integrator channel partnerships and sovereign hosting infrastructure investments.
Within the building-management heritage tier, Spacewell leverages its Northern European facility portfolio dominance. Among mobile-first disruptors, MaintainX exemplifies the aggressive field-execution positioning that displaces ruggedized hardware. At the maintenance-specialist anchor, eMaint CMMS occupies a position defined by deep work order management specialization and extensive partner certification programs.
| Leading Market Players |
|---|
| Spacewell |
| ARC Facilities |
| MaintainX |
| Maxpanda Software |
| ManWinWin Software |
| Quickbase |
| Snapfix |
| Click Maint |
| eMaint CMMS |
| Others |
Supply & Pricing Matrix
The Rhine-Main-Danube waterway corridor channels logistics costs through Central European industrial clusters, concentrating supply-side leverage among German and Dutch systems integrators while forcing price stratification between sovereign-hosted cloud deployments and air-gapped on-premise alternatives. GDPR-compliant data residency requirements impose infrastructure premiums that vendors pass downstream, creating tiered cost structures aligned with compliance intensity rather than pure feature differentiation.
Pricing Analysis
Volume-discount tiering structures dominate European CMMS procurement, with enterprise-scale manufacturing facilities in Germany and the Benelux capturing 20-30% unit economics advantages over mid-cap food processors in Southern Europe. Price differentiation hinges on GDPR certification grade and integration complexity with SAP-dominated ERP stacks. Pricing pressure stems from hyperscale cloud providers entering the sovereign hosting space, compressing margins for specialized vendors. Mid-cap buyers in Spain and Italy exhibit highest price sensitivity, while French nuclear operators prioritize uptime guarantees over cost optimization.
Supply Chain Analysis
Upstream feedstock for CMMS platforms draws from cloud infrastructure providers concentrated in Germany, Ireland, and the Netherlands, with edge computing hardware sourcing from Taiwan and South Korean sensor manufacturers. Software development labor pools center on Poland and Romania, while systems integrator partnerships anchor distribution through established industrial IT channels. Single-source vulnerability persists in EU-certified sovereign hosting capacity, where limited domestic data center operators create procurement bottlenecks. Distribution runs through direct enterprise sales teams and certified systems integrator networks, bypassing traditional value-added reseller channels for asset-heavy verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe CMMS software market sits in a cyclical recovery phase, with capital expenditure rebounds at German automotive suppliers and Benelux process manufacturers driving replacement demand for legacy maintenance management systems.
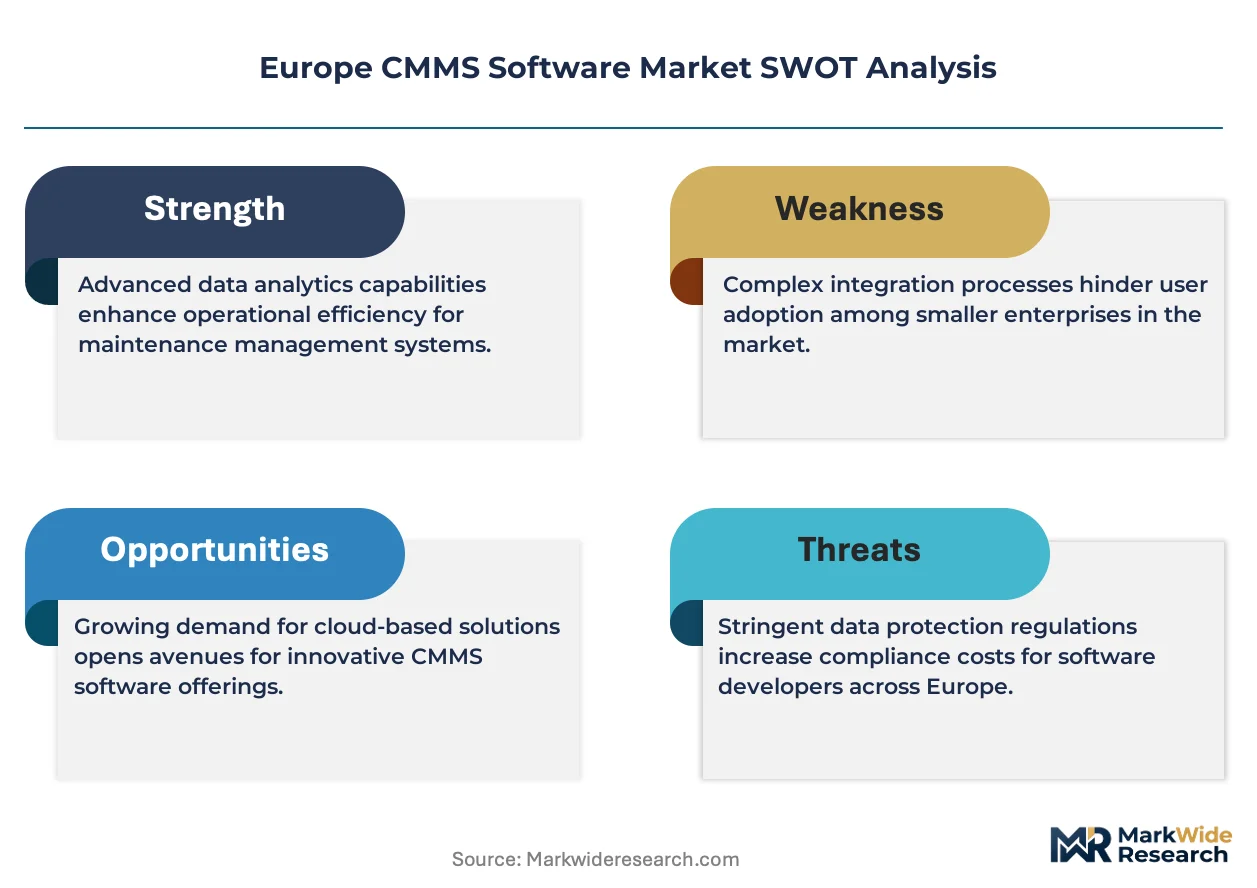
For Market Incumbents: Insulate core maintenance management revenue by deepening ERP integration partnerships with SAP and Oracle, while accelerating sovereign hosting infrastructure investments to neutralize hyperscale cloud entrants. The threat of mobile-first disruptors like MaintainX capturing field technician mindshare demands preemptive UX modernization. Certification engineering teams must expand to address emerging EU cybersecurity schemes for critical infrastructure software. For New Entrants and Emerging Players: Pursue white-space penetration in Spain and Italy's food and beverage processing clusters, where family-owned mid-caps show accelerating trial rates but remain underserved by Northern European vendor footprints. Mobile-first work order execution with monthly subscription pricing offers the most penetrable entry angle, displacing ruggedized handheld hardware as field technician smartphone penetration exceeds 94% across European utilities. For Investors and Strategic Acquirers: Narrow vertical specialists with deep ECHA compliance engineering capabilities represent the most defensible acquisition targets, given REACH chemical facility regulations and EU AI Act explainability mandates that favor established platforms. Long-term viability hinges on positioning within CSRD sustainability reporting workflows, where maintenance activity data becomes auditable ESG input. Watch for inflection signals in Spanish and Italian mid-cap trial-to-conversion rates as indicators of Southern European market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Expansion | GDPR-compliant EU data center investments neutralize hyperscale competition for defense and healthcare buyers. |
| Mobile-First Platform Modernization | Smartphone-native work order execution displaces ruggedized hardware across 94% field technician penetration. |
| Predictive Maintenance Module Development | Vibration sensor integration at German automotive suppliers compresses mean-time-to-repair through pre-positioned dispatch. |
| Systems Integrator Certification Programs | Deep SAP integration partnerships extend sales cycles but lock out mobile-native competitors from enterprise accounts. |
| ECHA Compliance Engineering Investment | REACH chemical facility traceability mandates create regulatory moats for platforms with dedicated compliance teams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs data, and hyperscaler capex disclosures, combining structured interviews with maintenance directors, plant engineers, IT procurement officers, and systems integrator partners across German, French, Benelux, Spanish, and Polish industrial clusters. Secondary validation draws from ECHA chemical facility registries, EU AI Act implementation guidance, CSRD sustainability reporting frameworks, and SEC filings of publicly traded industrial software vendors. Bottom-up demand modeling triangulates against top-down market sizing from deployment mode and vertical adoption patterns.
Forecast inputs include deployment model migration curves, vertical-specific compliance deadline clustering, and mobile-first adoption rates across field technician populations. Segmentation dimensions span deployment architecture, organization scale, asset intensity vertical, integration complexity with legacy ERP systems, and regional regulatory enforcement patterns. CAGRs derive from logistic diffusion modeling of predictive maintenance module penetration and inventory control module acceleration, with cross-checks against capital expenditure intentions from automotive and process manufacturing survey panels.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, interest rate environments affecting capital expenditure cycles, or EU cybersecurity certification timeline delays would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and sovereign hosting capacity expansion. Cross-checking against industrial software M&A transaction benchmarks and peer valuation multiples is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global API Management Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Digital Sculpture Software Market
Software & Services
Email Applications Market
Software & Services
Avionics Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Global Political Campaign Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Global Enterprise Architecture Tools Market
Software & Services
Europe Business Software Market
Software & Services
HACCP Software Market
Software & Services
Sports League Management Software Market
Software & Services
3PL Software Market
Software & Services
PAC Programming Software Market
Software & Services
Global Automotive Software Market
Software & Services
School Timetable Software Market