
 Europe Cloud CRM Market | 2026-2036
Europe Cloud CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cloud CRM Market Analysis
Subscription-based financing and asset-light deployment models are narrowing the competitive field for mid-market CRM access in Europe. SAP leverages its deep ERP integration to anchor enterprise accounts across German manufacturing corridors. Salesforce competes through verticalized cloud architecture purpose-built for regulated European industries. Odoo specializes in modular, open-source pricing that extends its reach among cost-conscious SMEs in Benelux and Southern Europe.
Europe Cloud CRM comprises software delivered via internet-hosted infrastructure for customer relationship management, typically operating through multi-tenant architectures with API connectivity to enterprise resource planning and data warehouse systems. The technology automates sales pipelines, service ticketing, and marketing orchestration while centralizing customer interaction records for commercial decision-making. Public cloud deployments dominate volume across the continent, though hybrid cloud configurations command stronger margin pools as financial services and healthcare buyers demand sovereign data residency. Among industry verticals, financial services generates the most complex implementation requirements, while retail shows the fastest uptake of real-time personalization engines. Small enterprises represent the largest addressable user base by count, yet large enterprises drive the majority of annual contract value through multi-module solution offerings spanning sales automation and analytics.
GDPR enforcement by national data protection authorities and the EU AI Act's risk-classification framework shape product roadmaps, forcing vendors to engineer granular consent management and algorithmic transparency into customer-facing automation. EMA guidelines on pharmacovigilance and the CSRD's sustainability reporting mandates create additional compliance layers for CRM deployments in healthcare and industrial sectors. Stakeholders must weigh sovereignty requirements against interoperability gains as member states advance divergent cloud certification schemes.
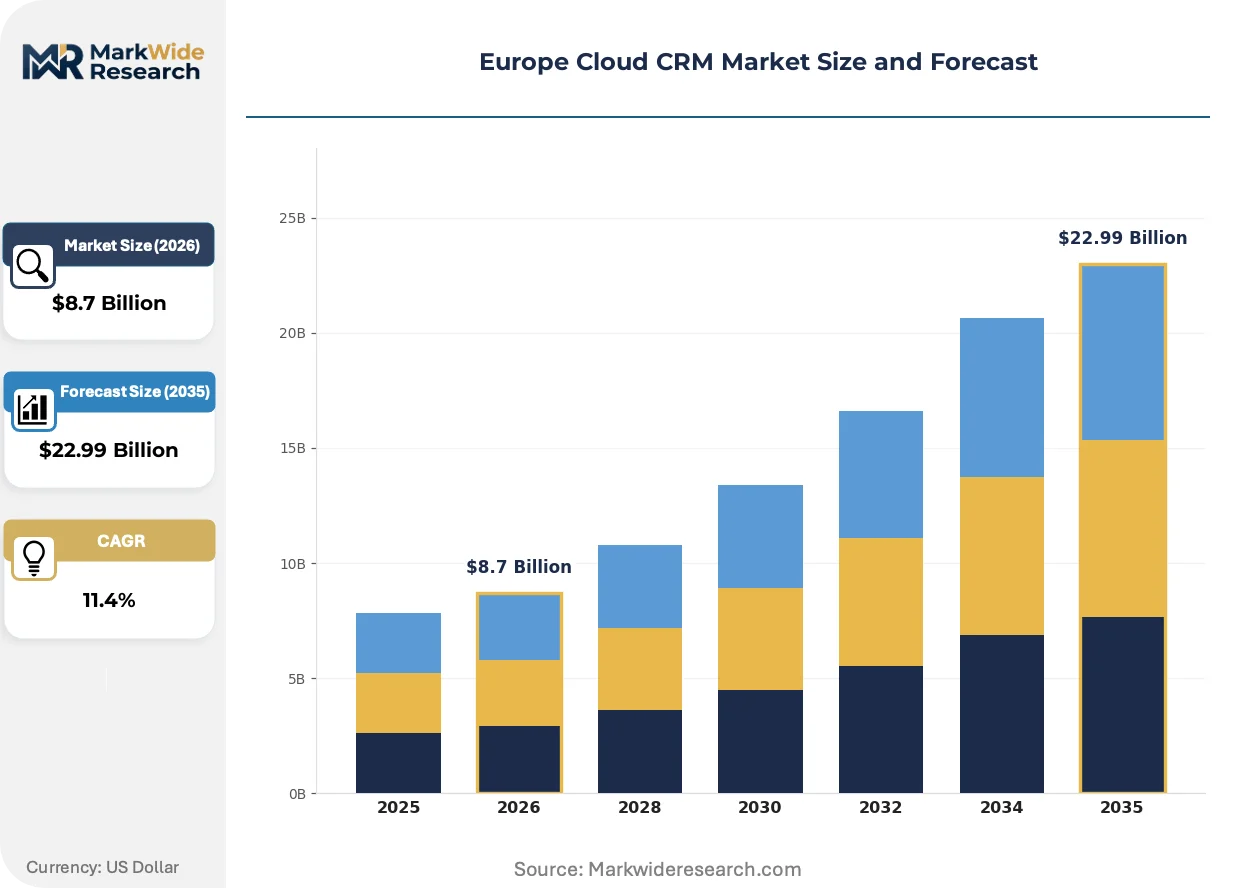
Market Dynamics
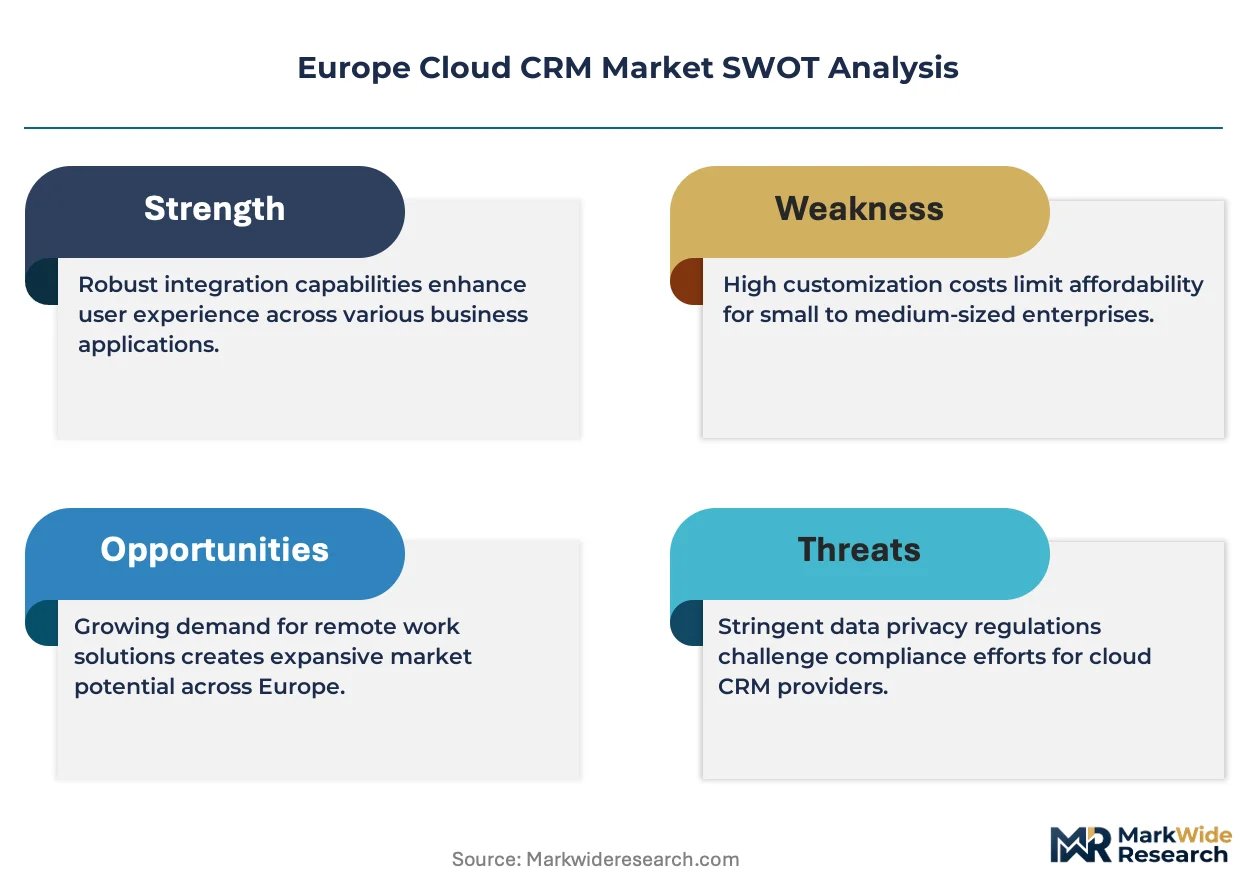
The EU AI Act's risk-classification framework is forcing CRM vendors to engineer explainable automation into customer-facing workflows, while GDPR enforcement by national data protection authorities demands granular consent management. This dual regulatory pressure is compressing product development cycles and raising compliance costs across the European vendor landscape.
Growth Catalysts
- EMA pharmacovigilance guidelines:Healthcare CRM deployments must integrate adverse event reporting workflows, expanding specialized module demand across pharmaceutical sales organizations in Germany and Switzerland.
- Real-time personalization engines:French luxury houses deploy predictive clienteling platforms that unify online and boutique customer data, driving premium-tier subscription upgrades.
- German automotive supplier consolidation:Tier-1 manufacturers standardize dealer network management through SaaS CRM subscriptions, replacing fragmented legacy DMS installations.
Market Restraints
- CSRD sustainability reporting mandates:Industrial buyers face additional compliance layers that extend CRM procurement cycles and inflate implementation consulting costs.
- Sovereign data residency requirements:Financial services and healthcare buyers in France and Germany demand hybrid cloud configurations, limiting pure public cloud margin expansion.
- API standardization gaps:ERP integration complexity with legacy SAP on-premise installations creates technical friction that slows mid-market migration timelines.
Strategic Opportunities
- Benelux SME penetration:Modular open-source pricing models address cost-conscious buyers in Belgium and the Netherlands currently underserved by enterprise-focused vendors.
- EU Green Deal procurement criteria:Public sector tenders increasingly require carbon footprint disclosures in vendor selection, favoring cloud-native CRM providers with verified sustainability credentials.
- Edge-to-cloud synchronization:Convergence of 5G low-latency networks with containerized CRM microservices enables real-time field sales automation for distributed industrial workforces.
Industry Challenges
- Algorithmic audit expertise scarcity:Vendors struggle to recruit data scientists capable of documenting automated decision logic for EU AI Act high-risk system classifications.
- Legacy mainframe integration:Italian and Spanish banks face multi-year re-platforming projects to connect cloud CRM layers with core banking systems running on decades-old infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cloud CRM Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Industry Vertical: Financial Services, Healthcare, Retail, Technology End User: Small Enterprises, Medium Enterprises, Large Enterprises, Nonprofits Solution Offering: Sales Automation, Marketing Automation, Customer Support, Analytics |
| Companies Covered | SAP, Zoho Corporation, Salesforce, Odoo, HubSpot, Microsoft, Zendesk, Pipedrive, Oracle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cloud CRM Market Emerging Trajectories
European CRM architecture is pivoting toward composable, API-first designs that decouple data layers from workflow engines. This structural shift enables faster regulatory adaptation and supports the modular procurement patterns emerging among mid-market buyers.
Low-code workflow builders are virtualizing traditional CRM customization. These platforms allow business users to configure sales automation without vendor professional services. Mid-market enterprises in the Netherlands and Denmark adopt these tools aggressively to compress implementation timelines from quarters to weeks. The technology is virtualizing the systems integration layer that previously anchored vendor lock-in.
The EU AI Act's transparency mandates reshape product roadmaps. Vendors must now embed explainability interfaces that surface algorithmic logic to end-users. Healthcare and financial services deployments face the steepest compliance curves, with French and German buyers demanding audit trails for automated lead scoring and next-best-action recommendations.
Subscription fatigue among enterprise buyers is fragmenting procurement authority. Chief revenue officers now negotiate CRM contracts directly with vertical specialists rather than routing through centralized IT procurement. This pattern concentrates in Germany's manufacturing Mittelstand, where plant-level managers select field service modules independent of headquarters sales automation decisions.
Europe Cloud CRM Market Segmentation
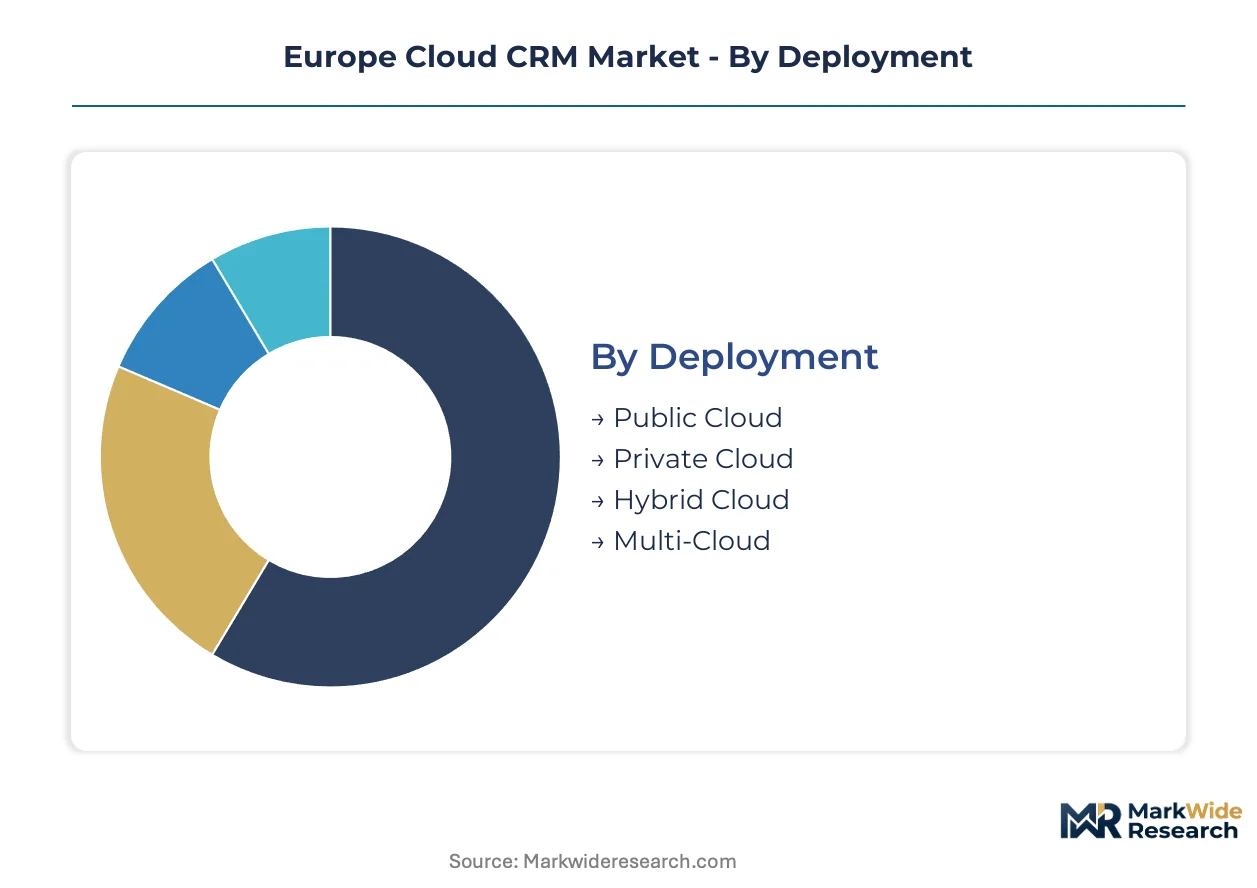
European Cloud CRM buyers segment sharply by sovereignty requirements and integration complexity. Deployment architecture and enterprise scale determine pricing elasticity, while industry verticals dictate compliance module specifications.
Deployment:
Cost tier separates volume buyers from margin-rich configurations demanding data residency guarantees.
- Public Cloud:Multi-tenant infrastructure delivers standardized sales automation and marketing orchestration through shared hosting environments. German automotive suppliers and Benelux SMEs concentrate demand here, driven by subscription economics and rapid provisioning timelines without capital expenditure.
- Hybrid Cloud:Split architectures maintain sensitive customer records on-premises while pushing analytics workloads to sovereign cloud regions. French financial services and German healthcare buyers mandate this configuration under GDPR and national banking regulator requirements, accepting premium pricing for jurisdictional control.
- Private Cloud:Single-tenant deployments serve defense contractors and critical infrastructure operators requiring air-gapped environments.
- Multi-Cloud:Distributed workloads across AWS, Azure, and Google Cloud regions reduce vendor concentration risk for multinational enterprises.
Public Cloud commands the established base. The steepest expansion runs through Hybrid Cloud.
Industry Vertical:
Application-specific compliance layers reshape module requirements and sales cycle duration.
- Financial Services:Core banking integration, MiFID II transaction reporting, and EBA guidelines on outsourcing demand encrypted data pipelines with audit-grade logging. German and French institutions lead procurement of these specialized configurations.
- Healthcare:EMA pharmacovigilance mandates and GDPR health data classifications require adverse event tracking workflows and granular consent management. Swiss pharmaceutical sales organizations and German hospital networks drive specialized module adoption.
- Retail:Real-time personalization engines unify e-commerce and boutique customer data for French luxury houses.
- Technology:API-first architectures and developer-centric customization tools attract software vendors in the Netherlands and Ireland.
Financial Services commands the established base. The steepest expansion runs through Healthcare.
End User:
Customer type determines contract value concentration versus addressable market breadth.
- Large Enterprises:Multi-module deployments spanning sales automation, service ticketing, and predictive analytics generate the majority of annual contract value. German manufacturing conglomerates and French banking groups negotiate enterprise-wide master agreements with SAP and Salesforce.
- Small Enterprises:Modular, pay-per-user subscriptions from Odoo and HubSpot capture the largest user count across Southern Europe and Benelux, constrained by limited IT staffing and integration budgets.
- Medium Enterprises:Mid-market buyers in Denmark and the Netherlands adopt low-code configuration tools to compress implementation timelines.
- Nonprofits:Discounted licensing programs from major vendors address donor management and volunteer coordination needs.
Large Enterprises commands the established base. Small Enterprises gains share fastest.
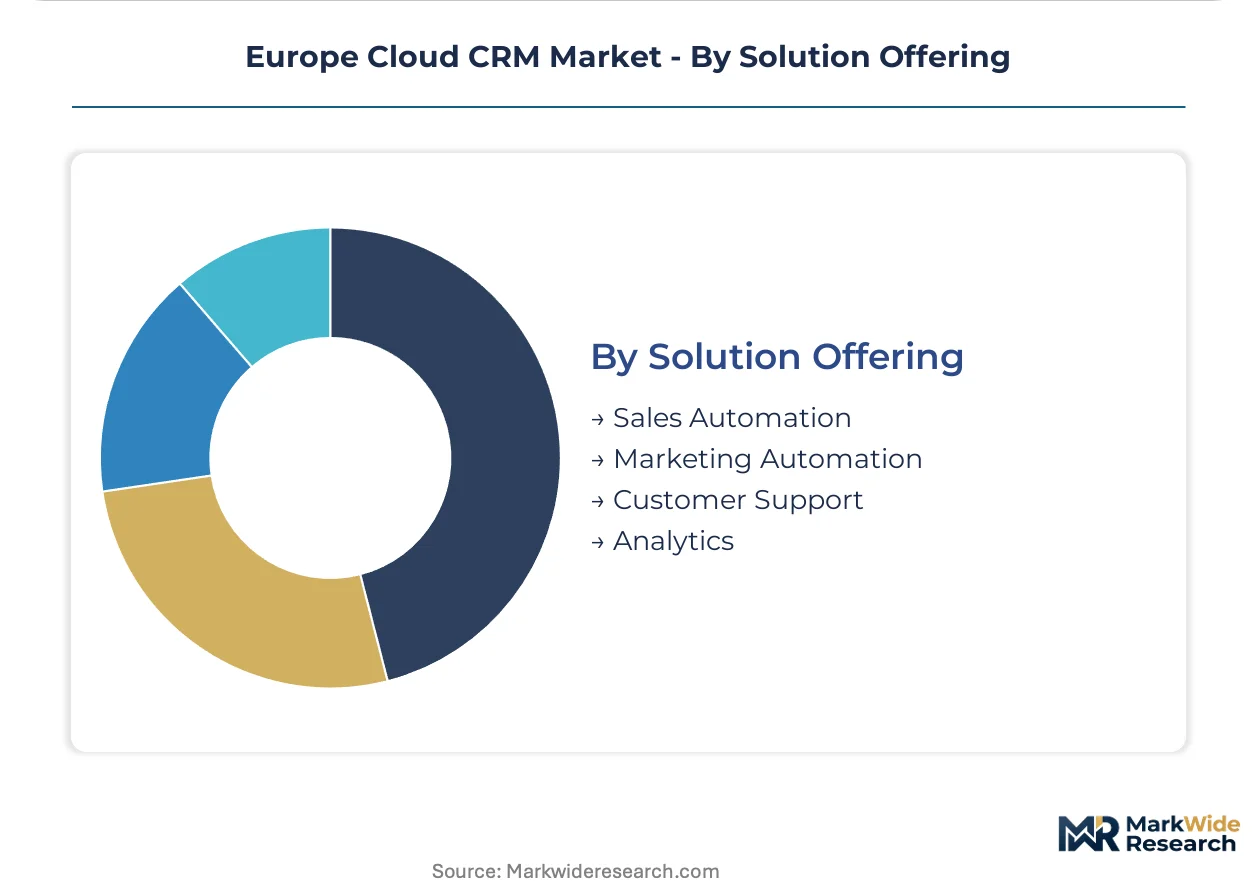
Solution Offering:
Maturity levels vary sharply across functional modules, with adjacent categories converging through AI augmentation.
- Sales Automation:Pipeline management, forecasting algorithms, and mobile field access constitute the most penetrated category. German automotive supplier networks standardize on these tools for dealer coordination.
- Analytics:Predictive scoring and next-best-action engines face the steepest compliance curves under EU AI Act transparency mandates. French luxury retailers and healthcare providers invest here despite audit complexity.
- Marketing Automation:Campaign orchestration and lead nurturing workflows integrate with e-commerce platforms across retail verticals.
- Customer Support:Omnichannel ticketing and knowledge management serve as entry modules for cost-conscious buyers.
Sales Automation commands the established base. Analytics climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe runs a net services surplus in enterprise software, with Cloud CRM exports concentrated from German engineering hubs and French luxury technology platforms offsetting import demand for US-originated cloud infrastructure. Trade flows reflect regulatory arbitrage, as EU data residency requirements redirect procurement toward regional vendors capable of sovereign hosting configurations.
Germany
Automotive supplier networks and industrial Mittelstand firms drive hybrid cloud CRM procurement for dealer management and field service coordination. The KBA and BSI enforce strict data localization for connected vehicle customer data, pushing tier-1 manufacturers toward on-premise edge deployments. Stuttgart and Munich anchor this demand, with Bosch and Siemens Energy standardizing sales automation across supplier ecosystems.
France
French luxury houses deploy predictive clienteling platforms that unify e-commerce and boutique customer data for personalized concierge services. The CNIL enforces granular consent management under GDPR Article 7, complicating real-time personalization engine deployments. Paris and Lyon concentrate this activity, with LVMH and Kering subsidiaries pioneering AI-augmented customer relationship workflows.
United Kingdom
London financial services firms procure specialized CRM modules for MiFID II transaction reporting and EBA outsourcing guidelines compliance. The FCA and Prudential Regulation Authority mandate encrypted data pipelines with audit-grade logging for cloud-based customer systems. The City of London and Canary Wharf clusters dominate, with multinational banks re-platforming legacy mainframe integrations.
Netherlands
Dutch mid-market enterprises adopt low-code CRM configuration tools to compress implementation timelines without vendor professional services dependency. The Dutch Data Protection Authority enforces strict cross-border transfer mechanisms under GDPR Schrems II rulings. Amsterdam and Eindhoven serve as adoption centers, with ASML suppliers and agritech exporters driving modular procurement patterns.
Switzerland
Swiss pharmaceutical sales organizations integrate EMA pharmacovigilance adverse event reporting into specialized healthcare CRM deployments. Swissmedic mandates granular health data classifications that exceed baseline GDPR requirements for customer-facing automation. Basel and Zurich anchor this demand, with Roche and Novartis field forces standardizing on compliant cloud configurations.
Europe Cloud CRM Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in API connectivity and vertical workflow modules. The European vendor base stratifies between ERP-anchored enterprise suites and modular SaaS point solutions, with mid-market buyers fragmenting procurement authority across departmental budgets. Three archetypes dominate: legacy system modernizers bridging on-premise SAP installations, cloud-native vertical specialists, and open-source modular platforms. Competitive intensity concentrates on hybrid deployment expertise and regulatory compliance engineering rather than raw feature expansion.
Within the ERP-anchored tier, SAP represents the legacy modernizer archetype with deep manufacturing corridor penetration. Salesforce exemplifies the cloud-native vertical specialist position, while Odoo occupies the open-source modular platform segment for cost-conscious SME procurement. These three anchors illustrate the competitive fault lines: integration depth versus deployment velocity versus pricing flexibility.
| Leading Market Players |
|---|
| SAP |
| Zoho Corporation |
| Salesforce |
| Odoo |
| HubSpot |
| Microsoft |
| Zendesk |
| Pipedrive |
| Oracle |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's congestion-driven cost spikes concentrate margin pressure on cloud CRM vendors serving German automotive suppliers, compressing delivery economics for hybrid hardware-software bundles while amplifying price differentiation between sovereign-hosted and standard public cloud tiers.
Pricing Analysis
Industrial OEM buyers anchor subscription pricing structures across the European Cloud CRM landscape. Three-tier pricing stratifies across premium sovereign-cloud configurations, standard multi-tenant SaaS, and economy modular deployments. Certification under the EU AI Act's high-risk system classification commands substantial premiums over baseline GDPR-compliant tiers. Cost compression in the economy tier intensifies because Odoo and HubSpot compete aggressively for Benelux SME accounts. Small enterprises exhibit the sharpest price sensitivity, while French financial services buyers accept premium positioning for hybrid residency guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for European CRM vendors dependent on server hardware and semiconductor components. Taiwan, South Korea, and Ireland concentrate manufacturing of the GPUs and specialized accelerators powering AI-augmented CRM analytics. German and Dutch data center operators draw from these supply pools for sovereign cloud infrastructure buildouts. Single-source vulnerability in advanced chip packaging creates procurement bottlenecks that extend hardware refresh cycles. Distribution runs through hyperscaler partner networks and direct enterprise sales teams with embedded implementation consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European Cloud CRM market sits at a platform-economics inflection where API-first composability and cross-vendor data interoperability are displacing monolithic suite dominance, with the EU AI Act's transparency mandates accelerating this architectural shift.
For Market Incumbents: Pre-empt modular disaggregation by embedding explainable AI interfaces directly into core workflow engines before specialized compliance vendors capture high-risk system segments. SAP and Salesforce must accelerate sovereign cloud certification across German BSI and French ANSSI frameworks to defend against emerging regional hosting specialists. Vertical integration into edge-to-cloud synchronization capabilities represents the critical capacity lever for field service automation dominance.
For New Entrants and Emerging Players: Southern European mid-market manufacturers currently underserved by enterprise-focused vendors offer the most penetrable white-space target for modular, low-code CRM platforms with native GDPR consent management. Portugal and Spain's industrial corridors lack localized vendor presence despite accelerating digital procurement mandates. A channel partnership strategy with regional systems integrators accelerates market access without direct sales infrastructure.
For Investors and Strategic Acquirers: Cloud-native vertical specialists with pre-built EU AI Act compliance modules and established French or German regulatory relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on defensible data residency positioning as sovereign requirements proliferate across member states. Watch for inflection signals in national cloud certification scheme harmonization discussions that would consolidate vendor qualification barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BSI and ANSSI approvals unlock German and French financial services procurement pipelines. |
| API-First Platform Integration | Composable architecture accelerates EMA pharmacovigilance workflow deployment for pharmaceutical sales. |
| Acquisition of Compliance Specialist | EU AI Act audit expertise scarcity makes algorithmic transparency vendors strategic targets. |
| Strategic Partnership with Hyperscaler | AWS, Azure, or Google Cloud co-selling agreements expand reach into Benelux mid-market accounts. |
| Geographic Expansion to Southern Europe | Portugal and Spain's manufacturing corridors lack localized CRM vendor presence despite accelerating demand. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with CRM product executives, data protection officers at German automotive suppliers, French luxury house IT directors, and Benelux SME procurement leads informed deployment architecture preferences and pricing elasticity assessments. Secondary sources include EMA pharmacovigilance guidance documents, CNIL GDPR enforcement decisions, EU AI Act implementation drafts, and hyperscaler regional infrastructure investment disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from enterprise software trade flows.
Calibration against historical adoption curves in regulated European software markets shapes the projection framework across the analysis window. Segmentation dimensions include deployment architecture, organization size tier, industry vertical, integration complexity level, and national regulatory cluster. CAGRs derive from fitted growth curves adjusted for compliance-driven procurement delays and sovereign cloud infrastructure buildout timelines. Forecast inputs incorporate EU Green Deal procurement criteria adoption rates and 5G network coverage expansion for edge-to-cloud synchronization enablement.
The forecast holds incumbent behavior within observed patterns; aggressive platform unbundling moves by ERP-anchored vendors or rapid hyperscaler vertical specialization would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market