
 South East Asia CRM Market | 2026-2036
South East Asia CRM Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia CRM Market Outlook
Market Context
Banking and financial services is decoupling from retail as the dominant CRM buyer vertical across South East Asia. Salesforce sustains technology leadership through its Einstein AI layer and multi-cloud architecture tailored for regulated industries. Oracle Corporation anchors enterprise-grade deployments with deep database integration and vertical-specific compliance modules. Zoho Corporation competes aggressively on price-performance for mid-market ASEAN firms seeking localized support and multi-currency operations.
Technical Definition and Segment Structure
Customer relationship management software comprises integrated platforms that orchestrate sales pipelines, marketing campaigns, service interactions, and behavioral analytics through centralized customer data repositories, API-connected touchpoints, and workflow automation engines. Cloud-based deployment leads solution uptake as telecommunications infrastructure improves and total cost of ownership advantages compound for distributed workforces. Sales automation captures the largest solution segment by revenue commitment, while analytics grows fastest as predictive models penetrate credit scoring and churn prevention in financial services. Among end users, SMEs represent the fastest-expanding category as subscription pricing and modular onboarding reduce entry barriers previously reserved for large enterprises with dedicated IT functions.
Regulatory Environment and Outlook
Indonesia's Ministry of Communication and Informatics enforces data localization through Government Regulation Number 71 of 2019, compelling CRM vendors to establish domestic data centers or partner with local cloud operators. Thailand's Personal Data Protection Act and Vietnam's Cybersecurity Law impose cross-border transfer restrictions that reshape vendor architecture decisions and compliance roadmaps. Singapore's Monetary Authority issues technology risk management guidelines that elevate audit and encryption standards for financial services CRM deployments. Stakeholders must monitor evolving data residency enforcement across ASEAN member states to determine whether federated infrastructure investments or regional hub strategies better align with compliance cost trajectories.
Market Dynamics
Cloud migration mandates from Indonesia's Ministry of Communication and Informatics are forcing wholesale replacement of legacy on-premises CRM installations across ASEAN financial services, compressing vendor deployment timelines and reshaping data center investment patterns.
Growth Catalysts
- Indonesia's GR 71/2019 Data Localization:The regulation compels CRM vendors to establish domestic infrastructure, accelerating partnership formations with local cloud operators and expanding addressable market for compliant solutions.
- Fintech Proliferation:Digital lending platforms and neobanks across Jakarta, Bangkok, and Ho Chi Minh City require real-time customer journey orchestration, driving subscription volume for sales automation modules.
- Telecommunications Infrastructure Modernization:5G rollout and submarine cable investments across the ASEAN region reduce latency barriers, enabling cloud-native CRM adoption by distributed workforces previously constrained by connectivity gaps.
Market Restraints
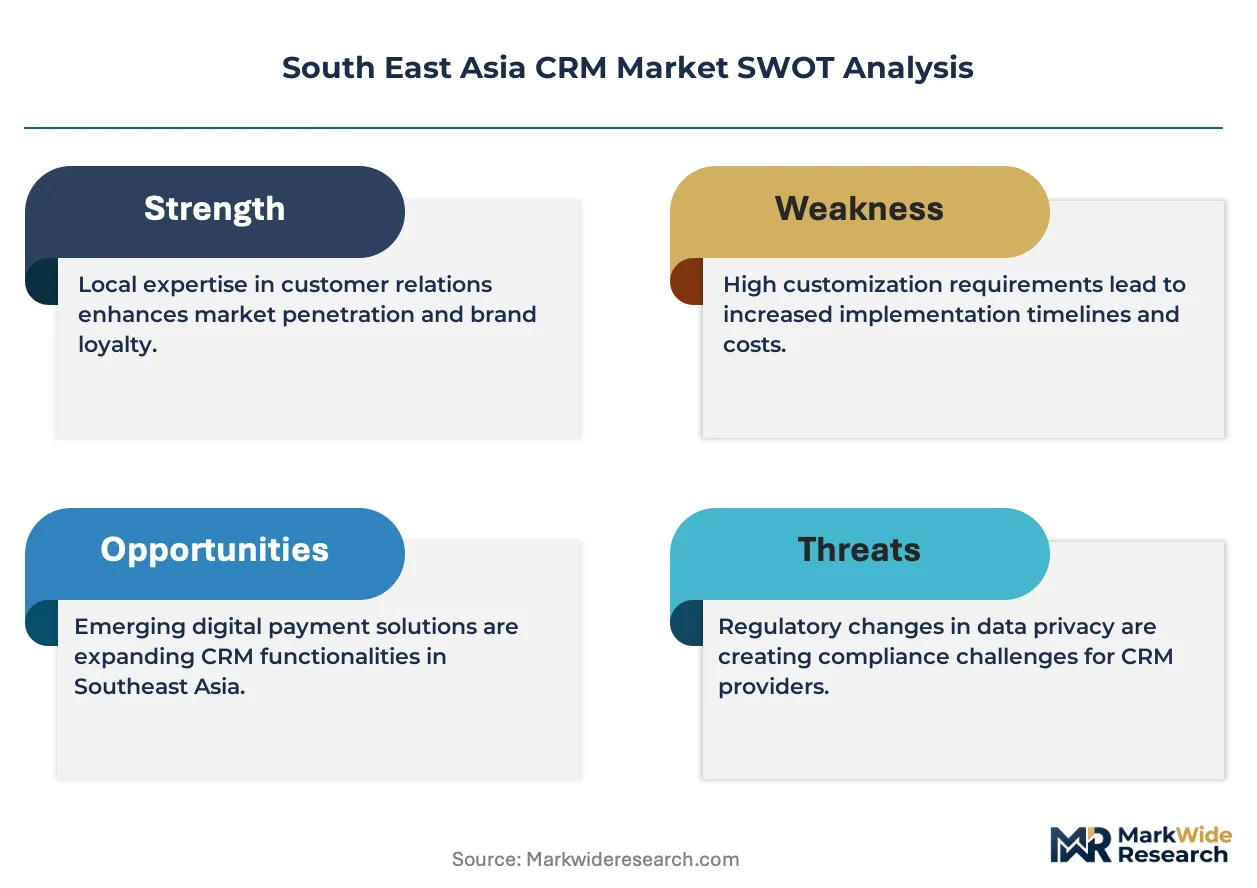
- Multi-Jurisdictional Compliance Burden:Thailand's Personal Data Protection Act and Vietnam's Cybersecurity Law impose conflicting cross-border transfer restrictions, fragmenting vendor architecture roadmaps and elevating legal advisory costs.
- Technical Talent Scarcity:Shortage of certified Salesforce and Oracle implementation specialists across Indonesia and Vietnam extends deployment timelines and inflates professional services rates.
- Legacy System Entrenchment:On-premises Siebel and SAP installations at established Thai banks resist cloud migration due to decade-old custom integrations, slowing replacement cycles.
Strategic Opportunities
- Philippines BPO Sector Digitization:Customer service outsourcing hubs in Manila and Cebu remain underpenetrated by enterprise CRM, presenting greenfield deployment opportunities for workforce management and omnichannel service modules.
- AI-Powered Predictive Analytics Convergence:Integration of natural language processing with credit scoring workflows enables Vietnamese digital banks to reduce churn through behavioral intervention models.
- Singapore MAS Technology Risk Guidelines:Elevated audit and encryption standards for financial services CRM create premium pricing tiers for vendors with pre-certified compliance architectures.
Industry Challenges
- Fragmented API Ecosystems:Inconsistent data exchange protocols between Indonesian core banking systems and third-party CRM platforms require costly middleware development, delaying time-to-value for enterprise deployments.
- Localization Depth Requirements:Multi-currency operations, Islamic banking compliance modules, and Bahasa/Thai/Vietnamese interface adaptations demand sustained R&D investment beyond baseline product development.
Report Scope
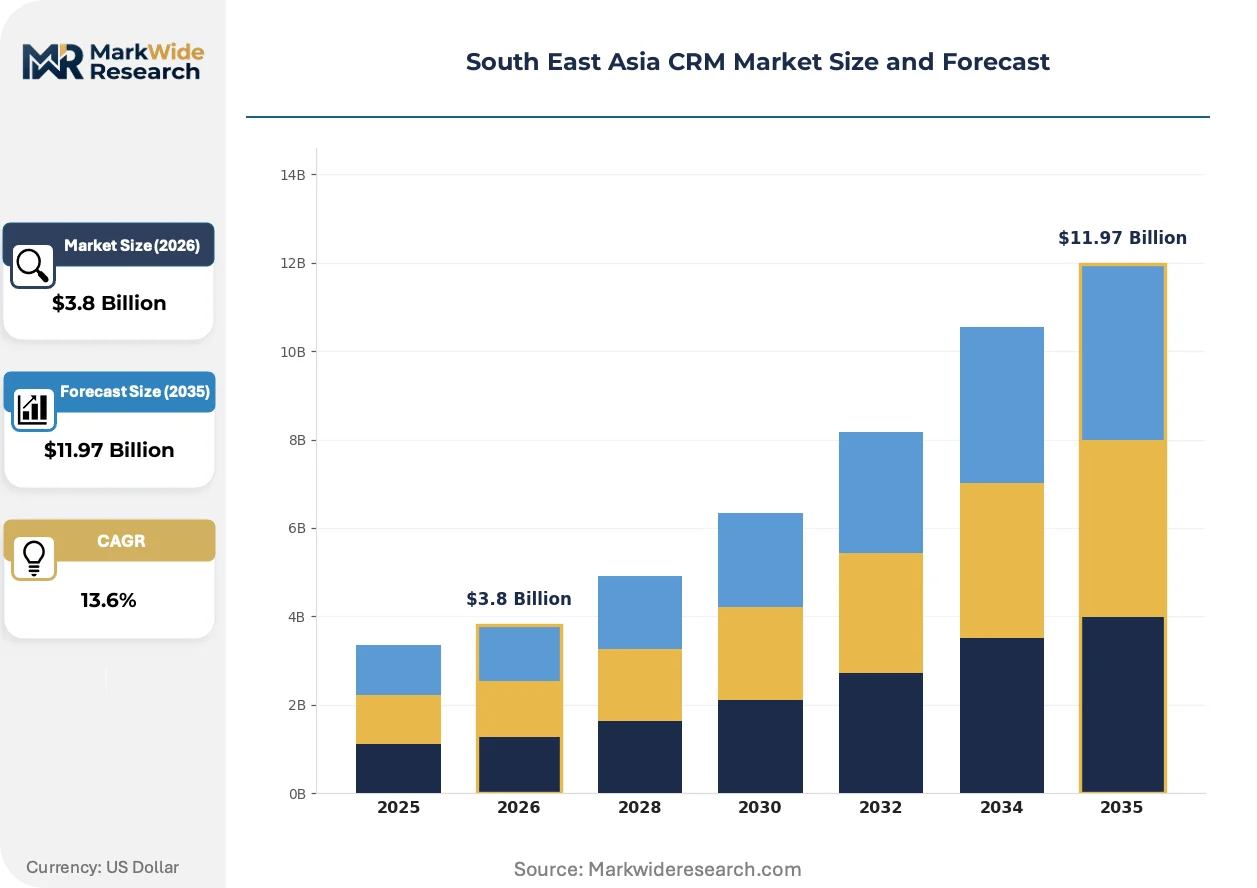
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia CRM Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Startups, Nonprofits Solution: Sales Automation, Marketing Automation, Customer Support, Analytics Industry Vertical: Retail, Healthcare, Financial Services, Education |
| Companies Covered | Oracle Corporation (Oracle CX), Zoho Corporation, Salesforce, Zendesk, Freshworks, Microsoft Corporation (Dynamics 365), HubSpot, Pipedrive, SAP SE (SAP Customer Experience), Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia CRM Market Strategic Shifts
Artificial intelligence layers are unifying previously siloed sales, service, and marketing workflows across ASEAN CRM deployments, compressing the traditional multi-vendor stack into integrated platforms while regulatory pressure accelerates compliance-native architecture design.
Embedded machine learning is unifying predictive lead scoring, sentiment analysis, and next-best-action recommendations within single vendor environments. Indonesian digital banks and Thai insurers are adopting these capabilities fastest, reducing their reliance on separate analytics tools. This convergence is unifying procurement decisions around platform breadth rather than point-solution depth, favoring vendors with pre-integrated AI engines.
Thailand's Personal Data Protection Act enforcement is tightening cross-border data flow documentation requirements for CRM operators. Financial institutions must now maintain auditable consent chains and localized processing logs, elevating operational overhead. Thai banking CRM deployments are responding by prioritizing domestic data residency architectures over regional hub strategies.
Subscription pricing models are displacing perpetual licenses across mid-market ASEAN firms. Modular onboarding and usage-based tiers reduce capital commitment barriers for Vietnamese SMEs and Philippine BPOs. This behavioral shift concentrates most visible in Indonesia's Jakarta-Surabaya corridor, where fintech startups prioritize operational flexibility over long-term asset ownership.
South East Asia CRM Market Segmentation
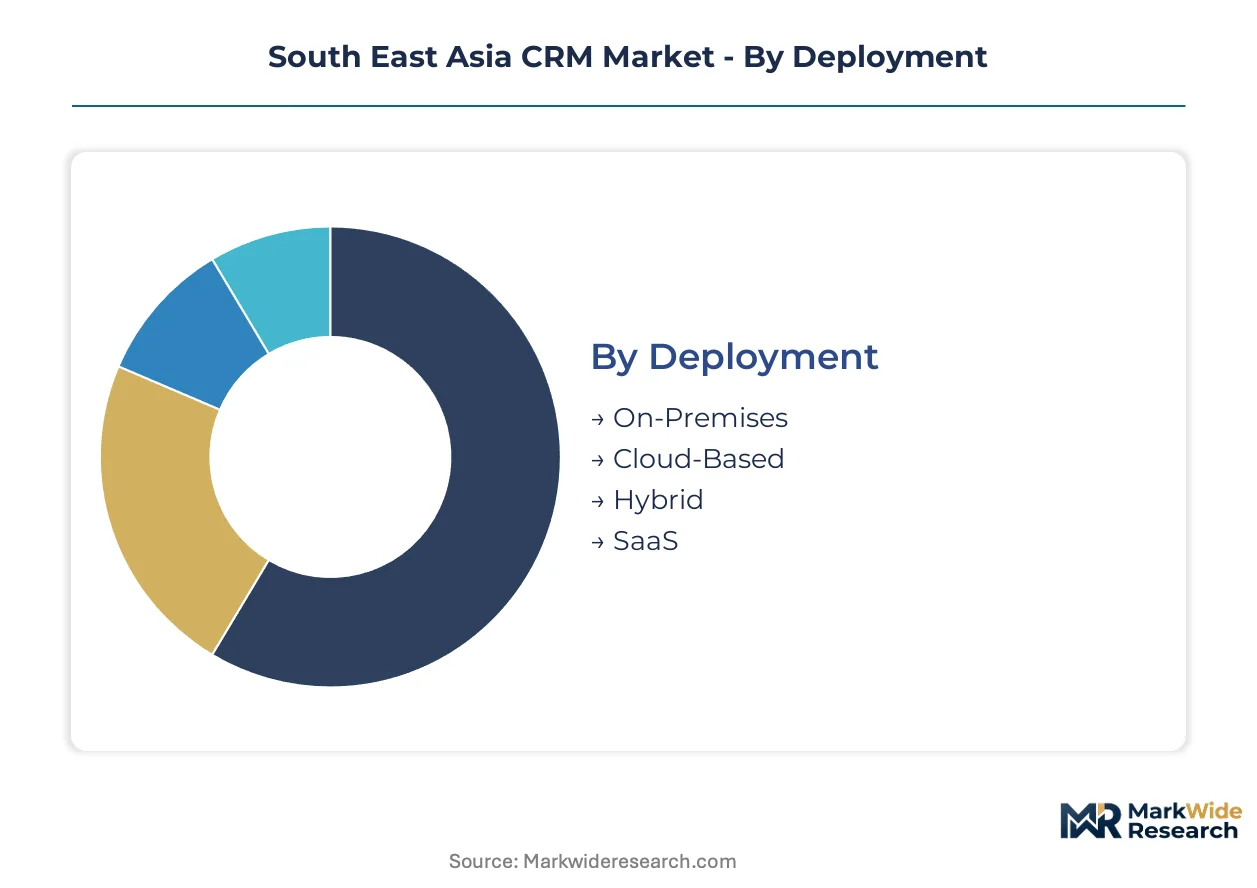
CRM procurement patterns across South East Asia diverge sharply by deployment readiness, organizational scale, and regulatory exposure. Segment-specific requirements around data residency, workflow complexity, and compliance certification reshape vendor positioning and pricing architecture throughout the region.
Deployment:
Cost tier and compliance exposure separate buyers most decisively in this dimension.
- Cloud-Based:Multi-tenant architectures with automatic scaling and API-native integration dominate new procurement across Indonesian fintech and Thai digital lenders. Jakarta-Surabaya corridor enterprises favor this model for its alignment with GR 71/2019 data localization when paired with domestic cloud partnerships.
- SaaS:Subscription pricing with modular feature activation reduces capital barriers for Vietnamese SMEs and Philippine BPOs. Pre-configured compliance templates for Thailand's Personal Data Protection Act accelerate deployment timelines for financial services buyers.
- On-Premises:Legacy Siebel and SAP installations persist at established Thai banks with decade-old custom integrations.
- Hybrid:Split architectures separating customer data on-premises from analytics workloads in cloud environments appeal to Singapore financial institutions under MAS technology risk guidelines.
Cloud-Based leads volumes today; SaaS is gaining share fastest.
End User:
Organizational scale dictates feature depth, implementation support needs, and procurement cycle length.
- Large Enterprises:Multi-cloud orchestration, advanced workflow automation, and dedicated compliance modules characterize requirements at Indonesian banking conglomerates and Singaporean insurers. These buyers command longest sales cycles but highest annual contract values.
- SMEs:Rapid deployment templates, Bahasa/Thai/Vietnamese localization, and usage-based pricing unlock adoption across Vietnam's growing digital commerce sector and Philippine service firms.
- Startups:API-first architectures and pay-as-you-scale models attract Jakarta fintech founders prioritizing operational flexibility.
- Nonprofits:Discounted licensing and donor management specialization drive procurement at ASEAN educational and humanitarian organizations.
Large Enterprises dominate contract value; SMEs are expanding most quickly.
Solution:
Functional maturity and integration depth separate vendor competitiveness in this category.
- Sales Automation:Pipeline management, lead scoring, and forecast modeling capture the largest revenue commitment across ASEAN CRM procurement. Indonesian digital banks deploy these capabilities for real-time lending decision workflows.
- Analytics:Predictive churn modeling and behavioral segmentation penetrate fastest at Vietnamese neobanks and Thai insurers reducing customer attrition through intervention triggers.
- Marketing Automation:Campaign orchestration and journey mapping tools concentrate demand among retail and e-commerce operators in Bangkok and Ho Chi Minh City.
- Customer Support:Omnichannel ticket management and workforce optimization serve Philippine BPO hubs in Manila and Cebu with high agent concurrency requirements.
Sales Automation anchors revenue today; Analytics shows the steepest expansion trajectory.
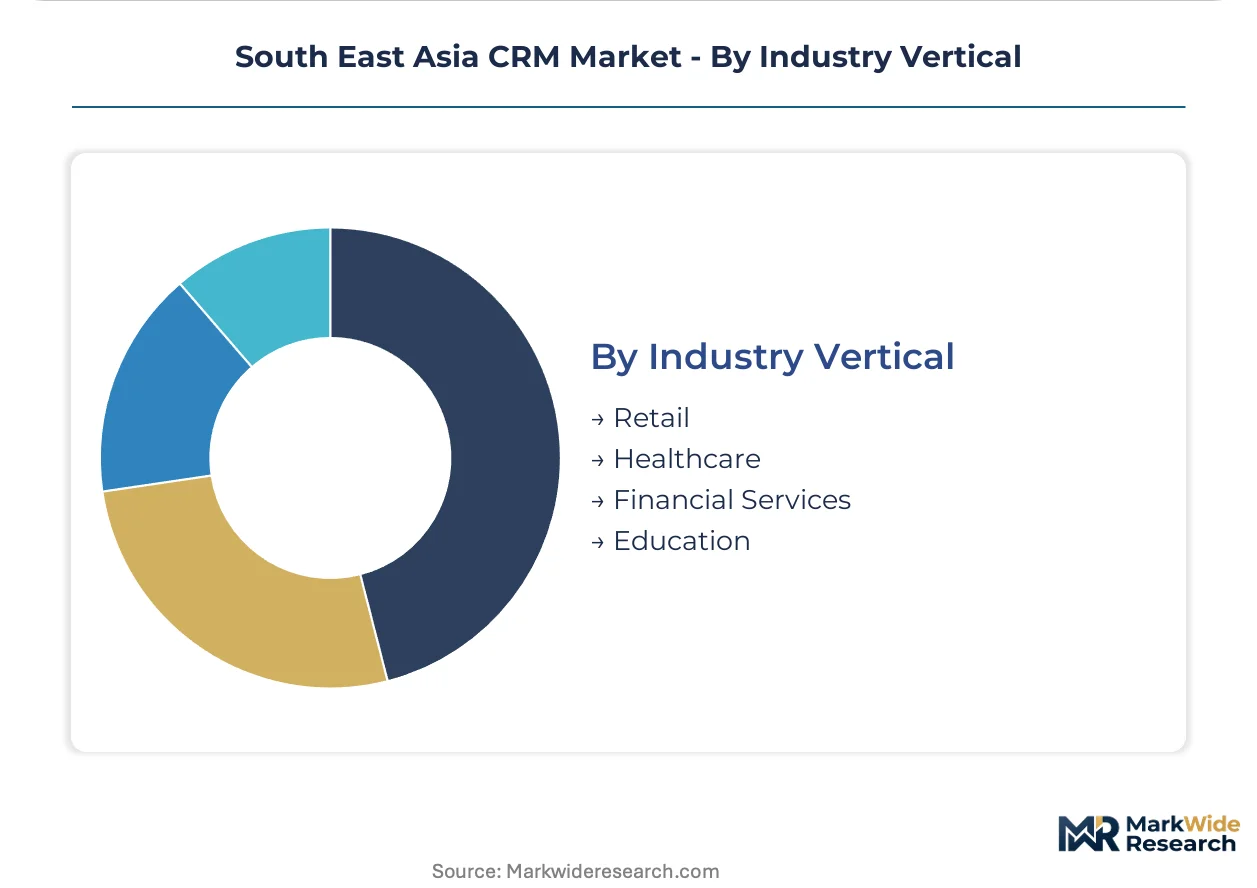
Industry Vertical:
Regulatory intensity and digital maturity reshape solution requirements across sectors.
- Financial Services:Audit logging, encryption standards, and pre-certified compliance architectures for Singapore MAS and Indonesia GR 71/2019 dominate vendor selection at regional banks and insurers. This vertical decouples from retail as the dominant CRM buyer across South East Asia.
- Retail:Omnichannel inventory synchronization and loyalty program integration drive adoption among Thai and Vietnamese consumer brands expanding digital commerce operations.
- Healthcare:Patient journey tracking and appointment scheduling systems penetrate private hospital networks in Bangkok and Jakarta with rising outpatient digitization.
- Education:Student lifecycle management and alumni engagement tools serve universities and vocational institutes across Malaysia and the Philippines.
Financial Services leads procurement intensity; Retail is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor infrastructure decisions across ASEAN, as compliance cost differentials between data localization regimes accelerate partnership formations with domestic cloud operators and fragment regional hub strategies.
Indonesia
GR 71/2019 mandates compel foreign CRM vendors to establish domestic data centers or partner with local operators, elevating compliance costs but expanding market access for compliant solutions. The Ministry of Communication and Informatics enforces strict cross-border transfer documentation, forcing architecture redesigns. The Jakarta-Surabaya corridor concentrates procurement activity, where banking conglomerates and fintech startups drive enterprise digitization.
Thailand
The Personal Data Protection Act tightens consent chain documentation and localized processing requirements for financial institutions deploying customer journey orchestration. Established banks with legacy Siebel installations resist cloud migration due to decade-old custom integrations, slowing replacement cycles. Bangkok anchors demand, with digital lenders and insurers prioritizing domestic data residency over regional hub models.
Vietnam
The Cybersecurity Law imposes data localization and cross-border transfer restrictions that reshape vendor compliance roadmaps for neobanks and digital lending platforms. Technical talent scarcity for certified implementation specialists extends deployment timelines and inflates professional services rates. Ho Chi Minh City clusters fintech procurement, where behavioral intervention models for churn prevention drive analytics module adoption.
Singapore
Monetary Authority technology risk guidelines elevate audit and encryption standards for financial services CRM, creating premium pricing tiers for pre-certified compliance architectures. Hybrid deployments separating customer data on-premises from analytics workloads appeal to institutional risk managers. The city-state functions as a regional compliance benchmark, with vendor certification here unlocking access to conservative ASEAN financial buyers.
Philippines
Customer service outsourcing hubs in Manila and Cebu remain underpenetrated by enterprise CRM, presenting greenfield opportunities for workforce management and omnichannel service modules. Subscription pricing with modular onboarding reduces capital barriers for mid-market BPO operators. The sector's digitization lags regional peers, concentrating demand in basic sales automation and ticket management capabilities.
South East Asia CRM Market Competitive Environment
Strategic partnerships with local cloud operators dominate the current landscape, as vendors race to satisfy data localization mandates while compressing deployment timelines. The market structures around three tiers: global platform providers with multi-cloud orchestration, regional specialists with deep localization, and mid-market challengers competing on price-performance. Two archetypes prevail—enterprise-grade incumbents leveraging database integration and compliance modules, and agile SaaS-native firms capturing SME adoption through API-first architectures. Competitive intensity centers on M&A activity for localization capabilities and capacity expansion into domestic data center infrastructure.
Within the enterprise platform tier, Oracle Corporation and Salesforce exemplify divergent approaches to regulated industry penetration, with the former anchoring deep database integration strategies and the latter driving AI-layer differentiation. Zoho Corporation occupies a distinct position among mid-market specialists, competing aggressively on localized support and multi-currency operations for ASEAN SMEs. These three firms represent the competitive spectrum: infrastructure-heavy compliance architectures, predictive analytics convergence, and price-disruptive modular onboarding.
| Leading Market Players |
|---|
| Oracle Corporation (Oracle CX) |
| Zoho Corporation |
| Salesforce |
| Zendesk |
| Freshworks |
| Microsoft Corporation (Dynamics 365) |
| HubSpot |
| Pipedrive |
| SAP SE (SAP Customer Experience) |
| Others |
Value Chain & Pricing Dynamics
Indonesia's GR 71/2019 data localization mandate gates qualified supply for CRM vendors seeking premium-tier pricing access, compelling domestic data center partnerships that elevate compliance costs while fragmenting regional hub strategies across ASEAN financial services procurement.
Pricing Analysis
Distributor margin compression in the indirect channel is reshaping how Oracle and Salesforce structure enterprise contracts across Jakarta and Bangkok. Three-tier pricing structure across premium, standard, and economy levels separates MAS-certified deployments in Singapore from basic SaaS tiers for Philippine BPOs. Pricing pressure stems from Zoho's aggressive price-performance positioning in Vietnam's mid-market. SMEs exhibit highest price sensitivity; Singaporean insurers under MAS guidelines show lowest.
Supply Chain Analysis
Regional distribution centers in Singapore and Jakarta anchor hub-and-spoke patterns for CRM implementation services across ASEAN. Technical talent pools concentrate in India, Singapore, and the Philippines. Raw material dependencies span cloud compute infrastructure, API middleware, and localized compliance modules. Single-source vulnerability runs through certified Salesforce and Oracle implementation specialist networks. Distribution runs through value-added resellers and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory data localization mandates across Indonesia, Thailand, and Vietnam driving steady replacement cycles and recurring subscription revenue expansion.
For Market Incumbents: Cement data residency architectures through domestic cloud partnerships in Jakarta and Bangkok to defend against emerging SaaS-native entrants. Prioritize MAS certification maintenance in Singapore to preserve premium pricing tiers. Channel control over implementation specialist networks represents the critical lever for compressing deployment timelines.
For New Entrants and Emerging Players: GR 71/2019 in Indonesia opens a window for API-first platforms targeting fintech startups in the Jakarta-Surabaya corridor with pay-as-you-scale models. Philippine BPOs in Manila and Cebu present the most penetrable white-space for workforce management modules. Go-to-market through vertical-specific compliance templates accelerates time-to-value against incumbent complexity.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with deep Bahasa/Thai/Vietnamese localization because fragmented compliance requirements prevent pure global platforms from capturing mid-market share efficiently. Target firms with pre-built Indonesia data center partnerships and established banking sector references. Watch enforcement intensity of Vietnam's Cybersecurity Law as the inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Partnership | GR 71/2019 compliance unlocks Indonesian banking procurement previously reserved for local operators. |
| MAS Certification Investment | Pre-certified encryption architectures command premium pricing tiers at Singaporean financial institutions. |
| API-First Platform Development | Modular onboarding reduces capital barriers for Vietnamese SMEs and Jakarta fintech startups. |
| Specialist Talent Acquisition | Certified Salesforce and Oracle implementation capacity compresses deployment timelines in talent-scarce markets. |
| Vertical Compliance Template Expansion | Islamic banking and Thai PDPA modules differentiate against generic global offerings. |
Study Parameters
Bottom-up financial services procurement modeling reconciled against top-down vendor capacity tracking forms the analytical core of this study. Primary interviews with CTOs at Indonesian banking conglomerates, IT procurement officers at Thai insurers, platform engineers at Singaporean fintechs, and integration specialists across Manila BPOs combined with secondary validation from SEC filings, hyperscaler capex disclosures, and Indonesia Ministry of Communication enforcement records. Triangulation between demand-side commitment data and supply-side partnership announcements ensures cross-verified outputs.
Historical trendline analysis of cloud migration patterns across the analysis window established baseline adoption curves. Segmentation modeling incorporated deployment model, organization size, vertical regulatory intensity, integration complexity, and regional data residency requirements. CAGRs derived from weighted average of vendor-reported subscription growth and enterprise procurement pipeline visibility. Forecast inputs included telecommunications infrastructure rollout timelines and evolving enforcement patterns for ASEAN data localization regimes.
Revisions become necessary when regulatory enforcement intensity shifts, major vendor partnership formations alter competitive dynamics, or telecommunications infrastructure investments accelerate cloud adoption beyond modeled trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Reference Management Software Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Conversational Customer Engagement Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
Global Saas Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Mobile CRM Market