
 Global Client Management Tools Market | 2026-2036
Global Client Management Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Client Management Tools Market Foresight
North American SaaS infrastructure is consolidating around a handful of dominant platforms. Salesforce leverages its AppExchange ecosystem to sustain developer loyalty across enterprise segments. HubSpot anchors mid-market positioning with inbound marketing integration that competitors struggle to replicate. Zoho CRM competes aggressively on price while extending feature parity into emerging markets.
Client management tools encompass software platforms that centralize customer interaction records, automate sales workflows, and embed analytics for relationship intelligence. These systems typically integrate via REST APIs and support role-based access controls across distributed teams. Cloud-based deployment leads solution type adoption as financial services firms and IT consultancies prioritize remote accessibility and reduced capital expenditure. Customer relationship management remains the largest solution category, though client analytics is gaining traction among hospitality operators seeking predictive churn models.
The EU AI Act and GDPR shape product roadmaps for vendors serving European financial services firms, forcing explicit consent logging and algorithmic transparency features. In the United States, HIPAA and SEC record-keeping rules create compliance moats for platforms targeting healthcare and investment advisory verticals. Stakeholders must weigh jurisdictional certification requirements against the cost of maintaining parallel product configurations.
Market Dynamics
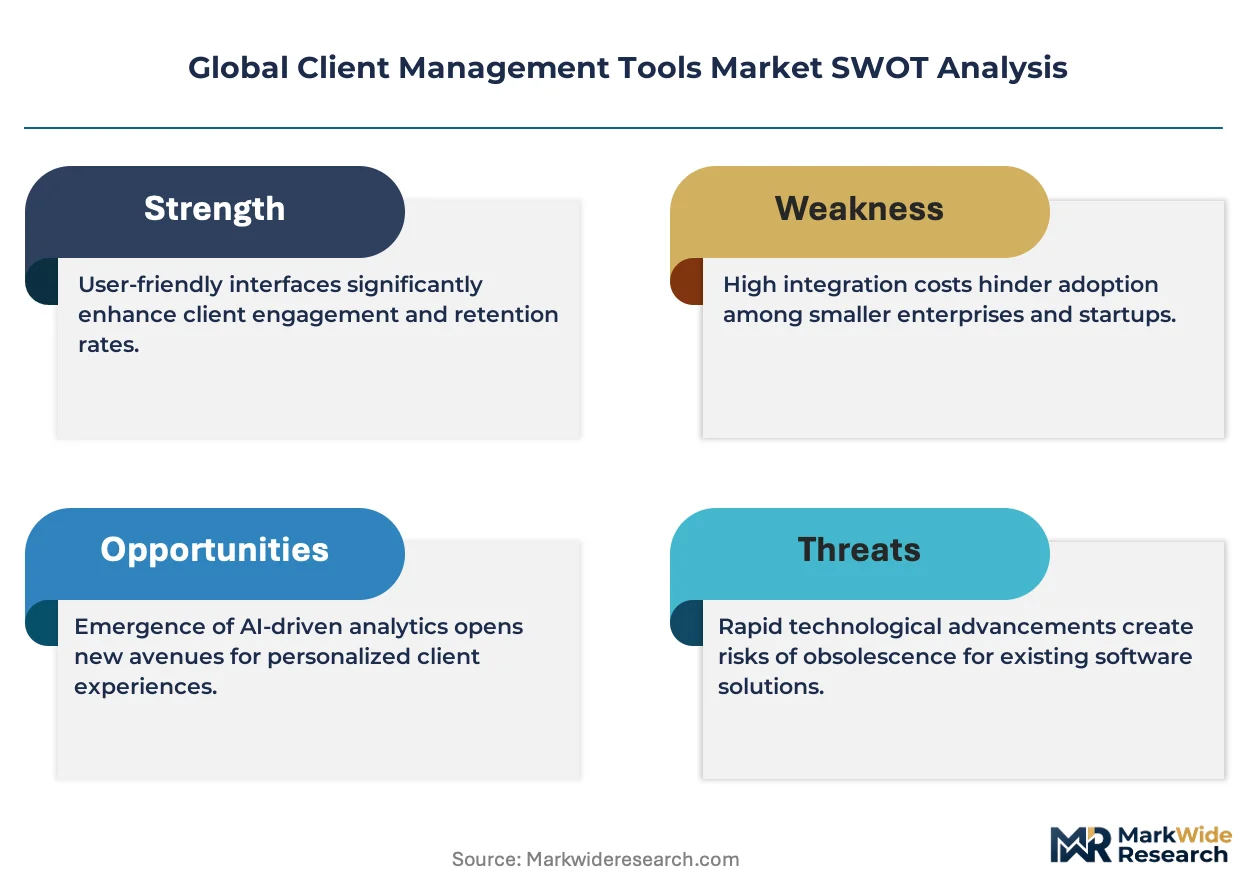
Cloud migration mandates under the EU AI Act and GDPR are compressing replacement cycles for on-premise client management systems, forcing financial services firms to accelerate SaaS procurement decisions.
Growth Catalysts
- GDPR Algorithmic Transparency Mandates:European financial services firms must replace legacy CRM systems with consent-logging platforms, creating immediate procurement demand across Germany, France, and the Netherlands.
- Hospitality Predictive Analytics:Hotel chains and cruise operators are deploying client churn models to optimize loyalty program spend, expanding the addressable market beyond traditional sales automation.
- Remote Workforce Distribution:Distributed IT consultancies require REST API-enabled platforms with role-based access controls, prioritizing cloud deployment over capital-intensive on-premise infrastructure.
Market Restraints
- Parallel Compliance Architecture Costs:Vendors serving both EU and US markets must maintain separate product configurations for GDPR consent logging versus HIPAA audit trails, inflating R&D overhead.
- Data Residency Requirements:Saudi Arabia's SFDA and China's NMPA impose strict localization rules that fragment cloud infrastructure economics and complicate multi-tenant SaaS delivery.
- Legacy System Entrenchment:Investment advisory firms face SEC record-keeping rule friction when migrating decades of customer interaction archives to modern platforms.
Strategic Opportunities
- India SME Digitization:RBI's push for formalized financial services access is creating first-time CRM demand among regional banks and non-banking financial companies in Mumbai and Bangalore.
- AI-CRM Convergence:Natural language processing integration with relationship intelligence is opening premium pricing tiers for predictive client health scoring in wealth management.
- Embedded Finance Channels:Client management tools are penetrating non-financial verticals through banking-as-a-service integrations, particularly among Brazilian fintech-enabled retailers.
Industry Challenges
- API Integration Complexity:Enterprise IT teams struggle to reconcile REST-based client management platforms with decades-old COBOL core banking systems without custom middleware development.
- Cross-Border Data Governance Talent:Shortages of compliance engineers fluent in both GDPR Article 22 algorithmic decision rules and SEC cybersecurity disclosure requirements delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Client Management Tools Market |
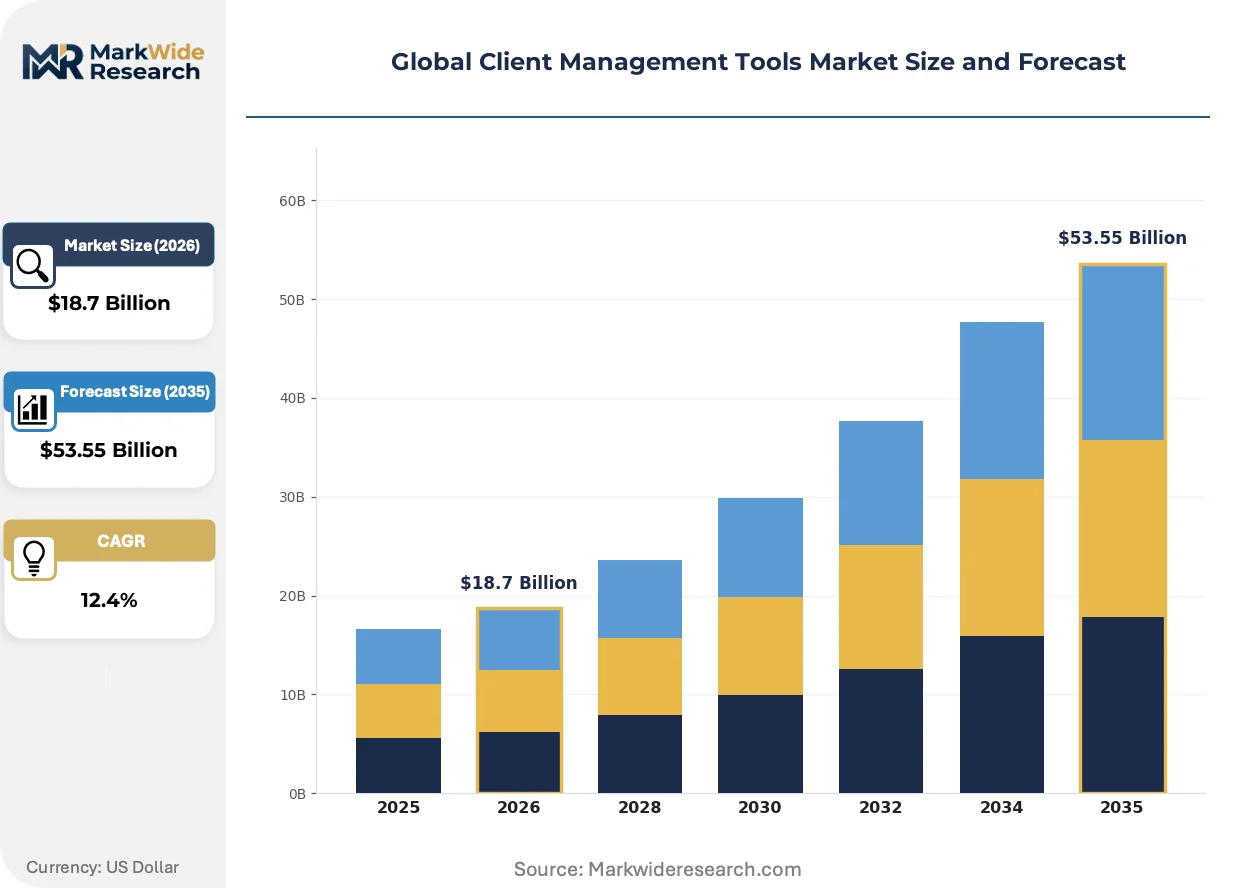
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $53.55 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Hosted Solution Type: Customer Relationship Management, Contact Center Automation, Sales Force Automation, Help Desk Management, Case Management Use Case: Lead Management, Customer Support, Sales Tracking, Marketing Automation, Client Analytics End User: Financial Services Firms, IT Consultancies, Educational Institutions, Hospitality Operators, Telecom Providers |
| Companies Covered | monday.com, Freshworks CRM, Salesforce, ActiveCampaign, Pipedrive, HubSpot, Microsoft Dynamics 365, Copper, Zoho CRM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Client Management Tools Market Shifts & Advancements
Artificial intelligence is embedding predictive capabilities directly into client interaction workflows, compressing the gap between data capture and actionable relationship intelligence across enterprise segments.
Unified customer data platforms are consolidating fragmented interaction records from call centers, mobile apps, and branch visits into single client profiles. Large US banks and European insurers are adopting these systems fastest, with procurement cycles shortening from 18 months to 9 months. This consolidation is unifying previously siloed marketing, sales, and service operations into continuous engagement loops.
The EU AI Act's risk classification framework is mandating explicit human oversight for automated client scoring in credit and insurance decisions. Vendors must now build explainability dashboards and audit trails into algorithmic features. European retail banks are most affected, with product roadmaps prioritizing transparency modules over pure predictive accuracy.
Subscription pricing for client management tools is displacing perpetual license models among mid-market buyers. Value-added resellers and systems integrators in the United States are capturing recurring revenue through managed service wrappers rather than implementation fees alone. Healthcare providers and regional investment advisors show the fastest behavioral shift toward operational expenditure preference.
Global Client Management Tools Market Segmentation
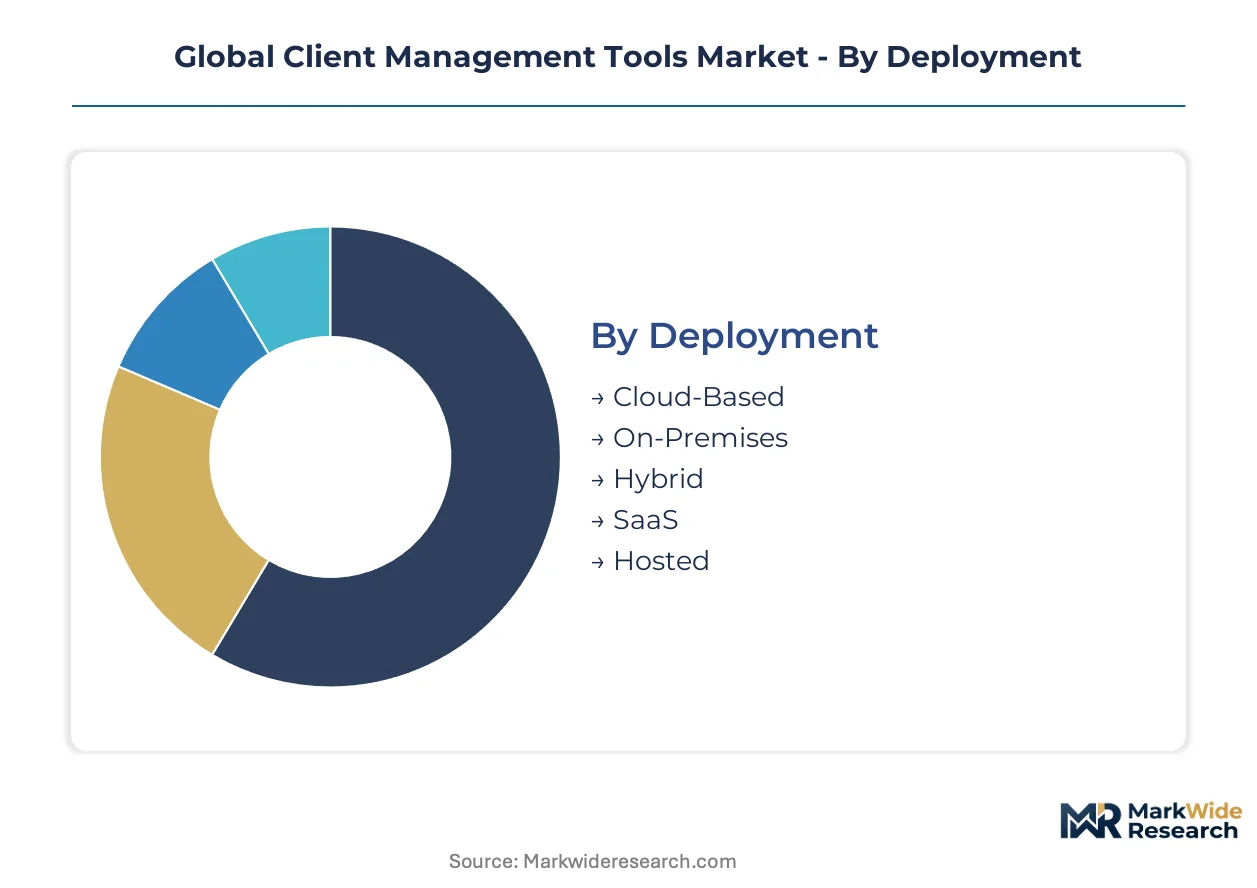
Client management tools fragment across deployment architectures, functional modules, and industry verticals. Understanding these divisions reveals where procurement budgets concentrate and which integration patterns dominate enterprise roadmaps.
Deployment:
Standalone cloud deployments sit at one integration extreme; embedded hybrid stacks anchor the other, with cost and compliance drivers determining placement.
- Cloud-Based:Multi-tenant architectures deliver remote accessibility through browser interfaces and mobile applications. Financial services firms in the United States prioritize these platforms to satisfy SEC cybersecurity disclosure requirements while eliminating data center capital expenditure.
- SaaS:Subscription licensing with automatic feature updates and API extensibility. IT consultancies across Germany and France are migrating here to meet GDPR consent-logging mandates without maintaining infrastructure.
- On-Premises:Single-tenant installations behind corporate firewalls with full data sovereignty. Saudi Arabian banks select this model to satisfy SFDA localization requirements.
- Hybrid:Sensitive client records remain on-site while engagement tools operate in cloud environments. Japanese insurers favor this split to balance METI data governance with operational flexibility.
- Hosted:Vendor-managed private cloud instances with dedicated infrastructure. Brazilian fintechs deploy these to navigate ANVISA audit trail expectations without building internal DevOps teams.
Volume placements concentrate in Cloud-Based; the faster expansion belongs to SaaS.
Solution Type:
Cost tiers separate enterprise-grade relationship platforms from departmental automation tools, with pricing stratifying across premium, standard, and economy levels.
- Customer Relationship Management:Core platforms unifying contact records, opportunity pipelines, and communication histories across distributed teams. Wealth managers in Switzerland and Singapore embed these for SEC and MAS record-keeping compliance.
- Client Analytics:Predictive scoring engines identifying churn risk and lifetime value propensity. Hospitality operators in Dubai and Miami deploy these to optimize loyalty program ROI.
- Sales Force Automation:Territory management, quota tracking, and mobile order entry for field representatives. Indian pharmaceutical distributors adopt these to satisfy CDSCO documentation standards.
- Contact Center Automation:Interactive voice response, workforce management, and real-time coaching dashboards. Australian telecom providers integrate these under TGA-aligned service quality frameworks.
- Help Desk Management:Ticket routing, knowledge base curation, and SLA monitoring for internal IT support. Educational institutions in Canada select these to meet Health Canada privacy guidelines.
- Case Management:Legal and regulatory matter tracking with document versioning and deadline alerts. UK investment advisory firms require these for FCA suitability rule adherence.
Procurement volume tilts toward Customer Relationship Management; Client Analytics is climbing the fastest.
Use Case:
Application maturity varies sharply, with some workflows decades old and others emerging from recent AI convergence.
- Lead Management:Capture, scoring, and distribution systems converting prospect interest into qualified opportunities. Brazilian retailers integrate these with banking-as-a-service platforms to embed credit offers at point-of-sale.
- Client Analytics:Behavioral segmentation and predictive modeling for relationship health assessment. Cruise operators in Norway and Italy deploy churn models to optimize passenger retention spend.
- Customer Support:Omnichannel case resolution across email, chat, phone, and social touchpoints. South Korean electronics manufacturers staff these 24/7 under MFDS post-market surveillance obligations.
- Sales Tracking:Pipeline visibility and forecast accuracy tools for revenue operations. Regional banks in Mumbai adopt these following RBI digitization directives.
- Marketing Automation:Campaign orchestration, personalization engines, and attribution analytics. French luxury brands leverage these under CNIL consent management rules.
Adoption depth is greatest in Lead Management; Client Analytics shows the steepest expansion trajectory.
End User:
Customer type determines feature prioritization, with compliance-heavy verticals demanding audit trails that lighter users dismiss.
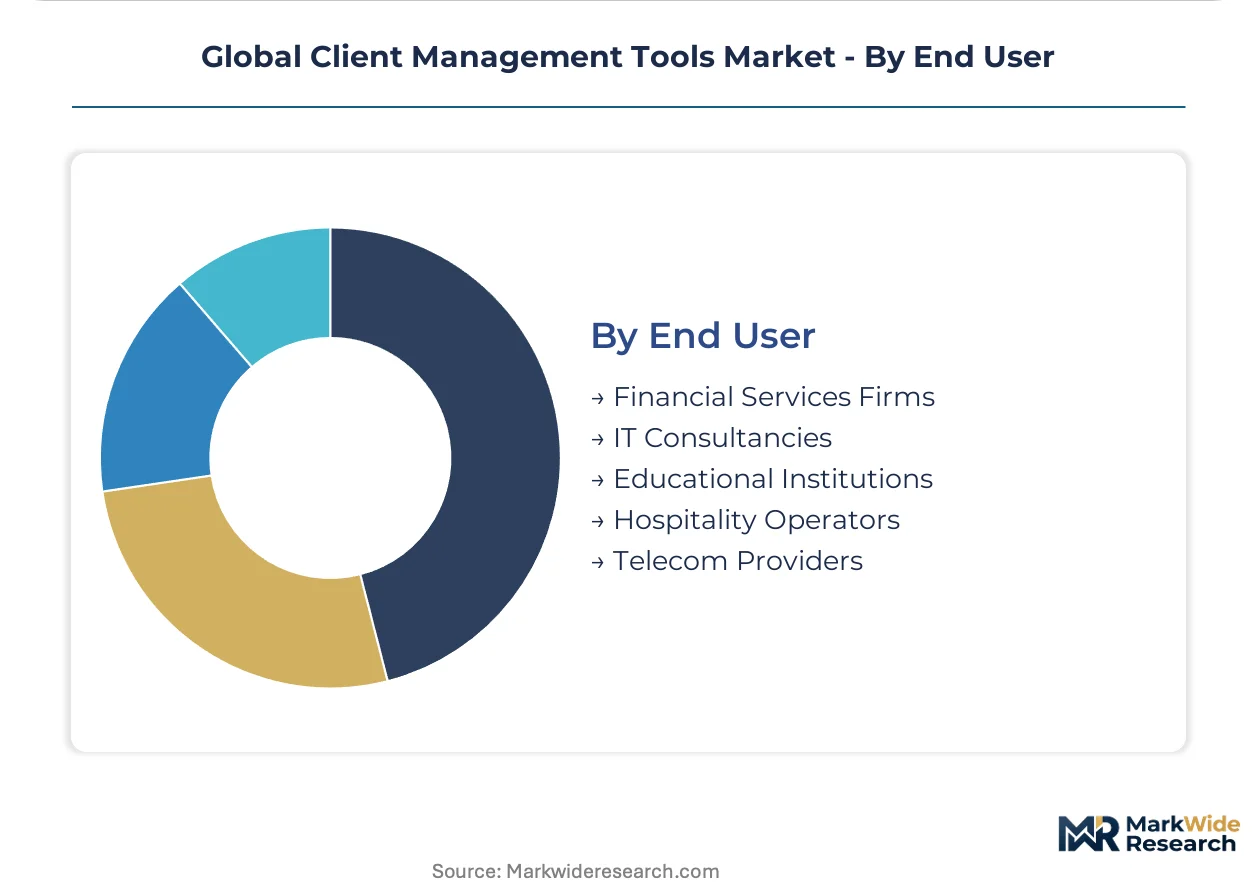
- Financial Services Firms:Banks, insurers, and asset managers requiring algorithmic transparency and immutable record archives. German and Dutch institutions lead replacement cycles driven by EU AI Act risk classification mandates.
- IT Consultancies:Project-based professional services firms tracking billable hours and client deliverables. Distributed teams across Bangalore and Hyderabad prioritize REST API platforms with granular role-based access.
- Hospitality Operators:Hotel chains, resorts, and cruise lines managing guest preferences and loyalty tiers. Operators in Singapore and the Maldives deploy predictive models to optimize occupancy yield.
- Telecom Providers:Subscription lifecycle management and churn prevention for mobile and broadband subscribers. Australian and Canadian carriers integrate these with national broadband initiative reporting.
- Educational Institutions:Alumni relations, admissions pipeline, and student success tracking. US universities select platforms satisfying FERPA record retention alongside HIPAA research compliance.
Financial Services Firms dominate current procurement; Hospitality Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's SaaS infrastructure anchors North American demand for client management platforms, while cloud migration mandates across European financial centers and Asia-Pacific IT hubs reshape procurement geography.
United States
Enterprise SaaS procurement concentrates around SEC cybersecurity disclosure requirements and HIPAA audit trail obligations for healthcare providers. Financial services firms in New York and Boston accelerate replacement cycles for legacy CRM systems. The San Francisco Bay Area hosts the dominant platform ecosystems that set integration standards for distributed teams.
Germany
Frankfurt-based banks and insurers drive demand for GDPR-compliant consent-logging platforms under EU AI Act risk classification rules. Stuttgart automotive suppliers adopt client analytics for predictive churn modeling in B2B service contracts. Bavarian IT consultancies prioritize REST API architectures with granular role-based access controls.
United Kingdom
London investment advisory firms navigate FCA suitability rules while migrating decades of customer interaction archives to cloud platforms. Edinburgh wealth managers embed algorithmic transparency dashboards for automated client scoring compliance. Manchester fintechs integrate banking-as-a-service channels into non-financial verticals.
India
RBI digitization directives spur first-time CRM adoption among Mumbai regional banks and Bangalore non-banking financial companies. Hyderabad IT consultancies require cloud-based platforms for distributed workforce management. Chennai manufacturing exporters deploy sales force automation to satisfy CDSCO documentation standards.
Japan
Tokyo insurers favor hybrid deployments balancing METI data governance with operational flexibility for sensitive client records. Osaka hospitality operators deploy predictive churn models to optimize loyalty program spend. Nagoya automotive distributors integrate unified customer data platforms across call centers and mobile apps.
Global Client Management Tools Market Competitive Landscape
Global majors compete with regional champions across platform integration depth and compliance specialization. The vendor base organizes into three tiers: dominant ecosystem players with AppExchange marketplaces, mid-market inbound marketing specialists, and aggressive price competitors extending feature parity. Consolidation pressures concentrate around M&A activity targeting AI-CRM convergence capabilities and geographic expansion into SME digitization markets.
Within the ecosystem-platform tier, Salesforce and Microsoft Dynamics 365 occupy positions anchored by enterprise-grade API extensibility and vertical compliance modules. HubSpot exemplifies the mid-market inbound marketing archetype with workflow automation that competitors struggle to replicate. Zoho CRM represents the price-competitive vector, extending feature parity into emerging markets through localized deployment options.
| Leading Market Players |
|---|
| monday.com |
| Freshworks CRM |
| Salesforce |
| ActiveCampaign |
| Pipedrive |
| HubSpot |
| Microsoft Dynamics 365 |
| Copper |
| Zoho CRM |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates from Frankfurt and Paris banks are forcing SaaS vendors to absorb algorithmic transparency development costs, compressing margins on European deployments while creating pricing premiums for certified configurations elsewhere.
Pricing Analysis
Service bundling separates premium tiers with dedicated implementation support from self-service economy tiers with community-only assistance. Three-tier pricing structure across premium, standard, and economy levels reflects compliance certification depth, with GDPR-audited platforms commanding premiums over baseline cloud offerings. Price differentiation hinges on API call volume allowances and vertical-specific compliance modules, with financial services buyers least sensitive due to regulatory non-negotiability. Cost compression in the mid-market is intensifying because HubSpot and Zoho CRM are racing to feature parity.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor hub-and-spoke delivery for cloud infrastructure serving financial services clients. Software development draws from engineering talent pools in India, Poland, and Vietnam, while data center hardware sources from Taiwan semiconductors and Korean memory components. Supply chain risk centers on single-source vulnerability for AI training compute from NVIDIA-dominated GPU supply. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with localized compliance engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native SaaS architectures are displacing on-premise legacy CRM installations across financial services, with REST API extensibility and automated compliance updates becoming table stakes for procurement.
For Market Incumbents: Deepen vertical integration into specialized compliance modules for SEC and GDPR jurisdictions, locking in switching costs through embedded audit trail workflows. Acquire boutique AI-CRM convergence specialists in wealth management to preempt challenger encroachment on predictive client scoring premiums.
For New Entrants and Emerging Players: Regional banks in Mumbai and Bangalore represent the most penetrable buyer archetype, with first-time CRM demand outpacing vendor supply under RBI digitization pressure. Target hospitality operators in Dubai and Singapore with churn-optimized analytics bundles, using industry-specific ROI calculators as the primary go-to-market wedge.
For Investors and Strategic Acquirers: The window for entry favors platforms with pre-built GDPR Article 22 explainability modules, as EU AI Act enforcement hardens procurement requirements. Watch for algorithmic transparency dashboard adoption rates among German retail banks as the inflection signal distinguishing viable acquisition targets from compliance-lagged legacy vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | REST API ecosystems from Salesforce and Microsoft Dynamics 365 lock in enterprise developer loyalty across distributed teams. |
| Acquisition of Specialist Firm | AI-CRM convergence targets with predictive churn models command premiums from hospitality operators in Singapore and Dubai. |
| Geographic Expansion | Localized deployment options in Saudi Arabia satisfy SFDA data residency mandates without multi-tenant architecture rebuilds. |
| Strategic Partnership | Banking-as-a-service integrations with Brazilian fintechs penetrate non-financial verticals through embedded finance channels. |
| Product Launch | Explainability dashboards addressing EU AI Act risk classification open immediate procurement pipelines in Frankfurt and Amsterdam. |
Research Methodology
Document review covered SEC cybersecurity disclosure filings, GDPR enforcement decisions, and EU AI Act implementation guidance, complemented by interviews with CTOs at US financial services firms, compliance officers at German insurers, and integration specialists at Bangalore IT consultancies. Secondary validation drew from hyperscaler capex disclosures, AppExchange marketplace metrics, and hospital procurement databases. Bottom-up deployment estimates triangulated against top-down SaaS spending benchmarks across the analysis window.
Market size outputs reflect segmentation across deployment models, solution types, and end-user verticals, with organization size and regional adoption patterns as cross-cutting dimensions. CAGRs were derived from procurement cycle compression rates and replacement timeline acceleration under regulatory mandates. Forecast inputs incorporated cloud migration mandates from EU AI Act enforcement and RBI digitization directives.
Revisions become necessary when GDPR enforcement intensity shifts, SEC cybersecurity disclosure rules expand, or AI training compute supply constraints disrupt vendor roadmaps. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market