
 Customer Relationship Management in Healthcare Market | 2026-2036
Customer Relationship Management in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Relationship Management in Healthcare Market Insights
North American cloud infrastructure expansion is reconfiguring how healthcare providers deploy patient relationship platforms. Salesforce Health Cloud leverages extensive API ecosystems to anchor enterprise health system contracts across integrated delivery networks. Microsoft Dynamics 365 sustains competitive position through backward integration into Azure compliance frameworks that meet federal healthcare data standards. Oracle Corporation dominates database-centric deployments where hospitals require on-premise sovereignty over protected health information.
Customer relationship management in healthcare encompasses software systems that aggregate patient demographics, clinical interactions, billing histories, and communication logs into unified profiles accessible across care teams. These platforms typically integrate with electronic health record systems through HL7 FHIR protocols while maintaining audit trails for every data access event. Cloud-based CRM deployments command expanding share as health systems prioritize remote accessibility and disaster recovery capabilities over capital-intensive local server maintenance. Artificial Intelligence and machine learning segments attract disproportionate R&D investment as vendors compete on predictive analytics for patient no-show reduction and readmission risk scoring. Mobile CRM remains nascent in clinical settings where workflow interruptions carry liability exposure, though pharmacy and home health applications show stronger adoption velocity.
FDA oversight of software-as-medical-device classifications intersects with HIPAA security rule enforcement to create dual compliance burdens for CRM vendors serving US providers. The EU AI Act and GDPR cross-border data transfer restrictions impose additional architectural requirements for platforms with multinational health system clients. Stakeholders must monitor evolving FDA guidance on clinical decision support algorithms to determine which CRM-embedded analytics tools trigger regulatory submission requirements.
Market Dynamics
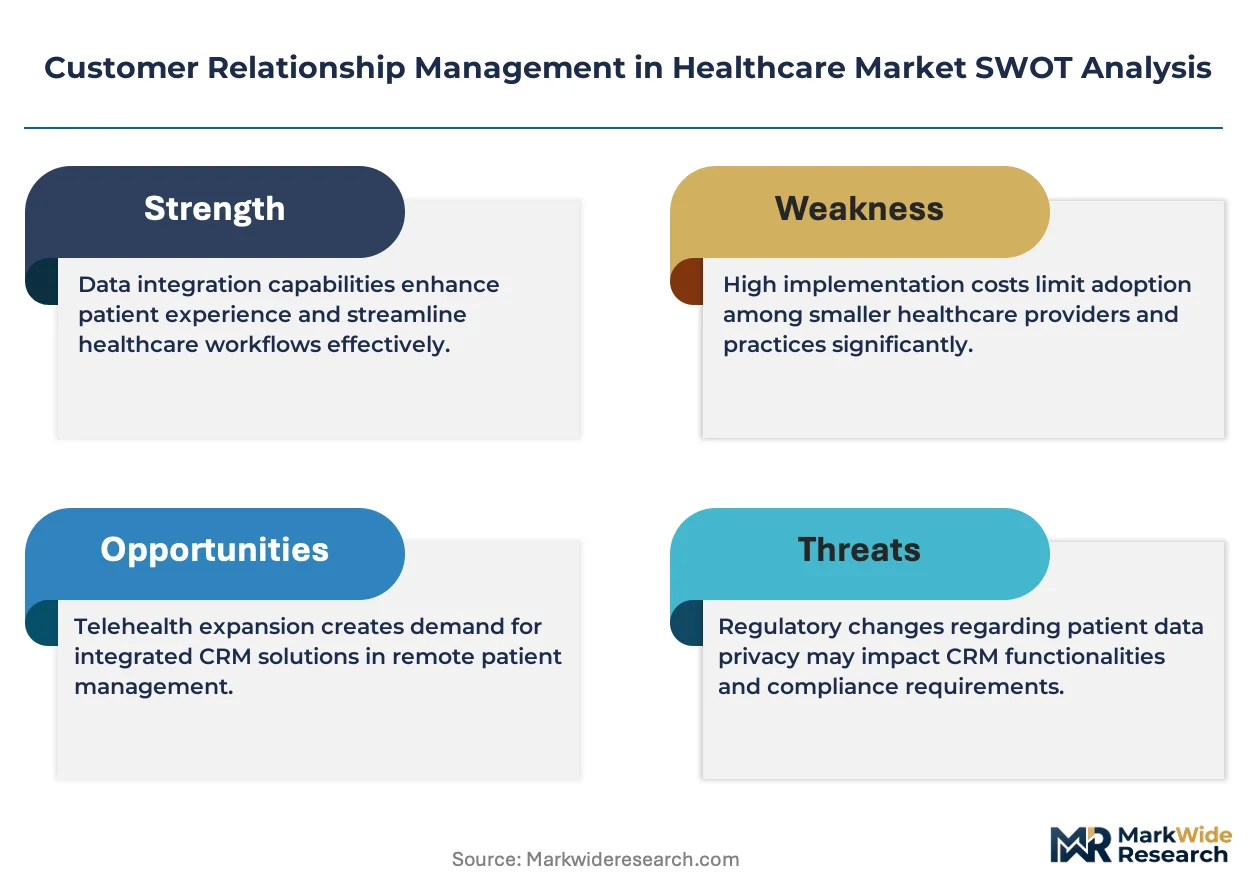
Health system consolidation and the mandate for interoperable data exchange are compressing vendor selection cycles while elevating platform consolidation over point solutions.
Growth Catalysts
- HIPAA Security Rule enforcement:The Office for Civil Rights has intensified audit frequency, compelling hospitals to replace legacy contact management with auditable cloud CRM architectures that log every data access event.
- Artificial Intelligence integration:Predictive models for patient no-show reduction and readmission risk scoring are pulling R&D investment toward platforms that embed machine learning natively rather than through bolt-on modules.
- Rural hospital closures:Consolidation into regional integrated delivery networks is creating demand for centralized patient relationship platforms that span multiple facility types under unified data governance.
Market Restraints
- Specialized health IT labor scarcity:The shallow talent pool for HL7 FHIR integration specialists and HIPAA compliance architects inflates implementation timelines and professional services costs.
- Cloud infrastructure concentration:Three hyperscalers dominate health-compliant cloud hosting, creating single-point-of-failure risk for CRM vendors dependent on their federal authorization frameworks.
- FDA software-as-medical-device ambiguity:Uncertain classification boundaries for clinical decision support algorithms embedded in CRM platforms delay product roadmaps and expand legal exposure.
Strategic Opportunities
- Behavioral health integration:Substance use disorder clinics and community mental health centers remain underserved by enterprise CRM vendors, presenting greenfield deployment potential for specialized workflow tools.
- EU AI Act compliance services:Multinational health systems require architectural redesigns for cross-border data flows, creating consulting and software revenue streams around GDPR and AI risk classification alignment.
- Home health and remote patient monitoring convergence:CRM platforms that ingest biometric streams from connected devices can anchor longitudinal patient records beyond acute care episodes, displacing siloed remote monitoring dashboards.
Industry Challenges
- Electronic health record integration complexity:Proprietary data models from dominant EHR vendors force costly custom middleware development, fragmenting CRM deployment timelines across health systems.
- Interoperability certification backlog:The Office of the National Coordinator for Health IT's delayed enforcement of information blocking rules creates uncertainty about which integration standards will prevail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Relationship Management in Healthcare Market |
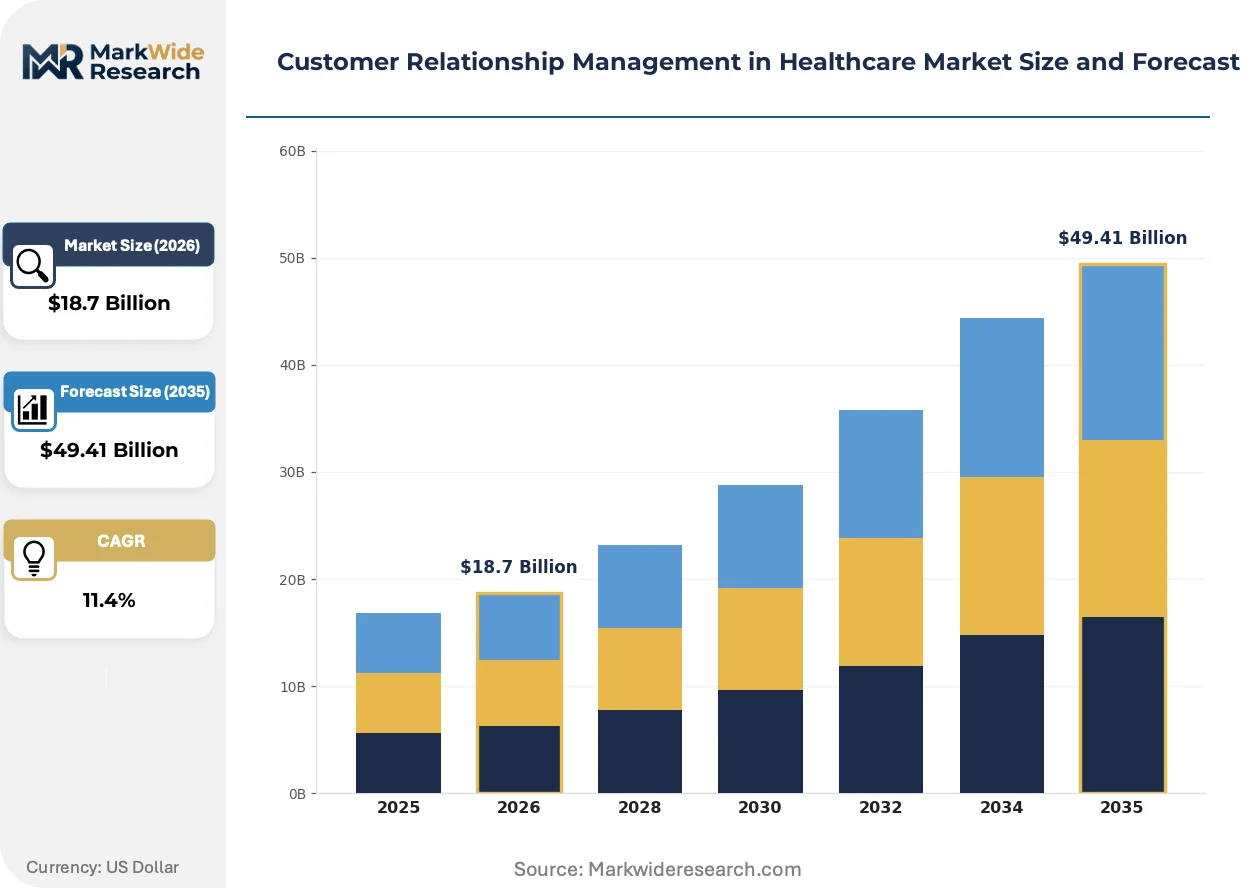
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based CRM, On-Premise CRM, Integrated CRM, Mobile CRM End User: Hospitals, Clinics, Pharmacies, Healthcare Providers Deployment: Private Cloud, Public Cloud, Hybrid Cloud, Local Server Technology: Artificial Intelligence, Machine Learning, Data Analytics, Telehealth Solutions |
| Companies Covered | Salesforce Health Cloud, Microsoft Dynamics 365, Oracle Corporation, SAP SE, IBM Corporation, HubSpot, Infor Inc., Cerner Corporation, Athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Relationship Management in Healthcare Market Trends and Innovations
Generative AI and ambient clinical documentation are restructuring how patient data enters CRM systems, compressing manual entry burdens while raising new questions about algorithmic transparency in care coordination workflows.
Natural language processing engines are collapsing the distinction between unstructured clinical notes and structured CRM data fields. Health systems in the United States are piloting ambient documentation tools that populate patient profiles in real time during encounters. This compression of data entry labor is enabling care coordinators to manage panel sizes previously requiring dedicated administrative staff.
The EU AI Act's risk classification framework for health applications is forcing architectural separation between predictive analytics modules and core CRM databases. Vendors serving multinational clients must maintain dual compliance tracks—one for HIPAA-aligned US deployments and another for GDPR-plus-AI-Act European configurations. Medium-sized health systems with cross-border operations face the steepest adaptation costs as they lack dedicated regulatory technology teams.
Subscription pricing for CRM modules is displacing perpetual licensing as the dominant procurement model among US health systems capitalizing on federal interoperability incentive payments. Chief information officers now prioritize operating expense predictability over capital expenditure ownership, particularly for AI-enabled features where model improvement velocity matters more than static functionality. This shift is most pronounced among nonprofit hospital networks with constrained bond financing capacity.
Customer Relationship Management in Healthcare Market Segmentation
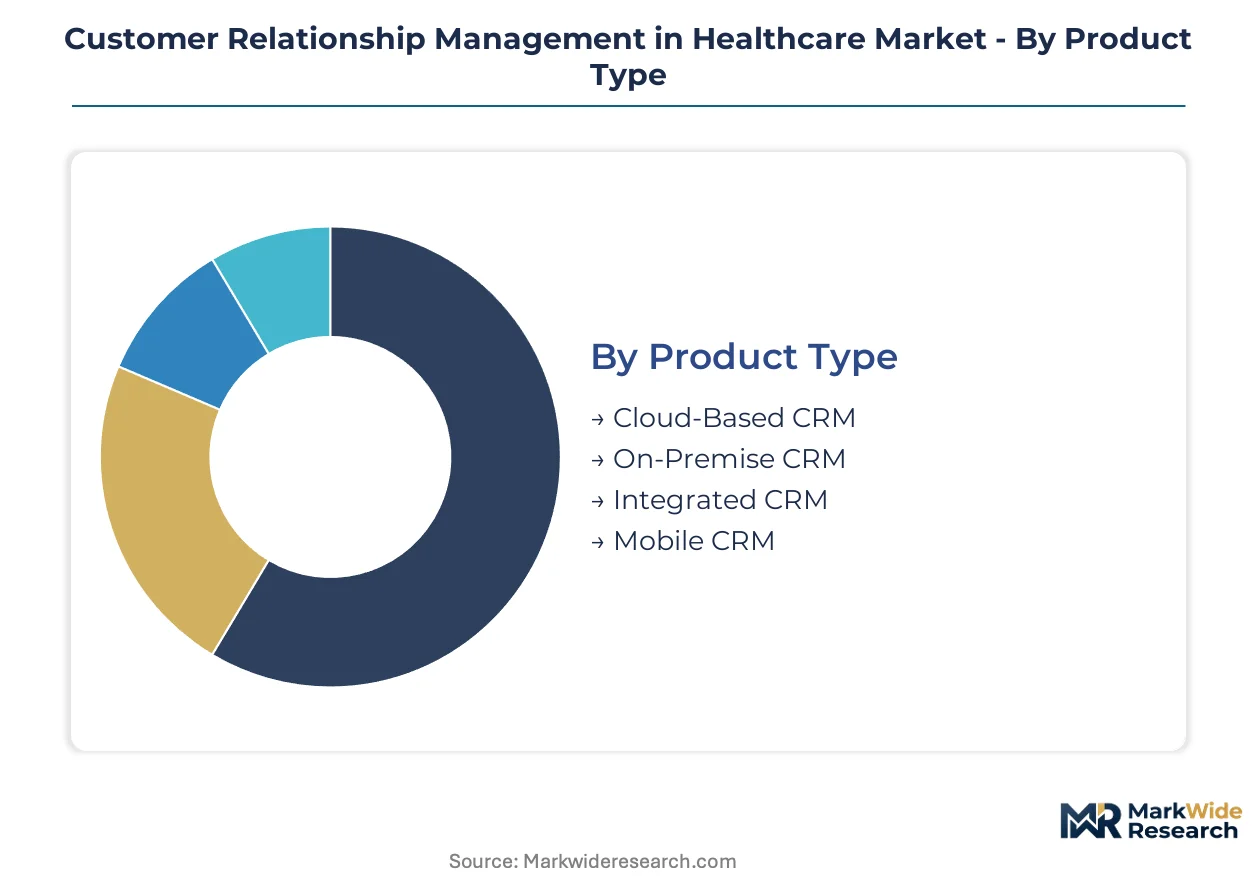
Healthcare CRM segmentation reflects divergent risk tolerances for data sovereignty, cloud dependency, and AI governance. Procurement patterns split between institutions prioritizing capital flexibility versus those demanding architectural control over protected health information.
Product Type:
Use-case spectrum spans episodic patient outreach through longitudinal care coordination, with infrastructure decisions tethered to HIPAA audit readiness and disaster recovery mandates.
- Cloud-Based CRM:Multi-tenant architectures with automatic security patching attract nonprofit hospital networks lacking dedicated infrastructure teams. United States health systems in tornado-prone corridors prioritize geographic redundancy over on-premise control. Federal interoperability incentive payments accelerate subscription procurement over capital-intensive alternatives.
- On-Premise CRM:Database sovereignty satisfies academic medical centers managing dual-use research datasets alongside clinical operations. Oracle and Microsoft SQL Server deployments dominate where institutional review boards impose additional access logging beyond HIPAA baseline requirements. Implementation timelines stretch 18-24 months due to custom firewall configurations.
- Integrated CRM:Native HL7 FHIR connectivity with Epic and Cerner EHRs reduces middleware development burden for mid-sized regional networks.
- Mobile CRM:Pharmacy refill management and home health scheduling drive adoption where clinical workflow interruption liability remains minimal.
Established volume favors Cloud-Based CRM; emerging adoption favors Integrated CRM.
End User:
Customer type determines feature prioritization, with acute care settings demanding real-time EHR synchronization while ambulatory environments emphasize patient self-service portals.
- Hospitals:Enterprise deployments coordinate discharge planning, readmission risk scoring, and philanthropic donor management through unified patient master indices. Magnet-designated facilities in the United States embed CRM access into nursing workflow stations. AI-enabled no-show prediction modules justify premium licensing tiers.
- Clinics:Federally qualified health centers leverage CRM for sliding-fee eligibility verification and care gap closure reporting to HRSA. Rural sites with unreliable broadband depend on offline-synchronized mobile clients.
- Pharmacies:Medication adherence programs and prior authorization tracking dominate CRM utilization patterns.
- Healthcare Providers:Individual practitioner adoption remains constrained by EHR vendor bundling strategies.
Procurement concentration tilts toward Hospitals; steepest expansion trajectory appears in Clinics.
Deployment:
Infrastructure topology selection hinges on data residency requirements, with hybrid configurations gaining traction among systems navigating state-level privacy supplements.
- Private Cloud:Single-tenant environments with dedicated encryption key management satisfy Texas and California state privacy laws exceeding federal HIPAA floors. Catholic health systems mandate private cloud for ethical and religious directives compliance documentation.
- Public Cloud:AWS GovCloud and Azure Government regions carry FedRAMP authorization reducing procurement friction for Veterans Health Administration facilities.
- Hybrid Cloud:PHI remains on-premise while analytics workloads burst to public infrastructure.
- Local Server:Critical access hospitals with fewer than 25 beds maintain legacy installations due to bond financing constraints.
Current procurement favors Private Cloud; architectural experimentation centers on Hybrid Cloud.
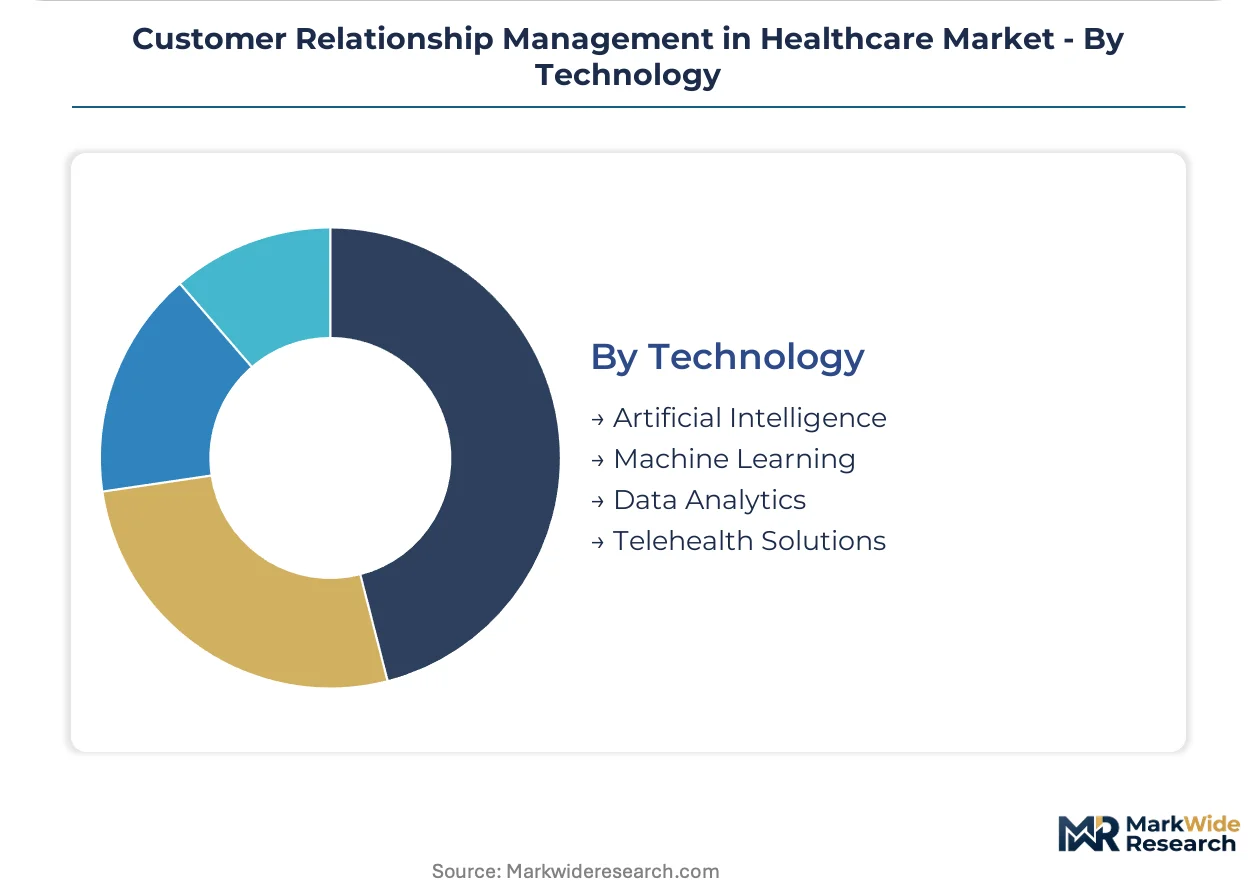
Technology:
Capability layering determines competitive differentiation, with native AI embedding displacing bolt-on analytics modules across enterprise RFP evaluations.
- Artificial Intelligence:Generative AI for ambient clinical documentation and care plan drafting attracts venture investment, though FDA software-as-medical-device classification uncertainty delays commercial rollout. United States pilot programs at Mayo Clinic and Kaiser Permanente test real-time encounter summarization.
- Machine Learning:Predictive models for patient no-show reduction deliver measurable ROI within 12-month implementation horizons, anchoring procurement justification for community health centers.
- Data Analytics:Population health dashboards aggregate claims and clinical data for ACO quality reporting.
- Telehealth Solutions:CRM-embedded video scheduling and asynchronous messaging extend patient relationship continuity beyond physical encounters.
Revenue concentration clusters around Machine Learning; R&D investment flows toward Artificial Intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA enforcement by the Office for Civil Rights anchors procurement velocity in the United States, while GDPR and the EU AI Act reshape European deployment architectures. Cloud infrastructure concentration and data sovereignty requirements fragment regional adoption patterns.
United States
Health system consolidation into regional integrated delivery networks drives enterprise CRM procurement across multi-facility footprints. Federal interoperability incentive payments accelerate subscription-based cloud deployments over capital-intensive on-premise alternatives. The Mayo Clinic in Minnesota and Kaiser Permanente in California pilot generative AI for ambient clinical documentation within CRM workflows.
Germany
Academic medical centers demand database sovereignty for dual-use research datasets alongside clinical operations, favoring on-premise Oracle and Microsoft SQL Server configurations. The BfArM and LfDI enforce GDPR-plus-German state privacy supplements exceeding federal baselines. The Berlin-Brandenburg health cluster maintains extended implementation timelines for custom firewall configurations.
United Kingdom
NHS England's integrated care system reforms consolidate patient relationship platforms across former clinical commissioning group boundaries. The UK Information Commissioner's Office enforces GDPR cross-border data transfer restrictions for multinational health system clients. London-based trusts prioritize native HL7 FHIR connectivity with Epic deployments.
Japan
PMDA oversight of software-as-medical-device classifications intersects with pharmaceutical industry CRM requirements for clinical trial patient management. METI promotes AI-enabled care coordination platforms through regulatory sandbox programs. The Kanto region around Tokyo concentrates health IT vendor development for export-oriented pharmaceutical services.
India
CDSCO guidance on clinical decision support algorithms creates compliance uncertainty for CRM vendors serving medical device manufacturers and hospital chains. The NITI Aayog's National Health Stack initiative promotes interoperable patient data exchange standards. Bangalore and Hyderabad health IT clusters develop middleware for HL7 FHIR integration with legacy hospital information systems.
Customer Relationship Management in Healthcare Market Competitive Landscape
Platform-native specialists and cloud hyperscaler extensions split the market between workflow-embedded CRM and infrastructure-anchored deployments. Consolidation pressure from health system procurement favors vendors with pre-certified HIPAA architectures and native EHR integration. Three archetypes dominate: enterprise software incumbents with healthcare verticals, cloud-native challengers with API-first architectures, and EHR vendors bundling relationship management modules. Competitive moves center on M&A for FHIR integration talent and strategic partnerships with federal-authorized cloud providers.
Within the enterprise software tier, Salesforce Health Cloud and Microsoft Dynamics 365 occupy positions shaped by their parent cloud infrastructure dominance, while Oracle Corporation exemplifies database-centric deployment archetypes favored by sovereignty-conscious institutions. These three entities represent distinct strategic postures: API ecosystem breadth, backward integration into compliance frameworks, and on-premise architectural control.
| Leading Market Players |
|---|
| Salesforce Health Cloud |
| Microsoft Dynamics 365 |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| HubSpot |
| Infor Inc. |
| Cerner Corporation |
| Athenahealth |
| Others |
Pricing and Supply Chain Analysis
Bangalore and Hyderabad health IT clusters anchor global CRM development capacity, with their talent density in HL7 FHIR integration and HIPAA compliance architecture translating directly into pricing power for specialized implementation services. Cloud hyperscaler concentration in United States federal-authorized regions compresses infrastructure costs while elevating professional services premiums for scarce health IT labor.
Pricing Analysis
United States cloud deployments command 15-25% premiums over equivalent European configurations due to FedRAMP authorization overhead and HIPAA audit trail requirements. Subscription SaaS-tiered structures dominate procurement, with pricing stratifying across enterprise, mid-market, and community health center tiers based on AI module depth and EHR integration complexity. Cost compression in mid-market segments is intensifying because health systems consolidate vendor relationships and demand volume discounts for multi-facility footprints. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers with research funding demonstrate lowest sensitivity to premium AI-enabled tiers.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk calculations for hardware-dependent on-premise deployments, though pure software CRM remains insulated. Development capacity concentrates in India, United States, and Germany, with Indian clusters feeding from engineering talent pipelines and German centers anchoring GDPR-compliant architectural design. Raw material dependencies span cloud compute instances from AWS GovCloud and Azure Government, encryption key management hardware, and specialized health IT labor for FHIR integration. Single-source vulnerability concentrates around three hyperscalers holding federal healthcare authorizations. Distribution runs through direct enterprise sales teams, systems integrators like Accenture and Deloitte, and emerging cloud-native channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity across behavioral health, rural health networks, and EU AI Act compliance services as health system consolidation simultaneously elevates platform requirements and displaces point solutions. The demand-side shift toward AI-native care coordination rather than bolt-on analytics fragments procurement criteria and opens niches for specialized vendors.
For Market Incumbents: Insulate enterprise positions through backward integration into FHIR integration talent pools and pre-certified HIPAA architectures that compress rival implementation timelines. Defend against cloud-native challengers by embedding generative AI ambient documentation natively rather than through partnership modules. Priority lever rests with exclusive hospital system partnerships that lock in longitudinal patient data flows across acquisition targets.
For New Entrants and Emerging Players: Build out specialized workflow tools for substance use disorder clinics and community mental health centers where enterprise CRM vendors maintain thin presence. Target federally qualified health centers with offline-synchronized mobile clients addressing broadband reliability gaps. Go-to-market angle centers on HRSA reporting automation and sliding-fee eligibility verification bundled below incumbent pricing floors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with native AI embedding and established EHR integration rather than infrastructure-anchored deployments. Long-term viability over the next decade hinges on regulatory technology capabilities spanning HIPAA, GDPR, and EU AI Act compliance. Acquisition target archetype: specialized FHIR integration boutiques with health system reference contracts. Signal to watch: FDA software-as-medical-device classification clarity for clinical decision support algorithms embedded in CRM workflows.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Integration Talent Acquisition | Scarce HL7 FHIR specialists compress implementation timelines and anchor competitive differentiation. |
| FedRAMP-Authorized Cloud Partnership | AWS GovCloud and Azure Government certification reduces procurement friction for Veterans Health Administration facilities. |
| EU AI Act Compliance Architecture | German academic medical centers demand GDPR-plus-AI-Act configurations exceeding baseline HIPAA requirements. |
| Behavioral Health Workflow Specialization | Substance use disorder clinics remain underserved by enterprise CRM vendors, presenting greenfield deployment potential. |
| Generative AI Ambient Documentation | Mayo Clinic and Kaiser Permanente pilots test real-time encounter summarization within CRM workflows. |
Research Methodology
Desk research of FDA 510(k) filings, CMS Medicare reimbursement databases, and hospital procurement contract disclosures preceded structured interviews with health system CIOs, HL7 FHIR integration specialists, HIPAA compliance architects, and GPO contracts managers. Primary fieldwork captured deployment timelines, vendor selection criteria, and AI module adoption patterns across United States integrated delivery networks. Secondary validation drew from ONC information blocking rule enforcement records, Office for Civil Rights breach notification archives, and hyperscaler healthcare vertical revenue disclosures. Bottom-up sizing of cloud subscription volumes triangulated against top-down health system IT budget allocations.
Assumptions held interoperability incentive payment continuity and HIPAA audit frequency at observed levels, while varying AI regulatory classification timelines and rural hospital consolidation velocity across sensitivity scenarios. Segmentation modeling spanned deployment topology, end-user facility type, technology capability layer, and regional regulatory framework. CAGRs derived from logarithmic trend fitting of subscription revenue trajectories, cross-referenced against EHR vendor bundling pressure and health system capital expenditure cycles. Forecast inputs included federal cloud authorization expansion rates and EU AI Act enforcement granularity.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers into clinical workflow software would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Software Market
Customer Relationship Management (CRM)
APAC Loyalty Management Market
Customer Relationship Management (CRM)
Online CRM Software Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Android CRM Software Market