
 Cloud CRM Market | 2026-2036
Cloud CRM Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud CRM Market Analysis
Mid-market enterprises are rotating toward cloud CRM platforms as their primary buyer archetype, displacing traditional large-enterprise dominance in contract value. Salesforce leads in AI-embedded workflow automation across North America. Microsoft Dynamics 365 anchors its position through deep integration with enterprise productivity stacks. HubSpot differentiates by specializing in inbound marketing automation for scaling businesses.
Cloud CRM denotes software delivered through internet-hosted infrastructure that centralizes customer data, automates sales pipelines, and enables real-time analytics across distributed teams, typically operating on multi-tenant architectures with API-first connectivity. The platform serves commercial organizations seeking to unify prospect engagement, transaction history, and service interactions into actionable intelligence. Public cloud deployment captures the largest installed base due to lower capital requirements and faster implementation cycles, while hybrid cloud configurations are expanding fastest among regulated industries requiring data residency controls. Sales automation retains the deepest margin pools, though analytics modules are accelerating as buyers prioritize predictive customer intelligence over retrospective reporting.
The EU AI Act and GDPR impose algorithmic transparency and data localization requirements that constrain cross-border data flows and elevate compliance costs for vendors serving European enterprises. The SEC and state-level privacy frameworks in the United States add overlapping disclosure obligations that fragment product roadmaps. Stakeholders must monitor how divergent regulatory timelines for AI governance reshape vendor certification priorities and customer procurement criteria.
Market Dynamics
Mid-market retailers are displacing large enterprises as the primary contract archetype, forcing vendors to reconfigure pricing architectures and implementation timelines around faster deployment cycles and lower IT staffing thresholds.
Growth Catalysts
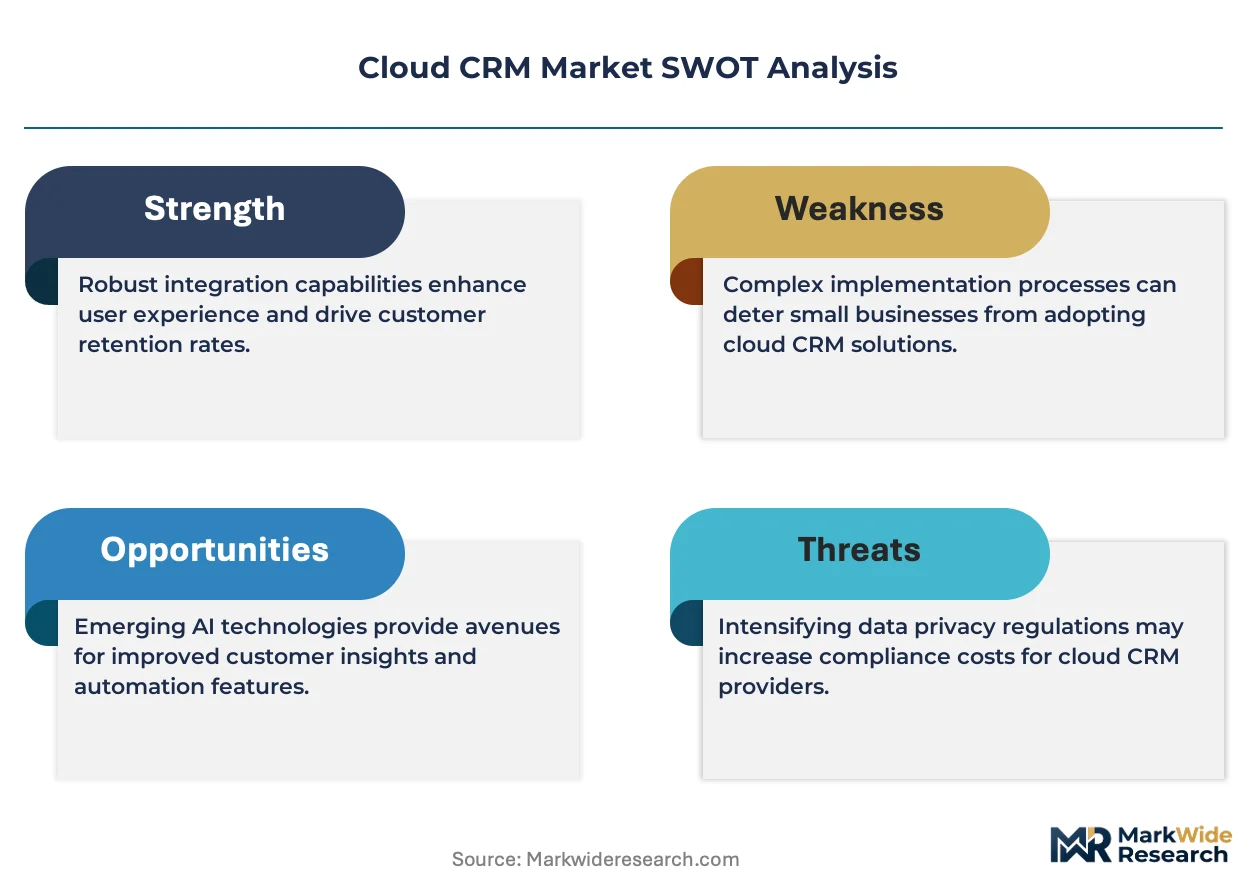
- EU AI Act compliance mandates:European enterprises must demonstrate algorithmic transparency in customer-facing automation, creating mandatory upgrade cycles for legacy on-premise installations.
- API-first connectivity standards:Universal data exchange protocols enable seamless integration with e-commerce platforms, payment processors, and logistics networks without custom middleware development.
- India's PLI scheme for IT hardware:Domestic cloud infrastructure incentives reduce latency and data sovereignty risks for enterprises serving South Asian consumer markets.
Market Restraints
- GDPR cross-border friction:Data localization requirements fragment multi-tenant architectures, forcing vendors to maintain redundant infrastructure across European member states.
- Specialized ML engineer scarcity:Talent shortages in predictive analytics and natural language processing constrain feature velocity for AI-embedded workflow modules.
- Hybrid cloud complexity:Regulated industries requiring on-premise data residency face extended implementation timelines and higher total cost of ownership versus public cloud alternatives.
Strategic Opportunities
- German Mittelstand digitization:Family-owned industrial distributors remain underpenetrated by cloud CRM platforms, presenting whitespace for verticalized solutions targeting B2B equipment sales.
- CSRD disclosure convergence:Corporate sustainability reporting mandates create demand for carbon footprint tracking modules integrated with customer transaction histories.
- Voice-to-CRM interfaces:Convergence of speech recognition APIs and mobile field sales applications enables hands-free data capture for distributed workforce segments.
Industry Challenges
- ISO 27001 certification timelines:Security management standard audits create six-to-nine month procurement delays for vendors serving financial services and healthcare verticals.
- Legacy ERP integration friction:On-premise SAP and Oracle installations require expensive custom connectors, compressing margins on mid-market deals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud CRM Market |
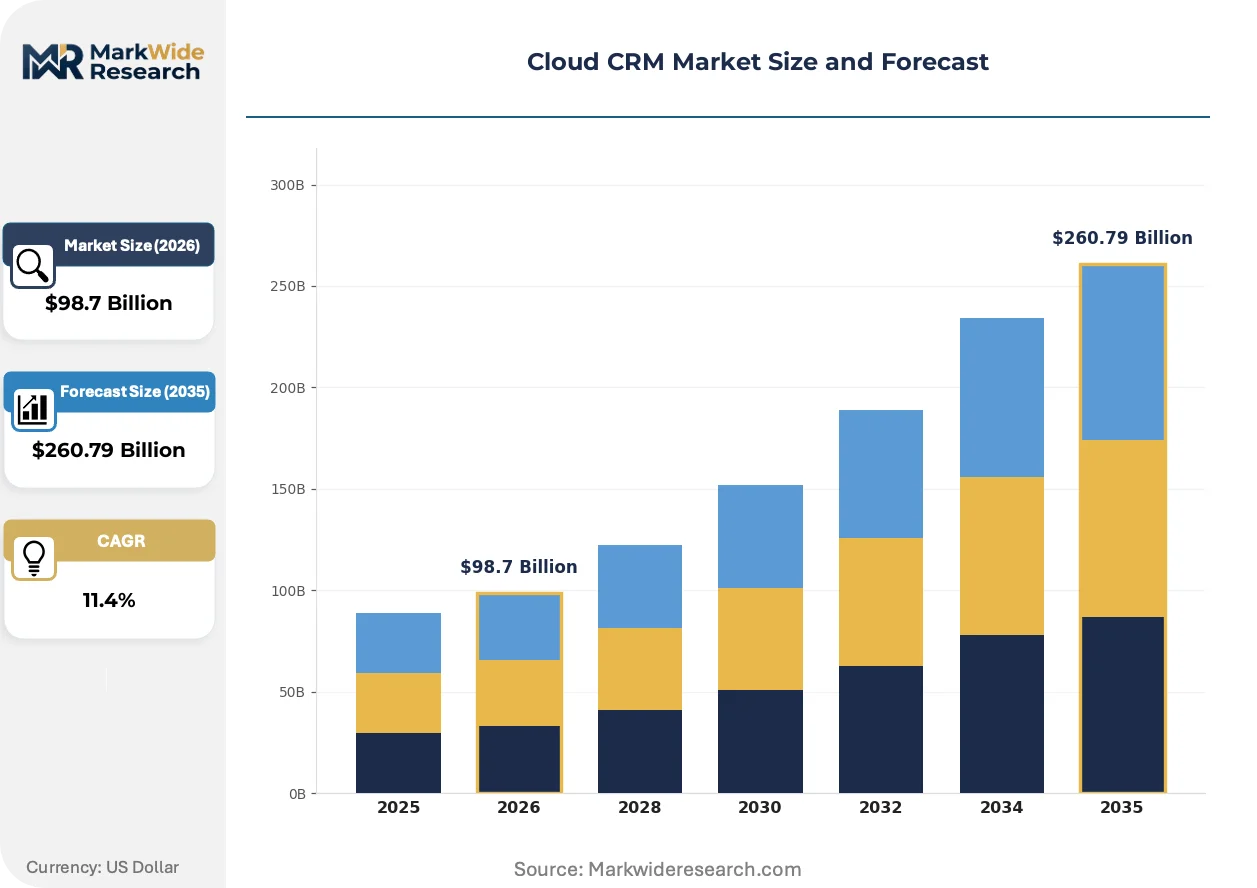
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Small Enterprises, Medium Enterprises, Large Enterprises, Startups Feature: Sales Automation, Marketing Automation, Customer Support, Analytics Service Type: Subscription, Freemium, Tiered Pricing, One-time Payment |
| Companies Covered | Salesforce, Microsoft Dynamics 365, Oracle, HubSpot, SAP, Adobe, Zoho CRM, Freshworks, Insightly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud CRM Market Emerging Trajectories
Generative AI capabilities are compressing feature development cycles and enabling natural language interfaces that bypass traditional dashboard navigation, while regulatory fragmentation forces architectural divergence across major economies.
Embedded large language models are bifurcating CRM functionality between predictive sales forecasting and autonomous customer service agents. Mid-market retailers in the United States and Germany are deploying these tools at scale, replacing manual lead scoring and tier-one support staffing. The technology is bifurcating vendor competitive positioning between automation depth and data governance transparency.
The EU AI Act's risk classification framework imposes documentation burdens on high-stakes customer profiling algorithms. Vendors must maintain technical files demonstrating human oversight mechanisms and bias mitigation protocols. Financial services deployments across France and the Netherlands face the steepest compliance adjustments, with procurement committees now requiring algorithmic impact assessments prior to contract execution.
Subscription-to-usage pricing migration is displacing seat-based licensing in enterprise renewals. Manufacturing and logistics buyers in India increasingly demand consumption metrics tied to actual customer interactions rather than prepaid user allocations. This pattern is most visible among third-party logistics providers managing seasonal demand volatility, where workforce scaling renders fixed licensing economically inefficient.
Cloud CRM Market Segmentation
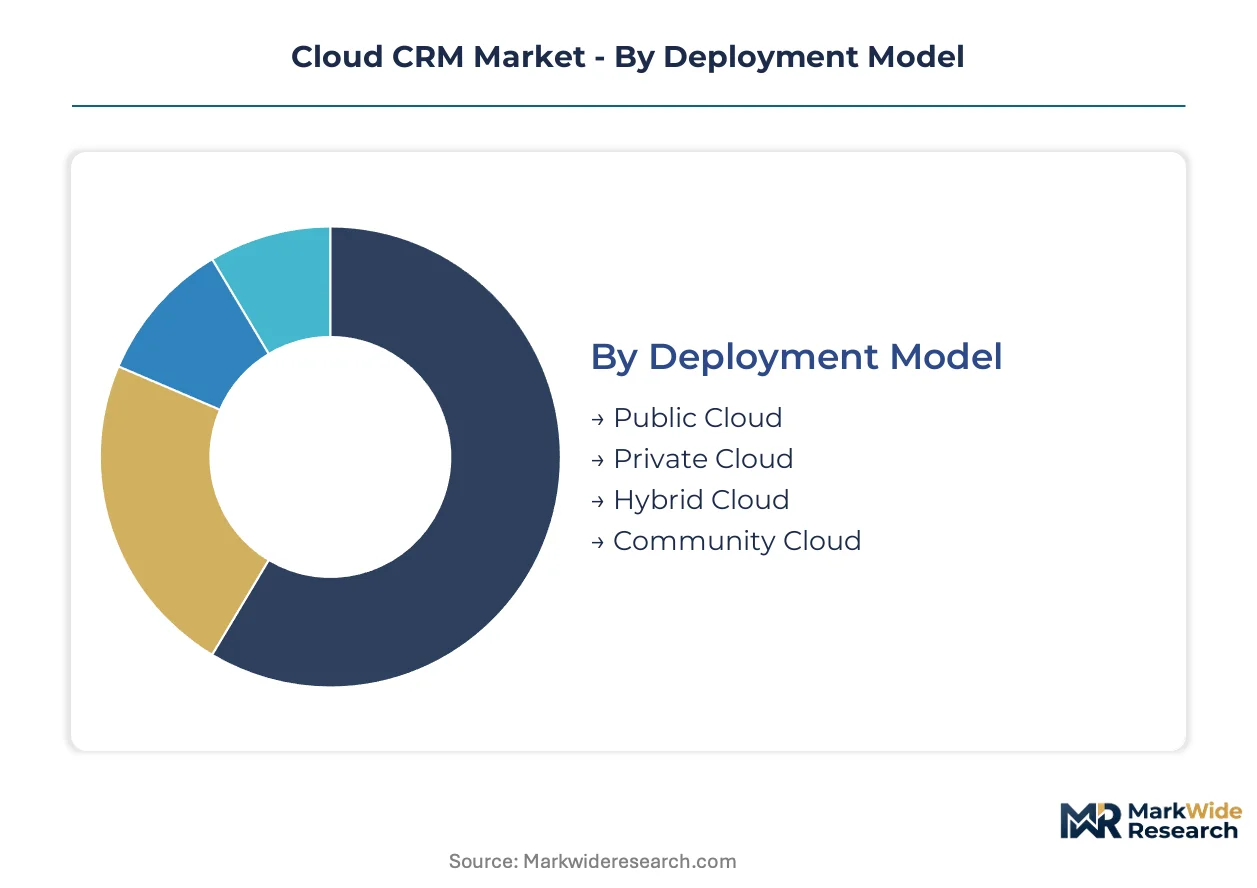
Cloud CRM segmentation reveals how deployment economics and buyer sophistication reshape vendor go-to-market strategies. Pricing architectures and feature bundling diverge sharply across enterprise maturity tiers, forcing platform providers to maintain parallel product roadmaps.
Deployment Model:
Margin pools concentrate in configurations that balance operational flexibility with compliance overhead, particularly where data residency mandates apply.
- Public Cloud:Multi-tenant infrastructure delivers the lowest capital requirements and fastest implementation cycles through shared resource pooling. Demand concentrates among mid-market retailers in the United States and Germany seeking to minimize IT staffing thresholds while scaling customer data volumes. The segment captures the deepest installed base due to subscription economics that align vendor revenue with customer expansion.
- Hybrid Cloud:Split architectures separate customer-facing automation from sensitive transaction records, enabling regulated industries to maintain on-premise data residency without sacrificing cloud-native analytics. Financial services deployments across France and the Netherlands are expanding most quickly as EU AI Act documentation requirements elevate compliance scrutiny. Extended implementation timelines compress margins relative to public alternatives.
- Private Cloud:Single-tenant dedicated infrastructure serves defense contractors and government agencies with mandatory air-gapped environments.
- Community Cloud:Shared infrastructure restricted to specific industry verticals addresses collective compliance needs among pharmaceutical distributors and healthcare networks.
The dominant share belongs to Public Cloud, while Hybrid Cloud is gaining share fastest among regulated verticals.
End User:
Procurement authority has shifted toward organizations with leaner IT functions and faster decision cycles, displacing traditional enterprise buying centers.
- Medium Enterprises:Organizations with 100-999 employees now drive the steepest expansion trajectory, rotating toward cloud CRM as their primary customer data infrastructure. These buyers prioritize API-first connectivity over custom integration development, compressing sales cycles from twelve months to under ninety days. Vendors are reconfiguring implementation timelines and pricing architectures around this archetype.
- Small Enterprises:Companies below 100 employees deploy lightweight configurations focused on pipeline visibility and basic marketing automation. India's scaling digital commerce sector generates concentrated demand as family-owned distributors modernize customer engagement practices. Freemium-to-paid conversion rates determine vendor unit economics in this tier.
- Large Enterprises:Complex procurement committees and legacy ERP integration requirements extend sales cycles and elevate professional services dependency.
- Startups:Venture-backed technology companies prioritize growth-stage scalability over feature depth, favoring platforms with robust ecosystem marketplaces.
Medium Enterprises command the largest addressable expansion, with Small Enterprises climbing fastest as digitization penetrates traditional trade sectors.
Feature:
Buyer prioritization has shifted from retrospective reporting toward predictive intelligence, reshaping R&D allocation across module development.
- Sales Automation:Pipeline management, lead scoring, and opportunity forecasting retain the deepest margin pools through established buyer willingness to pay for revenue acceleration tools. Manufacturing and logistics buyers in India increasingly demand consumption-based pricing tied to actual customer interactions rather than prepaid user allocations. The segment anchors vendor profitability through mature feature sets and proven ROI documentation.
- Analytics:Predictive customer intelligence modules are expanding most quickly as mid-market retailers prioritize behavioral forecasting over historical dashboards. Embedded large language models enable natural language interfaces that bypass traditional navigation, compressing time-to-insight for distributed sales teams. EU AI Act algorithmic transparency requirements constrain cross-border deployment architectures.
- Marketing Automation:Campaign orchestration and lead nurturing workflows serve inbound-centric scaling businesses with content personalization requirements.
- Customer Support:Case management and knowledge base functionality address post-sale retention economics for subscription-heavy business models.
Sales Automation maintains the revenue concentration, though Analytics is closing the gap fastest as AI-embedded capabilities mature.
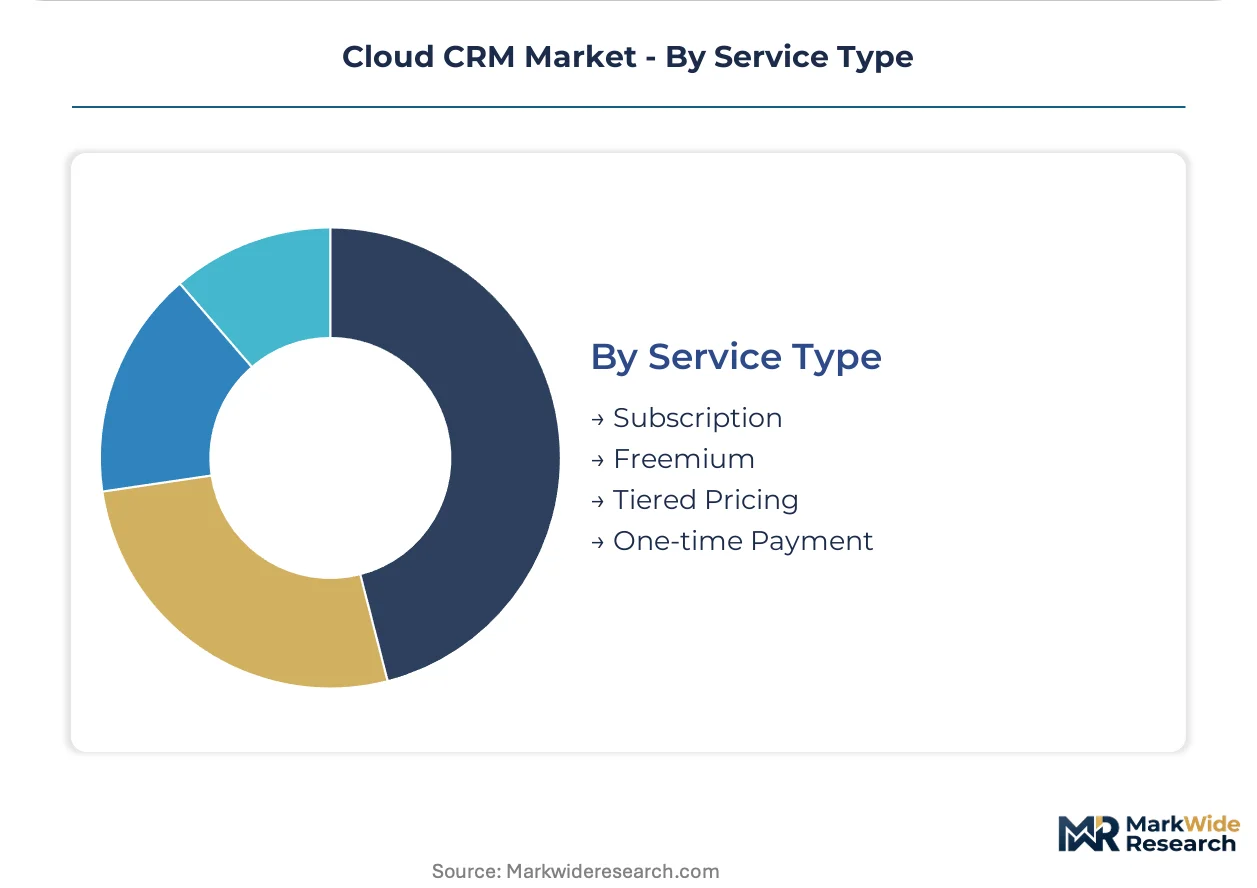
Service Type:
Pricing model selection correlates directly with customer cash flow predictability and workforce scaling patterns.
- Subscription:Recurring annual or monthly contracts dominate enterprise renewals, aligning vendor revenue visibility with customer operational budgeting. Third-party logistics providers managing seasonal demand volatility favor this structure for its workforce scaling flexibility. The model captures the largest revenue share through established procurement comfort.
- Tiered Pricing:Three-level differentiation across premium, standard, and economy configurations enables self-service segmentation without sales intervention. Mid-market retailers in the United States and Germany deploy these tools at scale, matching feature access to organizational maturity. This structure is expanding most quickly as product-led growth strategies proliferate.
- Freemium:Limited-feature entry tiers drive user acquisition for subsequent conversion to paid functionality.
- One-time Payment:Perpetual licensing persists among public sector entities with capital budget constraints and multi-year appropriation cycles.
Subscription retains the dominant position, while Tiered Pricing is climbing fastest as self-service procurement patterns mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DE-CIX internet exchange in Frankfurt anchors European data routing, underwriting Germany's centrality in cloud CRM infrastructure serving Mittelstand distributors.
United States
Mid-market retailers in Texas and Florida are deploying AI-embedded sales automation at scale. SEC disclosure requirements for algorithmic decision-making elevate procurement scrutiny. Chicago's logistics corridor drives concentrated demand among third-party distributors seeking consumption-based pricing.
Germany
Family-owned industrial equipment distributors across Baden-Württemberg and Bavaria represent underpenetrated whitespace for verticalized solutions. EU AI Act risk classification mandates documentation for customer-facing automation. The Rhine-Ruhr manufacturing belt generates clustered demand for predictive analytics modules.
India
PLI scheme incentives for domestic cloud infrastructure reduce latency risks for enterprises serving South Asian consumer markets. RBI data localization guidelines constrain cross-border architecture designs. Bangalore's technology corridor hosts scaling SaaS vendors targeting family-owned trade distributors.
France
Financial services deployments in Paris and Lyon face steep EU AI Act compliance adjustments for high-stakes customer profiling. CNIL enforcement of GDPR cross-border friction elevates multi-tenant infrastructure costs. The Île-de-France banking cluster demands algorithmic impact assessments prior to contract execution.
United Kingdom
Post-Brexit divergence from EU AI governance creates parallel certification tracks for vendors serving London's fintech corridor. FCA consumer duty rules reshape disclosure obligations for automated customer engagement. Manchester's scaling logistics sector drives hybrid cloud adoption for data residency controls.
Cloud CRM Market Vendor Landscape
Listed leaders compete with private specialists across AI-embedded workflow automation, creating a tiered structure where scale-driven platforms and verticalized challengers coexist. Consolidation concentrates around productivity-suite anchors and standalone automation specialists. Three archetypes dominate: ecosystem-integrated incumbents, inbound-marketing pure-plays, and emerging voice-interface disruptors. M&A activity targets API-first connectivity assets, while geographic expansion focuses on German Mittelstand and Indian mid-market penetration.
Within the ecosystem-integrated tier, Salesforce and Microsoft represent archetypal positioning around workflow depth versus productivity-stack anchoring. HubSpot exemplifies the inbound-specialist model targeting scaling businesses with marketing-automation-first land strategies. Zoho occupies a position bridging mid-market affordability with emerging-market localization, particularly across Indian family-owned distributors.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft Dynamics 365 |
| Oracle |
| HubSpot |
| SAP |
| Adobe |
| Zoho CRM |
| Freshworks |
| Insightly |
| Others |
Supply Flow & Price Mechanics
Multi-tenant infrastructure scale economies in public cloud deployments compress marginal delivery costs below on-premise alternatives, concentrating vendor margin pools among hyperscale platform operators while forcing price floors downward for mid-market configurations. This scale dynamic simultaneously elevates compliance overhead for hybrid architectures, bifurcating pricing power between commodity SaaS tiers and premium residency-controlled offerings.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels, with consumption-based metrics displacing prepaid seat allocations among logistics buyers managing seasonal workforce scaling. Price differentiation rests on API integration depth and EU AI Act algorithmic transparency certification grades. Cost compression in standard tiers intensifies because Microsoft's productivity-stack bundling and Salesforce's ecosystem density force standalone vendors toward feature specialization. Small enterprises in India's digitizing trade sectors exhibit highest price sensitivity, while German Mittelstand distributors demonstrate lowest sensitivity due to compliance-driven procurement criteria.
Supply Chain Analysis
Inventory and lead-time compression in API-first connectivity modules has shortened implementation cycles from twelve months to under ninety days for mid-market retailers. Cloud infrastructure supply concentrates in the United States, Germany, and India, with hyperscale data center capacity expansion in Frankfurt and Bangalore reducing latency for regional deployments. Raw material dependencies center on compute silicon, fiber optic transmission hardware, and renewable energy procurement for carbon-neutral hosting commitments. Single-source vulnerability in specialized ML engineering talent constrains feature velocity for AI-embedded modules. Distribution runs through direct vendor sales organizations, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI capabilities are compressing feature development cycles across cloud CRM platforms, while EU AI Act algorithmic transparency mandates impose documentation burdens that favor incumbent compliance infrastructure over emerging entrants.
For Market Incumbents: Secure API-first connectivity asset acquisitions to defend integration density against Microsoft's productivity-stack anchoring and Salesforce's workflow automation depth. ISO 27001 certification investment in financial services verticals creates procurement gatekeeping advantages. Vertical integration into voice-to-CRM interface development addresses field sales workforce segments before specialist disruptors establish category ownership. For New Entrants and Emerging Players: GDPR compliance fast-tracks for algorithmic impact assessment documentation open white-space among French and Dutch financial services deployments requiring EU AI Act adherence. German Mittelstand industrial equipment distributors remain underpenetrated by verticalized B2B sales solutions. Product-led growth strategies with tiered self-service pricing enable land-and-expand motions without enterprise sales overhead. For Investors and Strategic Acquirers: Mid-market SaaS specialists with established API marketplaces and regional localization capabilities in India represent compelling acquisition targets as hyperscalers seek geographic penetration without organic buildout. Long-term viability frames around 5-10 year regulatory divergence between EU AI governance and US state-level privacy fragmentation. Monitor SEC algorithmic disclosure rulemaking timelines as inflection indicators for compliance-tech vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft's productivity-stack anchoring forces ecosystem density investments from standalone vendors. |
| Acquisition of Specialist Firm | API-first connectivity assets command premium valuations as integration complexity elevates switching costs. |
| Geographic Expansion | German Mittelstand penetration requires verticalized solutions for family-owned industrial equipment distributors. |
| Product Launch | Voice-to-CRM interfaces enable hands-free data capture for distributed field sales workforces. |
| Strategic Partnership | Hyperscaler marketplace listings reduce customer acquisition costs for mid-market scaling businesses. |
Methodological Framework
Operator-level perspectives from CRM platform engineers, IT procurement officers at mid-market retailers, systems integration specialists, and compliance officers at financial services firms anchored the qualitative base. Primary interview findings triangulated against SEC filings from listed vendors, EU AI Act implementation guidance documents, RBI data localization circulars, and hyperscaler capex disclosure reports. Bottom-up deployment model sizing and top-down macroeconomic anchoring converged on segment-level estimates.
Sensitivity analysis across deployment model, organization size tier, vertical industry, and regional regulatory cluster framed the analytical approach over the projection horizon. CAGRs derived from segment-level adoption curves, pricing migration patterns, and compliance-driven upgrade cycle timing. Forecast inputs incorporated ML engineer talent availability indices, cloud infrastructure capacity expansion announcements, and EU member state AI Act enforcement variance.
Decision-makers should treat outputs as directional under sustained mid-market retailer adoption velocity and stable regulatory enforcement timelines; material deviation in AI governance implementation pace would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Global Contact Center Solution Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Ipad CRM Market
Customer Relationship Management (CRM)
CRM Analytics Market
Customer Relationship Management (CRM)
Contact Center Software Market
Customer Relationship Management (CRM)
Complaint Management Software Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Europe Cloud CRM Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Spending in Digital Customer Experience and Engagement Solutions Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market