
 Global Customer Success Platforms Market | 2026-2036
Global Customer Success Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Success Platforms Market Foresight
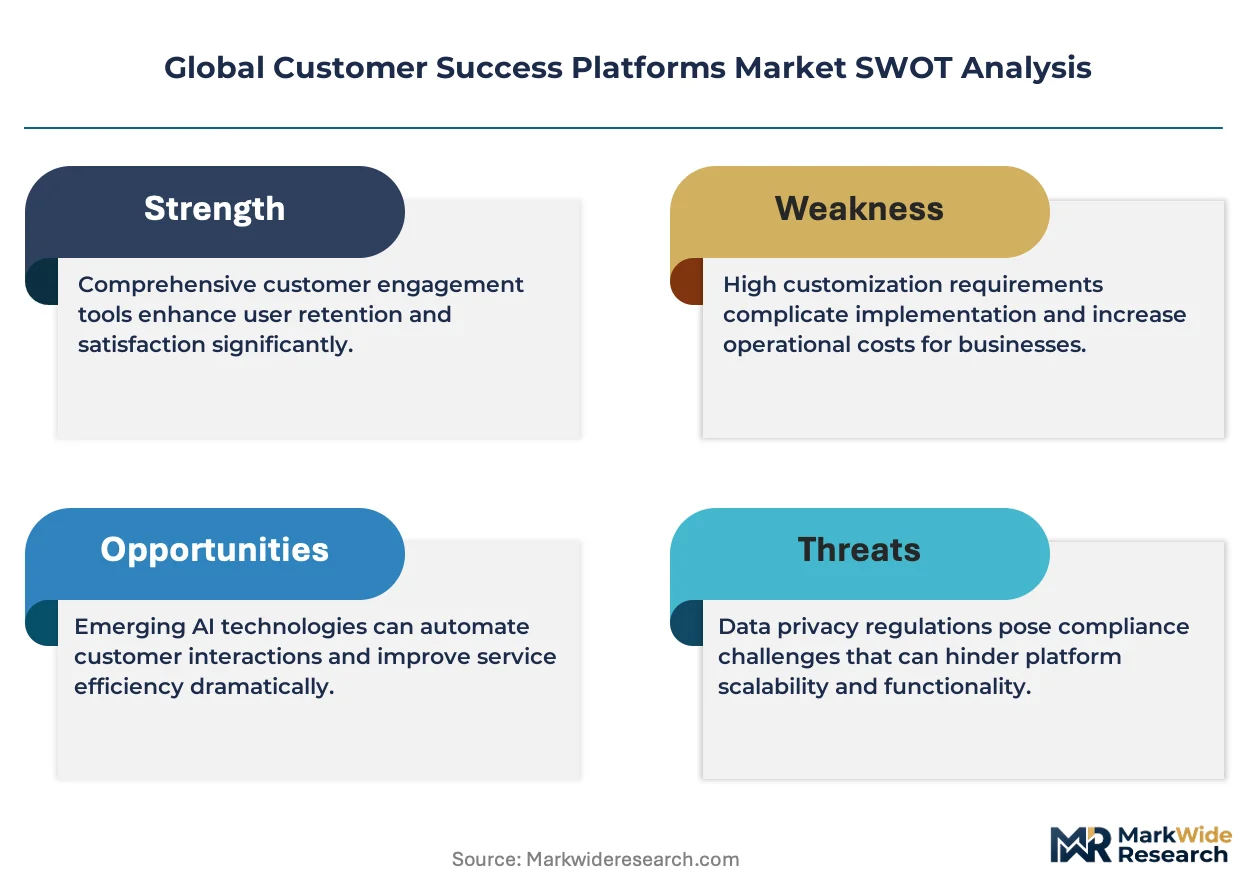
GDPR enforcement is consolidating the cost-of-entry calculus for customer success platforms serving European accounts. Salesforce leverages its native CRM data architecture to sustain platform stickiness across enterprise accounts. Gainsight specializes in health-scoring methodologies that anchor its differentiation against broader-suite competitors. HubSpot competes by extending freemium onboarding tools that lower adoption barriers for mid-market SaaS providers.
Customer success platforms are software systems that aggregate telemetry, usage analytics, and engagement signals to predict retention risk and guide expansion revenue tactics, typically processing event streams exceeding millions of data points per account daily. Their primary commercial purpose is to operationalize subscription economics by flagging churn propensity and automating intervention workflows. Cloud-based deployment leads solution delivery by eliminating infrastructure overhead and enabling real-time API integrations with CRM and billing stacks. Customer analytics and revenue optimization segments command the deepest margin pools because buyers treat these capabilities as directly tied to net revenue retention outcomes. Risk management functionality is maturing fastest as vendors embed predictive models trained on cross-portfolio benchmarks.
The EU AI Act and GDPR jointly constrain how platforms train models on customer behavioral data, forcing vendors to architect consent-aware inference pipelines or risk exclusion from European procurement cycles. The SEC's disclosure requirements for SaaS metrics indirectly pressure US-listed platform vendors to demonstrate measurable customer outcomes in sales narratives. ISO 27001 certification operates as a de facto market-access threshold for enterprise buyers conducting security reviews. Stakeholders must weigh whether to build compliant AI-native features in-house or absorb the integration cost of third-party governance tools.
Market Dynamics
The EU AI Act is forcing vendors to re-architect inference pipelines around consent-aware data flows, while SaaS buyers simultaneously demand predictive accuracy that requires behavioral training data. This regulatory-technical tension defines current competitive positioning.
Growth Catalysts
- GDPR enforcement maturation:European enterprise procurement now treats ISO 27001 and GDPR Article 35 compliance as non-negotiable gatekeepers, filtering vendor pools and concentrating spend among certified platforms.
- Revenue operations consolidation:Mid-market SaaS providers are collapsing silos between sales, support, and success functions, creating demand for unified telemetry layers that span CRM, billing, and product analytics.
- Net revenue retention benchmarking:The SEC's disclosure requirements for SaaS metrics are elevating customer success outcomes to board-level visibility, accelerating platform procurement cycles.
Market Restraints
- Cross-border data friction:The EU AI Act's prohibitions on certain automated decision-making systems create architectural complexity for vendors serving both European and non-European accounts from shared infrastructure.
- Model training cost inflation:Consent-aware data pipelines require redundant storage and processing overhead, compressing gross margins for AI-native feature development.
- Talent scarcity:The intersection of machine learning engineering, privacy law, and B2B SaaS domain expertise concentrates in San Francisco, Seattle, and Berlin, inflating compensation costs.
Strategic Opportunities
- India's SaaS ecosystem:Bangalore and Hyderabad are incubating mid-market software exporters with limited in-house customer success infrastructure, creating whitespace for cloud-deployed platform adoption.
- Embedded finance convergence:The integration of usage-based billing with payment processing and lending products is electrifying demand for platforms that correlate product telemetry with revenue events.
- CSRD reporting mandates:European corporate sustainability disclosure requirements are creating new data integration opportunities between customer success platforms and ESG reporting stacks.
Industry Challenges
- Legacy CRM integration complexity:Enterprise accounts with decades-old Salesforce or SAP deployments require costly professional services to normalize data schemas for real-time health scoring.
- Cross-functional change management:Customer success platform adoption demands retraining account managers, support agents, and product teams simultaneously, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Success Platforms Market |
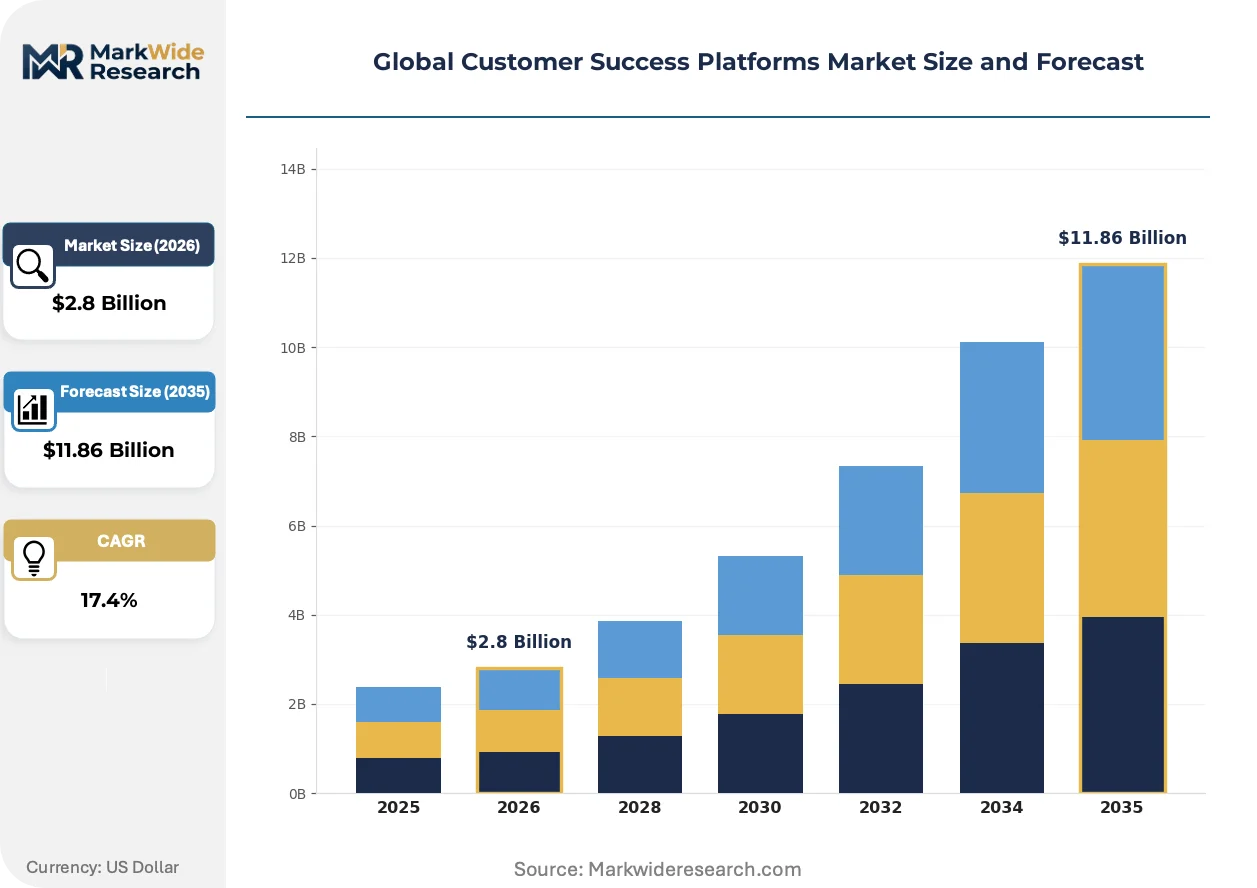
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, API-Integrated Solution Type: Customer Analytics, Engagement Management, Risk Management, Revenue Optimization, Communications Management End User Industry: Technology Providers, Telecommunications Firms, Financial Services, Education Services, Manufacturing Enterprises Customer Type: Small & Medium Businesses, Large Enterprises, Non-Profit Organizations, Government Agencies, Startups |
| Companies Covered | Gainsight, Salesforce, HubSpot, Totango, ChurnZero, Freshworks, Cisco Systems, Medallia, ClientSuccess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Success Platforms Market Shifts & Advancements
Real-time inference at the edge of customer data streams is displacing batch-processed health scores, compressing intervention windows from days to hours. Vendors are racing to embed predictive models directly within product telemetry pipelines.
Large language models fine-tuned on support ticket resolution patterns are electrifying automated intervention workflows. Enterprise SaaS providers with high ticket volumes are piloting generative response drafting and risk escalation routing. This capability compression is collapsing the historical separation between success automation and human account management.
The EU AI Act's risk classification framework for automated decision systems is forcing vendors serving European deployments to implement human-in-the-loop override mechanisms. High-risk customer churn prediction models now require documented human review protocols. German and French enterprise buyers are leading procurement preference shifts toward vendors with auditable intervention trails.
Usage-based pricing for customer success platforms is displacing traditional seat-based models among scaling SaaS providers. Buyers with variable account loads prefer contracts that scale with telemetry volume rather than headcount. This pattern is most visible among Series B and C software companies in the United States, where CFOs are scrutinizing fixed-cost commitments against recurring revenue volatility.
Global Customer Success Platforms Market Segmentation
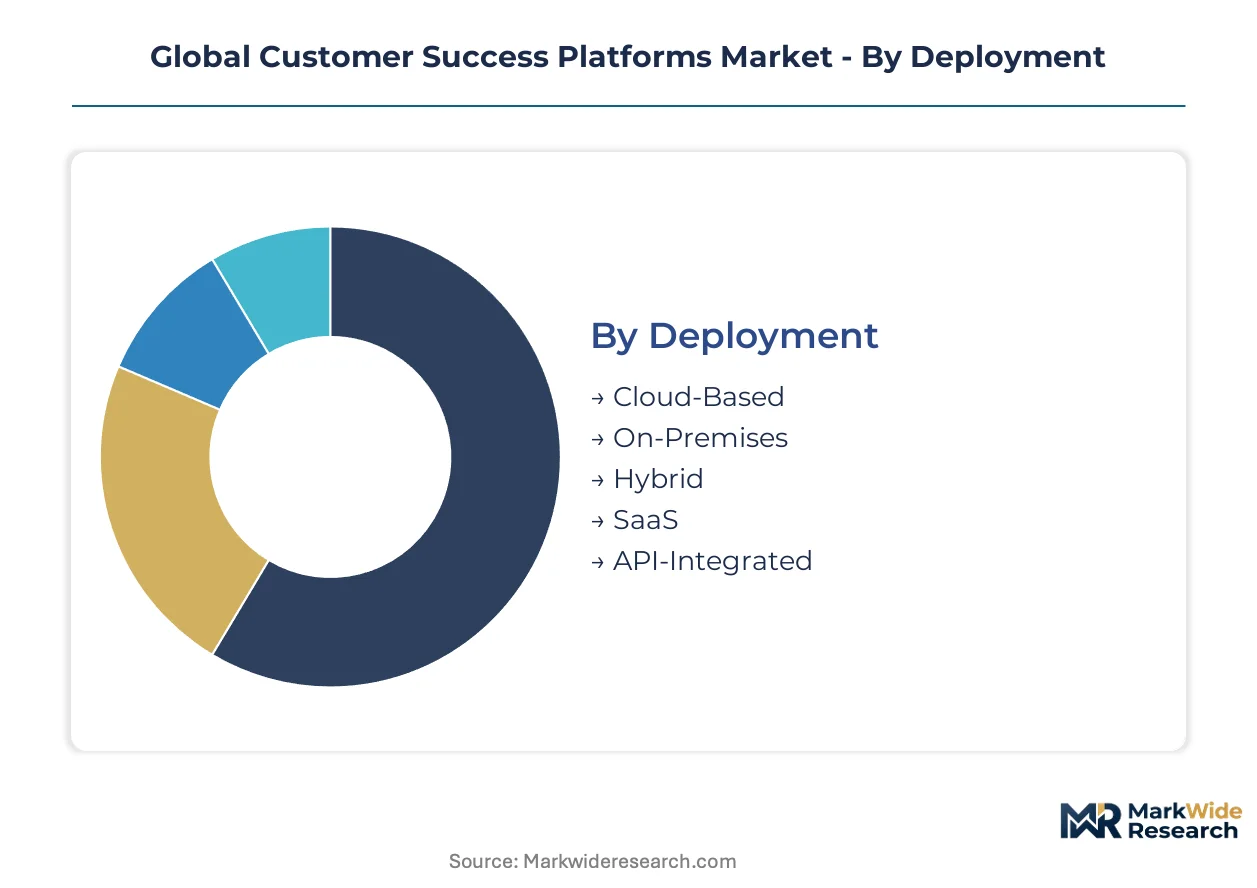
Deployment architecture determines infrastructure spend and compliance burden for customer success platforms. Solution specialization shapes margin profiles and integration complexity. End-user concentration and customer scale dictate sales motion economics and contract structuring.
Deployment:
Cloud-native architectures demand minimal upfront capital but lock in recurring subscription costs; on-premises installations require substantial hardware investment and dedicated IT staffing.
- Cloud-Based:Multi-tenant SaaS architectures eliminate server procurement and maintenance overhead. United States-based enterprise SaaS providers favor this model for rapid CRM connector deployment and elastic telemetry scaling.
- On-Premises:Single-tenant installations within client data centers address German and French banking sector data sovereignty requirements. Bundesbank-regulated financial institutions mandate air-gapped processing for customer behavioral analytics.
- Hybrid:Split architectures process sensitive inference workloads locally while pushing anonymized telemetry to cloud analytics layers.
- SaaS:Fully managed software delivery with vendor-controlled infrastructure updates and security patching.
- API-Integrated:Headless deployment models embedding health-scoring logic directly into existing product stacks.
Cloud-Based deployments absorb the bulk of installed capacity; API-Integrated models are expanding most quickly among developer-centric SaaS providers.
Solution Type:
Functional modules cluster around revenue impact intensity—analytics and optimization tools command premium pricing against operational automation layers.
- Customer Analytics:Telemetry aggregation engines processing millions of event streams per account for behavioral pattern recognition. Technology providers in California and New York treat these capabilities as directly correlated with net revenue retention outcomes.
- Revenue Optimization:Expansion opportunity scoring and upsell workflow automation. Mid-market SaaS providers prioritize this module to compress sales cycles and reduce account manager overhead.
- Engagement Management:Orchestration tools for email, in-app messaging, and meeting scheduling.
- Risk Management:Predictive churn models with escalating intervention triggers.
- Communications Management:Unified inbox and conversation threading across support channels.
Customer Analytics carries the deepest margin pool; Revenue Optimization is climbing the fastest as CFO scrutiny of SaaS unit economics intensifies.
End User Industry:
Sector-specific compliance requirements and contract value concentration shape platform configuration complexity and professional services attach rates.
- Technology Providers:Native SaaS companies with embedded product telemetry and API-first architectures. Silicon Valley and Bangalore software exporters represent the densest concentration of platform-native buyers with minimal implementation friction.
- Financial Services:Banks, insurers, and payment processors subject to SEC disclosure requirements and EU AI Act automated decision restrictions. German and French institutions lead procurement of consent-aware inference pipelines.
- Telecommunications Firms:Subscription-heavy operators with massive account bases and churn-sensitive ARPU metrics.
- Education Services:Universities and edtech platforms managing student lifecycle engagement.
- Manufacturing Enterprises:Industrial software vendors transitioning to servitized revenue models.
Technology Providers dominate current deployment volume; Financial Services is expanding most quickly under regulatory pressure for auditable customer outcomes.
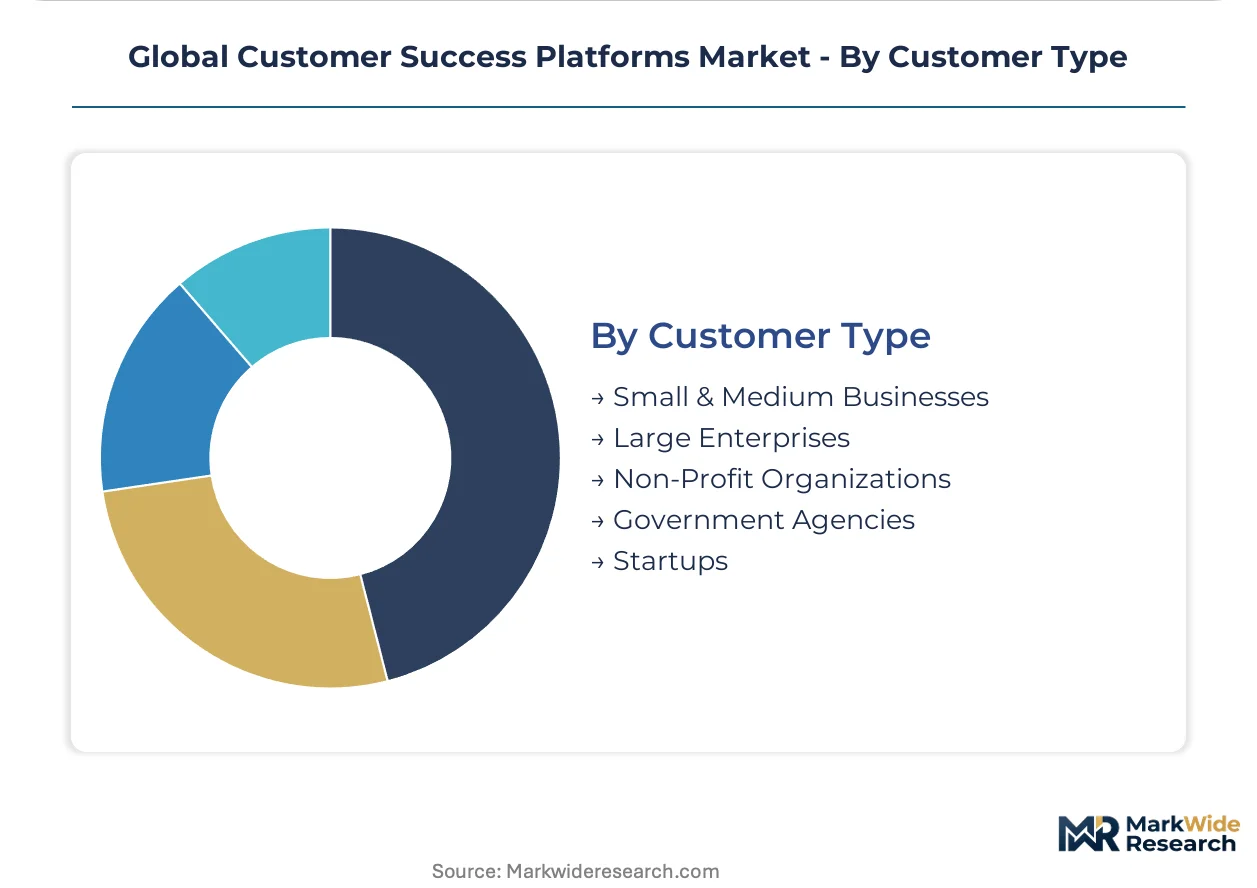
Customer Type:
Organizational scale dictates feature depth requirements, integration complexity, and willingness to absorb professional services costs.
- Large Enterprises:Multi-divisional accounts with legacy CRM estates and complex data governance requirements. Fortune 500 technology providers in the United States demand ISO 27001 certification and custom Salesforce schema normalization.
- Small & Medium Businesses:Scaling SaaS providers with limited IT headcount and preference for out-of-box configurations. Series B and C software companies prioritize usage-based pricing to align platform costs with account volume volatility.
- Startups:Seed and early-stage companies with minimal historical telemetry and freemium onboarding needs.
- Non-Profit Organizations:Donor and beneficiary management use cases with constrained procurement budgets.
- Government Agencies:Federal and state entities with FedRAMP or equivalent security authorization requirements.
Large Enterprises command the deepest contract values; Small & Medium Businesses is gaining share fastest as self-serve onboarding tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in the United States and enterprise software corridors in India are concentrating platform adoption. Germany's banking regulators and France's data protection authorities are reshaping deployment architectures. Japanese manufacturers and British SaaS exporters are expanding procurement cycles.
United States
SEC disclosure requirements for SaaS metrics are pressuring listed software providers to demonstrate measurable customer outcomes. California-based enterprise technology vendors maintain the deepest installed bases of CRM-integrated platforms. The San Francisco Bay Area and Seattle corridor concentrate vendor headquarters and machine learning engineering talent pools.
Germany
Bundesbank-regulated financial institutions mandate air-gapped processing for customer behavioral analytics under data sovereignty requirements. The EU AI Act's risk classification framework forces vendors serving German deployments to implement human-in-the-loop override mechanisms. Frankfurt and Munich host the densest concentration of banking sector procurement decision-makers.
India
Bangalore and Hyderabad are incubating mid-market software exporters with limited in-house customer success infrastructure. The country's national software regulator emphasizes data localization for financial services deployments. Series B and C SaaS companies in Karnataka and Telangana prefer usage-based platform pricing to align costs with account volume volatility.
United Kingdom
London-based SaaS exporters are expanding procurement of revenue optimization modules to satisfy investor scrutiny of net revenue retention metrics. The Information Commissioner's Office enforces GDPR Article 35 compliance for automated decision systems processing customer data. The Thames Valley corridor concentrates enterprise software buyers with legacy Salesforce estates requiring schema normalization.
Japan
Tokyo-based manufacturers transitioning to servitized revenue models are piloting customer success platforms for industrial software deployments. METI guidelines on data governance influence procurement specifications for cross-border telemetry flows. The Kanto region hosts the largest concentration of enterprise accounts with hybrid cloud requirements.
Global Customer Success Platforms Market Competitive Landscape
United States producers anchor the premium tier with native CRM data architectures; European specialists hold compliance-driven positions. The vendor base clusters around three strategic archetypes: health-scoring methodologists, freemium onboarding enablers, and unified-suite incumbents. Dominant competitive moves include strategic partnerships with billing stack providers and portfolio diversification into embedded finance convergence.
Within the health-scoring archetype, Gainsight occupies a position exemplifying predictive churn methodology specialization. Salesforce and HubSpot represent the unified-suite and freemium-onboarding tiers respectively, with geographic origins in California and Massachusetts anchoring their competitive positioning. These three companies illustrate the market's segmentation between deep functional specialization and broad platform consolidation.
| Leading Market Players |
|---|
| Gainsight |
| Salesforce |
| HubSpot |
| Totango |
| ChurnZero |
| Freshworks |
| Cisco Systems |
| Medallia |
| ClientSuccess |
| Others |
Supply & Pricing Matrix
Mid-market SaaS procurement teams in the United States are demanding usage-based contracts that scale with telemetry volume rather than seat count, forcing vendors to restructure cloud infrastructure commitments and compressing margins on fixed-cost legacy pricing tiers. This buyer-driven shift toward variable consumption models is reshaping how platforms provision server capacity and negotiate hyperscaler contracts.
Pricing Analysis
Short lead-time deployments for enterprise accounts with urgent GDPR compliance deadlines command 20-30% premiums over standard SaaS onboarding schedules. The dominant pricing structure stratifies across premium, standard, and economy tiers differentiated by ISO 27001 certification status and dedicated support availability. Price differentiation centers on data residency guarantees and custom API development capacity. Cost compression in the economy tier is intensifying because self-serve onboarding tools are commoditizing basic health-scoring functionality. Series B and C software companies exhibit the highest price sensitivity, while Bundesbank-regulated German financial institutions demonstrate minimal elasticity for air-gapped installations.
Supply Chain Analysis
Freight costs for on-premises hardware shipments to European banking clients have risen substantially, elevating total cost of ownership for single-tenant deployments. Supply concentrates in the United States for cloud-native platform development, India for implementation services and integration engineering, and Germany for compliance consulting and data sovereignty architecture. Raw material dependencies include hyperscaler compute capacity from AWS, Azure, and Google Cloud; enterprise CRM connector licenses from Salesforce and SAP; and specialized machine learning accelerators from NVIDIA. Single-source vulnerability around Salesforce API access poses structural risk for vendors dependent on real-time CRM synchronization. Distribution runs through direct enterprise sales teams, channel partners specializing in SaaS implementation, and API-first developer marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The customer success platform market is becoming a vertical-integration race as vendors pursue upstream control over machine learning training data pipelines and downstream embedding into billing and payment stacks.
For Market Incumbents: Lock in data architecture advantages by deepening native CRM integrations that increase switching costs for enterprise accounts. Acquire specialized consent-management tooling to neutralize EU AI Act compliance threats from European specialists. Prioritize capacity expansion in Bangalore and Hyderabad to capture India's scaling SaaS exporter base before regional champions consolidate. For New Entrants and Emerging Players: Capture whitespace in embedded finance convergence by building usage-based billing correlations that incumbent platforms lack. Target mid-market manufacturing enterprises in Japan transitioning to servitized revenue models with hybrid cloud deployments. Lead with API-integrated headless architectures that minimize change management friction for IT-constrained buyers. For Investors and Strategic Acquirers: The window for entry favors platforms with pre-built GDPR Article 35 compliance frameworks and established Bundesbank relationships. Long-term viability hinges on owning inference pipeline technology rather than orchestration layers. Watch for inflection when Series B SaaS CFOs begin consolidating success automation spend with revenue operations platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce connector deployment accelerates enterprise procurement cycles by eliminating schema normalization projects. |
| Strategic Partnership | Billing stack alliances with Stripe or Chargebee embed customer success logic directly into revenue event streams. |
| Acquisition of Specialist Firm | Consent-aware inference pipeline vendors in Berlin or Paris neutralize EU AI Act exclusion risks for US-based platforms. |
| Geographic Expansion | Bangalore and Hyderabad offices capture India's Series B and C SaaS exporters before local competitors mature. |
| Product Launch | Edge inference capabilities compress intervention windows from batch-processed daily scores to real-time hourly triggers. |
Research Methodology
SEC filings, EU regulatory guidance documents, and hyperscaler capex disclosures formed the secondary backbone for this analysis. Primary interviews with CTOs at scaling SaaS providers, customer success operations directors, integration specialists, and procurement officers at German financial institutions validated demand-side assumptions. Bottom-up telemetry volume estimates and top-down software spend allocations were triangulated to anchor market sizing.
Historical trendline analysis of cloud software procurement patterns informed the projection framework across deployment models, organization size tiers, vertical concentration, and regional adoption patterns. CAGRs were derived from segment-level growth rate differentials applied to base-year estimates. Forecast inputs included EU AI Act implementation timelines, SEC disclosure requirement adoption curves, and India SaaS exporter formation rates.
The model holds under steady regulatory enforcement and continued SaaS subscription economics dominance; deviation in hyperscaler pricing, major GDPR penalty events, or AI Act risk reclassification would shift trajectory materially. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Global Customer Experience Management Software Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Lead Management Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Cloud Based Contact Center Market
Customer Relationship Management (CRM)
Customer Information System (CIS) Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Customer Experience Platforms Market
Customer Relationship Management (CRM)
Customer Communication Management Market
Customer Relationship Management (CRM)
Pharmaceutical Customer Relationship Management (CRM) Software Market
Customer Relationship Management (CRM)
Retail CRM Software Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market