
 Customer Information System (CIS) Market | 2026-2036
Customer Information System (CIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Customer Information System (CIS) Market Outlook
Subscription-based SaaS financing is reconfiguring capital requirements for utilities adopting Customer Information System platforms. Oracle leverages its database heritage to anchor enterprise-scale deployments across regulated water districts. SAP competes through deep ERP integration that sustains cross-functional workflows for billing and field service. Salesforce specializes in CRM-layer extensions that differentiate its offering for retail energy marketers seeking agile customer engagement tools.
A Customer Information System constitutes an integrated software platform that manages utility customer lifecycle operations including meter-to-cash processing, service order orchestration, and consumption analytics through relational database architectures and API-connected modular components. Its primary commercial purpose centers on enabling accurate billing, reducing revenue leakage, and supporting demand-side management programs for electric, gas, and water utilities. Cloud-based deployment now leads solution type adoption as utilities prioritize scalability and disaster recovery over capital-intensive on-premise infrastructure. The analytics functionality segment is expanding fastest as smart meter proliferation generates granular interval data requiring real-time processing and predictive modeling capabilities.
FERC Order 2222 in the United States and the EU Green Deal's digitalization requirements are reshaping CIS procurement specifications to demand interoperability with distributed energy resource management systems. ISO 55000 asset management standards and IEC 61968 Common Information Model protocols further constrain product design by mandating standardized data exchange interfaces. Stakeholders must evaluate whether their current CIS architecture can absorb forthcoming telemetry loads from vehicle-to-grid integration and building-level energy flexibility markets without wholesale replacement.
Market Dynamics
Cloud-native architecture migration is compressing replacement cycles for legacy mainframe CIS deployments as utilities face escalating telemetry loads from distributed energy resources and smart meter networks. FERC Order 2222 and analogous grid modernization mandates in Germany and Japan are forcing interoperability investments that legacy systems cannot accommodate.
Growth Catalysts
- FERC Order 2222:The US Federal Energy Regulatory Commission's mandate for distributed energy resource aggregation is compelling utilities to replace siloed billing systems with API-native platforms capable of real-time settlement.
- Smart meter proliferation:Interval data volumes from advanced metering infrastructure in Australia and Japan are exceeding legacy database throughput limits, necessitating scalable cloud architectures.
- EU Green Deal digitalization:Brussels' requirements for building-level energy flexibility tracking are accelerating CIS procurement among German municipal utilities.
Market Restraints
- Mainframe technical debt:COBOL-dependent utilities face 18-24 month migration timelines as specialized talent pools shrink, delaying cloud transitions despite procurement approval.
- Concentrated database licensing:Oracle's dominance in relational engine patents creates vendor lock-in risks for water districts seeking multi-cloud redundancy.
- IEC 61968 compliance costs:Common Information Model protocol certification requires six-figure third-party validation budgets that constrain mid-tier cooperative utilities.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional charging telemetry from electric fleets in California and Texas creates demand for CIS modules capable of dynamic pricing and grid services settlement.
- Building flexibility markets:Automated demand response participation by commercial real estate in Germany requires sub-hourly consumption analytics that legacy platforms cannot deliver.
- AI-driven predictive billing:Convergence of machine learning models with interval data streams enables utilities to forecast revenue leakage and optimize payment plan offerings.
Industry Challenges
- API orchestration complexity:Field service management integration with CIS platforms requires scarce integration architects familiar with both utility operations and microservices architecture.
- Data residency fragmentation:Australia's critical infrastructure regulations and Germany's GDPR implementations impose conflicting sovereignty requirements on multi-tenant SaaS deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customer Information System (CIS) Market |
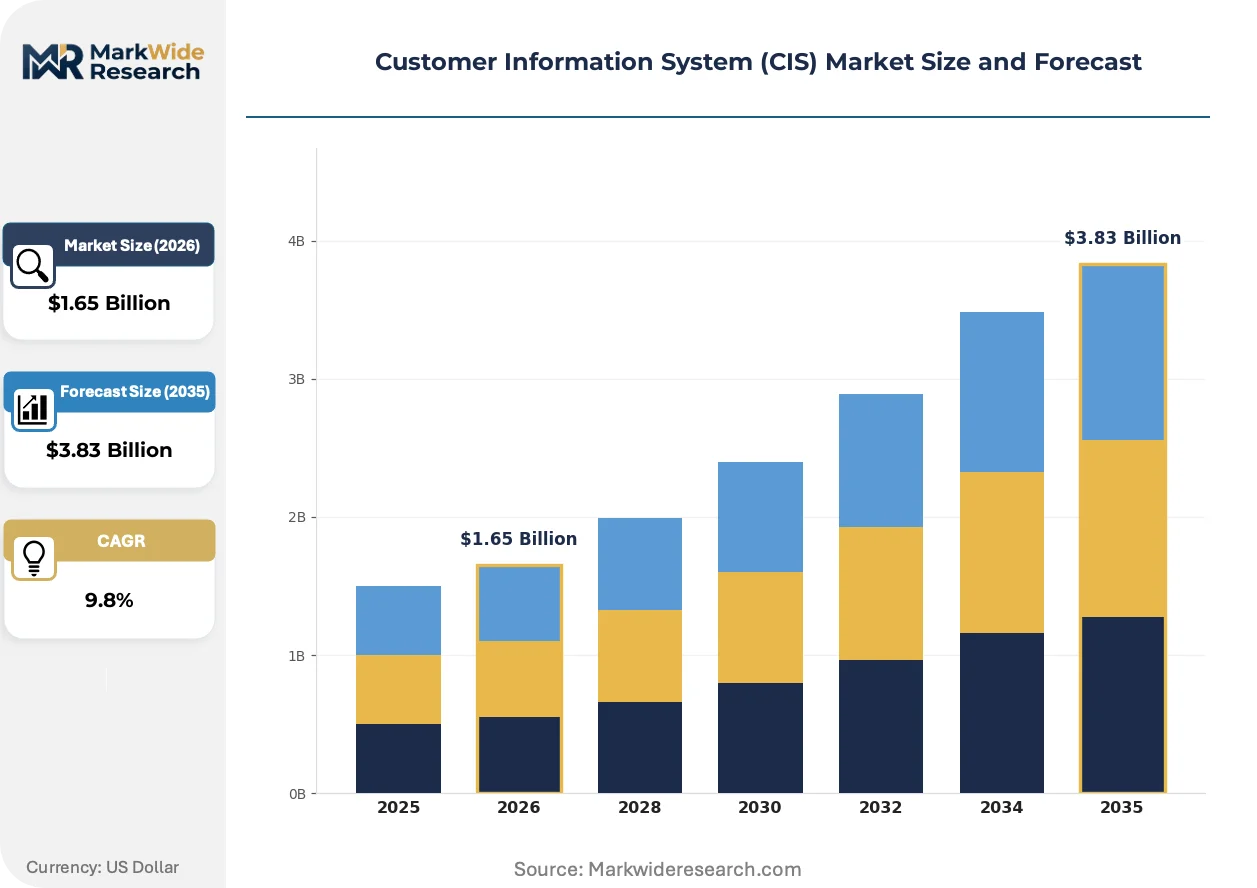
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.83 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: On-Premise, Cloud-Based, Hybrid, Mobile End User: BFSI, Retail, Telecom, Healthcare Deployment Model: Private Cloud, Public Cloud, Community Cloud, Multi-Tenant Functionality: Customer Support, Data Management, Billing, Analytics |
| Companies Covered | IBM, Minsait, Oracle, CSG Systems International, Kraken Technologies, SAP, Salesforce, Gentrack, Hansen Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customer Information System (CIS) Market Strategic Shifts
Real-time analytics engines are displacing batch-processing architectures as the primary value layer in utility software stacks. This shift is compressing vendor competitive windows and forcing architectural bets on stream processing versus data lakehouse approaches.
Edge computing nodes deployed at substations and water treatment facilities are hybridizing traditional centralized CIS architectures with distributed processing capabilities. Electric cooperatives in Texas and municipal utilities in Japan are piloting these configurations to reduce latency for outage management and leak detection alerts. The structural consequence is a compression of acceptable vendor response times from minutes to sub-second thresholds.
The EU AI Act's risk classification framework is mandating algorithmic transparency for automated billing dispute resolution and credit scoring modules. German and French utilities must now maintain explainability logs for machine learning models affecting customer financial outcomes. CIS vendors are responding by embedding model interpretability dashboards that expose feature importance weights to regulatory auditors.
Subscription financing is displacing perpetual license purchases among North American water districts capital-constrained by rate case delays. SaaS structures spread implementation costs across operational budgets rather than requiring upfront IT capital allocations. California and Ontario utilities are most advanced in this transition, with procurement committees now evaluating total cost of ownership over seven-year horizons rather than initial license fees.
Customer Information System (CIS) Market Segmentation
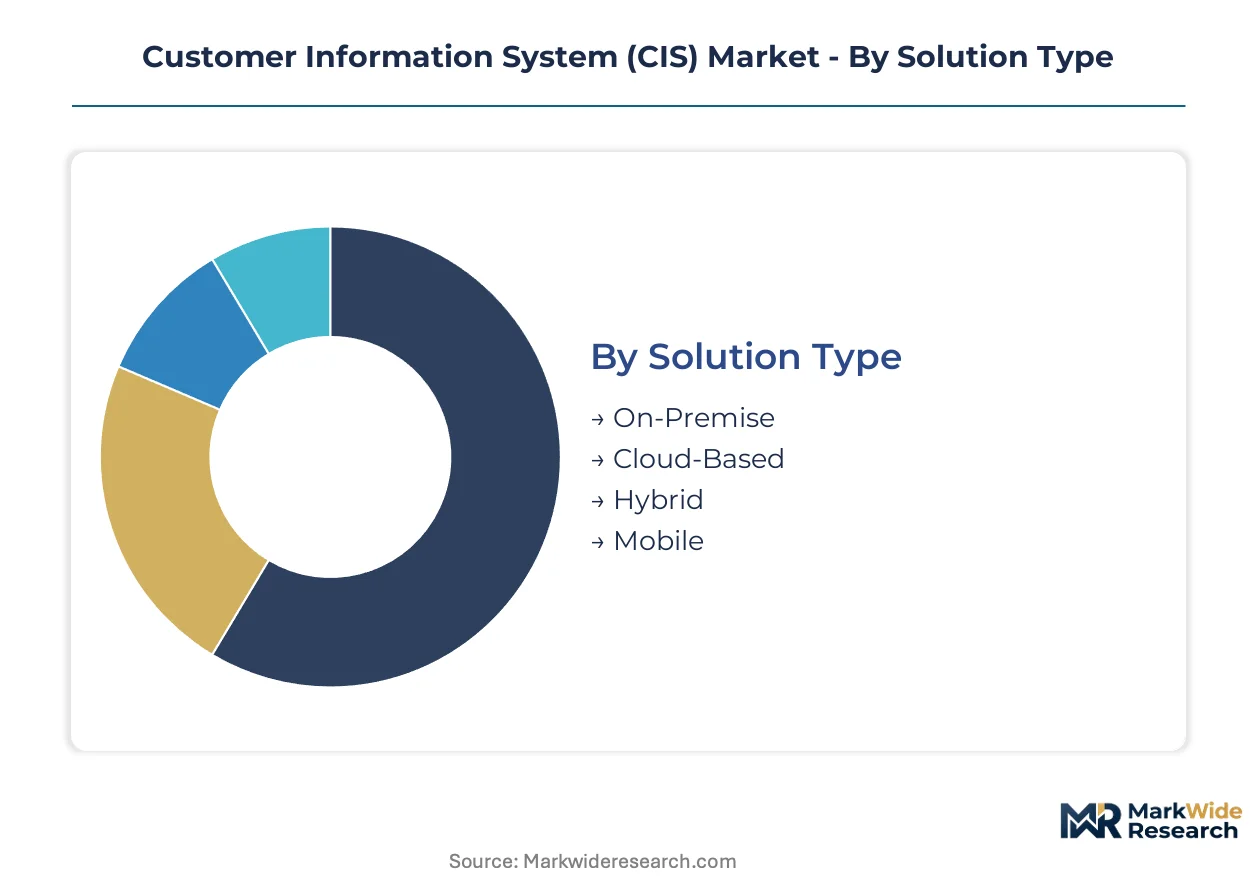
CIS procurement patterns diverge sharply across deployment architectures and operational requirements. Utility technology committees evaluate segments against telemetry throughput needs, regulatory compliance burdens, and capital availability constraints.
Solution Type:
Cost tier structures the procurement calculus as utilities weigh upfront capital against operational flexibility and disaster recovery capabilities.
- On-Premise:Legacy mainframe installations running COBOL-dependent architectures persist among water districts with rate case delays blocking cloud migration. These deployments demand dedicated data center infrastructure and specialized maintenance talent pools that shrink annually.
- Cloud-Based:API-native platforms with auto-scaling relational databases now dominate new procurement among electric utilities facing FERC Order 2222 interoperability mandates. German municipal utilities and Australian water providers lead this transition, prioritizing sub-hourly settlement capabilities for distributed energy resources.
- Hybrid:Configurations retain sensitive billing data on-premise while pushing analytics workloads to public cloud instances. Mid-tier cooperatives favor this model to satisfy data residency requirements without sacrificing computational elasticity.
- Mobile:Field technician applications with offline synchronization capabilities support meter reading and outage response workflows. Texas electric cooperatives pilot these modules for rural service territories with intermittent connectivity.
On-Premise retains the installed base. Cloud-Based climbs the fastest as grid modernization mandates accelerate replacement cycles.
End User:
Application context determines functional requirements, integration complexity, and regulatory exposure for CIS vendors.
- BFSI:Banking and financial services deployments emphasize payment plan orchestration, credit risk scoring, and PCI-DSS compliance for utility bill financing programs. Water districts in capital-constrained regions leverage these integrations to reduce delinquency rates.
- Retail:Energy marketers require CRM-layer agility for customer acquisition and churn reduction. Salesforce-specialized configurations serve this segment with rapid campaign deployment tools.
- Telecom:Convergent billing platforms merge utility and communications charges for municipal providers offering bundled services. Japanese utilities explore these architectures for smart city initiatives.
- Healthcare:Hospital campus microgrids demand CIS modules capable of tracking behind-the-meter generation and demand response participation. California medical centers pilot these configurations for resilience against Public Safety Power Shutoff events.
BFSI commands the established revenue base. Retail gains share fastest as competitive energy markets expand.
Deployment Model:
Customer type and data sovereignty requirements fragment cloud architecture preferences across utility ownership structures.
- Private Cloud:Dedicated tenant environments satisfy German GDPR implementations and Australia's critical infrastructure regulations. Investor-owned utilities with cybersecurity insurance mandates prefer this model.
- Public Cloud:Shared infrastructure delivers lowest unit economics for small municipal utilities without dedicated IT operations. Subscription financing spreads costs across operational budgets.
- Community Cloud:Multi-utility collaborations among rural electric cooperatives share infrastructure costs while maintaining sector-specific compliance certifications. Texas and Oklahoma co-ops pioneer these arrangements.
- Multi-Tenant:SaaS platforms with logical data segregation serve water districts seeking rapid deployment without capital allocation delays. Ontario utilities advance this model through procurement committee precedent.
Private Cloud holds the conservative majority. Public Cloud expands most quickly among capital-constrained districts.
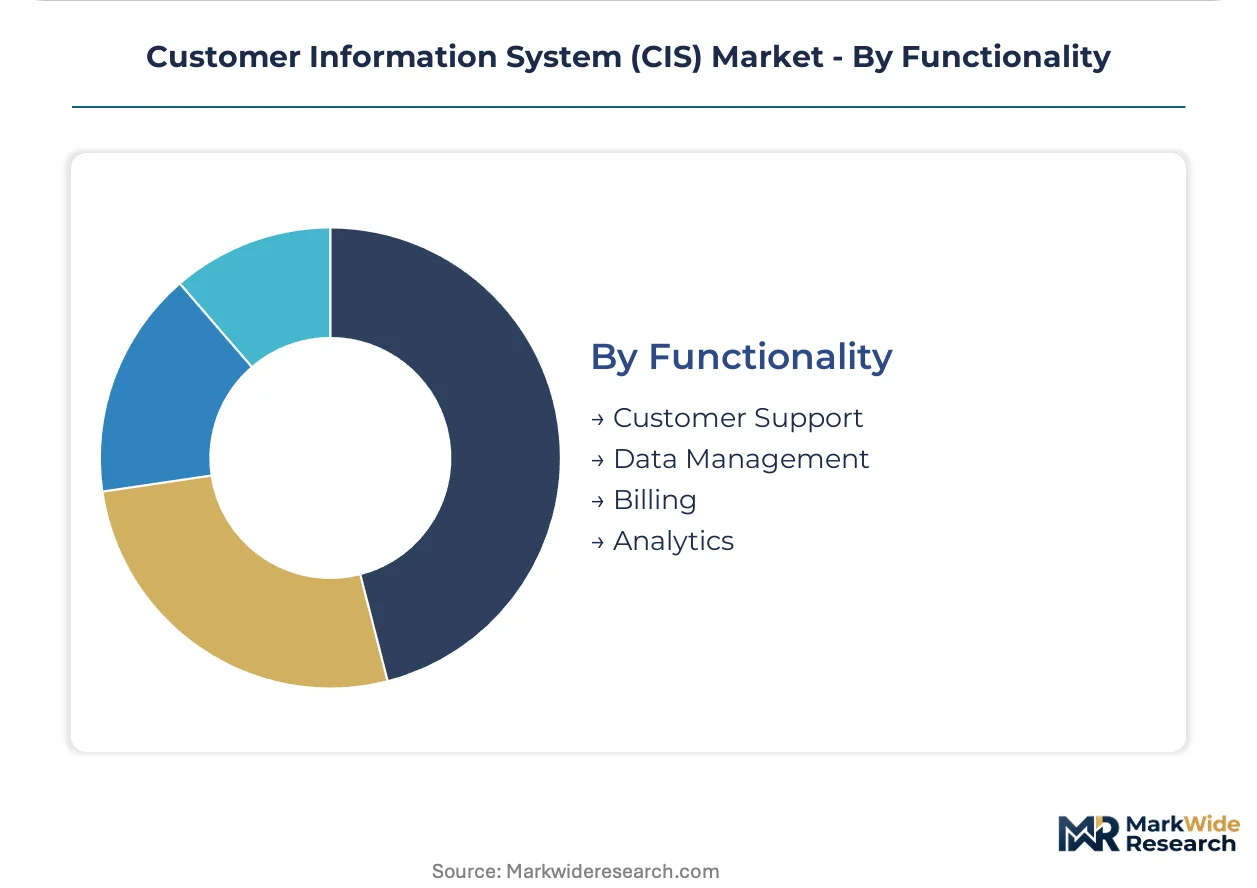
Functionality:
Maturity of utility data infrastructure determines which functional modules deliver immediate operational value versus future-state capabilities.
- Customer Support:Omnichannel case management and automated dispute resolution workflows reduce call center staffing requirements. AI-driven modules now require explainability logs under EU AI Act risk classifications.
- Data Management:Master data governance and IEC 61968 CIM protocol compliance form the integration backbone for smart meter telemetry ingestion. Validation budgets for certification constrain mid-tier cooperative adoption.
- Billing:Meter-to-cash processing with interval data rating engines represents the core revenue protection function. Legacy batch architectures face displacement by real-time settlement requirements.
- Analytics:Predictive models for revenue leakage detection and demand forecasting leverage machine learning on granular consumption data. German building flexibility markets and California vehicle-to-grid pilots drive this segment's acceleration.
Billing anchors current procurement budgets. Analytics represents the steepest expansion trajectory as telemetry volumes multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal utilities command pricing premiums for CIS modules compliant with EU Green Deal digitalization mandates, while Australian water districts absorb cost penalties from mainframe migration timelines stretching capital recovery periods.
United States
FERC Order 2222 interoperability requirements and vehicle-to-grid pilot programs in California and Texas are accelerating cloud-native procurement. Texas electric cooperatives deploy edge computing nodes at substations to compress outage response latency. California medical centers pilot behind-the-meter CIS tracking for Public Safety Power Shutoff resilience.
Germany
Building-level energy flexibility markets and GDPR data sovereignty requirements are fragmenting deployment architecture preferences. Municipal utilities in Bavaria and North Rhine-Westphalia prioritize private cloud configurations with IEC 61968 CIM protocol certification. Berlin-Brandenburg clusters concentrate AI-driven predictive billing development under EU AI Act explainability mandates.
Japan
Smart city convergence initiatives and METI grid modernization directives are expanding telemetry throughput requirements. Tokyo and Osaka metropolitan utilities migrate interval data processing to auto-scaling relational databases. Chubu region pilots edge computing for leak detection alerts at water treatment facilities.
Australia
Critical infrastructure regulations and smart meter proliferation are exceeding legacy database throughput limits. New South Wales and Victoria water districts face 18-24 month COBOL migration timelines despite procurement approval. Sydney and Melbourne clusters concentrate subscription-based SaaS financing adoption among capital-constrained districts.
Customer Information System (CIS) Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying analytics modules and API connectors. The vendor base clusters around three strategic archetypes: database heritage players anchoring enterprise water districts, ERP-integrated suites sustaining cross-functional workflows, and CRM-layer extensions serving retail energy marketers. Consolidation pressure concentrates among mid-tier cooperatives seeking multi-cloud redundancy against vendor lock-in. Dominant competitive moves include strategic partnerships for IEC 61968 compliance certification and portfolio diversification into vehicle-to-grid settlement modules.
Within the database heritage tier, Oracle and IBM occupy positions anchored by relational engine patents and mainframe modernization expertise. SAP exemplifies the ERP-integrated archetype through billing-to-field-service workflow orchestration. Salesforce sits within the CRM-specialist vector, representing agile customer engagement configurations for competitive retail markets. These three anchors collectively illustrate how vendor selection stratifies across utility ownership structures and regulatory exposure profiles.
| Leading Market Players |
|---|
| IBM |
| Minsait |
| Oracle |
| CSG Systems International |
| Kraken Technologies |
| SAP |
| Salesforce |
| Gentrack |
| Hansen Technologies |
| Others |
Value Chain & Pricing Dynamics
Oracle's relational engine patent concentration in the United States funnels margin pools toward database licensing tiers, while downstream utilities absorb cost premiums for multi-cloud redundancy configurations that break vendor lock-in.
Pricing Analysis
Configured-to-order pricing for IEC 61968 CIM protocol certification commands substantial premiums over standard SaaS-tiered subscriptions. Subscription-based SaaS financing dominates new procurement, spreading implementation costs across operational budgets rather than upfront capital allocations. Price differentiation hinges on customization depth for FERC Order 2222 interoperability and after-sales integration support. Cost compression in mid-tier cooperative utilities is intensifying because six-figure third-party validation budgets strain limited procurement committees. Small municipal utilities exhibit highest price sensitivity; investor-owned utilities with cybersecurity insurance mandates show lowest.
Supply Chain Analysis
Upstream cloud infrastructure feeds from hyperscaler concentrations in the United States, Germany, and Japan. Raw material dependencies center on proprietary relational database engines, API middleware stacks, and edge computing hardware. Single-source vulnerability around Oracle's patent portfolio creates structural exposure for water districts seeking architectural flexibility. Distribution runs through direct enterprise sales teams for large utilities and regional systems integrators for mid-tier cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integration architects fluent in both utility operations and microservices architecture constrains deployment velocity, compressing competitive windows for vendors who can certify talent pipelines fastest.
For Market Incumbents: Harden API-native platform architectures against emerging cloud-native challengers by embedding IEC 61968 CIM protocol certification as a default feature rather than premium add-on. Deepen vertical integration into edge computing hardware partnerships to compress outage response latency below sub-second thresholds for Texas electric cooperatives. For New Entrants and Emerging Players: Pursue white-space opportunities in vehicle-to-grid settlement modules for California and Texas pilot programs, where legacy incumbents lack real-time dynamic pricing capabilities. Australian water districts facing 18-24 month COBOL migration timelines represent the most penetrable geography; lead with subscription financing structures that bypass capital allocation delays. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier CIS vendors holding concentrated municipal utility relationships but lacking analytics module depth. Five-to-ten year viability hinges on successful convergence with AI-driven predictive billing and building flexibility market participation. Watch German GDPR enforcement actions against multi-tenant SaaS deployments as the signal for data sovereignty premium repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native architectures satisfy FERC Order 2222 interoperability mandates for distributed energy resource aggregation. |
| Strategic Partnership | Edge computing hardware alliances compress outage response latency for Texas electric cooperative substation deployments. |
| Acquisition of Specialist Firm | Analytics module depth addresses German building flexibility market requirements for sub-hourly consumption tracking. |
| Geographic Expansion | Australian water district procurement committees prioritize subscription financing to bypass rate case capital delays. |
| Product Launch | Vehicle-to-grid settlement modules capture California and Texas bidirectional charging telemetry revenue streams. |
Study Parameters
A spread of perspectives from utility CIOs, integration architects, procurement committee chairs, and regulatory affairs officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA grid modernization databases, EU Green Deal implementation trackers, and IEC protocol certification registries. Bottom-up telemetry throughput modeling triangulated against top-down utility IT spending surveys.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions spanned deployment architecture, utility ownership structure, and regulatory compliance burden. CAGRs derived from replacement cycle velocity for legacy mainframe estates and smart meter penetration curves. Forecast inputs incorporated FERC Order 2222 implementation timelines and EU AI Act explainability mandate enforcement schedules.
Sensitivities concentrate around COBOL talent pool shrinkage extending migration timelines, and GDPR data sovereignty rulings fragmenting multi-tenant SaaS economics. Forecasts reflect documented assumptions about grid modernization mandate adherence rates. Cross-checking against state public utility commission rate case approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Customer Experience Management Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Global CRM197 Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Healthcare CRM Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Global Client Management Tools Market
Customer Relationship Management (CRM)
Cloud CRM Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Smart Customer Service System Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Android CRM Software Market