
 Contact Centers Speech Applications Market | 2026-2036
Contact Centers Speech Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Centers Speech Applications Market Analysis
Market Context
The capability gap between cloud-native infrastructure and legacy on-premise deployments is bifurcating competitive outcomes in the contact center speech sector. Nuance Communications leverages its deep integration with healthcare and enterprise workflows to sustain premium positioning in voice biometrics. Amazon Web Services anchors its growth through captive cloud infrastructure that undercuts rivals on compute pricing for real-time speech processing. Google LLC differentiates via Tensor-optimized natural language models that reduce latency for live agent assistance tools.
Technical and Segment Structure
Contact centers speech applications encompass software systems that capture, process, analyze, and respond to human voice inputs in real-time customer service environments, typically operating with sub-200-millisecond latency requirements for interactive voice response and employing acoustic models trained on millions of hours of conversational audio. Speech analytics and voice biometrics represent the fastest-expanding technology layers, with the former extracting sentiment and compliance signals from recorded interactions and the latter replacing knowledge-based authentication in banking and telecommunications. Cloud-based deployment dominates new installations as enterprises abandon capital-intensive hardware refresh cycles, while hybrid configurations persist in regulated BFSI environments where data residency requirements fragment infrastructure decisions.
Regulatory Environment and Outlook
The Federal Communications Commission enforces truth-in-billing and robocall mitigation rules that shape how speech applications disclose automated system use to consumers, while the EU AI Act imposes conformity assessments on high-risk AI systems including credit and insurance eligibility decisions rendered through voice channels. Health Insurance Portability and Accountability Act requirements in the United States constrain cloud storage architectures for healthcare contact centers, pushing vendors toward private-instance deployments or business associate agreement structures. Stakeholders must monitor whether emerging state-level AI transparency laws fragment compliance obligations beyond federal frameworks, particularly as voice cloning detection becomes a mandatory feature in financial services authentication stacks.
Market Dynamics
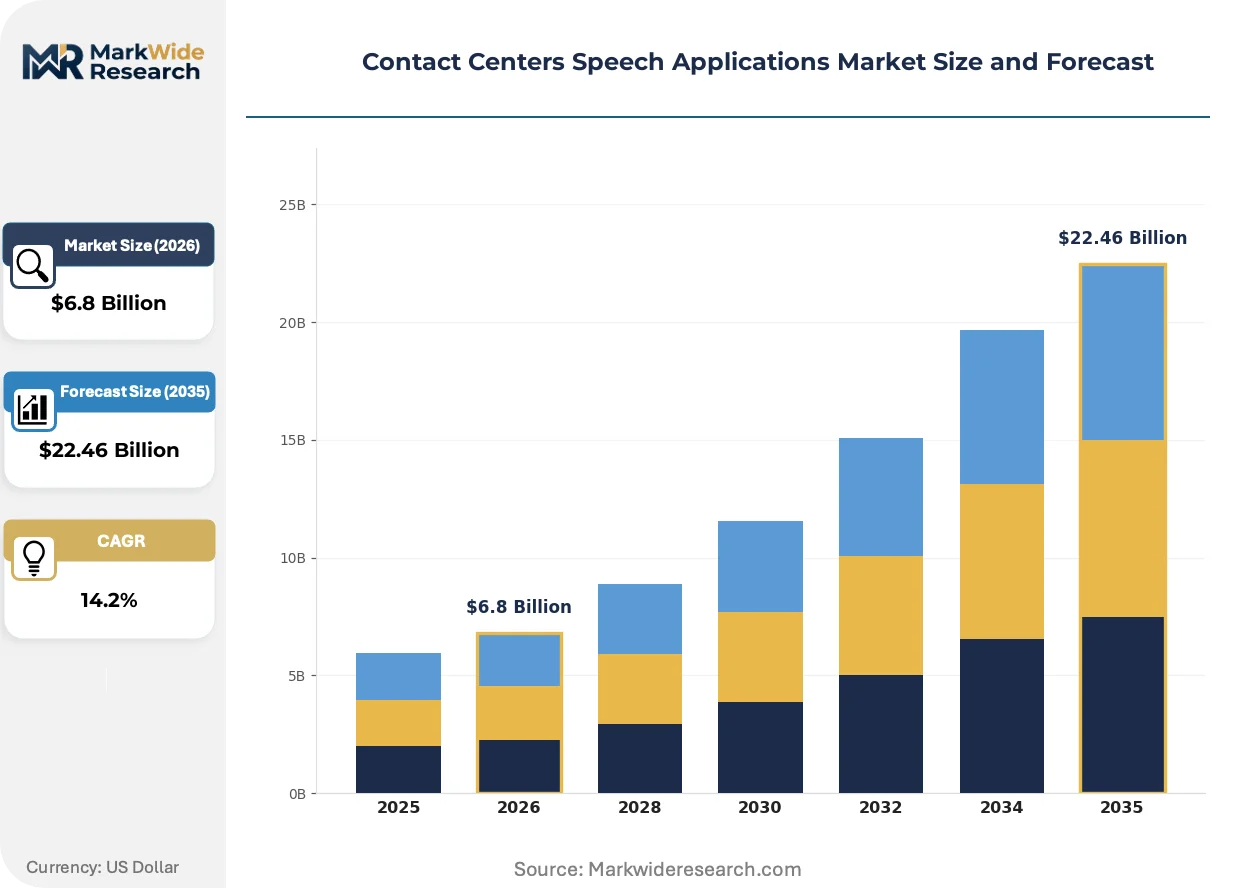
The migration from on-premise hardware to cloud-native speech infrastructure is compressing deployment timelines and redistributing competitive advantage toward vendors with captive compute capacity.
Growth Catalysts
- EU AI Act compliance mandates:Financial institutions across Europe must implement auditable decision trails for automated voice interactions, forcing upgrades to compliant speech analytics platforms.
- Voice biometrics in banking:Knowledge-based authentication is yielding to acoustic voiceprint verification, cutting average handle times by eliminating security question sequences.
- Real-time agent assistance:Tensor-optimized natural language models now deliver sub-200-millisecond transcription latency, enabling live coaching during active customer calls.
Market Restraints
- Data residency fragmentation:HIPAA constraints and EU data sovereignty rules prevent unified cloud architectures, forcing redundant infrastructure investments in healthcare and BFSI verticals.
- GPU compute cost volatility:Training and inference workloads for large acoustic models depend on NVIDIA H100 supply concentrated in Taiwan and South Korea foundries.
- Legacy IVR technical debt:Touch-tone menu trees and proprietary telephony protocols resist API-based integration with modern speech AI stacks.
Strategic Opportunities
- Voice cloning detection mandates:The FCC's robocall mitigation framework is expanding to require synthetic voice identification in financial services authentication flows.
- Hybrid cloud configurations:Regulated enterprises seek private-instance deployments with burst capacity to public clouds, creating managed service openings for regional system integrators.
- Sentiment-to-compliance convergence:Speech analytics platforms that fuse emotional state detection with regulatory risk scoring address both quality assurance and legal defensibility needs.
Industry Challenges
- Conversational AI talent scarcity:Phonetics engineers and dialogue designers command premium compensation, constraining vendor scaling and enterprise internal development.
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud face inconsistent speech API implementations and divergent latency profiles.
- Biometric enrollment friction:Customer opt-in rates for voiceprint registration lag behind deployment targets, delaying ROI realization on authentication infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Centers Speech Applications Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voice Recognition, Speech Analytics, IVR Systems, Call Routing Deployment: On-Premise, Cloud-Based, Hybrid, Virtual End User: Telecommunications, BFSI, Retail, Healthcare Technology: Natural Language Processing, Machine Learning, AI, Voice Biometrics |
| Companies Covered | Nuance Communications, Google LLC, Amazon Web Services, IBM Corporation, Verint Systems, Genesys Telecommunications Laboratories, NICE, SoundHound, Uniphore Software Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Centers Speech Applications Market Emerging Trajectories
Speech application architectures are bifurcating between centralized cloud inference and edge-deployed models, with regulatory pressure and latency requirements pulling in opposite directions.
Foundation-model-based speech recognition is fragmenting the vendor landscape. Pre-trained acoustic and language models now enable mid-tier contact center software providers to match incumbent transcription accuracy without proprietary training data. Regional BFSI players in Germany and Canada are adopting these open-weight architectures to avoid cloud dependency. The technology is fragmenting market share concentration that previously favored vendors with decade-long audio corpora.
The EU AI Act's high-risk system classification is reshaping procurement criteria. Automated credit and insurance eligibility decisions rendered through voice channels now require conformity assessments and human oversight protocols. German automotive finance call centers and Dutch insurance providers are rebuilding IVR flows to insert agent handoff triggers before binding determinations. This regulatory architecture is compressing deployment timelines for conversational AI projects in European financial services.
Subscription-based speech API consumption is displacing perpetual licensing in enterprise procurement. Contact center operators in the United States now meter transcription and analytics volumes monthly rather than provisioning fixed-capacity licenses. This shift aligns vendor revenue with actual usage but exposes buyers to cost volatility during seasonal demand spikes. Telecommunications carriers and healthcare providers exhibit the most pronounced migration toward consumption-based pricing models.
Contact Centers Speech Applications Market Segmentation
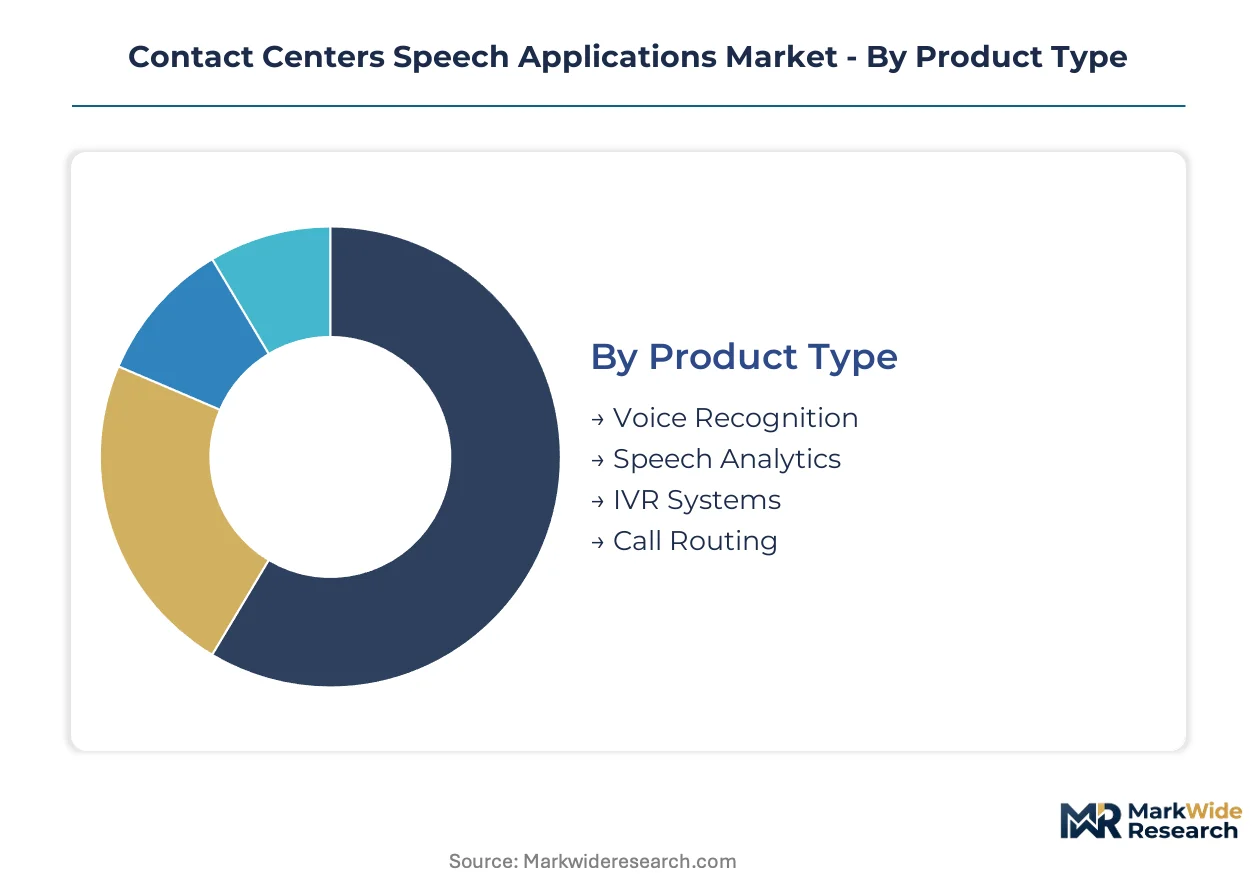
Speech application architectures diverge sharply across deployment modes and end-use requirements, with regulated verticals demanding hybrid configurations while cloud-native stacks dominate cost-sensitive segments. Technology layers compete for capital allocation as voice biometrics and real-time analytics reshape procurement priorities.
Product Type:
Domestic demand concentrates in North American banking and telecommunications, while export-led growth flows from European compliance mandates and Asia-Pacific cloud migration.
- Voice Recognition:Acoustic models process spoken commands with sub-200-millisecond latency for interactive voice response systems. Demand clusters in United States telecommunications carriers modernizing legacy touch-tone infrastructure amid FCC robocall mitigation requirements.
- Speech Analytics:Platforms extract sentiment signals and compliance markers from recorded interactions using foundation-model transcription. German automotive finance call centers and Dutch insurance providers are rebuilding IVR flows to satisfy EU AI Act human-oversight protocols.
- IVR Systems:Automated menu trees and call flow management software persist in healthcare contact centers constrained by HIPAA data residency rules.
- Call Routing:Skills-based distribution algorithms direct inquiries to appropriate agents based on acoustic intent classification and queue optimization.
Speech analytics holds the largest share; momentum sits with voice recognition as latency requirements tighten.
Deployment:
Cost tiering separates capital-intensive perpetual licensing from consumption-metered cloud subscriptions, with mid-market enterprises gravitating toward hybrid middle grounds.
- Cloud-Based:Metered API consumption eliminates hardware refresh cycles and aligns vendor revenue with transcription volumes. United States contact center operators now bill monthly rather than provisioning fixed-capacity licenses, exposing buyers to seasonal cost volatility.
- Hybrid:Private-instance deployments with burst capacity to public clouds address regulated BFSI environments where data sovereignty fragments infrastructure decisions. German and Canadian regional banks adopt these configurations to maintain local control over voice biometric enrollment data.
- On-Premise:Legacy hardware persists in healthcare contact centers requiring business associate agreement structures for HIPAA compliance.
- Virtual:Containerized speech stacks enable rapid scaling across distributed agent workforces without dedicated physical infrastructure.
Cloud-based deployment commands the largest installed base; hybrid configurations are climbing the fastest as regulatory pressure intensifies.
End User:
Application intensity varies by sector-specific authentication requirements and conversational complexity, with financial services driving premium pricing for compliance-integrated stacks.
- BFSI:Voice biometrics replace knowledge-based authentication, cutting average handle times by eliminating security question sequences. EU AI Act conformity assessments now mandate auditable decision trails for automated credit and insurance eligibility determinations rendered through voice channels.
- Telecommunications:Carriers meter transcription and analytics volumes monthly, exhibiting the most pronounced migration toward consumption-based pricing models among all verticals.
- Healthcare:HIPAA constraints prevent unified cloud architectures, forcing redundant infrastructure investments and private-instance deployments for patient interaction recording.
- Retail:Seasonal demand spikes and lower compliance burdens favor fully cloud-native speech stacks with elastic capacity scaling.
BFSI holds the largest share; retail is gaining share fastest as e-commerce voice channels proliferate.
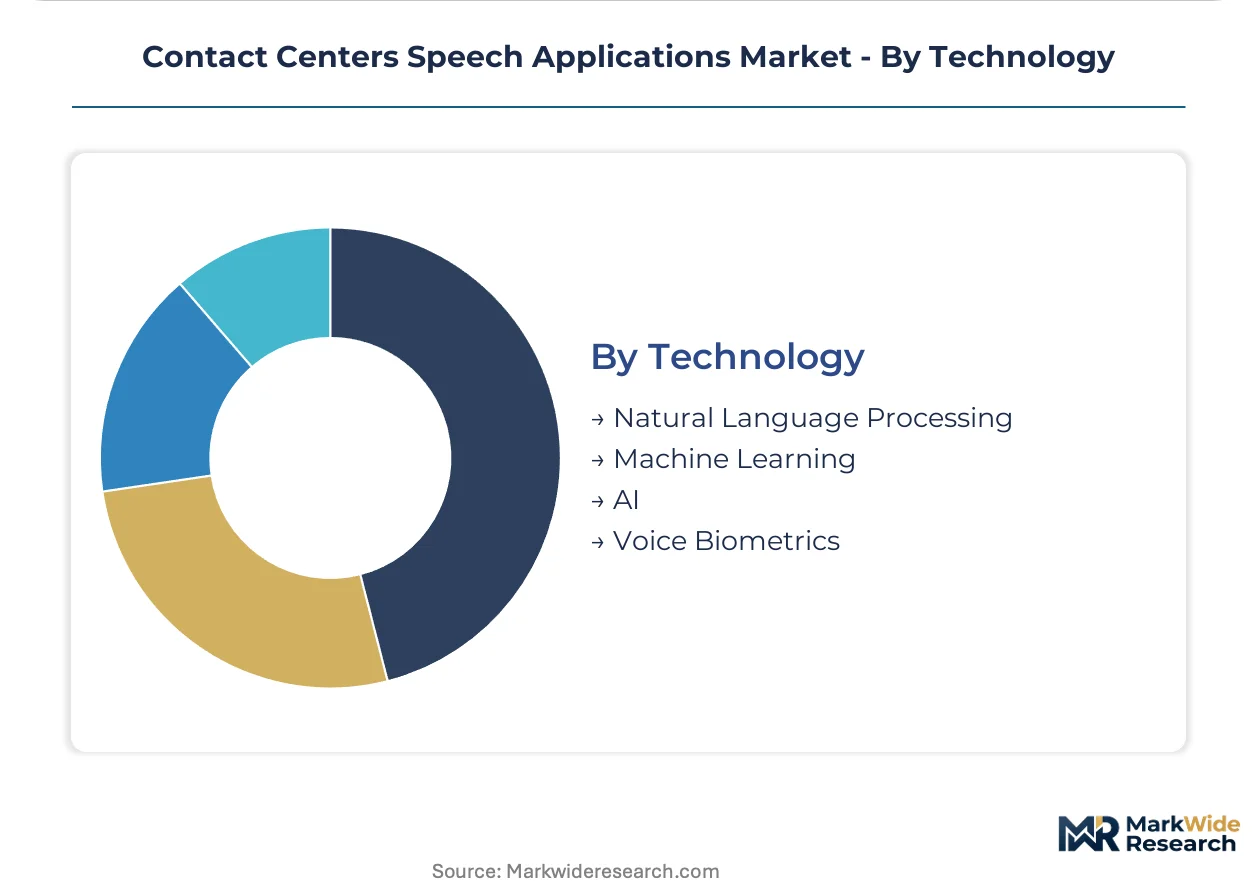
Technology:
Supply concentration in NVIDIA H100 foundry capacity creates cost tiering between GPU-dependent training workloads and optimized inference at the edge.
- Voice Biometrics:Acoustic voiceprint verification systems enroll customers through passive or active sampling during natural conversation. Financial services authentication stacks now require synthetic voice identification capabilities under expanding FCC robocall mitigation frameworks.
- Natural Language Processing:Tensor-optimized models deliver sub-200-millisecond transcription latency for live agent assistance tools, with Google LLC differentiating through specialized hardware-software integration.
- Machine Learning:Pre-trained acoustic models enable mid-tier providers to match incumbent transcription accuracy without proprietary decade-long audio corpora.
- AI:Foundation-model-based speech recognition fragments market share concentration previously favoring vendors with captive training data assets.
Natural language processing holds the largest share; voice biometrics shows the steepest expansion trajectory as authentication infrastructure displaces legacy security protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as cloud migration urgency overrides cost concerns, while European financial institutions absorb premium pricing for compliance-integrated stacks. Healthcare providers in Canada and Germany face the highest procurement friction from data residency mandates. Asia-Pacific telecommunications carriers exhibit mid-range elasticity, prioritizing scalable consumption models over capital-intensive perpetual licenses.
United States
Telecommunications carriers and banking conglomerates drive demand for sub-200-millisecond transcription latency in live agent assistance tools. FCC robocall mitigation rules mandate synthetic voice disclosure protocols that reshape authentication infrastructure procurement. The Dallas-Fort Worth metroplex hosts concentrated contact center operations where cloud-native speech stacks displace legacy touch-tone IVR systems.
Germany
Automotive finance call centers and insurance providers require auditable decision trails for automated credit eligibility determinations rendered through voice channels. EU AI Act conformity assessments impose human oversight triggers before binding determinations. Frankfurt's BFSI cluster leads deployment of hybrid cloud configurations to maintain local control over voice biometric enrollment data.
United Kingdom
Retail banking and telecommunications sectors prioritize consumption-metered API billing over fixed-capacity licensing. GDPR constraints intersect with FCA conduct rules to fragment cloud storage architectures for customer interaction recording. London's financial services hub anchors demand for sentiment-to-compliance converged speech analytics platforms.
Canada
Regional banks and healthcare providers seek private-instance deployments with burst capacity to public clouds. Health Canada and PIPEDA requirements constrain unified cloud architectures, forcing redundant infrastructure investments. Toronto's fintech corridor drives adoption of voice biometrics replacing knowledge-based authentication sequences.
India
IT services exporters and domestic telecommunications carriers meter transcription volumes monthly, exhibiting pronounced migration toward consumption-based pricing. TRAI regulations shape disclosure requirements for automated system use in customer interactions. Bangalore's technology services cluster anchors delivery of conversational AI talent for global enterprise deployments.
Contact Centers Speech Applications Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud hyperscalers undercutting rivals on compute pricing while specialized vendors sustain premium positioning through vertical integration. The market structure concentrates around three strategic tiers: captive infrastructure providers, healthcare-anchored biometrics specialists, and open-weight foundation model distributors. Consolidation pressure intensifies as GPU-dependent training costs favor scale. Dominant competitive moves include strategic partnerships for regulatory compliance coverage and portfolio diversification into edge-deployed inference architectures.
Among cloud-native infrastructure providers, Amazon Web Services and Google LLC exemplify the cost-leadership archetype through captive compute capacity and Tensor-optimized hardware-software integration. Nuance Communications occupies a position within the premium-tier vertical specialist segment, leveraging deep healthcare workflow integration. These three anchors demonstrate how vendor selection bifurcates between price-sensitive volume processing and compliance-integrated premium stacks.
| Leading Market Players |
|---|
| Nuance Communications |
| Google LLC |
| Amazon Web Services |
| IBM Corporation |
| Verint Systems |
| Genesys Telecommunications Laboratories |
| NICE |
| SoundHound |
| Uniphore Software Systems |
| Others |
Supply Flow & Price Mechanics
Ninety-day GPU allocation windows for NVIDIA H100 clusters determine pricing power across the contact center speech sector, compressing margins for vendors without captive cloud infrastructure while amplifying cost advantages for hyperscalers with direct foundry relationships.
Pricing Analysis
After-sales revenue from managed API services and extended compliance support contracts drives lifetime value beyond initial deployment fees. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade voice biometric stacks with EU AI Act certification from mid-market transcription APIs and basic IVR replacement tools. Cost compression in the standard tier is intensifying because foundation-model providers eliminate proprietary training data moats. Telecommunications carriers exhibit the highest price sensitivity due to seasonal volume volatility, while BFSI institutions in Germany and the United States absorb premium pricing for auditable decision-trail capabilities.
Supply Chain Analysis
Inventory buffers for AI accelerator hardware rarely exceed sixty days, exposing vendors to foundry allocation shocks. Supply concentrates in Taiwan and South Korea for GPU fabrication, with the United States anchoring cloud infrastructure deployment. Raw material dependencies span silicon wafers, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability in TSMC's advanced packaging capacity threatens inference cost stability for real-time speech workloads. Distribution runs through direct hyperscaler marketplaces and regional system integrators serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system classification creates a high-growth disruption as compliance-integrated speech stacks capture premium procurement budgets from legacy vendors lacking auditable decision-trail capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into GPU reservation pools and captive cloud regions, while accelerating EU AI Act certification investments to neutralize foundation-model challengers eroding transcription accuracy advantages. For New Entrants and Emerging Players: Lead with voice cloning detection modules targeting FCC-mandated financial services authentication flows, exploiting underpenetrated Canadian and Indian regional banking segments through API-first consumption models with minimal upfront deployment friction. For Investors and Strategic Acquirers: Carve-out targets emerge from healthcare-anchored biometrics divisions within diversified IT services conglomerates seeking to monetize HIPAA-compliant workflow integration. Watch for EU AI Act enforcement variance across member states as the inflection signal indicating which compliance-integrated stacks will capture accelerated procurement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Foundation Model Integration | Pre-trained acoustic models from OpenAI and Meta enable mid-tier providers to match incumbent transcription accuracy without decade-long audio corpora. |
| Hybrid Cloud Certification | Private-instance deployments with burst capacity address German and Canadian data sovereignty requirements while maintaining elastic cost structures. |
| Voice Biometric Enrollment Partnerships | Telecommunications carriers in India and the United States drive customer opt-in rates through passive sampling during natural conversation flows. |
| EU AI Act Compliance Engineering | Human-oversight trigger insertion before binding credit determinations satisfies conformity assessments for Dutch insurance and German automotive finance call centers. |
| Edge Inference Architecture | Containerized speech stacks reduce latency below 200 milliseconds for distributed agent workforces without dedicated physical infrastructure. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with contact center operations directors, conversational AI engineering leads, BFSI compliance officers, telecommunications procurement managers, and healthcare IT architects. Secondary validation drew from FCC robocall mitigation filings, EU AI Act implementation guidance, HIPAA business associate agreement templates, hyperscaler capex disclosures, and cloud API pricing benchmarks. Bottom-up deployment volume estimates were triangulated against top-down market sizing from infrastructure spend patterns.
Across the analysis window, the forecast framework modeled deployment mode transitions, technology layer adoption curves, vertical penetration intensity, and regional regulatory compliance premiums. Segmentation dimensions included product type, deployment architecture, end-user vertical, and technology stack composition. CAGRs were derived from fitted adoption curves calibrated to historical cloud migration velocity and GPU cost elasticity observations.
Forecasts assume regulatory continuity in EU AI Act enforcement, FCC robocall mitigation expansion, and HIPAA data residency constraints; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
South East Asia CRM Market
Customer Relationship Management (CRM)
Global Customer Success Management Market
Customer Relationship Management (CRM)
Global Customer Engagement Solutions Market
Customer Relationship Management (CRM)
Mobile CRM Market
Customer Relationship Management (CRM)
Key Opinion Leader Management Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Telecom CRM Market
Customer Relationship Management (CRM)
Global Salesforce CRM Document Generation Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Pharmaceutical CRM Software Market
Customer Relationship Management (CRM)
Loyalty Management Solutions Market
Customer Relationship Management (CRM)
Mortgage CRM Software Market
Customer Relationship Management (CRM)
CRM Outsourcing Market
Customer Relationship Management (CRM)
Global Partner Relationship Management Market
Customer Relationship Management (CRM)
Customer Relationship Management in Healthcare Market