
 Complaint Management Software Market | 2026-2036
Complaint Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Complaint Management Software Market Intelligence
Mid-market retail chains are collapsing into enterprise-grade complaint management platforms as legacy spreadsheet workflows fail PCI-DSS audit trails. Salesforce, Inc. leverages its CRM backbone to anchor multi-channel complaint intake across storefront and digital touchpoints. Zendesk, Inc. competes on agent experience design, while Oracle Corporation dominates in on-premise deployments for regulated manufacturing environments.
Complaint Management Software comprises digital platforms that capture, route, track, and resolve customer grievances through configurable workflows, typically integrating ticketing engines with SLA timers and escalation matrices. The technology serves commercial and institutional users by replacing fragmented email-and-spreadsheet systems with auditable resolution pipelines and root-cause analytics. Cloud-Based deployment leads in new customer acquisition due to lower capital requirements and faster implementation cycles, though On-Premise retains margin pools in financial services and defense-adjacent manufacturing where data sovereignty rules apply. The Analytics feature dimension is growing fastest as predictive complaint clustering and sentiment scoring displace reactive ticket handling.
FDA 21 CFR Part 820 quality system regulations and HIPAA privacy safeguards shape product requirements for healthcare complaint modules, while GDPR data-subject rights frameworks mandate erasure capabilities in European deployments. ISO 9001 certification audits drive standardized reporting templates across manufacturing end users. Stakeholders must weigh cloud migration timelines against evolving cross-border data localization statutes before committing to platform architecture decisions.
Market Dynamics
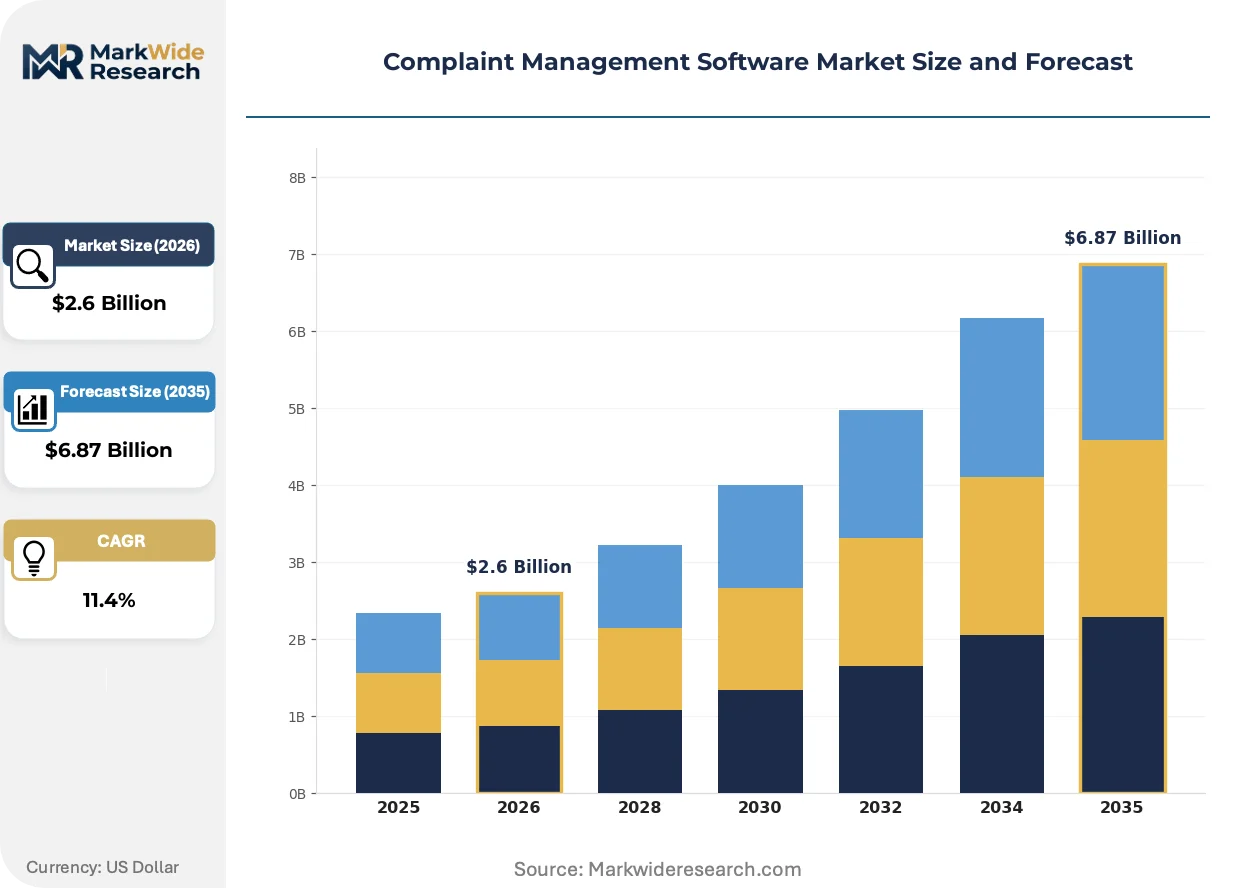
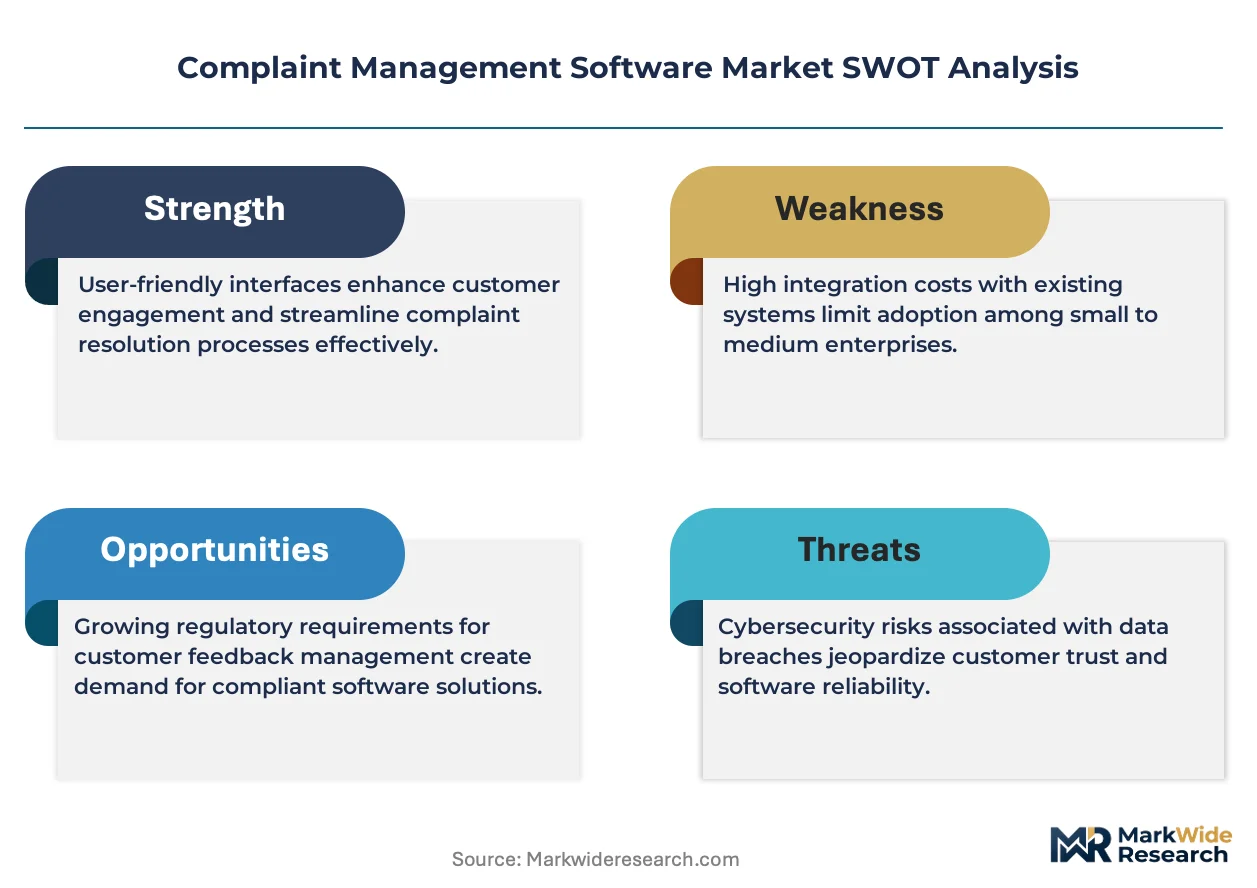
Cloud migration is compressing implementation timelines for complaint management platforms while HIPAA audit requirements force healthcare providers toward auditable digital workflows. Mid-market buyers now demand pre-configured compliance modules that eliminate custom development cycles.
Growth Catalysts
- HIPAA enforcement:Healthcare providers face escalating penalties for inadequate grievance documentation, accelerating replacement of paper-based complaint logs with timestamped digital systems.
- ISO 9001 certification:Manufacturing exporters require standardized non-conformance reporting to maintain supplier status with multinational OEMs, driving standardized platform adoption.
- PCI-DSS audit pressure:Retail chains must demonstrate secure customer data handling across complaint channels, collapsing fragmented spreadsheet systems into unified platforms.
Market Restraints
- Data localization statutes:Cross-border data transfer restrictions in Germany, France, and China fragment cloud architecture decisions and inflate compliance costs for multinational deployments.
- Legacy system entrenchment:On-premise Oracle and SAP installations in defense-adjacent manufacturing carry decade-long amortization cycles that resist SaaS migration.
- Specialized integration costs:Custom API development for ERP connectivity consumes 40-60% of implementation budgets, squeezing mid-market procurement decisions.
Strategic Opportunities
- GDPR Article 17 erasure:European data-subject rights create demand for automated deletion workflows that US-centric platforms lack, opening white space for compliance-first vendors.
- Predictive analytics convergence:Natural language processing integration with complaint clustering algorithms enables proactive quality intervention before escalation.
- India PLI scheme:Manufacturing incentives under the Production Linked Incentive program expand quality management software demand among domestic pharmaceutical and electronics producers.
Industry Challenges
- HIPAA Security Rule expertise:Shortage of compliance engineers capable of configuring access controls and audit trails delays healthcare deployments by 4-8 months.
- Multi-tenant architecture risks:Cloud providers struggle to demonstrate sufficient isolation between healthcare clients during FDA 21 CFR Part 820 inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complaint Management Software Market |
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Retail, Healthcare, Manufacturing, Hospitality Feature: Automated Workflow, Reporting, Integration, Analytics Compliance Standard: ISO 9001, Six Sigma, GDPR, HIPAA |
| Companies Covered | Salesforce, Inc., Zendesk, Inc., Oracle Corporation, SAP SE, Zoho Corporation, Freshworks Inc., Pegasystems Inc., NICE Ltd., Qualtrics XM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complaint Management Software Market Strategic Shifts & Innovations
Predictive complaint clustering is displacing reactive ticket handling across regulated industries, while regulatory frameworks harden data governance requirements. Platform vendors now compete on pre-built compliance templates rather than customization depth.
Sentiment scoring engines powered by transformer-based natural language processing are displacing keyword-based classification in enterprise complaint workflows. Healthcare providers and retail chains deploy these tools to flag escalations before SLA breaches occur. This capability is compressing average resolution times and reducing manual triage headcount.
GDPR data-subject rights enforcement is mandating automated erasure capabilities in European deployments, forcing architectural redesigns of audit trails. Vendors must now maintain cryptographic separation between deleted and retained records. Healthcare and financial services segments face the steepest reconfiguration costs.
Subscription-based procurement with outcome-linked pricing is replacing perpetual license models in mid-market retail and healthcare. Buyers now demand usage-based billing tied to resolved complaint volume rather than seat counts. This shift is most visible in United States hospital networks consolidating vendor relationships under value-based care contracts.
Complaint Management Software Market Segmentation
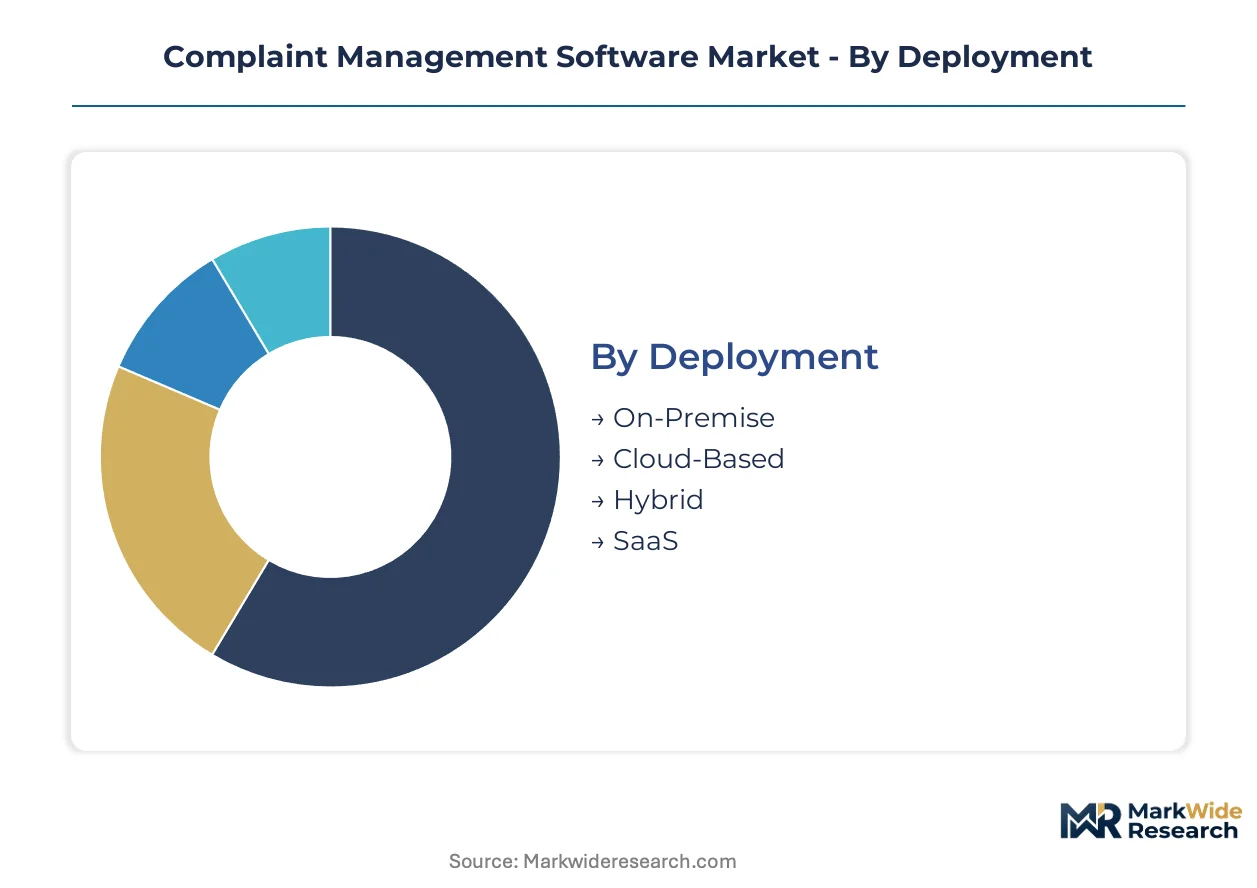
Complaint management software segments diverge sharply by technical architecture and regulatory exposure. Deployment mode determines capital intensity and compliance posture, while end-user verticals impose distinct workflow requirements and certification standards.
Deployment:
Channel mix splits between capital-light SaaS subscriptions favored by mid-market retail and hospitality, and perpetual-license on-premise systems retained by defense-adjacent manufacturing and financial services.
- Cloud-Based:Multi-tenant architectures with browser-based access eliminate server procurement cycles. United States hospital networks and retail chains concentrate demand here, driven by HIPAA audit requirements and PCI-DSS compliance deadlines that compress implementation timelines.
- SaaS:Subscription billing tied to resolved complaint volumes replaces seat-based pricing. Mid-market buyers in hospitality and retail procurement favor this model for its alignment with value-based care contracts and outcome-linked vendor relationships.
- On-Premise:Perpetual licenses with localized data storage serve manufacturing exporters requiring ISO 9001 audit trails and data sovereignty guarantees.
- Hybrid:Split architectures route sensitive records on-premise while leveraging cloud analytics layers, common among European healthcare providers navigating GDPR data-localization statutes.
By volume, Cloud-Based leads. By growth pace, SaaS is climbing the fastest.
End User:
Cost tier stratification separates enterprise-grade healthcare deployments from standardized retail implementations, with manufacturing occupying a mid-tier integration-heavy position.
- Healthcare:Patient grievance modules with FDA 21 CFR Part 820 quality system alignment and HIPAA Security Rule access controls. United States hospital networks drive demand as penalties for inadequate documentation escalate, forcing replacement of paper-based complaint logs.
- Retail:Multi-channel intake across storefront and digital touchpoints with PCI-DSS audit trail requirements. Mid-market chains collapsing fragmented spreadsheet systems into unified platforms represent the steepest expansion trajectory.
- Manufacturing:Non-conformance reporting with ISO 9001 standardized templates for supplier status maintenance with multinational OEMs.
- Hospitality:Guest feedback aggregation with sentiment scoring integration, typically deployed via SaaS models by hotel chains and restaurant groups.
Healthcare commands premium pricing. Retail shows the fastest volume expansion among verticals.
Feature:
Application maturity separates baseline ticketing from advanced predictive capabilities, with analytics modules commanding implementation budget priority in regulated environments.
- Analytics:Predictive complaint clustering and sentiment scoring powered by transformer-based natural language processing. Healthcare providers and retail chains deploy these tools to flag escalations before SLA breaches occur, compressing resolution times and reducing manual triage headcount.
- Automated Workflow:Configurable routing engines with SLA timers and escalation matrices. Manufacturing exporters require these capabilities for ISO 9001 certification audits, driving standardized platform adoption.
- Integration:API connectivity to ERP and CRM systems, consuming 40-60% of implementation budgets in mid-market procurement decisions.
- Reporting:Standardized audit templates for regulatory submission and root-cause documentation.
Analytics gains share fastest. Automated Workflow maintains the largest installed base.
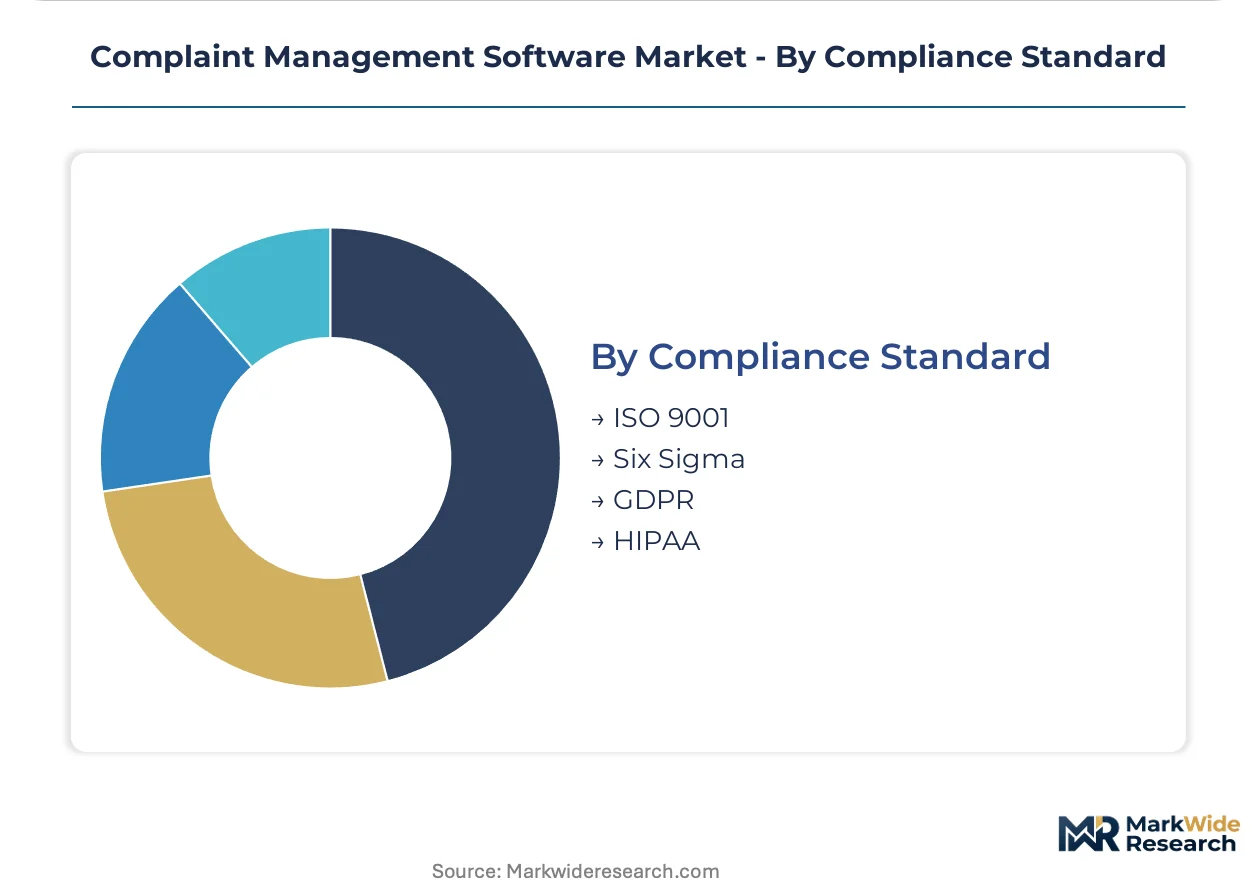
Compliance Standard:
Geography determines which certification frameworks dominate procurement specifications, with European deployments requiring capabilities absent from US-centric platforms.
- HIPAA:Privacy safeguards and Security Rule access controls mandatory for United States healthcare complaint modules. Shortage of compliance engineers capable of configuring audit trails delays deployments by 4-8 months.
- GDPR:Article 17 data-subject erasure rights mandating automated deletion workflows and cryptographic separation between deleted and retained records. European healthcare and financial services segments face steepest reconfiguration costs.
- ISO 9001:Quality management certification requirements driving standardized non-conformance reporting templates across manufacturing exporters.
- Six Sigma:Defect reduction methodologies applied to complaint volume and resolution time metrics in process-oriented manufacturing environments.
HIPAA specifications anchor the largest compliance-driven procurement volume. GDPR requirements are expanding most quickly as data-localization statutes tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based SaaS vendors export complaint management platforms to healthcare systems across Germany, Japan, and India, while European providers face data-localization barriers that fragment cross-border deployment architectures.
United States
Hospital networks in Texas and California are collapsing fragmented spreadsheet systems into unified cloud platforms ahead of HIPAA audit deadlines. FDA 21 CFR Part 820 quality system regulations force patient grievance modules to maintain timestamped digital audit trails. The Boston healthcare corridor drives specialized compliance engineering demand as penalties for inadequate documentation escalate.
Germany
Automotive suppliers in Baden-Württemberg require ISO 9001-certified non-conformance reporting to maintain OEM supplier status with multinational manufacturers. GDPR Article 17 erasure mandates force architectural redesigns of complaint audit trails with cryptographic separation between deleted and retained records. Munich-based manufacturing exporters concentrate demand for perpetual-license on-premise systems with data sovereignty guarantees.
India
Domestic pharmaceutical producers in Maharashtra and Gujarat are digitizing quality management workflows under the Production Linked Incentive scheme. CDSCO quality system regulations align with international standards for export-oriented manufacturers. Bangalore technology corridors host implementation specialists serving mid-market retail chains migrating from legacy systems.
Japan
Medical device manufacturers in the Kansai region deploy complaint tracking modules aligned with PMDA quality system requirements and METI digital transformation directives. Aging on-premise ERP installations in Osaka industrial zones resist SaaS migration due to decade-long amortization cycles. Tokyo hospital networks pilot predictive analytics integration with existing electronic health record infrastructures.
United Kingdom
Retail banking networks in London face FCA conduct rules requiring auditable complaint resolution pipelines with SLA documentation. GDPR data-subject rights frameworks mandate automated deletion workflows absent from US-centric platform architectures. Manchester and Birmingham mid-market chains consolidate vendor relationships under outcome-linked pricing contracts.
Complaint Management Software Market Key Industry Players
Listed leaders compete with private specialists across deployment architecture preferences, with public cloud vendors facing off against on-premise incumbents in regulated manufacturing environments. The vendor base splits between CRM-anchored platforms, standalone ticketing specialists, and ERP-integrated suites serving compliance-heavy verticals. Three archetypes dominate: cloud-native SaaS providers, legacy on-premise systems vendors, and vertical-specific compliance platforms. Consolidation pressures favor acquisition of niche compliance modules by broader enterprise software portfolios, while geographic expansion through localized data center partnerships addresses data sovereignty requirements.
Within the cloud-native tier, Salesforce, Inc. and Zendesk, Inc. occupy positions anchored to multi-channel intake capabilities across retail and healthcare touchpoints. Oracle Corporation exemplifies the on-premise archetype with perpetual-license retention in defense-adjacent manufacturing environments where data sovereignty rules apply. These three entities represent the dominant competitive positioning vectors: CRM-integrated cloud expansion, agent experience design specialization, and regulated industry entrenchment through localized infrastructure.
| Leading Market Players |
|---|
| Salesforce, Inc. |
| Zendesk, Inc. |
| Oracle Corporation |
| SAP SE |
| Zoho Corporation |
| Freshworks Inc. |
| Pegasystems Inc. |
| NICE Ltd. |
| Qualtrics XM |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure scale economies concentrate development costs among hyperscaler-backed vendors, compressing price floors for mid-market SaaS tiers while elevating premium pricing for HIPAA-compliant healthcare modules. This concentration simultaneously shapes supply chain vendor selection, as procurement teams prioritize API-ready platforms over custom integration builds.
Pricing Analysis
Legacy on-premise perpetual licenses command 3-4x first-year outlays versus cloud-native SaaS subscriptions, yet next-generation predictive analytics modules reverse this spread through value-based pricing tied to resolved complaint volumes. Pricing stratifies across enterprise healthcare deployments with FDA 21 CFR Part 820 certification, mid-market retail PCI-DSS tiers, and economy hospitality SaaS bundles. Price erosion runs through standardized retail implementations as Salesforce and Zendesk compete on seat-based economics. Healthcare providers show lowest price sensitivity due to penalty avoidance mandates, while hospitality chains face acute cost pressure from thin operating margins.
Supply Chain Analysis
Implementation lead times stretch 4-8 months for HIPAA-compliant healthcare deployments due to compliance engineer scarcity, while retail SaaS provisioning completes in weeks. Software development concentrates in the United States, India, and Ireland, with cloud infrastructure drawing from AWS, Azure, and Google Cloud data center networks. Supply chain risk centers on single-source vulnerability for specialized compliance modules serving FDA-regulated medical device manufacturers. Distribution runs through direct enterprise sales teams for healthcare and manufacturing, with self-service digital channels capturing mid-market retail and hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Complaint management platforms face a platform-economics inflection as CRM-anchored ecosystems absorb standalone ticketing vendors, with interoperability demands forcing API-first architecture bets.
For Market Incumbents: Consolidate around pre-built compliance templates that collapse implementation timelines for HIPAA and GDPR deployments. Acquire niche sentiment-scoring specialists to anchor predictive analytics roadmaps against cloud-native entrants. Vertical integration into compliance engineering talent pools defends margin position against implementation delay penalties.
For New Entrants and Emerging Players: Differentiate on automated erasure workflows for GDPR Article 17 mandates that US-centric platforms lack. Target European healthcare providers and financial services segments with cryptographic separation architectures. Pursue partnership-led go-to-market through localized data center operators navigating German and French data-localization statutes.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compliance-first vertical specialists over horizontal ticketing platforms. Long-term viability hinges on regulatory workflow depth rather than channel breadth. Acquisition target archetype: HIPAA-certified modules with FDA inspection track records. Watch for predictive analytics convergence with electronic health record infrastructures as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CRM-anchored ecosystems absorb standalone vendors through API interoperability mandates. |
| Acquisition of Specialist Firm | Sentiment-scoring NLP modules command premium valuations from healthcare compliance buyers. |
| Geographic Expansion | Localized data center partnerships address GDPR sovereignty requirements in Germany and France. |
| Product Launch | Automated erasure workflows capture European healthcare procurement specifications. |
| Strategic Partnership | Electronic health record vendor alliances accelerate predictive analytics deployment in hospital networks. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with healthcare compliance officers, retail IT procurement leads, manufacturing quality directors, and cloud platform engineers; and secondary validation against FDA 510(k) filings, HIPAA audit documentation, ISO 9001 certification registries, and hyperscaler SaaS revenue disclosures. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations across the analysis window.
Across the projection horizon, the analytical framework modeled deployment mode, end-user vertical, feature tier, and compliance standard segmentation dimensions. CAGRs derived from fitted growth curves calibrated to regulatory deadline clustering and cloud migration velocity. Forecast inputs incorporated HIPAA penalty escalation schedules and PCI-DSS audit cycle compression in retail.
Material uncertainties — regulatory enforcement intensity shifts, data-localization statute expansion, compliance engineer supply constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Customer Relationship Management (CRM)
Loyalty Management Market
Customer Relationship Management (CRM)
Customer Experience Management (CEM) in Telecommunication Market
Customer Relationship Management (CRM)
Call Center Market
Customer Relationship Management (CRM)
Social CRM Market
Customer Relationship Management (CRM)
Indonesia CRM Software Market
Customer Relationship Management (CRM)
Global Customer Relationship Management Market
Customer Relationship Management (CRM)
Contact Centers Speech Applications Market
Customer Relationship Management (CRM)
Global Customer Success Platforms Market
Customer Relationship Management (CRM)
Canada Customer Relationship Management Market
Customer Relationship Management (CRM)
CRM Application Software Market
Customer Relationship Management (CRM)
Client Onboarding Solutions Market
Customer Relationship Management (CRM)
Thailand CRM Market
Customer Relationship Management (CRM)
Enterprise Feedback Management Market
Customer Relationship Management (CRM)
Android CRM Software Market
Customer Relationship Management (CRM)
Cloud Customer Relationship Management (CRM) Market
Customer Relationship Management (CRM)
Collaborative Customer Interfaces Market