
 Cannabis Concentrate Market | 2026-2036
Cannabis Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Concentrate Market Analysis
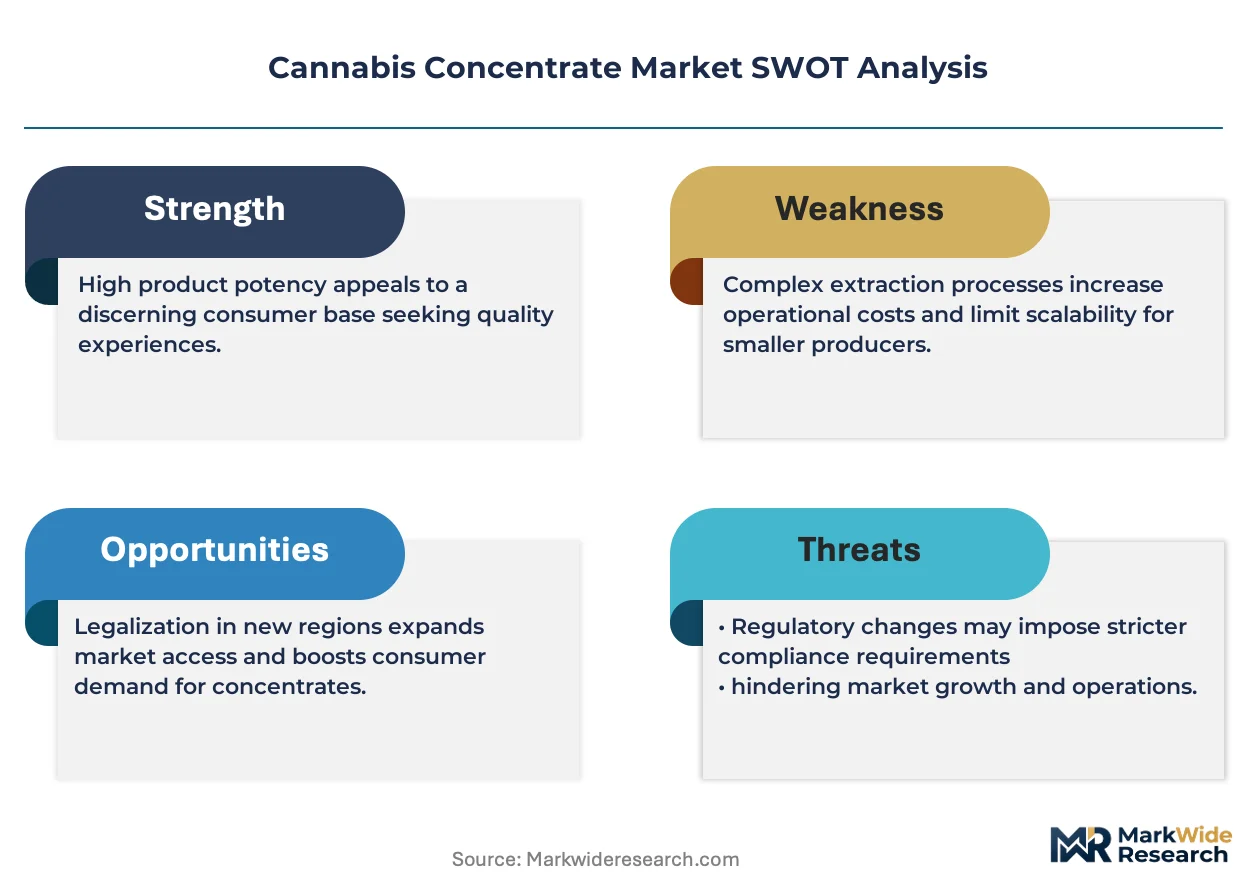
Good Manufacturing Practice certification for cannabis processing facilities is unwinding the competitive landscape by filtering out small-scale operators. Curaleaf leverages vertical integration across cultivation and retail to sustain pricing power in fragmented state markets. Green Thumb Industries anchors its position through controlled distribution networks in limited-license jurisdictions. Trulieve Cannabis dominates Florida's medical market with dense retail coverage and in-house extraction capacity.
Cannabis concentrates are highly potent extracts derived from cannabis plant material through mechanical or chemical separation, typically yielding tetrahydrocannabinol levels between 60% and 90% by weight. These products serve both recreational consumers seeking intensity and medical patients requiring precise dosing for chronic conditions. Wax and live resin segments command premium shelf positioning due to terpene preservation and artisanal production narratives. Solvent-based extraction still occupies the bulk of commercial volume, though rosin tech and ice water methods are capturing share among clean-label buyers. Recreational users drive the largest absolute demand pool, while medical patients generate higher per-unit margins and stronger repeat purchase rates.
FDA oversight of cannabis-derived pharmaceuticals and state-level track-and-trace systems such as Metrc shape product testing standards and supply chain transparency requirements. The EPA regulates pesticide residues on source biomass, directly affecting concentrate purity thresholds and extraction input costs. Stakeholders must monitor evolving state licensing caps and testing mandate expansions to anticipate margin compression points and geographic entry timing.
Market Dynamics
Solventless extraction technologies are decomposing the traditional competitive hierarchy by enabling small-scale operators to bypass capital-intensive hydrocarbon infrastructure and compete on purity narratives rather than scale economics.
Growth Catalysts
- Medical patient expansion:Chronic pain and oncology protocols in California, Colorado, and Canada are broadening therapeutic applications beyond recreational use, driving repeat purchase behavior and premium SKU uptake.
- Track-and-trace mandates:State-level systems such as Metrc are creating compliance infrastructure that rewards operators with integrated seed-to-sale software, filtering out informal supply.
- Rosin press diffusion:Small-batch mechanical extraction is capturing health-conscious buyers seeking clean-label concentrates without residual hydrocarbon concerns.
Market Restraints
- Input cost volatility:Biomass price swings in legacy cultivation states compress extraction margins when wholesale flower spikes coincide with finished goods price ceilings.
- Licensing concentration:Limited-license jurisdictions such as Florida and New York create artificial scarcity that favors incumbent vertically integrated operators over specialized extractors.
- EPA pesticide thresholds:Residue limits on source material force batch rejections and input testing costs that scale disproportionately for small processors.
Strategic Opportunities
- Canada federal framework:National legalization removes interstate friction entirely, enabling concentrate brands to build direct-to-patient subscription models without state-by-state adaptation.
- Veterinary therapeutics:Companion animal pain management represents an emerging application with minimal regulatory precedent and first-mover positioning potential.
- Pharmaceutical-grade isolates:FDA-registered API manufacturing opens white-label supply contracts to drug developers seeking cannabinoid inputs for clinical pipelines.
Industry Challenges
- Extraction technician scarcity:Skilled operators capable of hydrocarbon closed-loop management and terpene preservation command premium wages that strain mid-cap facility economics.
- Good Manufacturing Practice timelines:Certification for cannabis-specific processing requires 18-24 month validation cycles that delay revenue generation and investor returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Concentrate Market |
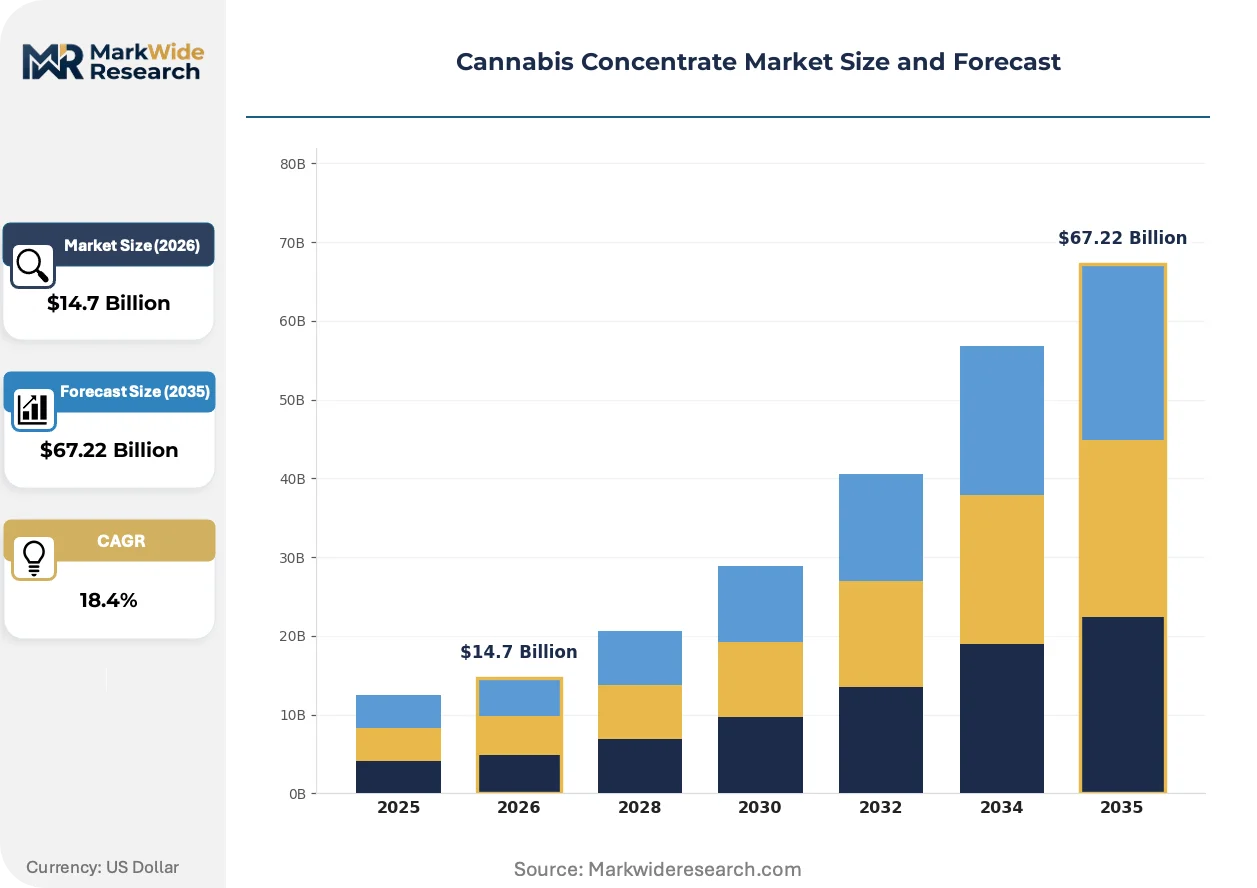
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $67.22 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wax, Oil, Shatter, Live Resin Extraction Method: Solvent-Based, CO2 Extraction, Rosin Tech, Ice Water End User: Recreational Users, Medical Patients, Dispensaries, Retailers Packaging Type: Glass Jars, Plastic Containers, Blister Packs, Pouches |
| Companies Covered | Curaleaf, Green Thumb Industries, Trulieve Cannabis, Cresco Labs, Tilray Brands, Canopy Growth Corporation, Cronos Group, Verano Holdings, Ascend Wellness Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Concentrate Market Emerging Trajectories
Technology diffusion is compressing the barrier between craft production and commercial scale, while regulatory fragmentation forces operators to build redundant compliance systems across state boundaries.
Cold-water hash and ice water extraction methods are decomposing the solvent-based volume dominance that has defined commercial concentrate production for two decades. Boutique cultivators in Humboldt County and the Emerald Triangle are adopting these mechanical systems to preserve volatile terpene profiles and market small-batch live rosin at 40-60% premiums over hydrocarbon equivalents. This shift is decomposing the capital-advantage hierarchy that previously favored large-scale butane extraction facilities, enabling terroir-based branding to compete with scale economics.
Health Canada's Good Production Practice requirements for cannabis processing are mandating pharmaceutical-grade cleanroom standards that exceed most US state requirements. Licensed processors must implement environmental monitoring, batch testing protocols, and sanitation validation that mirror biologics manufacturing. Canadian concentrate exporters to Germany and Australia are adapting to these standards fastest, creating a quality-tier segmentation that disadvantages US operators lacking equivalent certification infrastructure.
Medical patients are consolidating purchase decisions around dispensaries with in-house extraction and third-party lab verification, displacing the legacy model of multi-brand wholesale distribution. Florida's vertical license structure accelerates this concentration, as Trulieve and similar operators bundle consultation, product, and dosing guidance into single-point relationships. This behavioral shift is most visible in limited-license states where regulatory design inherently restricts competitive retail density.
Cannabis Concentrate Market Segmentation
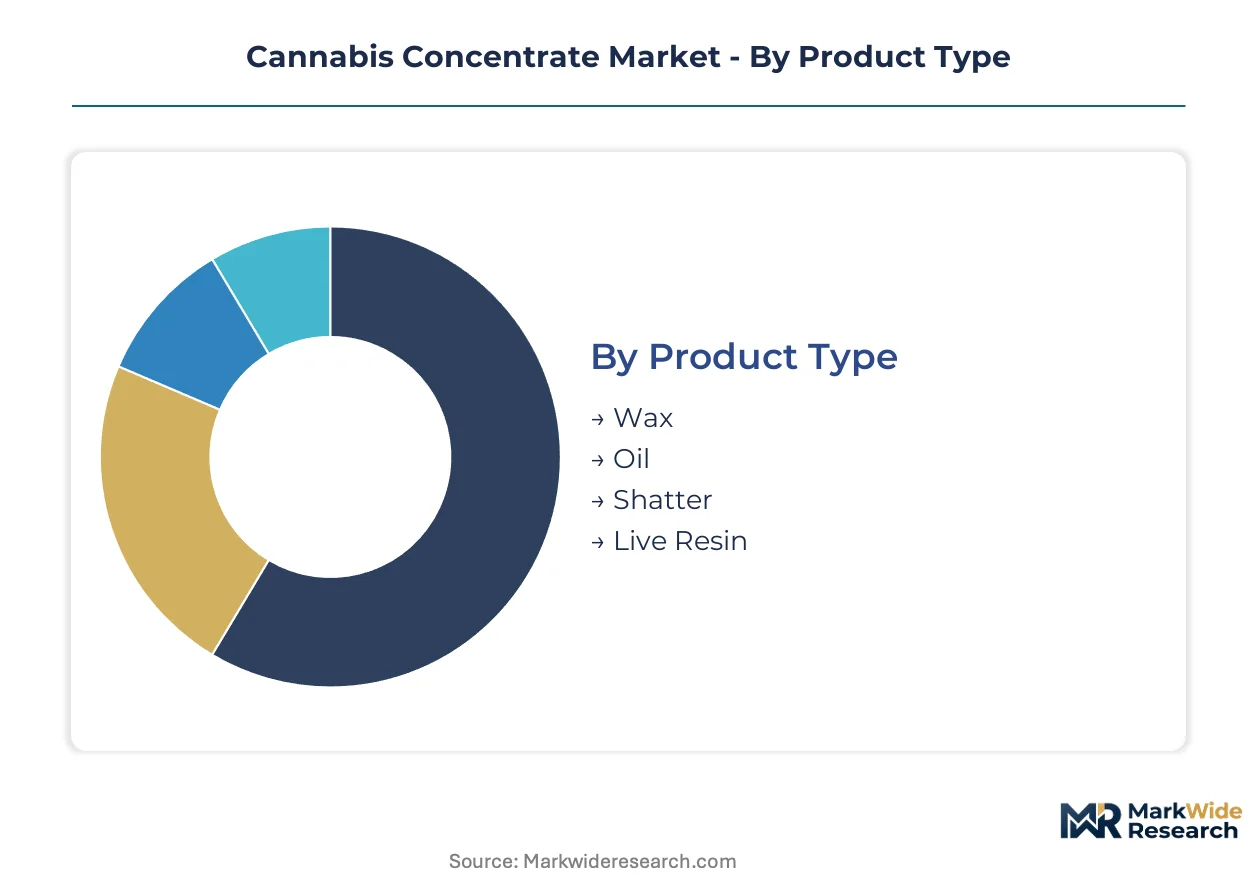
Cannabis concentrate segmentation reflects divergent supply chain economics and regulatory exposure across product formats. Extraction technology and end-user channel determine margin structure, compliance burden, and geographic addressability.
Product Type:
Dispensary shelf placement and wholesale pricing tiers flow through product consistency and terpene preservation credentials.
- Wax:Opaque, malleable extract with 60-80% THC concentration and visible crystalline structure. California and Colorado recreational dispensaries move the highest volumes, driven by price-accessible positioning and established consumer familiarity with dabbing consumption.
- Live Resin:Flash-frozen plant extraction preserves complete terpene profiles, commanding 40-60% premiums over cured-flower equivalents. Humboldt County craft operators and Canadian LPs target connoisseur segments through small-batch positioning and strain-specific marketing narratives.
- Oil:Fluid consistency optimized for vaporizer cartridge filling and sublingual application. Canadian federal distribution channels and US medical programs favor this format for standardized dosing and child-resistant packaging compatibility.
- Shatter:Brittle, translucent slab with glass-like fracture properties requiring precise temperature control during processing. Legacy hydrocarbon extraction facilities in Colorado and Washington maintain volume leadership despite rosin competition.
Live resin dominates installed base. Wax is where expansion concentrates.
Extraction Method:
Capital intensity and technician certification requirements stratify competitive entry across mechanical and chemical approaches.
- Solvent-Based:Butane and propane closed-loop systems yield 15-20% efficiency advantages over mechanical alternatives. Large-scale processors in Colorado and California leverage this scale economics to supply white-label volumes for multi-state retail chains.
- Rosin Tech:Heat and pressure mechanical extraction eliminates residual solvent testing requirements. Small-batch operators in the Emerald Triangle and Canadian craft sector capture health-conscious buyers through clean-label positioning and artisanal production narratives.
- CO2 Extraction:Supercritical fluid systems deliver pharmaceutical-grade consistency for medical formulations and FDA-registered API manufacturing. Health Canada GPP-certified facilities favor this method for export qualification to Germany and Australia.
- Ice Water:Cold-water hash separation preserves volatile terpenes through mechanical agitation without hydrocarbon exposure. Boutique cultivators in Mendocino County and British Columbia's Fraser Valley deploy this for premium live rosin SKUs.
Solvent-based methods anchor commercial volume. Rosin tech is climbing the fastest.
End User:
Channel access restrictions and purchasing behavior create distinct margin profiles across direct and intermediated demand.
- Medical Patients:Chronic pain and oncology protocols in Florida, California, and Canada drive repeat purchase behavior with higher per-unit margins. Vertical license structures bundle consultation and dosing guidance into single-point relationships.
- Recreational Users:California, Colorado, and Canadian adult-use markets generate absolute volume leadership through dispensary retail and delivery platforms. Price sensitivity concentrates in this segment during wholesale flower price spikes.
- Dispensaries:Limited-license jurisdictions such as Florida and New York create captive procurement relationships with in-house extraction capacity.
- Retailers:Multi-state operators in Colorado and Washington negotiate white-label supply contracts with specialized processors.
Recreational users anchor transaction volume. Medical patients represent the steepest expansion trajectory.
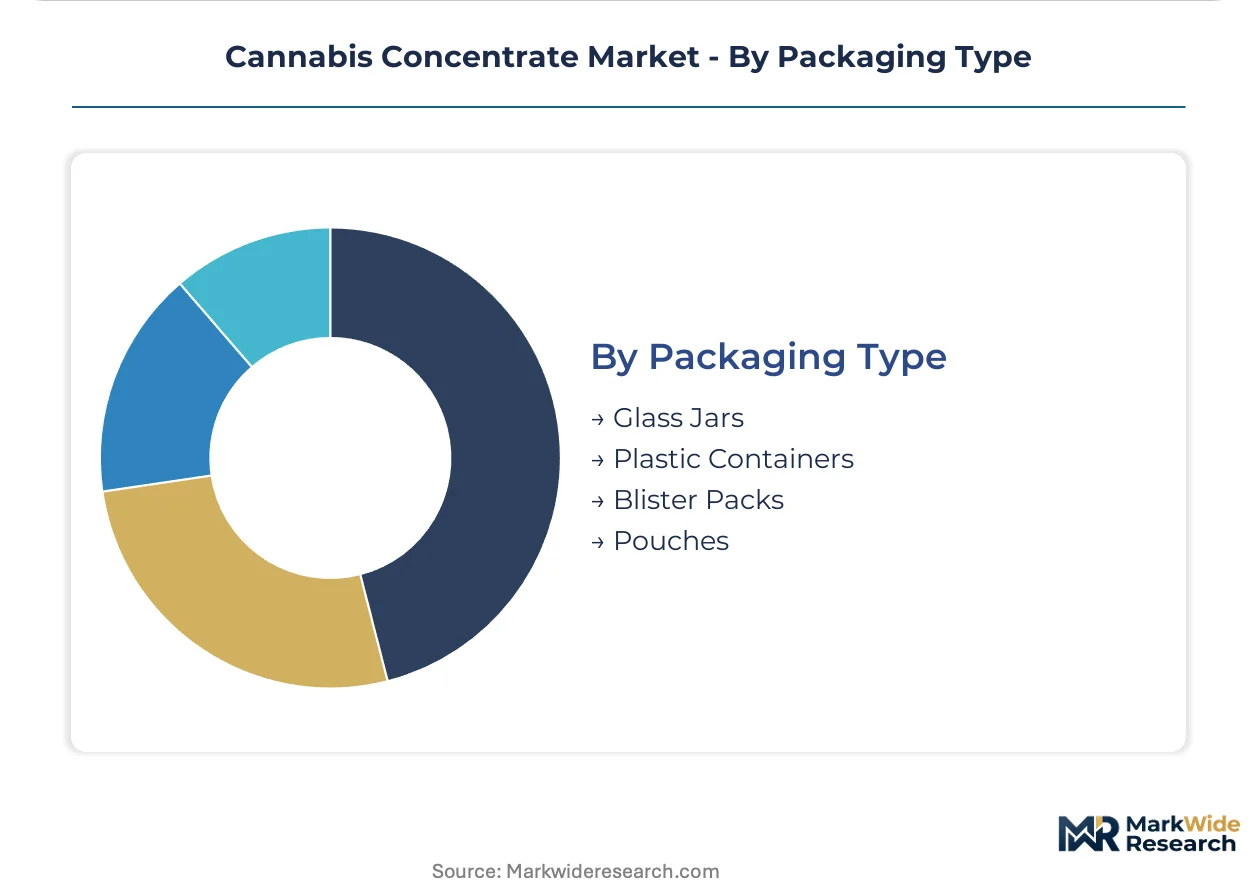
Packaging Type:
Child-resistant compliance and terpene preservation requirements determine material selection and unit economics.
- Glass Jars:Inert surface chemistry prevents terpene degradation and supports premium shelf positioning. California and Colorado concentrate brands specify borosilicate for live resin and rosin SKUs.
- Plastic Containers:Polypropylene and polystyrene formats reduce unit costs for high-volume wax and shatter distribution. Canadian LPs favor this for federal supply chain standardization.
- Blister Packs:Individual dose sealing meets pharmaceutical-grade stability requirements for medical formulations.
- Pouches:Flexible film barriers enable single-serve sampling and travel-sized SKUs for tourism-dependent markets.
Glass jars dominate premium positioning. Plastic containers anchor mass-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal frameworks in Canada and state-level licensing regimes in the United States are the primary policy levers shaping concentrate production geography and cross-border trade potential.
United States
California and Colorado host the deepest concentrate infrastructure, with Humboldt County craft operators competing against Denver-scale hydrocarbon processors. FDA oversight of cannabis-derived pharmaceuticals and EPA pesticide residue limits on source biomass create dual compliance burdens. Florida's vertical license structure concentrates extraction capacity within Trulieve's in-house facilities, limiting third-party processor entry.
Canada
Health Canada's Good Production Practice requirements mandate pharmaceutical-grade cleanroom standards exceeding most US state regimes. Licensed processors in British Columbia's Fraser Valley and Ontario deploy CO2 and ice water methods for export qualification to Germany and Australia. Federal legalization removes interstate friction entirely, enabling direct-to-patient subscription models without state-by-state adaptation.
Germany
The country's national pharmaceutical regulator oversees medical cannabis imports through a tightly controlled distribution channel. German pharmacies require GMP-certified concentrates for chronic pain and oncology protocols, favoring Canadian suppliers with established certification infrastructure. Berlin and Hamburg serve as importation and quality testing hubs for EU redistribution.
Australia
The Therapeutic Goods Administration's Special Access Scheme drives demand for pharmaceutical-grade isolates and standardized oil formulations. Victorian and New South Wales cultivation zones supply biomass to domestic processors, though GMP certification gaps limit local concentrate manufacturing relative to import dependence.
Israel
The Ministry of Health's medical cannabis program permits domestic cultivation and extraction for research and patient access. Tel Aviv-area biotechnology clusters host pilot facilities developing cannabinoid isolates for clinical trial export, though scale remains constrained by population limits and regional trade restrictions.
Cannabis Concentrate Market Vendor Landscape
Player mix skews toward vertically integrated multi-state operators with captive cultivation and retail networks. Concentrate specialists compete through extraction technology differentiation and white-label supply contracts. Three archetypes dominate: scale-driven hydrocarbon processors serving wholesale channels, craft rosin producers commanding terpene premiums, and pharmaceutical-grade isolators targeting medical and export markets. Competitive intensity concentrates on licensing acquisition in limited-license jurisdictions and GMP certification timelines for international qualification.
Within the vertically integrated tier, Curaleaf and Green Thumb Industries exemplify the US multi-state operator model combining cultivation density with controlled distribution. Trulieve Cannabis anchors Florida's medical market through dense retail coverage and in-house extraction capacity. Tilray Brands occupies a position bridging North American recreational supply with European pharmaceutical export certification, representing the international qualification archetype.
| Leading Market Players |
|---|
| Curaleaf |
| Green Thumb Industries |
| Trulieve Cannabis |
| Cresco Labs |
| Tilray Brands |
| Canopy Growth Corporation |
| Cronos Group |
| Verano Holdings |
| Ascend Wellness Holdings |
| Others |
Supply Flow & Price Mechanics
Rosin press technology substitution for hydrocarbon extraction is redistributing supply geography toward Humboldt County craft operators while collapsing the historical scale-premium correlation that rewarded large-scale butane processors with pricing power.
Pricing Analysis
Certification level creates the primary spread between Health Canada GPP-certified live resin and uncertified hydrocarbon wax. Three-tier pricing structure across premium, standard, and economy levels segments by terpene preservation credentials, batch testing depth, and retail channel access. Price erosion runs through wax segments as biomass oversupply in legacy cultivation states compresses extraction margins. Recreational users in California and Colorado exhibit highest price sensitivity, while Florida medical patients under vertical license structures show lowest elasticity due to bundled consultation and dosing guidance.
Supply Chain Analysis
Strait of Hormuz transit analogies illuminate how California's Emerald Triangle biomass chokepoint underwrites concentrate pricing volatility across North American markets. Supply concentrates in California, Colorado, and British Columbia's Fraser Valley as primary biomass zones, with German and Australian import channels as secondary processing destinations. Raw material dependencies rest on flash-frozen flower inputs, hydrocarbon solvents, and pharmaceutical-grade packaging substrates. Single-source vulnerability concentrates in limited-license jurisdictions where vertical integration locks out third-party processors. Distribution runs through dispensary retail networks in limited-license states and direct-to-patient subscription models in Canada's federal framework.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through Good Manufacturing Practice certification creates switching costs that pharmaceutical-grade buyers cannot circumvent without 18-24 month revalidation cycles.
For Market Incumbents: Consolidate extraction capacity in limited-license jurisdictions before licensing caps harden. Acquire rosin tech specialists in Humboldt County and the Emerald Triangle to capture terpene premium segments. Deepen backward integration into controlled-environment agriculture to buffer biomass price volatility. Secure Health Canada GPP certification ahead of European export qualification requirements.
For New Entrants and Emerging Players: Differentiate on solventless extraction narratives targeting health-conscious medical patients in Florida and Canada. Target veterinary therapeutics as a white-space application with minimal incumbent presence and first-mover positioning potential. Pursue white-label supply contracts with multi-state operators lacking in-house extraction capacity. Emphasize clean-label positioning through ice water and mechanical press methods.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hydrocarbon processors facing margin compression from rosin competition. Long-term viability favors operators with dual certification infrastructure spanning US state compliance and Health Canada GPP standards. Watch for inflection signals in FDA cannabis-derived pharmaceutical guidance timelines that would revalue pharmaceutical-grade isolate manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | Health Canada GPP validation opens German pharmacy distribution channels for chronic pain formulations. |
| Solventless Capacity Expansion | Ice water and rosin press deployment captures terpene premiums in California connoisseur segments. |
| Vertical License Acquisition | Florida and New York limited-license structures create captive patient relationships with bundled services. |
| Pharmaceutical-Grade Isolate Production | FDA-registered API manufacturing enables white-label supply to clinical trial sponsors and drug developers. |
| Direct-to-Patient Subscription Launch | Canada's federal framework removes interstate friction for concentrate brands building recurring revenue models. |
Methodological Framework
Operator-level perspectives from extraction facility managers, dispensary procurement directors, regulatory compliance officers, and medical patient advocacy groups anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Health Canada licensing databases, FDA cannabis-derived pharmaceutical guidance documents, state-level Metrc track-and-trace disclosures, and EPA pesticide residue monitoring reports. Bottom-up facility capacity assessments triangulated against top-down market sizing from biomass cultivation statistics and finished goods distribution records.
Sensitivity analysis around biomass price volatility and licensing timeline scenarios shaped the forecast framework. Segmentation dimensions modeled include product type, extraction method, end-user channel, and geographic regulatory cluster across the analysis window. CAGRs derived from historical volume trajectories adjusted for state-level legalization momentum and medical program expansion rates. Forecast inputs incorporated hydrocarbon input cost indices and pharmaceutical certification pipeline data.
Material uncertainties — FDA rescheduling decisions, state licensing cap revisions, and EPA pesticide threshold adjustments — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory continuity and biomass supply stability. Practitioners should keep alternative scenarios live as federal policy coordination and international trade qualification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Thailand Legal Cannabis Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Technology Market
Cannabis/Marijuana
Cannabis Lighting Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Asia-Pacific CBD Patch Market
Cannabis/Marijuana
Cannabis Pharmaceuticals Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Europe Medical Cannabis Market