
 Butane Hash Oil Market | 2026-2036
Butane Hash Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Butane Hash Oil Market Analysis
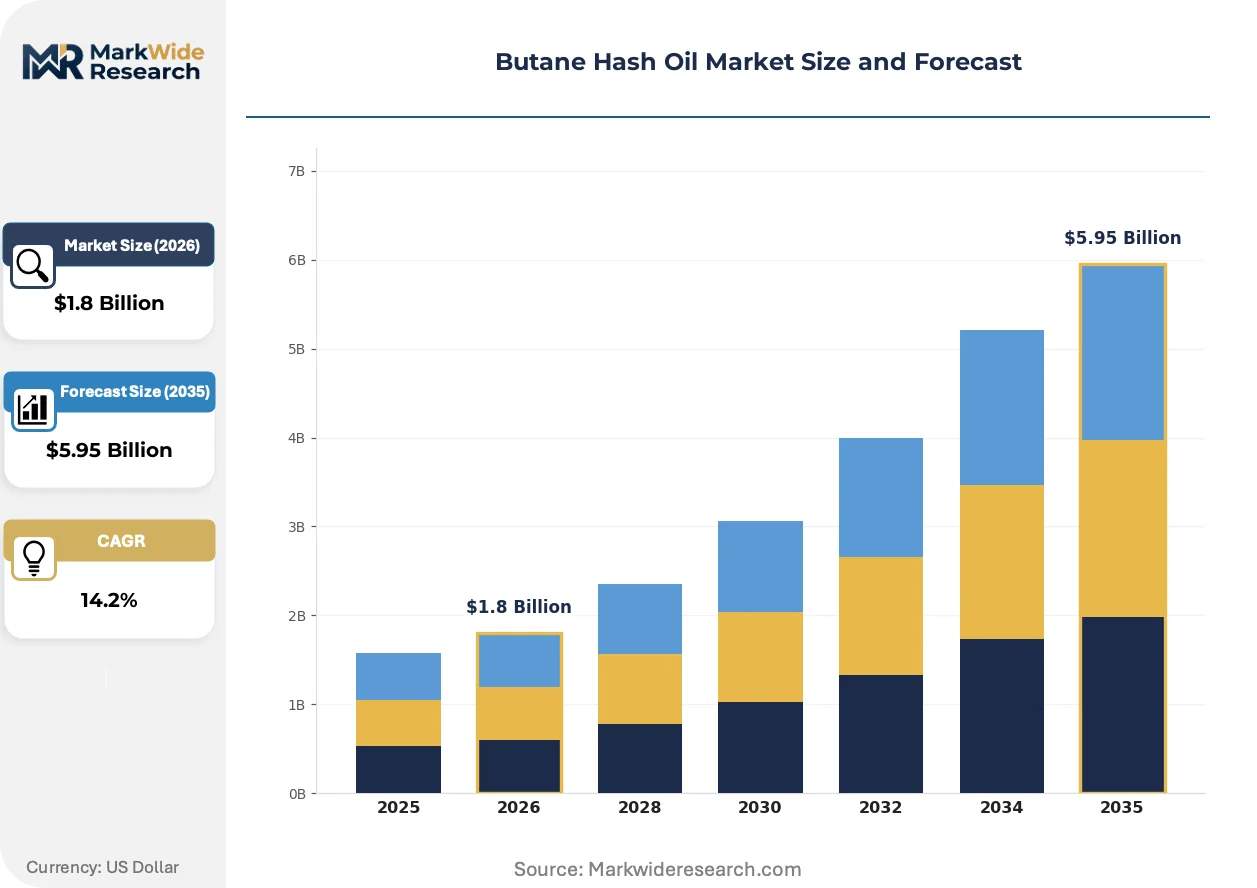
Asset-light extraction tolling and white-label manufacturing is reconfiguring capital requirements for new entrants in the Butane Hash Oil Market. Curaleaf Holdings leverages vertical integration from biomass cultivation through retail distribution to sustain margin capture across the value chain. Green Thumb Industries anchors its position through controlled-environment agriculture paired with in-house hydrocarbon extraction infrastructure. Trulieve Cannabis Corp. specializes in medical-market formulations, navigating stricter testing protocols that vary by state jurisdiction.
Butane hash oil refers to cannabis concentrates produced through hydrocarbon extraction using n-butane or isobutane as a solvent, typically yielding resinous extracts with cannabinoid concentrations exceeding 70% by weight. The process employs closed-loop systems with passive or active recovery to recapture solvent and mitigate ignition hazards in commercial settings. Concentrates dominate product type revenue pools due to established dabbing culture and dispensary shelf presence across mature state markets. Vapes represent the fastest-growing delivery format, as inhalation devices attract transitioning flower consumers seeking discretion and dose consistency. Medical patients and recreational users split end-user demand, with medical segments commanding premium pricing in states requiring physician certification.
State cannabis regulators in California, Colorado, and Michigan enforce residual solvent limits, batch-level testing, and packaging standards that determine which products reach licensed retailers. The FDA maintains federal prohibition, creating interstate commerce barriers that fragment supply chains and complicate multi-state operator strategies. OSHA workplace safety standards and state fire marshal codes govern extraction facility design, pressurized equipment certification, and employee training requirements. Stakeholders must monitor evolving state legislative sessions and potential federal rescheduling proceedings that could reshape banking access, tax treatment, and interstate distribution frameworks.
Market Dynamics
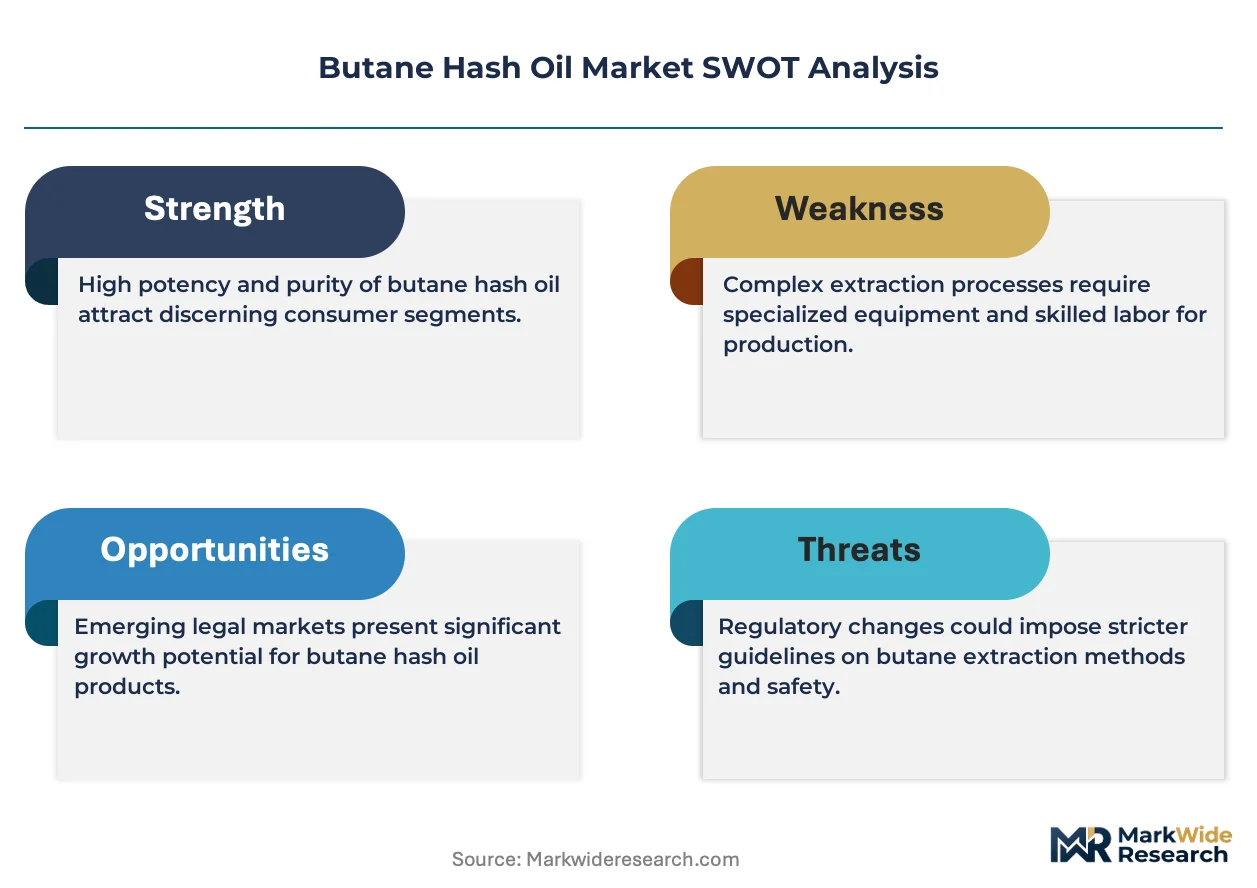
Closed-loop hydrocarbon extraction infrastructure is concentrating capital deployment among licensed operators, squeezing small-batch producers out of compliance-heavy state markets. Equipment certification costs and fire marshal inspections now filter market entry more than solvent access or biomass supply.
Growth Catalysts
- California Bureau of Cannabis Control testing mandates:Batch-level residual solvent screening and terpene profiling requirements drive demand for laboratory-grade extraction systems that guarantee reproducible output.
- Vape cartridge formulation advances:Ceramic coil technologies and precision filling equipment enable cannabinoid concentrations above 80% by weight in inhalable formats.
- Michigan medical registry expansion:Patient enrollment growth concentrates demand for high-potency concentrates in Detroit, Grand Rapids, and Ann Arbor metropolitan procurement zones.
Market Restraints
- Butane supply chain volatility:Petrochemical feedstock price swings and regional fuel-grade shortages compress margins for non-integrated extractors lacking volume purchase agreements.
- FDA Schedule I classification:Federal prohibition blocks interstate commerce, fragments supply chains, and denies standard banking services to hydrocarbon extraction facilities.
- CO2 extraction substitution:Supercritical systems attract capital from risk-averse investors seeking solvent-free marketing claims and simplified regulatory pathways.
Strategic Opportunities
- Colorado social equity licensing:State-mandated ownership set-asides for communities impacted by prohibition create first-mover positions for new entrants in Denver and Pueblo extraction zones.
- Minor cannabinoid isolation:CBG and CBN concentrate streams command pharmaceutical-grade pricing from wellness formulators seeking non-THC active ingredients.
- Direct-to-patient delivery channels:State-authorized courier services in California bypass retail markup, capturing margin previously allocated to dispensary shelf fees.
Industry Challenges
- Extraction technician certification gaps:OSHA-compliant hydrocarbon handling credentials remain scarce, forcing operators to poach talent from petroleum refinery and chemical process industries.
- Legacy facility retrofit timelines:Converting open-blasting operations to closed-loop C1D1 rated environments demands 18-24 month capital deployment cycles before licensure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butane Hash Oil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Edibles, Tinctures, Vapes Delivery Mode: Oral, Inhalation, Sublingual, Topical End User: Recreational Users, Medical Patients, Retail Shops, Distributors Packaging Type: Glass Jars, Syringes, Vape Cartridges, Pouches |
| Companies Covered | Curaleaf Holdings, Inc., Trulieve Cannabis Corp., Green Thumb Industries Inc., Canopy Growth Corporation, Aurora Cannabis Inc., Tilray, Inc., Cronos Group Inc., Verano Holdings, TerrAscend Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butane Hash Oil Market Emerging Trajectories
Automation and solvent recovery efficiency are compressing unit economics for commercial extractors. Process control systems now dominate competitive differentiation more than strain selection or branding.
Automated hydrocarbon extraction skids with integrated chilling loops and inline dewaxing are virtualizing manual winterization steps. Mid-scale operators in Colorado and Michigan adopt these systems to reduce labor headcount by 40% while maintaining throughput. This virtualization of post-processing labor is compressing the viable scale floor for commercial operations.
OSHA Process Safety Management standards and state fire marshal C1D1 electrical classification requirements are mandating explosion-proof equipment specifications. Facility designers must specify NEMA 7 enclosures and gas detection interlocks before occupancy permits issue. California operators face the strictest enforcement, with Los Angeles County requiring third-party peer review of extraction room ventilation calculations.
White-label tolling contracts are displacing captive manufacturing among multi-state operators. Brand holders now outsource hydrocarbon processing to licensed third parties, converting fixed extraction infrastructure costs into variable per-gram fees. This procurement model shift is most visible in Michigan, where asset-light brands capture retail shelf space without cultivation or processing capital deployment.
Butane Hash Oil Market Segmentation
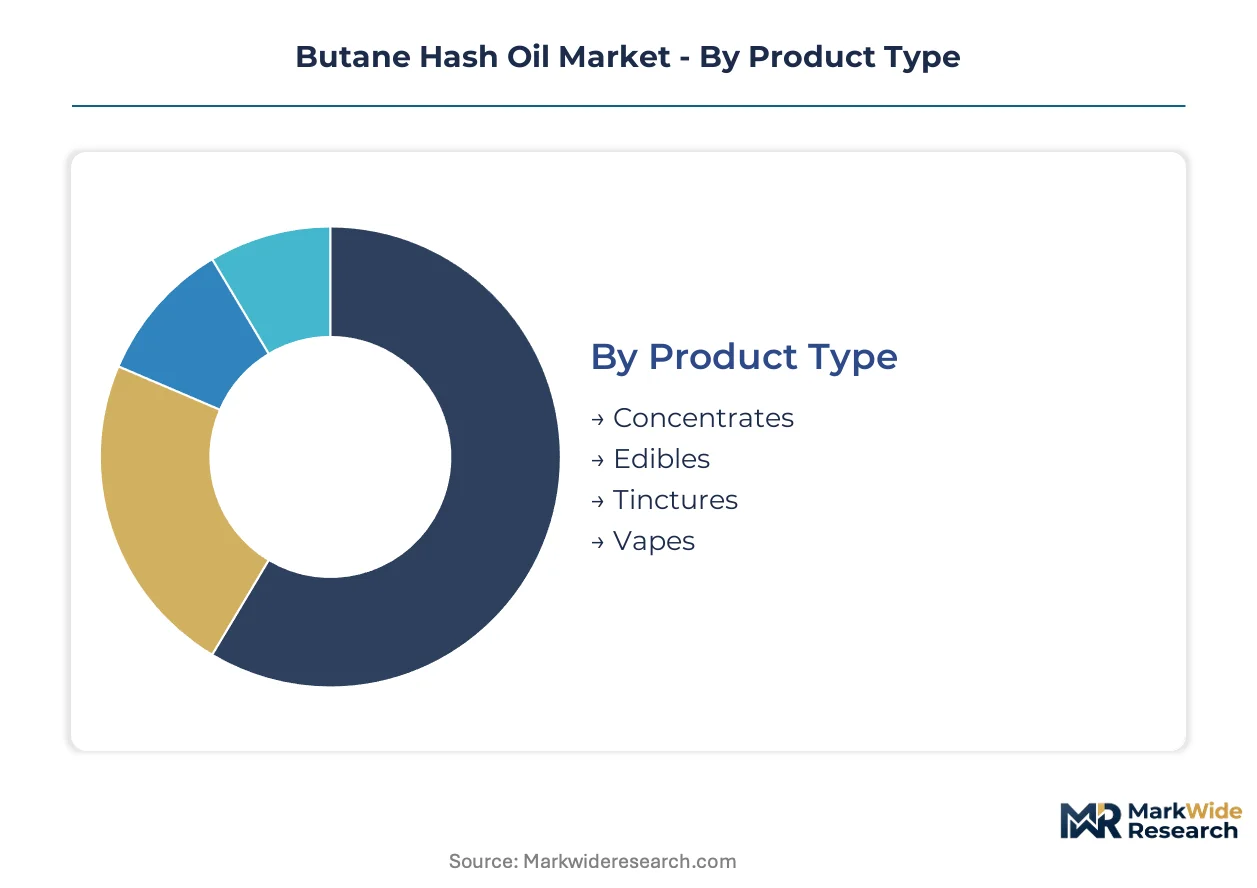
Product heterogeneity in butane hash oil markets creates distinct margin profiles and inventory velocity patterns. Each segment category demands specialized extraction protocols, compliance frameworks, and distribution channel configurations that determine competitive positioning.
Product Type:
Cycle times vary dramatically across concentrate formats, with vape cartridges turning inventory weekly while tinctures sit for months. Shelf stability and consumer purchase frequency separate rapid-turnover segments from slower-moving inventory pools.
- Concentrates:Resinous extracts with cannabinoid concentrations exceeding 70% by weight, typically consumed through dabbing or vaporization. California dispensaries and Colorado provisioning centers move the highest concentrate volumes, driven by established dabbing culture and terpene-forward product differentiation. Dab rigs and e-nails concentrate demand in urban coastal markets.
- Vapes:Ceramic coil cartridges filled with winterized hydrocarbon extracts, offering discretion and dose consistency for transitioning flower consumers. Michigan's medical registry expansion and Detroit metropolitan procurement zones absorb the steepest volume climbs in this category. Inhalation devices attract users seeking odor control and portability.
- Edibles:Infused food products incorporating decarboxylated BHO distillate for precise cannabinoid dosing.
- Tinctures:Alcohol or oil-based suspensions of activated cannabinoids for sublingual absorption.
Concentrates anchors the volume base while Vapes gains share at the steepest rate.
Delivery Mode:
Cost tiers separate inhalation devices commanding premium pricing from oral formats competing on per-dose economy. Regulatory scrutiny intensity varies by delivery pathway, with inhalation facing stricter residual solvent testing protocols.
- Inhalation:Pulmonary absorption through vaporized or combusted concentrates, delivering rapid onset and bioavailability. California Bureau of Cannabis Control mandates batch-level residual solvent screening specifically for inhalable products, driving laboratory-grade extraction system investments. Dispensary shelf placement prioritizes inhalable formats in mature markets.
- Oral:Gastrointestinal absorption via infused edibles and capsules, with delayed onset but extended duration. Colorado and Michigan recreational consumers favor oral formats for social settings where smoking restrictions apply. Discrete consumption patterns expand addressable occasions beyond traditional cannabis use contexts.
- Sublingual:Mucosal absorption beneath the tongue for intermediate onset timing.
- Topical:Transdermal application of cannabinoid-infused creams and balms for localized effects.
Oral formats capture the broadest addressable consumer base while Inhalation commands the highest per-gram realized pricing.
End User:
Customer type determines pricing power and compliance burden, with medical patients requiring physician certification and retail shops demanding volume discounts. Procurement authority and decision velocity separate individual consumers from institutional buyers.
- Recreational Users:Adult-use consumers purchasing without medical certification, prioritizing potency, flavor profiles, and brand recognition. California and Colorado recreational dispensaries concentrate the largest recreational BHO volumes, with purchase patterns tracking seasonal tourism and local event calendars. Brand loyalty forms around consistent terpene preservation and predictable effects.
- Medical Patients:State-registered consumers with physician recommendations, accessing higher potency limits and tax exemptions in certain jurisdictions. Michigan's expanding medical registry and Detroit-area provisioning centers drive concentrated demand for high-THC formulations. Stricter testing protocols and documentation requirements elevate compliance costs for medical-market SKUs.
- Retail Shops:Licensed dispensaries and provisioning centers purchasing wholesale inventory for resale to end consumers.
- Distributors:Third-party logistics providers handling bulk transport and storage between processors and retail endpoints.
Recreational Users generates the highest absolute transaction volume while Medical Patients sustains the most durable pricing premiums.
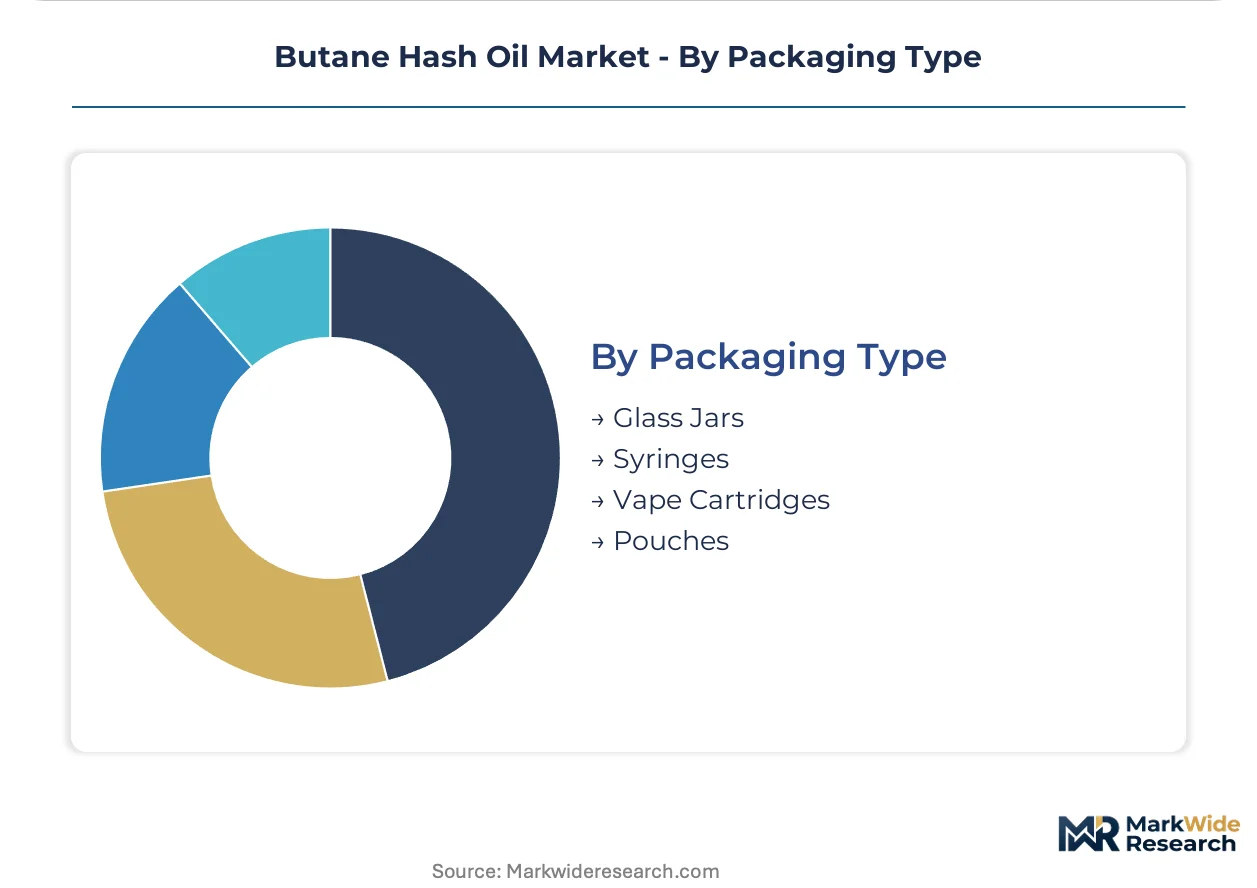
Packaging Type:
Supply concentration clusters around child-resistant formats meeting state-specific testing mandates, with material costs and regulatory compliance separating premium from economy positioning. Packaging innovation cycles faster in vape formats than stable concentrate containers.
- Vape Cartridges:Ceramic or cotton-wick atomizers in 510-thread or proprietary formats, requiring precision filling equipment and leak-resistant seals. California mandates comprehensive heavy metals testing for vape hardware, eliminating low-cost import suppliers from compliant supply chains. Michigan and Colorado operators invest in automated filling lines to achieve the throughput volumes retail buyers demand.
- Glass Jars:Borosilicate containers with child-resistant lids for viscous concentrates like shatter and wax. Colorado and California concentrate producers favor glass for terpene preservation and premium shelf presentation. Weight-based tax regimes in certain jurisdictions favor lighter packaging alternatives.
- Syringes:Medical-grade applicators for precise dosing of distillate and sauce products.
- Pouches:Flexible barrier films for single-serve edibles and discrete concentrate portions.
Glass Jars anchors the volume base while Vape Cartridges climbs the fastest as inhalation devices displace combustion formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level cannabis legalization frameworks are determining where hydrocarbon extraction infrastructure deploys, with patient registry expansions and recreational licensing waves directing capital toward compliant manufacturing zones.
United States
California's Bureau of Cannabis Control enforces the nation's strictest residual solvent testing mandates, driving laboratory-grade closed-loop system investments across Los Angeles and Oakland extraction clusters. Michigan's medical registry growth concentrates demand in Detroit and Grand Rapids metropolitan procurement zones. Colorado's social equity licensing set-asites are creating first-mover positions in Denver and Pueblo hydrocarbon processing facilities.
Canada
Health Canada's Cannabis Act licensing framework permits hydrocarbon extraction under Good Production Practice standards, with Alberta and British Columbia hosting the majority of licensed processing capacity. Federal legalization enables interprovincial distribution, though provincial retail monopolies fragment end-market access. Ontario and Quebec concentrate the largest patient and consumer bases for concentrated cannabis products.
Germany
The BfArM cannabis agency oversees medical cannabis imports and domestic manufacturing licenses, with hydrocarbon extraction permitted under narcotics handling regulations. German pharmacists dispense high-THC concentrates to patients with severe conditions, creating demand for pharmaceutical-grade processing standards. Berlin and Hamburg cluster the initial licensed extraction facilities serving the EU's largest medical cannabis market.
Israel
The Medical Cannabis Unit at the Ministry of Health regulates extraction licensing, with hydrocarbon processing permitted for domestic research and export manufacturing. Israeli cannabis technology firms partner with licensed producers to develop terpene preservation protocols. Jerusalem and Tel Aviv metropolitan areas concentrate R&D-intensive extraction operations targeting European export markets.
Australia
The TGA's Special Access Scheme and Authorised Prescriber pathways enable medical cannabis concentrate distribution, with hydrocarbon extraction licensed under state manufacturing permits. Victoria and New South Wales host the majority of domestic processing capacity. Melbourne and Sydney extraction facilities serve both domestic patient demand and Asia-Pacific export opportunities.
Butane Hash Oil Market Vendor Landscape
On the supply side, the industry is consolidating around multi-state operators with captive biomass supply and in-house hydrocarbon processing infrastructure. Capital requirements for C1D1-rated extraction facilities and fire marshal compliance are filtering small-batch producers from licensed markets. Three archetypes dominate: vertically integrated cultivator-processors, asset-light brand holders outsourcing to tolling partners, and specialized extraction technology providers. Competitive moves center on backward integration into biomass cultivation and geographic license stacking across state jurisdictions.
Among North American cannabis operators, Curaleaf Holdings, Trulieve Cannabis Corp., and Green Thumb Industries exemplify the vertically integrated archetype, each maintaining controlled-environment agriculture paired with hydrocarbon extraction infrastructure to capture margin across the value chain. These operators represent positions sustained by state-level license ownership and retail distribution networks rather than technology differentiation alone.
| Leading Market Players |
|---|
| Curaleaf Holdings, Inc. |
| Trulieve Cannabis Corp. |
| Green Thumb Industries Inc. |
| Canopy Growth Corporation |
| Aurora Cannabis Inc. |
| Tilray, Inc. |
| Cronos Group Inc. |
| Verano Holdings |
| TerrAscend Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in California's extraction infrastructure is compressing tolling rates and forcing tolling providers into volume-based pricing postures that sacrifice margin for utilization. Equipment-heavy operators with C1D1-rated facilities face 18-24 month payback extensions as white-label contract values reset downward.
Pricing Analysis
Certification level creates the primary spread across California's BHO market, with Bureau of Cannabis Control-licensed facilities commanding per-gram premiums over provisional operators. Three-tier pricing structure across pharmaceutical-grade, dispensary-compliant, and unlicensed legacy tiers segments buyer pools. Cost compression in the mid-tier is intensifying because tolling contracts now bundle winterization and distillation services at fixed rates. Retail shops exhibit the sharpest price sensitivity, while medical patients sustain premiums for batch-level documentation.
Supply Chain Analysis
Tolling contract manufacturers in Colorado and Michigan hold the dominant extraction capacity, with California operators increasingly outsourcing to lower-cost Rocky Mountain facilities. N-butane and isobutane feedstocks draw from Gulf Coast petrochemical corridors, while biomass supply clusters in Humboldt County, the Emerald Triangle, and Michigan's northern cultivation zones. Single-source vulnerability in solvent supply chains exposes processors to fuel-grade shortages during regional refining disruptions. Distribution runs through state-licensed third-party logistics providers with bonded transport authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed hydrocarbon extraction capability remains scarce relative to brand proliferation, with OSHA-compliant technician credentials and C1D1 facility certification creating durable bottlenecks for expansion.
For Market Incumbents: Build regulatory compliance moats through preemptive investment in fire marshal peer-reviewed ventilation systems and automated solvent recovery infrastructure. Consolidate tolling relationships with asset-light brands to lock in volume commitments before Michigan's social equity licensing wave adds capacity. Threat substitution from CO2 extraction marketing claims demands terpene preservation R&D investment as defensive differentiation. For New Entrants and Emerging Players: Michigan's Detroit metropolitan procurement zones offer the most penetrable white-space, with medical registry growth outpacing licensed extraction capacity. Colorado's Pueblo extraction corridor presents secondary entry opportunity through social equity ownership set-asides. Target direct-to-patient delivery channel partnerships to bypass retail shelf fee structures that erode margin for wholesale-dependent entrants. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because state licensing scarcity and compliance capital requirements filter competitive entry across successive legislative waves. Acquisition candidates should demonstrate captive biomass supply or exclusive tolling relationships with multi-state brand holders. Signal to watch is federal rescheduling proceedings that would unlock interstate commerce and reshape facility valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Extraction Infrastructure Deployment | Reduces labor headcount by 40% while maintaining Bureau of Cannabis Control compliance throughput. |
| Backward Integration into Biomass Cultivation | Secures strain-specific supply for terpene-forward product differentiation in California dispensaries. |
| Social Equity Licensing Partnership | Captures first-mover positions in Colorado's Denver and Pueblo ownership set-aside programs. |
| Minor Cannabinoid Isolation Capability | Unlocks pharmaceutical-grade pricing from CBG and CBN wellness formulators. |
| Direct-to-Patient Delivery Authorization | Bypasses retail markup capture in California's state-authorized courier services. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with extraction facility operators, state regulatory compliance officers, and dispensary procurement managers; and secondary validation through state cannabis control board licensing databases, OSHA enforcement records, and hydrocarbon equipment certification filings. Bottom-up capacity estimates from C1D1 facility counts triangulated against top-down market value reconstructions.
Forecast inputs incorporated patient registry growth trajectories, recreational licensing waves, and equipment deployment cycles across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user category, and state regulatory cluster. CAGRs derived from fitted growth curves calibrated to historical legalization adoption patterns and solvent recovery efficiency improvements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated multi-state operators or federal rescheduling decisions would shift outcomes substantially. Quarterly review of state legislative sessions, patient enrollment data, and fire marshal inspection backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Missouri Medical Cannabis Market
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
CBD Edibles Market
Cannabis/Marijuana
Australia Legal Cannabis Market
Cannabis/Marijuana
Cannabis Use Disorder Treatment Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Cannabis Extract Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Trichome Separator/Extractor Market