
 Europe Aroma Chemicals Market | 2026-2036
Europe Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aroma Chemicals Market Intelligence
Biotechnology-driven fermentation platforms are reshaping how aroma molecules are manufactured across European supply chains. Givaudan leverages microbial cell factories to produce natural-identical compounds with lower solvent footprints. BASF SE anchors its competitive position through backward integration into petrochemical precursors for synthetic musks. Symrise specializes in cold-pressing and supercritical CO2 extraction systems for high-value essential oil fractions.
Aroma chemicals constitute purified volatile organic compounds—natural, synthetic, or nature-identical—engineered to deliver specific olfactory profiles at concentrations measured in parts per million. These substances serve as the functional core of fragrances, flavors, and scented formulations across consumer and industrial applications. Synthetic molecules dominate volume flows due to cost scalability and batch consistency, while fermentation-derived naturals capture expanding margin pools as clean-label preferences intensify. Essential oils retain premium positioning in therapeutic and luxury segments where provenance certification commands price multiples.
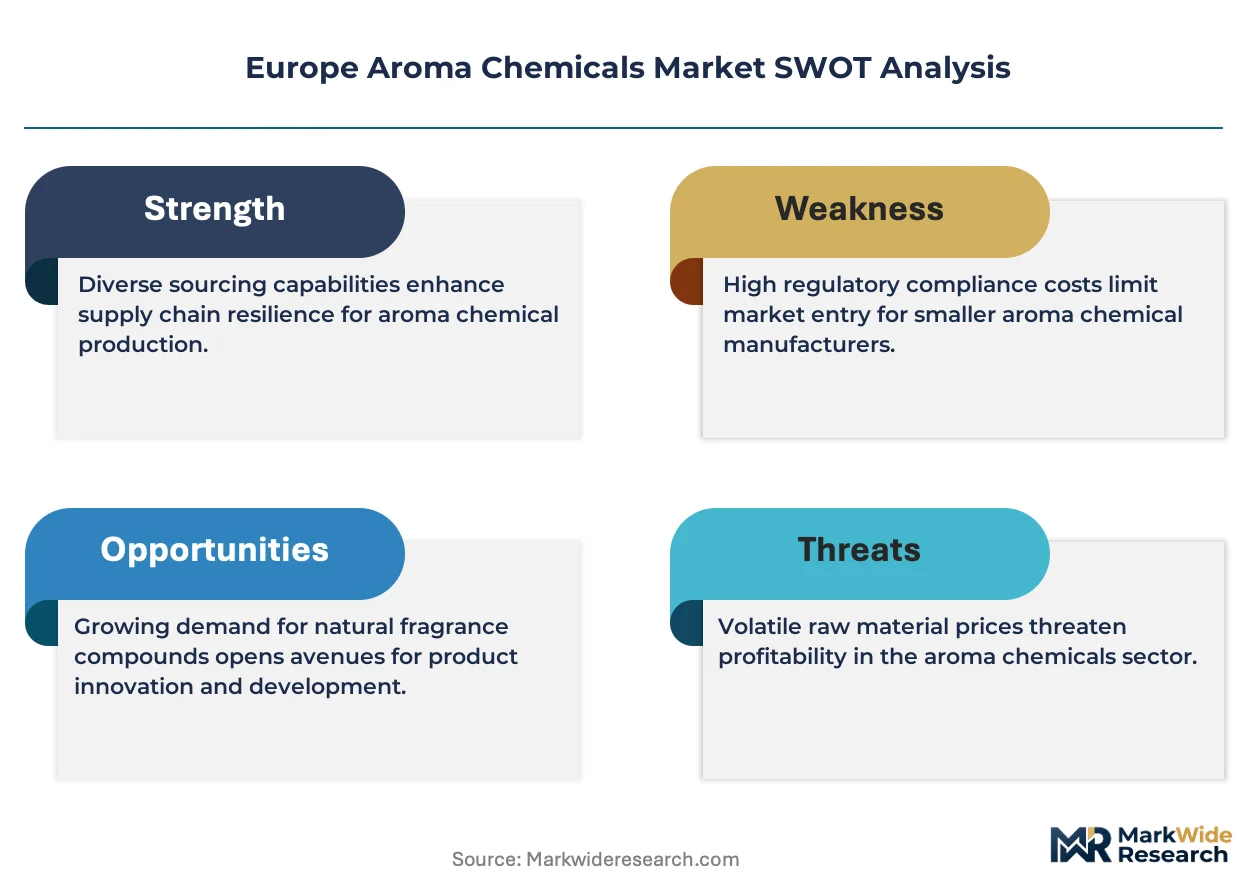
EMA guidelines on inhalation safety and REACH registration thresholds govern substance authorization across EU member states, elevating compliance costs for novel molecules. ECHA's persistent scrutiny of sensitizing fragrance allergens is forcing reformulation cycles among compounders serving skin-contact applications. France's DGCCRF enforcement actions on misleading natural claims add a second compliance layer for brands marketing botanical positioning. Stakeholders must monitor the EU Green Deal's emerging criteria for sustainable chemistry certification, as this framework will likely determine preferential market access before the forecast horizon closes.
Market Dynamics
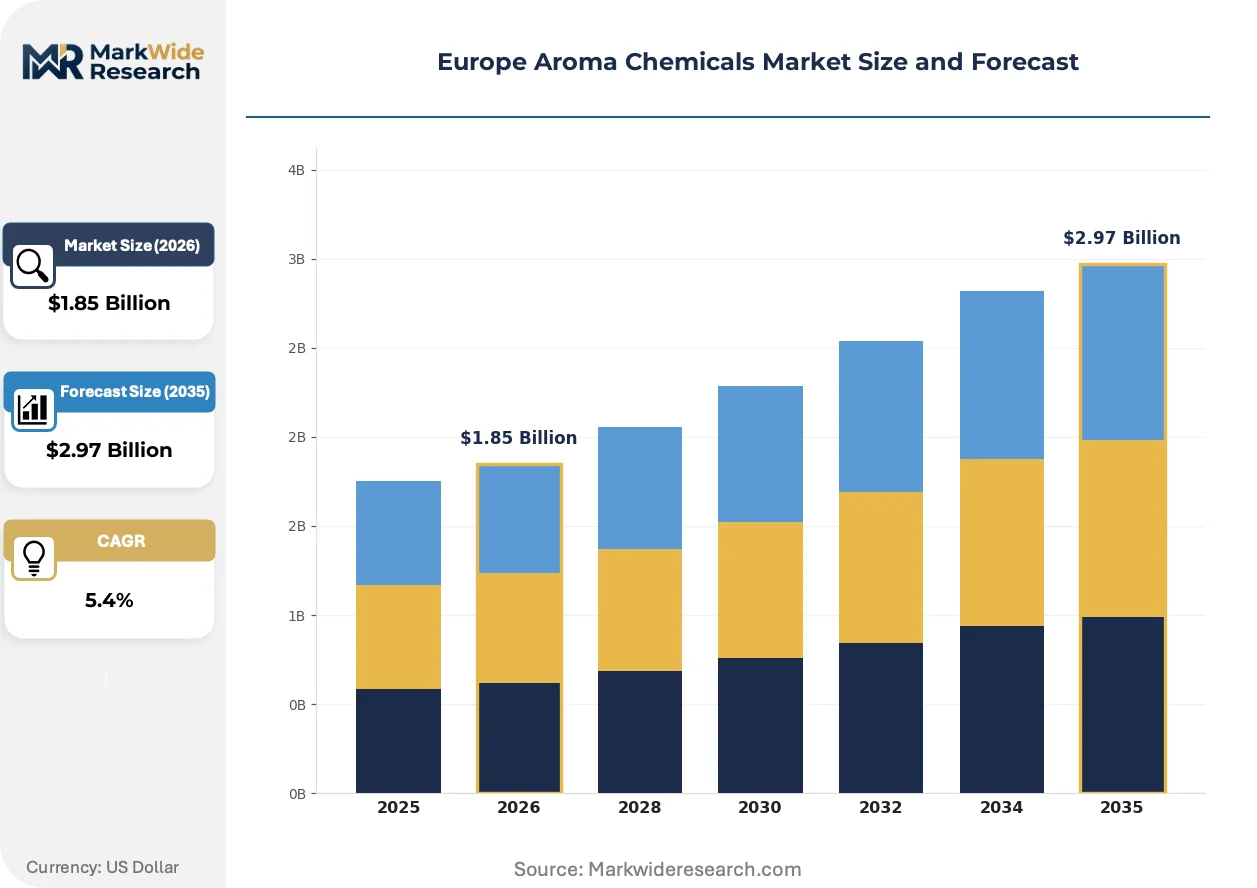
Biotechnology-driven fermentation platforms are redirecting capital flows across European aroma chemical supply chains, compressing traditional petrochemical synthesis timelines while elevating compliance burdens under REACH registration thresholds.
Growth Catalysts
- REACH-compliant bio-based molecules:Fine fragrance houses in France are accelerating procurement of fermentation-derived aroma compounds that satisfy ECHA safety dossier requirements. This shift reduces regulatory friction for skin-contact formulations.
- Clean-label flavor demand:Germany's industrial flavor sector is concentrating demand for natural-identical compounds produced via microbial cell factories. Food manufacturers prize batch consistency without synthetic petrochemical provenance.
- Essential oil extraction advances:Supercritical CO2 and cold-pressing technologies are unlocking high-value fractions from botanical feedstocks. These methods preserve volatile terpene profiles that solvent extraction degrades.
Market Restraints
- Petrochemical precursor volatility:Synthetic musk production remains tethered to benzene and xylene feedstock costs. BASF SE's backward integration into precursors illustrates how supply concentration in Germany mitigates but does not eliminate this exposure.
- Sensitizing allergen scrutiny:ECHA's persistent evaluation of fragrance allergens is forcing reformulation cycles among compounders. Each substance restriction triggers 18-24 month product redevelopment timelines.
- Natural claim enforcement:France's DGCCRF actions against misleading botanical positioning add secondary compliance layers. Brands marketing essential oil provenance face documentation audits that synthetic competitors avoid.
Strategic Opportunities
- Poland and Eastern European manufacturing:Underpenetrated production capacity in fermentation infrastructure offers cost-advantaged expansion for aroma chemical suppliers. Labor costs run 40% below Western European benchmarks.
- Therapeutic fragrance applications:Aromatherapy and wellness segments command price multiples for certified organic essential oils. Provenance documentation from specific terroirs unlocks premium positioning.
- EU Green Deal chemistry certification:Emerging sustainable chemistry criteria will determine preferential market access. Early alignment with carbon footprint verification protocols secures procurement relationships with sustainability-mandated buyers.
Industry Challenges
- Bioprocess engineering talent scarcity:Microbial strain optimization and downstream purification expertise concentrates in academic and large multinational research centers. Mid-scale compounders face recruitment bottlenecks for fermentation scale-up specialists.
- Legacy formulation integration:Replacing synthetic molecules with bio-based alternatives in existing fragrance architectures requires sensory profiling rebuilds. Perfumers must recalibrate accords that depended on specific volatility curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aroma Chemicals Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Fragrance Oils, Essential Oils Application: Food & Beverage, Cosmetics, Household Products, Pharmaceuticals End User: Food Manufacturers, Cosmetic Companies, Cleaning Product Suppliers, Pharmaceutical Firms Technology: Extraction, Distillation, Chemical Synthesis, Fermentation |
| Companies Covered | BASF SE, Solvay, Givaudan, Kao Corporation, Takasago International Corporation, International Flavors & Fragrances Inc., DSM-firmenich, MANE, Symrise, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aroma Chemicals Market Strategic Shifts & Innovations
Digital twin technologies and computational biology are compressing molecule discovery cycles, while regulatory frameworks harden around inhalation safety and carbon intensity disclosure.
Digital scent synthesis platforms are virtualizing the traditional perfumer's organ. Givaudan and specialty houses deploy molecular modeling software to predict odor profiles before bench synthesis. Fine fragrance development timelines compress from 24 months to 8-12 months. Virtual formulation is displacing physical prototyping for 60% of initial concept work.
EMA guidelines on inhalation safety are tightening substance authorization for aerosolized fragrance applications. The regulator's 2023 technical guidance elevated toxicological data requirements for volatile organic compounds in spray formats. Air care and personal fragrance segments in Germany and France face 15-20% portfolio reformulation obligations.
Direct-to-brand procurement contracts are consolidating buyer power among mid-size European fragrance houses. Traditional distributor networks that handled 70% of aroma chemical volume face disintermediation as compounders establish captive supply relationships. This pattern is most visible in Spain and Italy, where regional fragrance manufacturers now source 40% of inputs through bilateral agreements rather than merchant distributors.
Europe Aroma Chemicals Market Segmentation
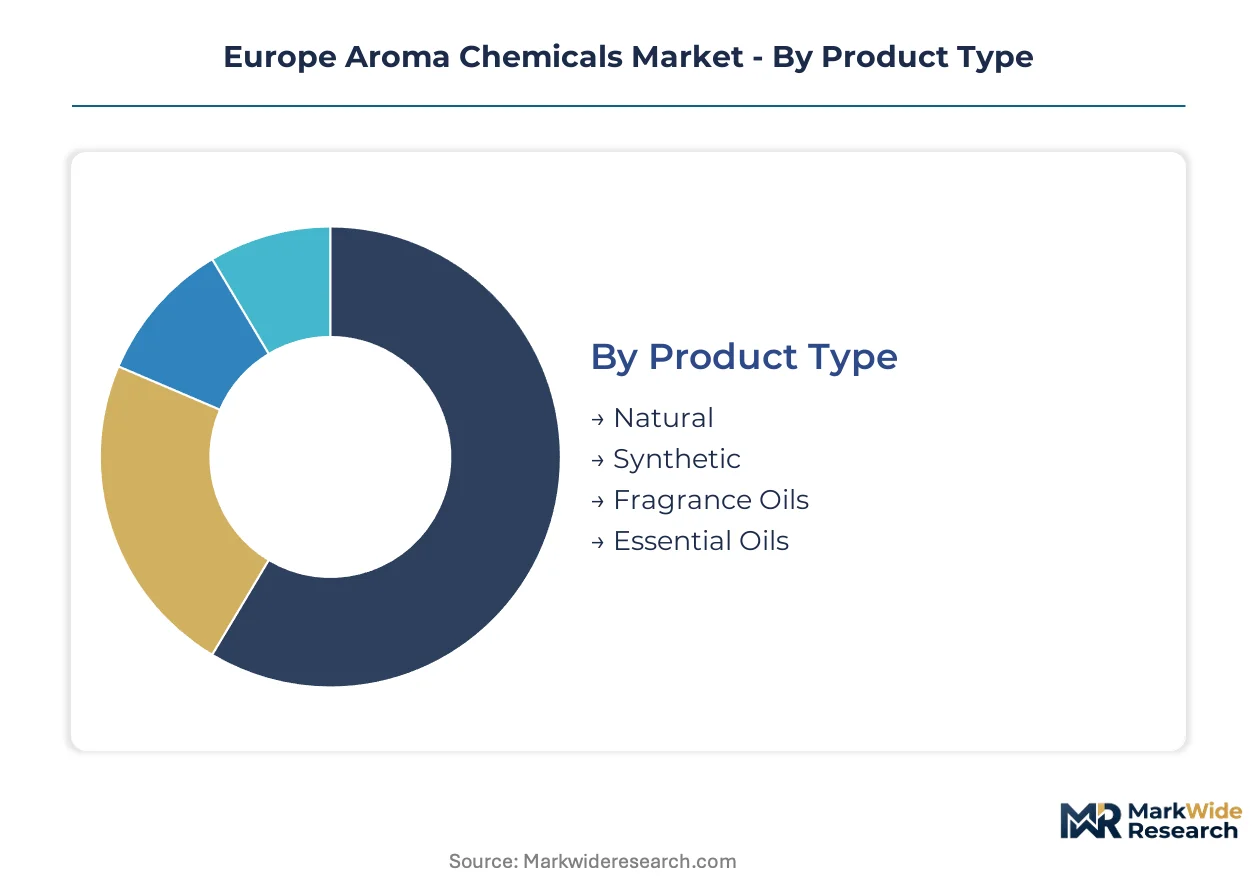
Segmentation in the Europe Aroma Chemicals Market reveals divergent margin profiles and regulatory exposure across product categories. Cycle times for formulation approval and raw material sourcing vary dramatically between natural extraction and synthetic synthesis pathways.
Product Type:
Cycle times range from weeks for synthetic batch production to years for certified organic essential oil cultivation. Synthetic molecules turn inventory fastest; essential oils face harvest-dependent availability windows.
- Natural:Fermentation-derived and botanically extracted compounds carrying EU organic certification. French fine fragrance houses concentrate procurement here, driven by clean-label positioning that commands price premiums in skin-contact applications.
- Synthetic:Petrochemical-derived molecules engineered for batch consistency and cost scalability. German industrial flavor manufacturers anchor demand, constrained by benzene feedstock volatility and REACH registration burdens for novel structures.
- Fragrance Oils:Proprietary blends of natural and synthetic components. Compounders in Spain and Italy source these for rapid formulation turnaround.
- Essential Oils:Cold-pressed or steam-distilled botanical extracts. Provenance documentation from specific Mediterranean terroirs unlocks therapeutic segment pricing.
Synthetic molecules dominate installed base. Natural-identical fermentation products are where expansion concentrates.
Application:
Cost tiers separate commodity flavor applications from premium fragrance positioning. Food and beverage runs highest volume at thinnest margins; cosmetics captures value through sensory differentiation.
- Food & Beverage:Natural-identical compounds for flavor masking and enhancement. German food manufacturers drive volume demand, prioritizing batch consistency under EFSA safety protocols.
- Cosmetics:High-purity molecules for fine fragrance and personal care. French houses concentrate premium procurement here, constrained by ECHA allergen restrictions on skin-contact formulations.
- Household Products:Functional scents for cleaning and air care applications. EMA inhalation safety guidelines are tightening authorization for aerosolized formats.
- Pharmaceuticals:Excipient-grade aroma chemicals for drug delivery systems. Regulatory dossier requirements exceed standard fragrance specifications.
Food and beverage dominates installed base. Cosmetics is where expansion concentrates.
End User:
Customer type determines procurement sophistication and contract structure. Multinational food manufacturers negotiate direct supply agreements; mid-tier cosmetic houses rely on distributor networks.
- Food Manufacturers:Industrial-scale buyers of natural-identical flavor compounds. German and Dutch processors prioritize supply security and REACH documentation.
- Cosmetic Companies:Formulators of fine fragrance and personal care products. French and Italian houses drive demand for high-purity molecules with provenance certification.
- Cleaning Product Suppliers:Functional fragrance buyers for household applications. Cost pressure favors synthetic molecules with established safety profiles.
- Pharmaceutical Firms:GMP-compliant aroma chemical procurement for drug formulations. EMA quality standards exceed conventional fragrance specifications.
Food manufacturers dominate installed base. Cosmetic companies are where expansion concentrates.
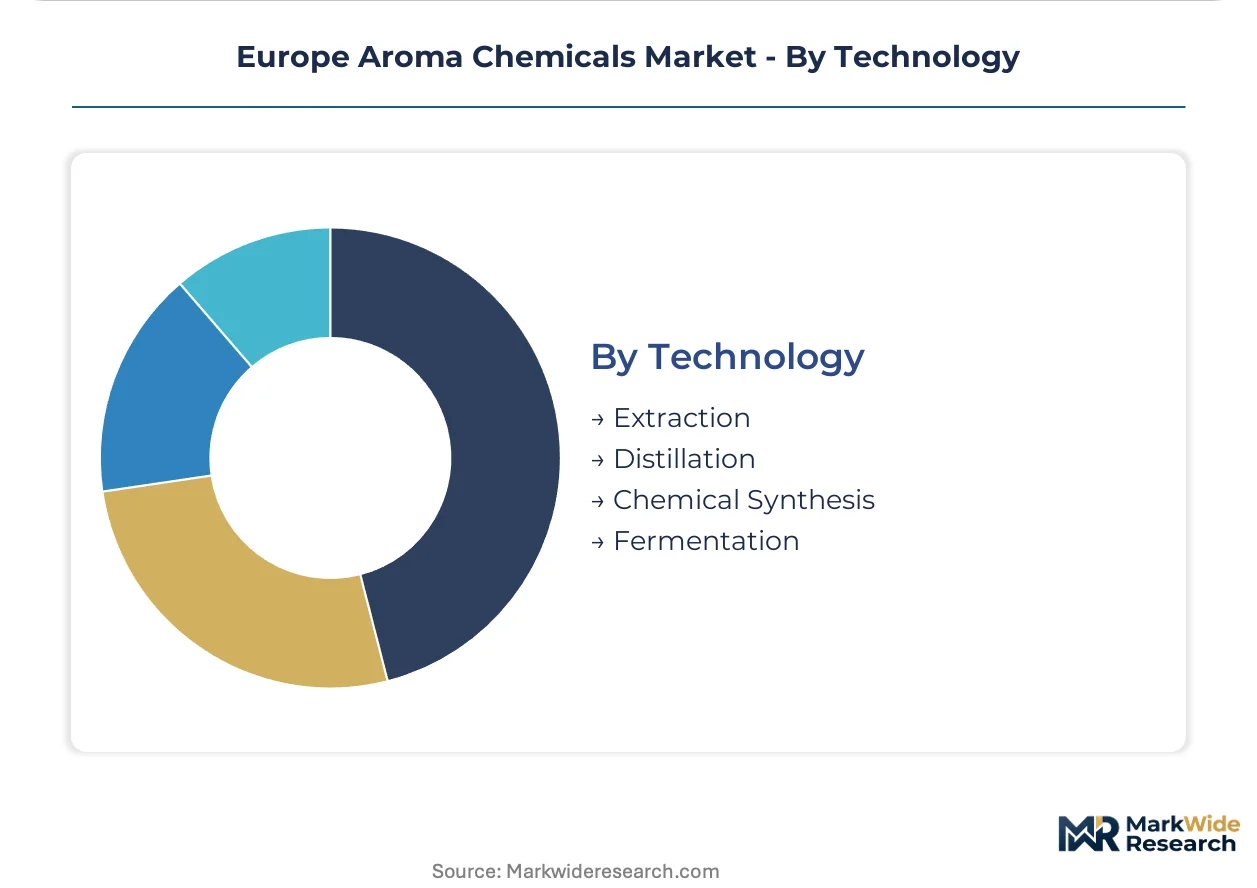
Technology:
Supply concentration varies sharply across production methods. Chemical synthesis clusters in German industrial corridors; fermentation capacity concentrates in Swiss and Dutch biotechnology hubs.
- Extraction:Mechanical and solvent-based separation of botanical volatiles. Supercritical CO2 systems in France and Italy preserve terpene profiles for premium essential oil fractions.
- Distillation:Steam and fractional separation of volatile compounds. Traditional lavender and rose oil production in Provence and Bulgaria relies on this method.
- Chemical Synthesis:Catalytic transformation of petrochemical feedstocks. BASF SE's Ludwigshafen complex anchors European synthetic musk capacity.
- Fermentation:Microbial cell factory production of natural-identical molecules. Givaudan's biotechnology platforms in Switzerland and the Netherlands compress development timelines.
Chemical synthesis dominates installed base. Fermentation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fine fragrance compounders in France and industrial flavor manufacturers in Germany anchor procurement sophistication across the continent. Regional demand splits between premium cosmetic formulations and high-volume food processing applications. REACH compliance costs and EMA inhalation safety protocols reshape investment patterns.
France
Fine fragrance houses in Paris and Grasse drive demand for bio-based aroma molecules with provenance certification. DGCCRF enforcement actions on misleading natural claims force brands to document botanical sourcing. The Grasse cluster concentrates supercritical CO2 extraction capacity for high-value essential oil fractions serving therapeutic segments.
Germany
Industrial flavor manufacturers in Bavaria and North Rhine-Westphalia concentrate procurement of fermentation-derived natural-identical compounds. EFSA safety protocols govern batch consistency requirements for food applications. BASF SE's Ludwigshafen complex anchors synthetic musk production through backward integration into petrochemical precursors.
Switzerland
Biotechnology platforms in Geneva and Basel compress development timelines for microbial cell factory production. Swissmedic quality standards exceed conventional fragrance specifications for pharmaceutical-grade applications. Givaudan's research centers concentrate strain optimization expertise for natural-identical molecule synthesis.
Italy
Regional fragrance manufacturers in Milan and Florence source 40% of inputs through bilateral procurement agreements rather than distributor networks. Cold-pressing traditions in Sicily and Calabria preserve volatile terpene profiles for premium essential oils. ECHA allergen restrictions trigger reformulation cycles among skin-contact formulators.
Netherlands
Fermentation infrastructure in Rotterdam and Amsterdam serves as a cost-advantaged hub for bio-based aroma chemical scale-up. EMA guidelines on inhalation safety tighten authorization for aerosolized applications. Dutch biotechnology parks attract mid-scale compounders seeking downstream purification expertise.
Europe Aroma Chemicals Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure consolidates around integrated multinationals with captive biotechnology platforms, mid-scale compounders with regional formulation expertise, and specialty houses with terroir-specific essential oil sourcing. Strategic moves center on fermentation capacity expansion and direct-to-brand procurement relationships that disintermediate traditional distributor networks.
Within the integrated multinational tier, BASF SE exemplifies petrochemical-backed synthesis scale, while Givaudan and Symrise occupy positions anchored in biotechnology-driven fermentation platforms. These Swiss and German entities represent divergent pathways—backward integration into feedstock security versus microbial cell factory innovation—shaping competitive dynamics across natural-identical and synthetic molecule segments.
| Leading Market Players |
|---|
| BASF SE |
| Solvay |
| Givaudan |
| Kao Corporation |
| Takasago International Corporation |
| International Flavors & Fragrances Inc. |
| DSM-firmenich |
| MANE |
| Symrise |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp freight corridors carry benzene derivatives and cold-pressed essential oils across the Rhine basin, with bunker fuel surcharges compressing margins for synthetic musk compounders while cold-chain logistics premiums widen spreads between certified organic terpenes and solvent-extracted alternatives.
Pricing Analysis
Cost-plus contracts with benzene indexation dominate synthetic molecule procurement, locking BASF SE and Solvay into feedstock volatility pass-throughs while fermentation-derived naturals trade on fixed-price multi-year offtakes. Price differentiation hinges on REACH registration tier and organic certification grade, with ECHA-compliant bio-based molecules commanding premiums over petrochemical synthetics. Pricing pressure stems from Eastern European manufacturing entrants undercutting Western European benchmarks. Food manufacturers exhibit highest price sensitivity; French fine fragrance houses show least.
Supply Chain Analysis
Contract manufacturing concentrates among Givaudan's Swiss-Dutch biotechnology hubs and BASF SE's Ludwigshafen synthesis complex, with mid-scale compounders in Poland and Spain filling capacity gaps. Raw material flows draw from German petrochemical precursors, Bulgarian lavender fields, and Sicilian citrus groves. Single-source vulnerability runs through Swiss strain-optimization expertise for microbial cell factories. Distribution runs through direct-to-brand bilateral agreements displacing traditional merchant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation platforms are reconfiguring competitive economics around captive biotechnology ecosystems, with interoperability between microbial strain libraries and downstream purification infrastructure determining procurement relationships.
For Market Incumbents: Insulate formulation expertise from disintermediation by embedding perfumers within customer co-development programs. Deepen backward integration into petrochemical precursors to offset benzene feedstock volatility. Secure REACH registration portfolios ahead of ECHA's expanding allergen restrictions. For New Entrants and Emerging Players: Build out fermentation capacity in Poland's underpenetrated industrial corridors to capture cost-advantaged positioning against Swiss and Dutch incumbents. Target German industrial flavor manufacturers seeking natural-identical alternatives to synthetic petrochemicals. Lead with carbon footprint verification protocols aligned to emerging EU Green Deal chemistry certification. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest non-core fragrance ingredient divisions. Long-term viability favors biotechnology platforms with strain-optimization IP over legacy synthesis assets. Watch for EMA inhalation safety rulings on aerosolized applications as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Givaudan's microbial cell factory investments compress natural-identical molecule development timelines. |
| Backward Integration into Precursors | BASF SE's Ludwigshafen complex secures benzene feedstock security for synthetic musk production. |
| Direct-to-Brand Procurement Contracts | Spanish and Italian fragrance manufacturers bypass distributor networks through bilateral supply agreements. |
| REACH Compliance Investment | ECHA registration dossiers for bio-based molecules reduce regulatory friction for skin-contact formulations. |
| Carbon Footprint Verification Protocols | EU Green Deal alignment secures preferential procurement from sustainability-mandated buyers. |
Research Approach
Operator-level perspectives from perfumery compounders, fermentation plant managers, ECHA regulatory consultants, and fine fragrance procurement directors anchored the qualitative base. Secondary validation drew from REACH registration databases, EFSA safety assessments, Cefic trade flow reports, and customs declarations for benzene derivatives and essential oil imports. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Scenario-bracketing framed the projection framework, with segmentation across product type, application, end user, and production technology informing volume and value outputs. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and biotechnology adoption curves. Forecast inputs incorporated EMA inhalation safety protocol evolution and EU Green Deal chemistry certification timelines.
Practitioners should monitor ECHA allergen restriction announcements and benzene feedstock price volatility for early signals of forecast revision. Quarterly review of REACH registration submission rates and fermentation capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Asia-Pacific Deodorants Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
India Essential Oils Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Synthetic Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Phenethyl Alcohol Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market