
 Synthetic Cinnamaldehyde Market | 2026-2036
Synthetic Cinnamaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Cinnamaldehyde Market Analytics
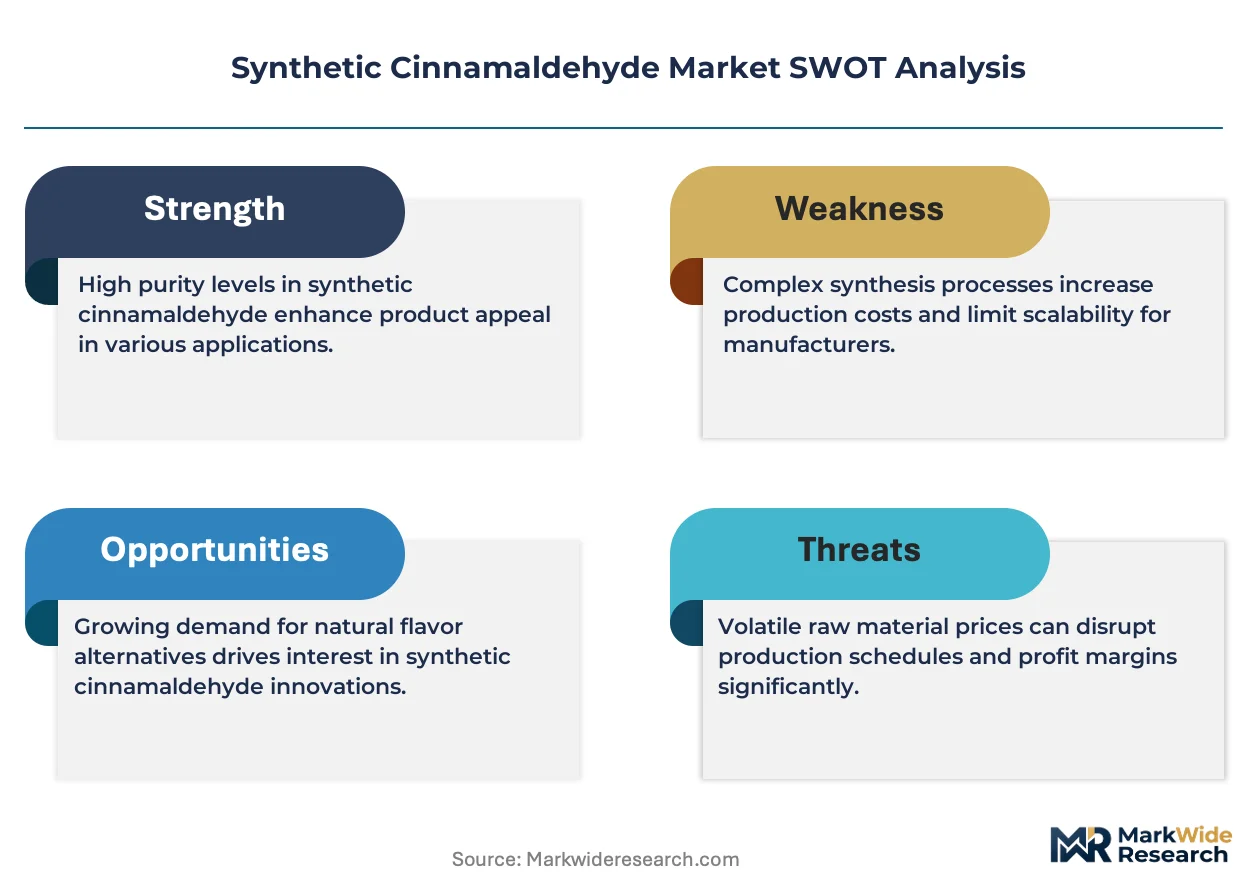
ISO 9001 certification cycles for fine chemical manufacturers is collapsing the supplier base as smaller producers fail recurring audits. Lanxess AG leverages its integrated benzaldehyde-to-cinnamaldehyde pipeline to sustain raw material cost advantages. Symrise AG anchors European supply through specialized flavor precursor facilities in Germany. Givaudan SA differentiates via biotechnology-derived routes that reduce petrochemical dependency.
Synthetic cinnamaldehyde is an aromatic aldehyde manufactured primarily through base-catalyzed condensation of benzaldehyde and acetaldehyde, yielding a compound with characteristic cinnamon odor at purity grades exceeding 98 percent for food and pharmaceutical applications. The substance serves as a critical intermediate for flavoring agents, fragrance compounds, and pharmaceutical synthesis where consistent organoleptic properties outweigh natural source variability. Flavoring agent production dominates volume as food manufacturers standardize taste profiles across processed goods, while fragrance compound demand accelerates fastest as cosmetic companies reformulate for allergen labeling compliance. Pharmaceutical-grade synthetic cinnamaldehyde commands premium positioning due to stringent USP-NF monograph requirements that limit qualified suppliers.
REACH registration under ECHA mandates full toxicological dossiers for cinnamaldehyde imports into Europe, while FDA food additive regulations under 21 CFR govern permissible concentrations in consumable products. EPA oversight of benzaldehyde feedstock emissions further shapes manufacturing location decisions for North American producers. China's SAMR enforces GB standards for food flavorants that diverge from Codex Alimentarius parameters, creating dual compliance burdens for exporters. Stakeholders must monitor regulatory divergence between jurisdictions as classification thresholds for skin sensitization trigger reformulation mandates without harmonized transition timelines.
Market Dynamics
REACH registration dossiers under ECHA are compressing the qualified supplier base for European imports, forcing food and fragrance manufacturers to consolidate procurement around ISO-certified producers with integrated benzaldehyde supply chains.
Growth Catalysts
- Flavor standardization mandates:Processed food manufacturers in Germany and India require consistent organoleptic profiles that natural cinnamon extracts cannot deliver, accelerating synthetic cinnamaldehyde adoption for bakery and confectionery applications.
- Allergen labeling compliance:EU Regulation 1169/2011 mandates disclosure of fragrance allergens in cosmetics, pushing cosmetic formulators toward synthetic alternatives with controlled impurity profiles.
- Biotechnology-derived routes:Fermentation-based production methods using engineered yeast strains reduce petrochemical feedstock dependency and appeal to clean-label positioning strategies in premium personal care.
Market Restraints
- Benzaldehyde feedstock volatility:Toluene oxidation capacity concentration in China creates price instability for Western aldehyde manufacturers without backward integration into aromatics.
- Skin sensitization thresholds:ECHA classification of cinnamaldehyde as a Category 1B skin sensitizer triggers concentration limits in leave-on cosmetic products, constraining formulation flexibility.
- Natural extract substitution:Supercritical CO2 extraction of Ceylon cinnamon bark yields odor profiles that premium fragrance houses position as authentic alternatives for niche perfumery.
Strategic Opportunities
- Pharmaceutical-grade expansion:USP-NF monograph compliance for cinnamaldehyde opens oncology and antimicrobial research applications where purity certificates command substantial premiums over technical grades.
- India domestic flavorant production:FSSAI harmonization with Codex Alimentarius under the PLI scheme for specialty chemicals incentivizes local cinnamaldehyde synthesis for processed food export zones.
- SAMR-REACH dual certification:Chinese exporters investing in parallel toxicological dossier preparation capture European fragrance compound contracts during competitor transition periods.
Industry Challenges
- Analytical chemist scarcity:GC-MS method development for cinnamaldehyde stereoisomer quantification requires specialized expertise that contract laboratories struggle to retain.
- Cross-contamination protocols:Food-grade and fragrance-grade production lines demand segregated equipment cleaning validation that extends batch turnaround times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Cinnamaldehyde Market |
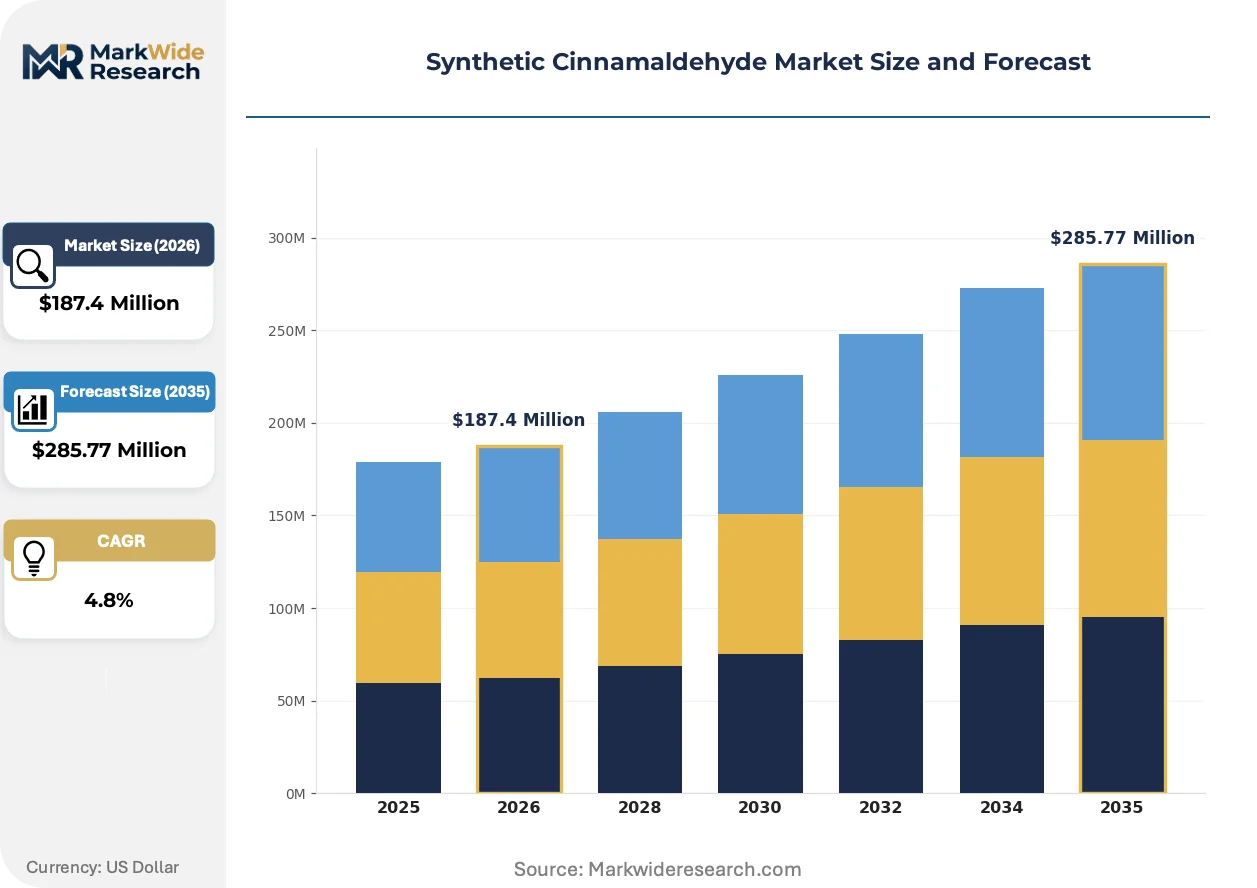
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Flavoring Agent, Fragrance Compound Application: Food & Beverages, Cosmetics, Pharmaceuticals, Household Products End User: Food Manufacturers, Cosmetic Companies, Chemical Industries, Pharmaceutical Firms Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Lanxess AG (Emerald Kalama Chemical), Symrise AG, Givaudan SA, Takasago International Corporation, Merck KGaA, Ashland Global Holdings Inc., Prasol Chemicals Pvt. Ltd., Penta Manufacturing, Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Cinnamaldehyde Market Evolving Landscape
Continuous flow reactor technology and enzyme-catalyzed condensation routes are fragmenting the traditional batch-process paradigm, creating divergent cost structures between established petrochemical producers and emerging biotech entrants.
Biocatalytic aldol condensation is bifurcating the manufacturing landscape. Specialty enzyme suppliers now license immobilized transketolase systems to mid-scale producers seeking to bypass benzaldehyde spot market exposure. Fragrance compound manufacturers in Switzerland and France are piloting these routes to secure supply chain resilience. The technology is compressing capital barriers for entry while fragmenting quality certification pathways between fermentation-derived and chemical-synthetic grades.
EU F-Gas Regulation phase-down schedules are accelerating solvent recovery system investments across European aldehyde purification operations. Distillation energy intensity now factors into ECHA registration cost calculations for import authorization renewals. German fine chemical producers are retrofitting molecular sieve adsorption units to maintain competitiveness against Middle Eastern capacity with lower cooling energy requirements.
Direct procurement from integrated aroma chemical manufacturers is displacing distributor intermediaries in North American flavorant supply chains. Large food processors in Chicago and New Jersey now contract quarterly benzaldehyde-cinnamaldehyde bundles with fixed purity specifications. The shift concentrates volume risk with fewer supplier relationships while compressing working capital cycles for buyers with sufficient storage infrastructure.
Synthetic Cinnamaldehyde Market Segmentation
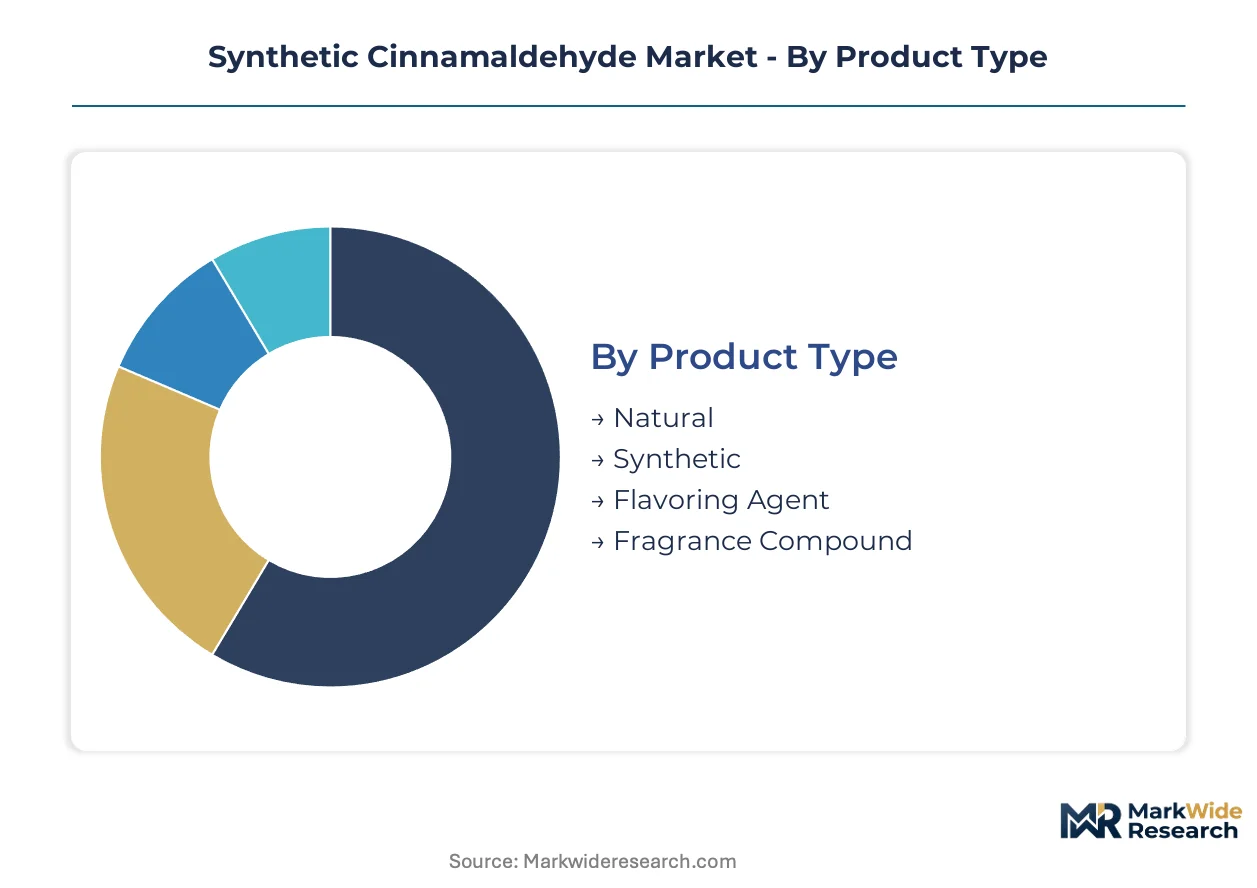
Synthetic cinnamaldehyde procurement patterns diverge sharply across product grades and end-use specifications, with REACH-compliant pharmaceutical grades commanding fundamentally different supplier relationships than technical-grade fragrance intermediates. Segmentation discipline separates volume-driven food additive contracts from premium cosmetic formulations where impurity thresholds trigger reformulation costs.
Product Type:
Natural extracts pose the most acute substitution threat to synthetic grades in premium fragrance positioning, while synthetic variants defend share through batch consistency and allergen documentation.
- Natural:Supercritical CO2 extraction from Ceylon cinnamon bark yields odor profiles with geographic provenance claims that niche perfumers in Grasse and Geneva leverage for authenticity marketing. Demand concentrates in Swiss and French fragrance houses seeking EU Regulation 1169/2011 allergen avoidance through unstandardized botanical variability.
- Synthetic:Base-catalyzed condensation of benzaldehyde and acetaldehyde achieves purity grades exceeding 98 percent with stereoisomer ratios controlled within narrow tolerances. Food manufacturers in Germany and India standardize bakery and confectionery taste profiles through consistent organoleptic properties that natural sources cannot replicate.
- Flavoring Agent:Technical grades optimized for heat stability in processed foods.
- Fragrance Compound:Purified grades meeting IFRA standards for skin sensitization thresholds.
Synthetic grades retain volume leadership; fragrance compound specifications hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity food additive contracts from pharmaceutical-grade premiums, with cosmetics occupying a mid-tier position sensitive to both raw material volatility and regulatory reclassification risk.
- Food & Beverages:Processed bakery and confectionery applications dominate tonnage, with FSSAI-harmonized Codex standards in Indian export zones driving specification convergence. Manufacturers in Mumbai and Ahmedabad require cinnamaldehyde with documented benzaldehyde feedstock provenance for PLI scheme compliance.
- Cosmetics:Leave-on products face ECHA Category 1B skin sensitizer concentration limits that constrain formulation flexibility. Formulators in Hamburg and Rotterdam pilot biocatalytic-derived alternatives to secure supply chain resilience against petrochemical price spikes.
- Pharmaceuticals:USP-NF monograph compliance limits qualified suppliers for oncology and antimicrobial research intermediates.
- Household Products:Air freshener and cleaning applications tolerate broader purity ranges.
Food and beverage applications anchor volume; pharmaceutical grades capture the widest margin spreads.
End User:
Customer type determines procurement sophistication, with chemical industries managing spot market exposure while pharmaceutical firms demand multi-year purity certification contracts.
- Food Manufacturers:Large processors in Chicago and New Jersey now contract quarterly benzaldehyde-cinnamaldehyde bundles with fixed purity specifications, displacing distributor intermediaries and compressing working capital cycles.
- Cosmetic Companies:EU allergen labeling mandates push formulators toward synthetic alternatives with controlled impurity profiles.
- Chemical Industries:Intermediate buyers for downstream aldehyde derivatives.
- Pharmaceutical Firms:Specialized procurement teams managing USP-NF dossier requirements.
Food manufacturers concentrate procurement volume; pharmaceutical firms drive specification escalation.
Distribution Channel:
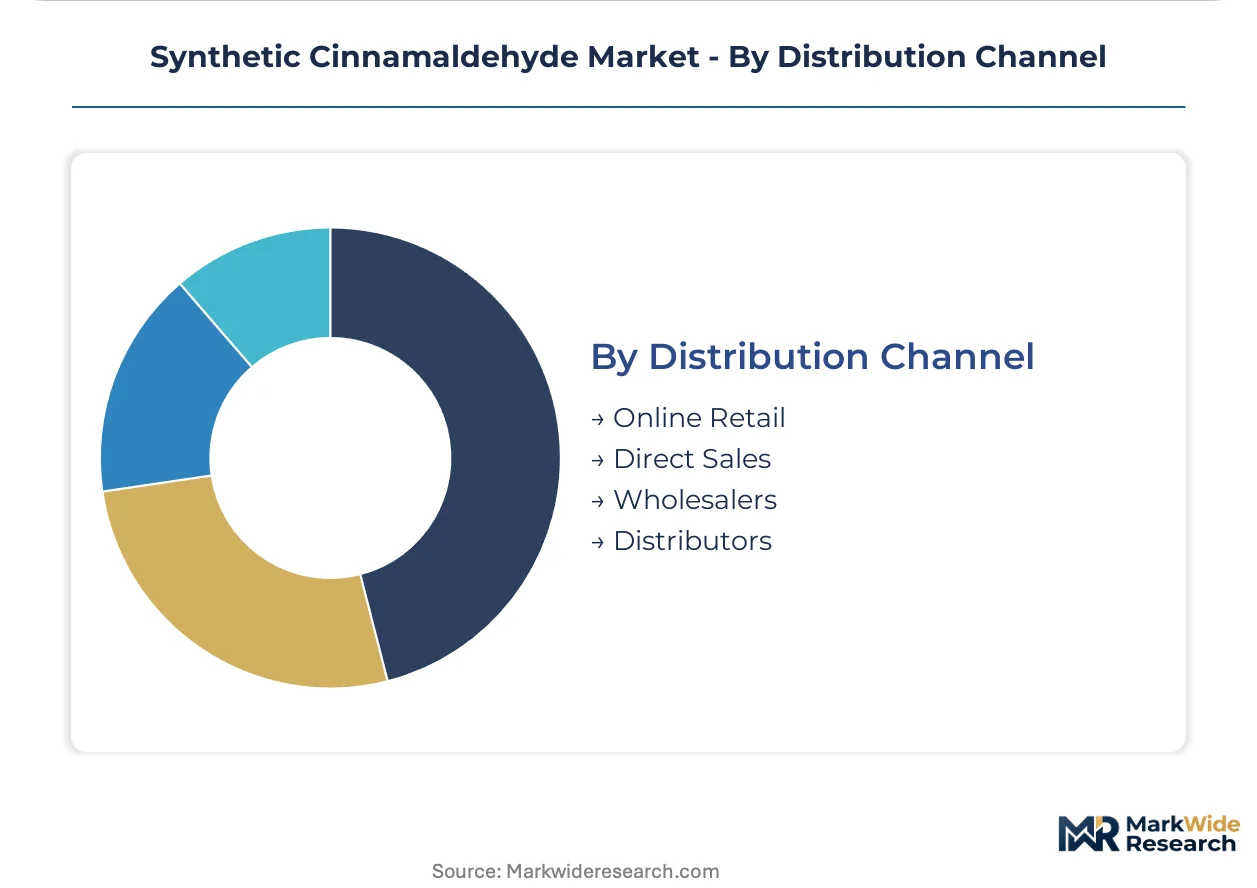
Supply concentration shapes channel selection, with integrated producers favoring direct relationships while fragmented buyers rely on distributor technical support.
- Direct Sales:Lanxess AG and Symrise AG leverage integrated benzaldehyde-to-cinnamaldehyde pipelines to sustain raw material cost advantages through captive supply arrangements.
- Distributors:Regional specialists provide REACH registration dossier management for mid-scale European importers.
- Online Retail:Limited to small-volume laboratory and research chemical procurement.
- Wholesalers:Aggregate demand from fragmented food additive compounders.
Direct sales capture the largest contract values; distributors retain relevance in regulatory navigation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex underwrites China's dominance in benzaldehyde feedstock logistics, anchoring the synthetic cinnamaldehyde trade corridor that connects Asian aromatics production to European fragrance compounders and North American flavor houses.
China
Jiangsu and Zhejiang provinces host the world's largest toluene oxidation capacity, feeding benzaldehyde-to-cinnamaldehyde pipelines that supply domestic flavorant exports and European REACH-registered imports. SAMR enforces GB standards for food flavorants that diverge from Codex Alimentarius parameters, forcing dual certification investments from exporters targeting German and Indian markets. The Yangtze River Delta chemical cluster around Shanghai concentrates backward-integrated producers with captive aromatics supply.
Germany
Specialized flavor precursor facilities in the Rhine-Ruhr industrial region anchor European supply security for fragrance compound manufacturers. ECHA REACH registration dossiers compress the qualified supplier base for cinnamaldehyde imports, consolidating procurement around ISO-certified producers with integrated benzaldehyde supply chains. Cologne and Leverkusen host technical centers where biocatalytic aldol condensation routes undergo pilot-scale validation.
India
Mumbai and Ahmedabad processors drive specification convergence under FSSAI-harmonized Codex standards for PLI scheme compliance in specialty chemicals. Food manufacturers in Gujarat require documented benzaldehyde feedstock provenance for export zone eligibility, concentrating demand among integrated domestic producers. The Maharashtra chemical corridor attracts fermentation-based cinnamaldehyde ventures seeking to bypass petrochemical price volatility.
United States
Chicago and New Jersey food processors now contract quarterly benzaldehyde-cinnamaldehyde bundles with fixed purity specifications, displacing distributor intermediaries and compressing working capital cycles. FDA food additive regulations under 21 CFR govern permissible concentrations in consumable products, while EPA oversight of benzaldehyde feedstock emissions shapes manufacturing location decisions for domestic producers. The Gulf Coast petrochemical corridor supplies aromatics feedstock to Midwest flavorant compounders.
Switzerland
Geneva and Basel fragrance houses pilot biocatalytic-derived cinnamaldehyde alternatives to secure supply chain resilience against petrochemical price spikes. Swissmedic oversight of pharmaceutical-grade intermediates creates parallel certification pathways for USP-NF monograph compliance, opening oncology and antimicrobial research applications. The country's specialized enzyme suppliers license immobilized transketolase systems to mid-scale European producers.
Synthetic Cinnamaldehyde Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded aroma chemical conglomerates commanding integrated supply chains while private manufacturers defend niche positions in regional flavorant markets. The supplier base compresses around ISO 9001-certified producers capable of sustaining REACH registration dossiers and USP-NF monograph compliance simultaneously. Three archetypes dominate: integrated petrochemical majors with captive benzaldehyde supply, biotechnology-derived specialists with fermentation-based routes, and regional compounders serving fragmented food additive demand. Competitive moves concentrate on backward integration into aromatics feedstock and technology licensing for biocatalytic production methods.
Among Germany-based integrated producers, Lanxess AG occupies a position exemplifying the petrochemical-major archetype with its benzaldehyde-to-cinnamaldehyde pipeline, while Symrise AG anchors the specialized-flavor-precursor tier through dedicated German facilities. Givaudan SA represents the biotechnology-derived specialist category, with its Swiss origin signaling positioning around clean-label fermentation routes that reduce petrochemical dependency. These three companies collectively illustrate the competitive spectrum spanning feedstock integration, geographic concentration, and production technology differentiation.
| Leading Market Players |
|---|
| Lanxess AG (Emerald Kalama Chemical) |
| Symrise AG |
| Givaudan SA |
| Takasago International Corporation |
| Merck KGaA |
| Ashland Global Holdings Inc. |
| Prasol Chemicals Pvt. Ltd. |
| Penta Manufacturing |
| Sigma-Aldrich |
| Others |
Value Network & Pricing Analysis
Ninety-day benzaldehyde inventory cycles at German fragrance compounders concentrate procurement leverage among backward-integrated producers, compressing spot-market premiums for non-integrated suppliers while amplifying cost pass-through power for captives of toluene oxidation capacity.
Pricing Analysis
Three-tier pricing structure across pharmaceutical, food-grade, and technical fragrance levels stratifies the market. Price differentiation hinges on USP-NF monograph certification and REACH registration completeness, with pharmaceutical grades commanding substantial premiums over technical grades. Cost compression in food-grade tiers is intensifying because FSSAI-harmonized Codex standards in India are converging specifications and eroding regional premiums. Small-scale fragrance compounders exhibit highest price sensitivity, while pharmaceutical firms prioritize purity documentation over unit cost.
Supply Chain Analysis
Forty-five to sixty-day lead times for REACH-registered European imports reflect inventory positioning ahead of ECHA authorization renewal windows. Supply concentrates in China, Germany, and India, with Jiangsu Province toluene oxidation feeding global benzaldehyde requirements. The chain draws from captive aromatics, acetaldehyde spot markets, and specialized enzyme suppliers for biocatalytic routes. Single-source vulnerability in Chinese benzaldehyde capacity creates concentration risk. Distribution runs through direct quarterly bundles for large food processors and distributor-managed regulatory dossiers for mid-scale importers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against supercritical CO2 cinnamon bark extracts that niche perfumers position as authenticity alternatives, requiring strategic repositioning around consistency documentation and allergen compliance.
For Market Incumbents: Consolidate procurement relationships around ISO-certified producers with integrated benzaldehyde supply chains to withstand REACH registration compression. Deepen upstream control over toluene oxidation capacity in China or secure long-term offtake agreements with Jiangsu-based aromatics producers. Biocatalytic route licensing from Swiss enzyme suppliers offers technology hedge against petrochemical feedstock volatility.
For New Entrants and Emerging Players: Differentiate on fermentation-derived production credentials that appeal to clean-label cosmetic formulators in Geneva and Basel. White-space targets include USP-NF pharmaceutical-grade supply where qualified supplier scarcity limits competition, and Indian domestic flavorant production under PLI scheme incentives. Go-to-market through direct technical sales to Mumbai and Ahmedabad processors seeking documented benzaldehyde provenance.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized aroma chemical divisions lacking REACH dossier maintenance resources. Long-term viability favors assets with dual SAMR-REACH certification capability and biocatalytic pilot infrastructure. Watch ECHA skin sensitization threshold revisions as inflection signal for reformulation-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Oxidation | Captive benzaldehyde supply insulates Lanxess and Symrise from Chinese spot market volatility. |
| Biocatalytic Production Licensing | Immobilized transketolase systems from Swiss enzyme suppliers fragment quality certification pathways. |
| Dual SAMR-REACH Certification | Parallel toxicological dossiers enable Chinese exporters to capture European contracts during competitor transitions. |
| Pharmaceutical-Grade Capacity Expansion | USP-NF monograph compliance opens oncology and antimicrobial research applications with premium positioning. |
| Direct Procurement Bundle Contracts | Quarterly benzaldehyde-cinnamaldehyde fixed-purity agreements displace distributor intermediaries for Chicago processors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the synthetic cinnamaldehyde value chain, including fragrance compound procurement managers at Swiss and German cosmetic houses, food additive technical directors in Mumbai and Ahmedabad, pharmaceutical intermediate sourcing leads, and specialty chemical distribution executives. Secondary validation drew from ECHA registration dossiers, FDA 21 CFR food additive standards, FSSAI harmonization notifications, customs trade data for benzaldehyde derivatives, and SEC filings of listed aroma chemical producers. Bottom-up volume estimates from grade-specific application consumption were triangulated against top-down aromatics feedstock allocation models.
Across the analysis window, projections incorporate segmentation by product grade, end-use application, and regional regulatory cluster. Modeled dimensions include pharmaceutical versus food-grade versus technical fragrance specifications, heat stability requirements for processed foods, and IFRA skin sensitization compliance tiers. CAGRs were derived from elasticity-adjusted consumption curves cross-referenced with benzaldehyde feedstock capacity expansion announcements and PLI scheme disbursement trajectories in Indian specialty chemicals.
Material uncertainties — benzaldehyde spot price volatility, ECHA classification revisions for skin sensitization, and FSSAI-Codex divergence timelines — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and biotechnology route commercialization rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Cedrol Methyl Ether Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Pocket Perfume Market