
 Europe Essential Oils Market | 2026-2036
Europe Essential Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Essential Oils Market Foresight
France is tilting toward expanded lavender and rosemary distillation capacity in Provence-Alpes-Côte d'Azur. Givaudan S.A. anchors its European botanical supply through long-term grower contracts in Grasse. Symrise AG leverages proprietary CO2 extraction technology for heat-sensitive citrus terpenes. Robertet Group dominates artisan-scale production of jasmine and rose absolutes from its historic base near Nice.
Europe essential oils are volatile aromatic compounds extracted from plant material through steam distillation, cold pressing, or solvent methods, typically yielding 0.01–5.00 percent oil by raw biomass weight depending on species and terroir. These oils function as functional ingredients imparting scent, antimicrobial properties, or flavor-active molecules across formulated consumer and industrial products. Steam-distilled natural oils command the largest volume share but face margin compression from synthetic alternatives in mass-market cleaning applications. CO2-extracted absolutes and supercritical fractions represent the fastest-expanding extraction-method segment, capturing premium positioning in luxury cosmetics and clinical aromatherapy where residual-solvent thresholds approach zero.
EMA guidelines on herbal medicinal products and REACH registration requirements for fragrance allergens are tightening compositional disclosure and safety-documentation burdens across the value chain. ECHA's ongoing restriction proposals on skin-sensitizing substances threaten conventional citrus oil formulations in leave-on cosmetic applications. Stakeholders must monitor regulatory divergence between EU harmonized standards and emerging national organic-certification schemes in member states.
Market Dynamics
REACH registration deadlines for fragrance allergens are compressing formulation timelines across European cosmetics supply chains, forcing distillers to rebuild traceability infrastructure from field to finished oil.
Growth Catalysts
- EU Green Deal bio-based mandates:Binding targets for renewable chemical feedstocks are redirecting industrial procurement toward certified organic essential oils in cleaning and personal care formulations.
- Clinical aromatherapy expansion:Hospital wellness programs in France and Germany are integrating pharmaceutical-grade lavender and citrus oils into patient anxiety management protocols.
- Provence-Alpes-Côte d'Azur distillation clusters:Concentrated lavender and rosemary cultivation around Grasse secures PDO-protected supply with provenance documentation for luxury fragrance houses.
Market Restraints
- Climate volatility in Mediterranean terroirs:Drought stress in French lavender zones and irregular frost patterns in Italian citrus groves are compressing yield predictability and harvest windows.
- Synthetic terpene substitution:Laboratory-derived limonene and linalool from petrochemical feedstocks are undercutting natural citrus and lavender oils in mass-market detergent and air care applications.
- ECHA restriction proposals on skin sensitizers:Pending regulatory action against conventional citrus oil phototoxicity is threatening formulation continuity in leave-on cosmetic products.
Strategic Opportunities
- Poland and Baltic organic cultivation:Underdeveloped peppermint and chamomile acreage in cooler climate zones offers expansion paths for EU organic-certified supply with lower land costs.
- CO2 extraction technology convergence:Supercritical fluid systems paired with molecular distillation are unlocking zero-residual-solvent absolutes for pharmaceutical and luxury cosmetic segments.
- Direct-to-formulator digital channels:B2B platforms connecting Provence distillers with mid-sized cosmetics manufacturers are disintermediating traditional broker networks.
Industry Challenges
- Cross-border organic certification alignment:Divergent national schemes in France, Italy, and Germany are creating documentation friction for oils traded across member state boundaries.
- Specialized distillation engineering talent:Shortage of technicians trained in both traditional alembic operation and modern supercritical system maintenance is constraining capacity expansion.
- Legacy ERP integration with traceability platforms:Small-scale distillers in Grasse and Nice are struggling to retrofit batch-tracking systems for REACH-compliant allergen disclosure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Essential Oils Market |
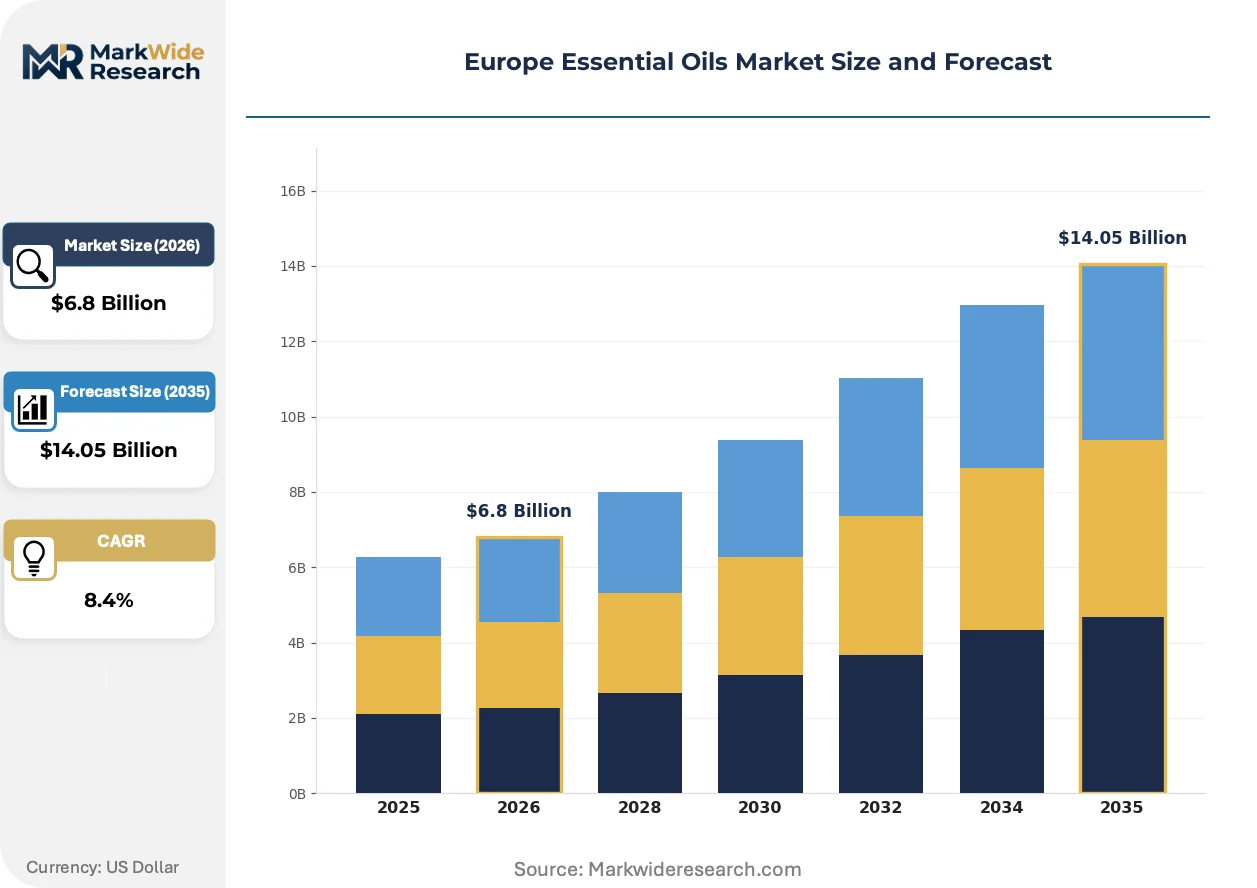
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Oils, Synthetic Oils, Blends, Absolutes Extraction Method: Steam Distillation, Cold Pressing, Solvent Extraction, CO2 Extraction Application: Cosmetics, Aromatherapy, Food & Beverages, Cleaning Products Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Supermarkets |
| Companies Covered | International Flavors & Fragrances, Inc., FLAVEX Natural Extracts GmbH, Givaudan S.A., Nako naturals GmbH, NHR Organic Oils, Symrise AG, Robertet Group, Botanical EU Ltd, DSM-Firmenich AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Essential Oils Market Shifts & Advancements
Extraction technology and regulatory disclosure requirements are compressing the gap between artisan production methods and industrial-scale quality assurance across European essential oil supply chains.
Supercritical CO2 extraction is collapsing the historical trade-off between yield efficiency and residual-solvent purity in heat-sensitive citrus terpene recovery. Premium cosmetic formulators in France and Germany are adopting these systems at accelerating rates. The technology is collapsing capital barriers that previously separated artisan distillers from pharmaceutical-grade certification.
EMA guidelines on herbal medicinal products are mandating expanded safety documentation for essential oils marketed with therapeutic claims. This regulatory pressure is forcing reformulation of existing product lines and accelerated toxicological testing budgets. Clinical aromatherapy applications in German hospital systems are most affected, with suppliers rebuilding dossiers to meet strengthened evidence requirements.
Certification-driven purchasing patterns are redirecting procurement decisions toward PDO-protected supply with full chain-of-custody documentation. Mid-sized cosmetics manufacturers are displacing spot-market buying with multi-year grower contracts in Provence and Sicily. French luxury fragrance houses and Italian natural cosmetics brands are the most visible adopters of this traceability-first sourcing model.
Europe Essential Oils Market Segmentation
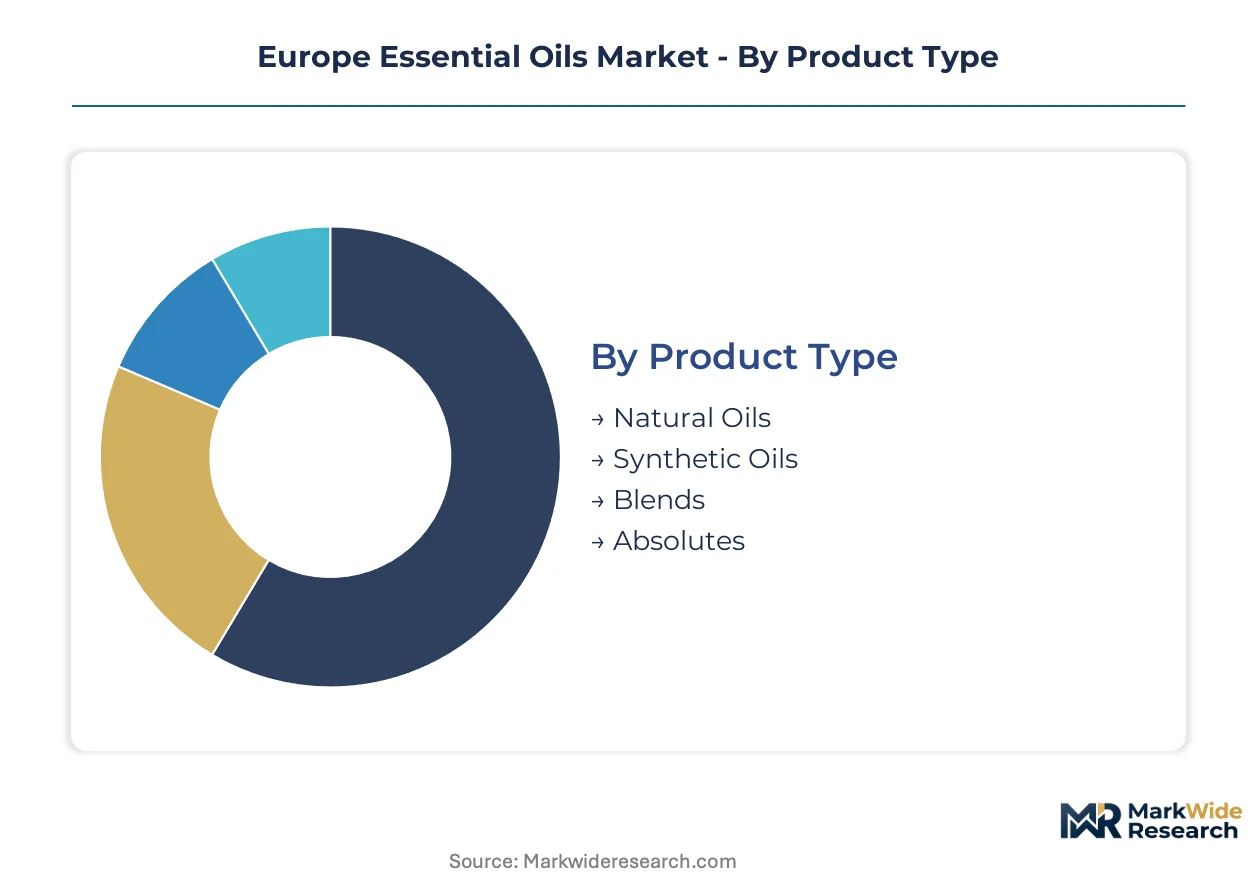
Segmentation in the Europe Essential Oils Market reveals divergent margin structures and regulatory exposure across product grades, extraction technologies, and end-use applications. Distillers and formulators calibrate inventory cycles and certification investments differently depending on which segment anchor their revenue base.
Product Type:
Cycle times vary dramatically across product grades, with synthetic oils turning inventory weekly while absolutes age months before release.
- Natural Oils:Steam-distilled or cold-pressed volatile compounds retaining full botanical complexity and traceable terroir documentation. French cosmetics manufacturers in Grasse and Paris concentrate procurement here for REACH-compliant fragrance formulations, though climate volatility in Provence lavender zones constrains supply predictability.
- Absolutes:Solvent-extracted or CO2-derived concentrated aromatic materials from delicate flowers like jasmine and rose. Italian luxury fragrance houses near Milan and Florentine cosmetics laboratories drive demand for zero-residual-solvent grades, with ECHA skin-sensitizer restrictions forcing reformulation timelines.
- Synthetic Oils:Laboratory-derived terpene replicas from petrochemical feedstocks.
- Blends:Proprietary combinations of natural and synthetic components.
Natural oils anchors the volume base while absolutes gains share at the steepest rate.
Extraction Method:
Capital intensity and batch duration separate artisan alembic operators from industrial supercritical facilities.
- Steam Distillation:Traditional heated water vapor passing through plant material to liberate volatile oils. Provençal lavender and rosemary distillers around Grasse dominate European capacity, with German pharmaceutical aromatherapy suppliers demanding batch-specific compositional certificates.
- CO2 Extraction:Supercritical carbon dioxide selectively dissolving heat-sensitive terpenes at moderate temperatures. French and German premium cosmetic formulators are displacing solvent extraction for citrus and floral materials, as REACH allergen disclosure requirements favor zero-residual processes.
- Cold Pressing:Mechanical rupture of citrus peels without thermal degradation.
- Solvent Extraction:Organic solvent dissolution followed by evaporation.
Steam distillation retains the widest installed base while CO2 extraction climbs the fastest among new capacity investments.
Application:
Regulatory scrutiny intensity varies sharply across end-use categories, with therapeutic claims triggering EMA herbal product guidelines.
- Cosmetics:Fragrance and functional ingredients in skincare, haircare, and fine perfumery. French and Italian luxury houses concentrate premium absolutes procurement here, though ECHA restriction proposals on phototoxic citrus oils threaten leave-on formulation continuity.
- Aromatherapy:Therapeutic and wellness applications including clinical anxiety management protocols. German hospital systems and French spa networks are expanding pharmaceutical-grade lavender and citrus oil sourcing, with EMA evidence requirements forcing toxicological dossier rebuilds.
- Food & Beverages:Flavor-active molecules in beverages and culinary preparations.
- Cleaning Products:Natural antimicrobial and fragrance components in household and industrial formulations.
Cosmetics anchors the revenue base while aromatherapy expands most quickly under clinical adoption.
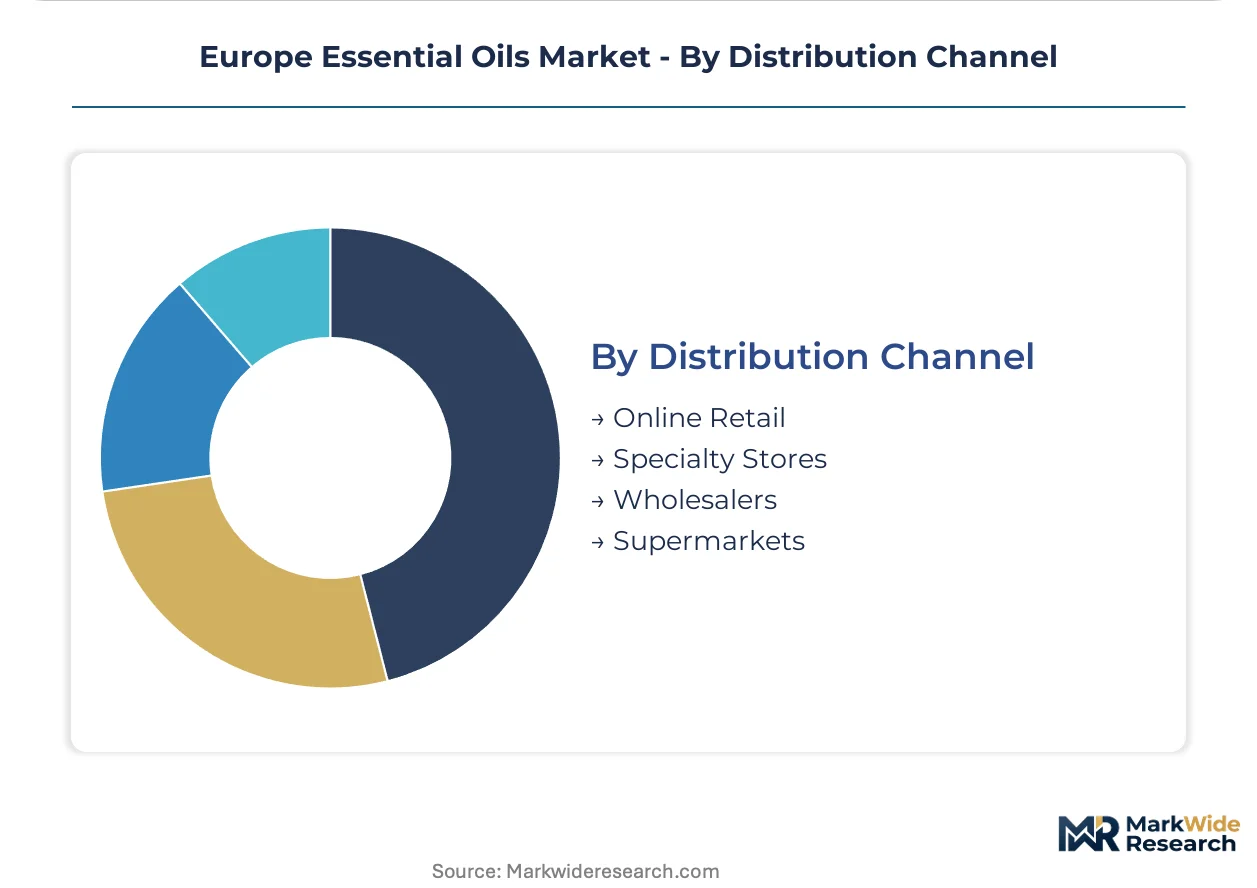
Distribution Channel:
Channel selection determines traceability depth and margin capture for distillers of different scale.
- Wholesalers:Aggregated bulk supply to cosmetics manufacturers and industrial formulators. Traditional broker networks in Grasse and Sicily still handle volume flows, though direct-to-formulator platforms are disintermediating smaller transactions.
- Specialty Stores:Curated retail for artisan producers and clinical aromatherapy practitioners. German naturopathic supply chains and French pharmacy networks concentrate demand here, with organic certification documentation required at point of sale.
- Online Retail:Direct consumer and small business e-commerce platforms.
- Supermarkets:Mass-market packaged oils for household applications.
Wholesalers anchors volume throughput while specialty stores gains share fastest on certification-premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PDO-protected cultivation clusters in Provence and Sicily concentrate premium supply, while REACH compliance costs are redrawing competitive boundaries across member states. German pharmaceutical-grade demand and French luxury fragrance procurement anchor the regional value chain.
France
Grasse-based distillers anchor lavender and jasmine absolute production for luxury fragrance houses. ANSM oversight of cosmetic safety dossiers tightens documentation requirements for leave-on formulations. Provence-Alpes-Côte d'Azur distillation capacity is expanding around historic alembic clusters near Nice.
Germany
Hospital wellness programs in Bavaria and Baden-Württemberg drive pharmaceutical-grade lavender oil procurement for clinical aromatherapy protocols. BfArM implementation of EMA herbal medicinal guidelines forces toxicological dossier rebuilds. Frankfurt-Rhine-Main logistics hubs consolidate bulk distribution to cosmetics manufacturers.
Italy
Sicilian and Calabrian citrus groves supply cold-pressed bergamot and lemon terpenes for flavor and fragrance applications. ECHA restriction proposals on phototoxic furanocoumarins threaten conventional oil formulations. Tuscan organic chamomile cultivation around Florence is scaling for EU-certified cosmetic supply.
Spain
Andalusian rosemary and thyme distillation serves industrial cleaning and personal care formulators seeking bio-based feedstocks. Spanish organic certification schemes diverge from French and German standards, creating cross-border documentation friction. Valencia citrus processing clusters are retrofitting CO2 extraction capacity for zero-residual-solvent output.
Poland
Underdeveloped peppermint and chamomile acreage in Masovia and Greater Poland offers lower-cost organic expansion paths. Polish organic certification aligns with EU regulations but operates distinct audit protocols from western member states. Warsaw-based B2B platforms are connecting Baltic growers directly with mid-sized German cosmetics manufacturers.
Europe Essential Oils Market Competitive Landscape
Integrated fragrance houses and specialized botanical extractors split the market between scale-driven supply security and terroir-specific provenance capture. The vendor base concentrates around three strategic archetypes: multinational flavor and fragrance conglomerates with captive cultivation networks; mid-sized regional distillers leveraging PDO certification for premium positioning; and technology-focused extractors deploying supercritical CO2 systems for pharmaceutical-grade compliance. Competitive moves center on backward integration into contracted grower acreage and technology licensing partnerships for zero-residual extraction methods.
Among Switzerland-based integrated players, Givaudan S.A. and DSM-Firmenich AG exemplify the conglomerate archetype with extensive European botanical supply chains. German specialist FLAVEX Natural Extracts GmbH occupies a position within the technology-focused tier, while France's Robertet Group anchors the heritage distiller segment from its historic base near Grasse. These three represent the strategic positioning spectrum: scale-driven supply security, proprietary extraction technology, and terroir-provenanced artisan production.
| Leading Market Players |
|---|
| International Flavors & Fragrances, Inc. |
| FLAVEX Natural Extracts GmbH |
| Givaudan S.A. |
| Nako naturals GmbH |
| NHR Organic Oils |
| Symrise AG |
| Robertet Group |
| Botanical EU Ltd |
| DSM-Firmenich AG |
| Others |
Supply & Pricing Matrix
Rhône-Alpes logistics corridors linking Grasse distillation clusters to Frankfurt-Rhine-Main distribution hubs concentrate freight cost volatility where PDO-certified lavender and rosemary oils command premium positioning against standard-grade alternatives.
Pricing Analysis
REACH registration requirements for fragrance allergens dictate the pricing tier structure across European essential oil supply chains. Three-tier pricing structure across PDO-certified premium, EU-organic standard, and conventional economy levels segments buyer archetypes sharply. Cost compression in economy-grade citrus oils is intensifying because synthetic terpene substitution from petrochemical feedstocks undercuts natural extraction costs. Mass-market cleaning product manufacturers exhibit highest price sensitivity, while French luxury fragrance houses demonstrate lowest sensitivity due to provenance documentation requirements.
Supply Chain Analysis
Extended payment terms from Grasse-based distillers to Provence lavender growers strain working capital cycles during harvest concentration windows. Geographic supply concentrates in France, Italy, and Spain where Mediterranean terroirs anchor lavender, citrus, and rosemary cultivation. Raw material dependencies rest on climate-sensitive biomass yields, seasonal harvest windows, and organic certification audit cycles. Single-source vulnerability from drought stress in French lavender zones threatens formulation continuity. Distribution runs through wholesaler broker networks in Grasse and Sicily, though direct-to-formulator B2B platforms are disintermediating smaller transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated mid-sized cosmetics manufacturers displacing spot-market procurement with multi-year grower contracts, fragmenting traditional broker dominance.
For Market Incumbents: Insulate margin position by deepening backward integration into contracted PDO-protected acreage in Provence-Alpes-Côte d'Azur and accelerating CO2 extraction technology licensing partnerships. Synthetic terpene substitution in mass-market applications threatens volume-based revenue streams. Certification investment in EU organic and REACH-compliant traceability infrastructure anchors defensive positioning. For New Entrants and Emerging Players: Build out underdeveloped peppermint and chamomile cultivation in Poland and Baltic zones where land costs undercut western European organic production. Direct-to-formulator digital channels connecting Baltic growers with mid-sized German cosmetics manufacturers offer the most penetrable go-to-market angle, bypassing entrenched Grasse broker networks. For Investors and Strategic Acquirers: Technology-focused extractors deploying supercritical CO2 systems for pharmaceutical-grade compliance represent the most attractive acquisition archetype. Long-term viability hinges on zero-residual-solvent certification moats widening as EMA herbal product guidelines tighten. Monitor ECHA restriction proposals on skin-sensitizing substances for early signals of formulation disruption requiring portfolio repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contracted Grower Acreage | Secures PDO-provenanced supply for REACH-compliant fragrance formulations in Grasse. |
| CO2 Extraction Technology Licensing | Unlocks zero-residual-solvent absolutes for German pharmaceutical aromatherapy segments. |
| Direct-to-Formulator Digital Platform Launch | Disintermediates traditional Grasse broker networks for mid-sized cosmetics manufacturers. |
| EU Organic Certification Investment | Aligns procurement with EU Green Deal bio-based mandates for cleaning applications. |
| Poland-Baltic Cultivation Expansion | Captures lower-cost organic supply for German cosmetics manufacturer procurement. |
Research Methodology
Desk research of customs trade databases, ECHA regulatory filings, and EU agricultural statistics preceded structured interviews with lavender distillery operators, cosmetics procurement managers, fragrance house technical directors, and organic certification auditors. Primary fieldwork across Provence-Alpes-Côte d'Azur, Sicily, and Polish cultivation zones validated yield estimates and distillation capacity expansion plans. Secondary sources included REACH registration databases, ANSM cosmetic safety dossiers, and EU PDO geographic indication records. Bottom-up biomass yield modeling triangulated against top-down cosmetics manufacturer procurement survey data.
Assumptions held fixed include EU Green Deal bio-based mandate enforcement timelines and EMA herbal medicinal product guideline implementation trajectories, while climate volatility scenarios and synthetic substitution rates were varied across sensitivity analyses. Segmentation dimensions modeled encompass product grade tier, extraction method technology, end-use application regulatory intensity, and regional cultivation cluster. CAGRs were derived from compound growth trajectory fitting to validated volume and value data points. Industry-specific forecast inputs incorporated lavender and citrus yield variability coefficients from French agricultural ministry surveys.
Practitioners should monitor ECHA restriction proposal finalizations, drought frequency indices in Mediterranean growing zones, and synthetic terpene cost curves for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Flavor and Fragrance Market
Flavor and Fragrance Chemicals
Massoia Bark Essential Oil Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Nonanal Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Cedarwood Oil Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Guaiacwood Oil Market
Flavor and Fragrance Chemicals
India Essential Oils Market