
 Ethylidene Norbornene Market | 2026-2036
Ethylidene Norbornene Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylidene Norbornene Market Analysis
Advanced metallocene catalyst technology is fragmenting traditional Ziegler-Natta production pathways across the ethylene-propylene-diene monomer value chain. Exxon Mobil Corporation leverages its Baton Rouge polymer complex to sustain captive supply of high-purity ENB grades for specialty rubber applications. INEOS Group Holdings anchors European demand through its integrated crackers and downstream compounding facilities in Belgium and Germany.
Ethylidene norbornene is a bicyclic diene monomer with a molecular formula of C9H12, manufactured via Diels-Alder cycloaddition of cyclopentadiene with butadiene followed by isomerization, serving primarily as the third monomer in EPDM rubber to introduce pendant unsaturation for sulfur vulcanization. The polymer segment dominates volume consumption due to tire manufacturers' requirements for ozone-resistant sidewall compounds, while the chemical intermediate category records faster expansion as pharmaceutical and agrochemical syntheses adopt ENB-derived building blocks. Adhesive applications occupy a narrower but higher-margin niche serving electronics and automotive bonding where thermal cycling resistance commands premium pricing.
EPA regulations under the Toxic Substances Control Act govern ENB manufacturing emissions and workplace exposure limits in the United States, while REACH registration requirements in Europe mandate comprehensive toxicological dossiers for monomer import and polymer production. Japan's METI enforces Chemical Substances Control Law classifications that restrict unregistered ENB derivatives from industrial use. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect fluoropolymer demand toward EPDM alternatives in sealing and gasket applications.
Market Dynamics
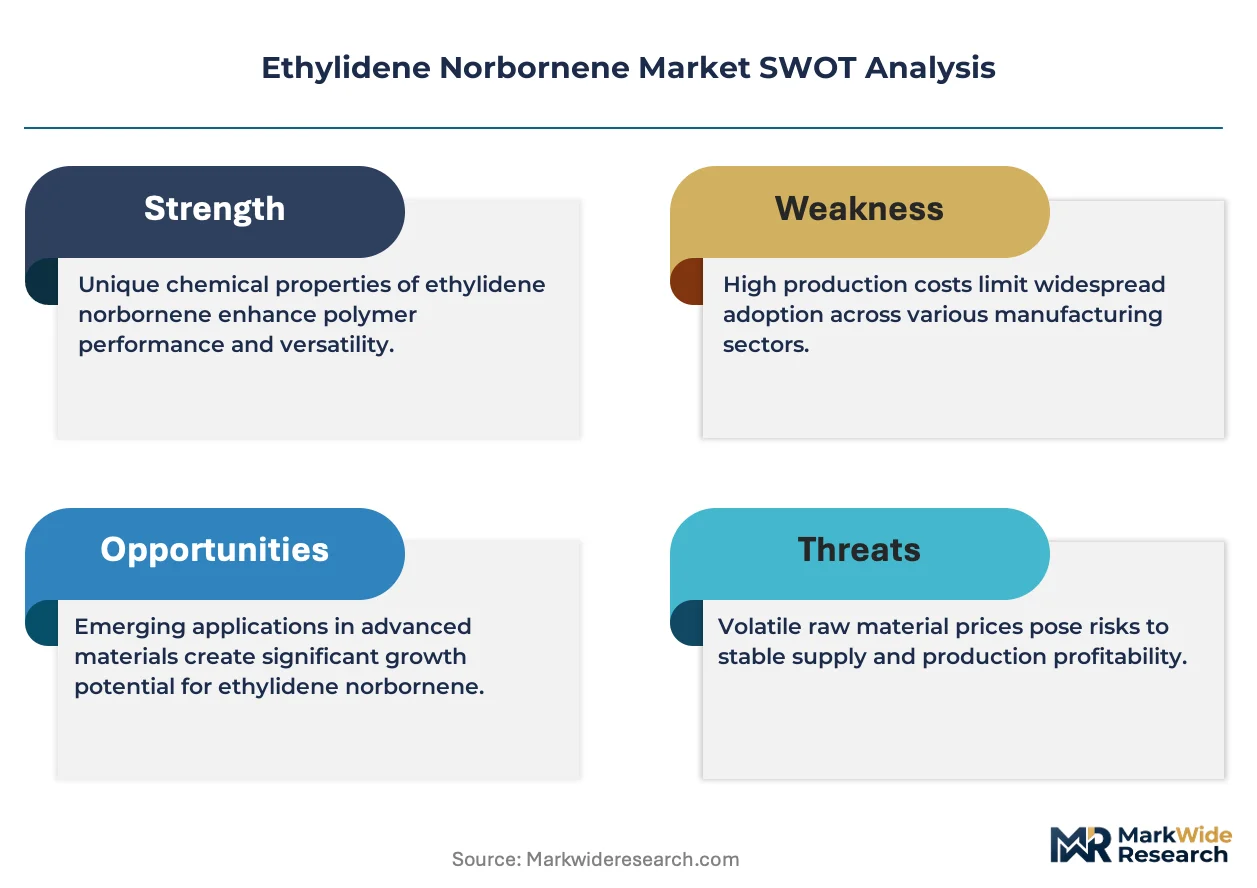
Metallocene catalyst adoption is fragmenting the ethylene-propylene-diene monomer value chain, compressing Ziegler-Nata production margins while specialty tire manufacturers in Thailand's Eastern Economic Corridor scale high-purity ENB purchases for electric vehicle thermal management applications.
Growth Catalysts
- EPDM Rubber Demand Surge:Specialty tire manufacturers in Southeast Asia are scaling purchases as electric vehicle platforms require higher thermal stability in sidewall compounds. Thailand's petrochemical complexes serve expanding regional automotive supply chains.
- REACH Registration Compliance:The European regulation mandates comprehensive toxicological dossiers for monomer import, creating competitive moats for producers with established registration pathways and certified purity grades.
- Pharmaceutical Synthesis Expansion:ENB-derived building blocks are accelerating adoption in agrochemical and pharmaceutical intermediate applications, diversifying demand beyond traditional polymer end-uses.
Market Restraints
- Cyclopentadiene Feedstock Volatility:Diels-Alder cycloaddition inputs face price swings tied to naphtha cracker operating rates, compressing margin predictability for ENB manufacturers without backward-integrated supply.
- China GB Standard Tightening:Industrial chemical purity specifications are elevating capital requirements for quality assurance systems, disadvantaging smaller producers lacking analytical infrastructure.
- Fluoropolymer Substitution Threat:Per- and polyfluoroalkyl substance restrictions could redirect some sealing and gasket demand toward EPDM alternatives, though fluoropolymer incumbents retain performance advantages in extreme temperature applications.
Strategic Opportunities
- Japan METI Chemical Safety Alignment:Chemical Substances Control Law classifications create first-mover advantages for producers registering ENB derivatives ahead of unregistered competitor lockout.
- Adhesive Premium Niche Expansion:Electronics and automotive bonding applications command pricing power where thermal cycling resistance differentiates ENB-formulated solutions from commodity alternatives.
- Integrated Cracker-Downstream Complexes:Belgium and Germany host petrochemical hubs where captive butadiene and cyclopentadiene streams enable cost-competitive ENB production with logistics advantages to European tire compounders.
Industry Challenges
- Metallocene Catalyst Talent Scarcity:Polymerization chemists with expertise in single-site catalyst systems command premium compensation, constraining rapid technology transfer at mid-scale producers.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA Toxic Substances Control Act, REACH, and METI compliance creates regulatory friction that delays product launches by 18-24 months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylidene Norbornene Market |
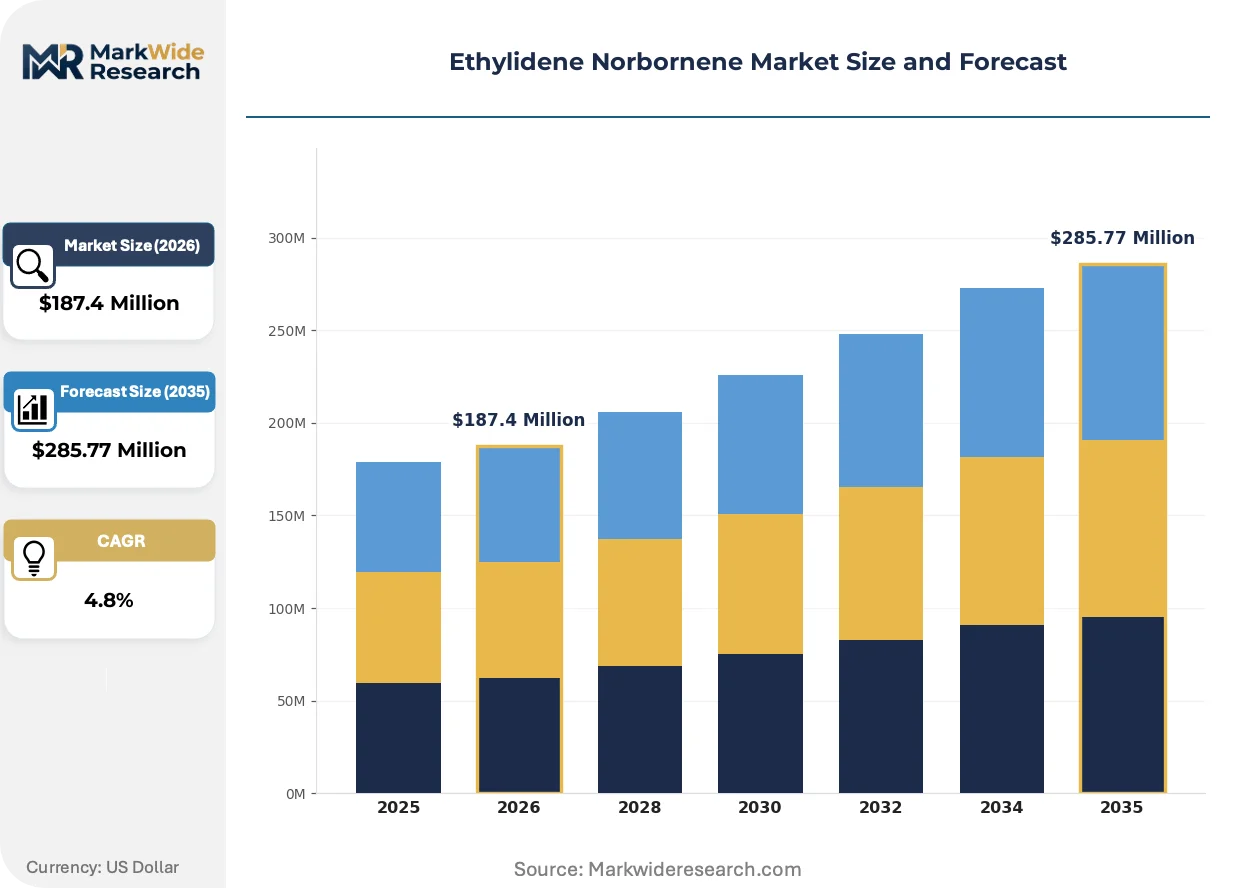
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Chemical Intermediate, Copolymer, Adhesive Application: Tire Manufacturing, Automotive, Electronics, Coatings End User: Manufacturers, Distributors, OEMs, Retailers Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Exxon Mobil Corporation, INEOS Group Holdings, Dow Chemical Company, Mitsui Chemicals, JXTG Nippon Oil & Energy Corporation, Zeon Corporation, LyondellBasell Industries, Evonik Industries, Jilin City Dayu Chemical Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylidene Norbornene Market Emerging Trajectories
Advanced polymerization technologies and regulatory fragmentation are reshaping competitive positioning across the ethylene-propylene-diene monomer ecosystem, with catalyst innovation and jurisdictional compliance emerging as primary differentiation vectors.
Single-site metallocene catalyst systems is hybridizing traditional Ziegler-Natta production pathways by enabling precise control over ENB incorporation levels in EPDM terpolymers. Specialty compounders in automotive sealing applications are adopting these systems fastest, drawn by reduced extractables and tighter molecular weight distribution. The technology is compressing commodity-grade margins while expanding premium-grade addressable markets.
Japan's METI Chemical Substances Control Law is tightening registration requirements for ENB derivatives used in industrial applications, creating compliance barriers for unregistered imports. Domestic formulators are consolidating supply relationships around pre-registered producers to avoid use restrictions. Pharmaceutical and agrochemical synthesis segments face the steepest compliance timelines, accelerating preference for established Japanese and European suppliers.
Automotive OEMs are unbundling traditional rubber compound procurement from tire manufacturer specifications, establishing direct ENB purity requirements for electric vehicle thermal management systems. Tier-1 suppliers in Thailand's Eastern Economic Corridor are responding by qualifying multiple ENB grades against OEM-specific test protocols. This pattern concentrates most visibly in Southeast Asian supply chains serving battery platform manufacturers.
Ethylidene Norbornene Market Segmentation
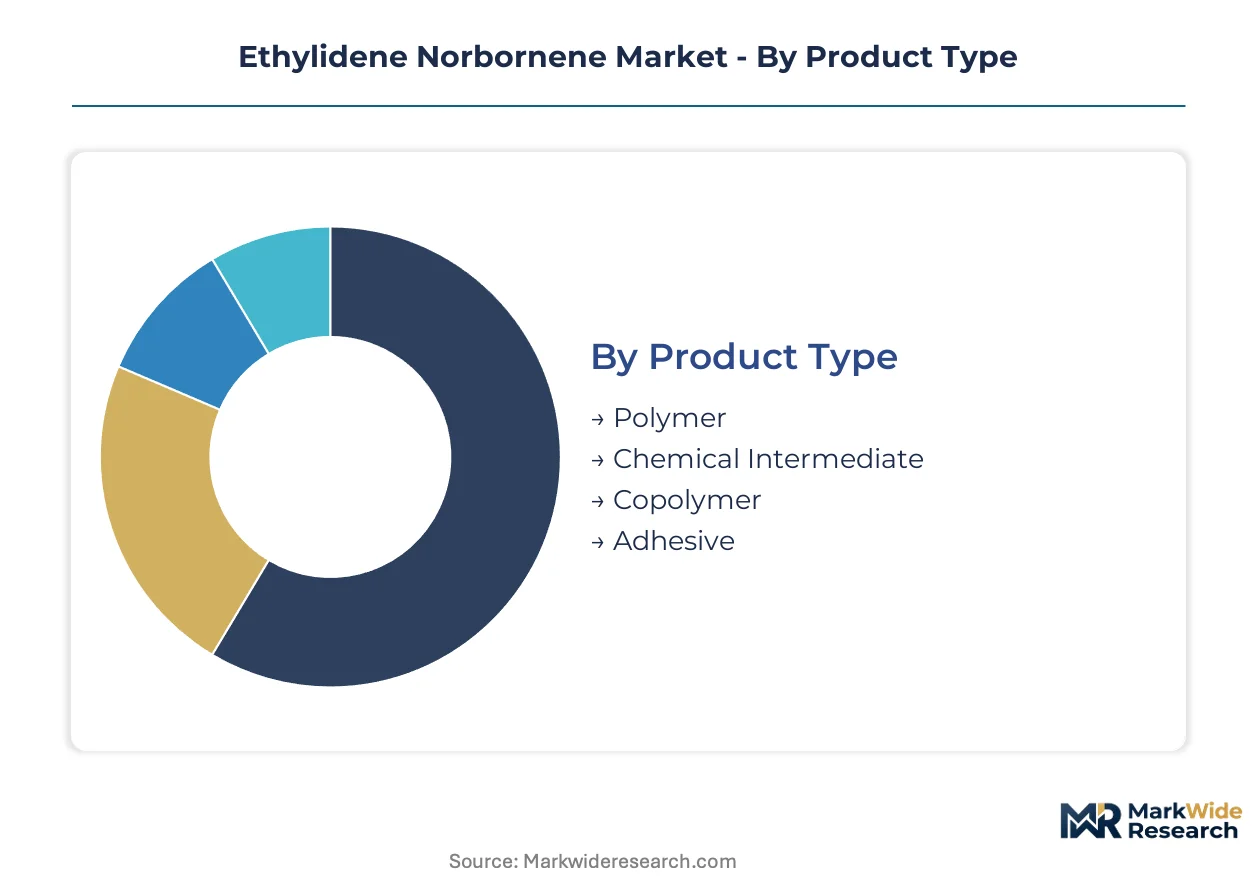
ENB's role as a specialty monomer creates distinct value pools across molecular applications. Segmentation reveals how purity grades, formulation requirements, and regulatory compliance reshape procurement patterns across tire, automotive, and electronics supply chains.
Product Type:
After-sales technical support intensity varies sharply across ENB grades, with polymer applications demanding continuous formulation troubleshooting while adhesive grades require application engineering on-site.
- Polymer:High-purity ENB serves as the third monomer in EPDM terpolymers, introducing controlled unsaturation for sulfur vulcanization. Demand concentrates in Thailand's Eastern Economic Corridor where specialty tire manufacturers qualify multiple grades against electric vehicle thermal management protocols. REACH registration requirements elevate competitive moats for established producers.
- Chemical Intermediate:ENB-derived building blocks accelerate adoption in pharmaceutical and agrochemical synthesis, diversifying demand beyond rubber applications. Pharmaceutical formulators in Japan consolidate supply around METI-registered producers to avoid Chemical Substances Control Law restrictions on unregistered derivatives.
- Copolymer:Modified ethylene-propylene systems incorporate ENB at varying incorporation levels for tailored crosslink density.
- Adhesive:Electronics and automotive bonding applications command premium pricing where thermal cycling resistance differentiates formulations from commodity alternatives.
Polymer holds the largest share; momentum sits with chemical intermediate applications.
Application:
Cost tier stratification separates specification-grade ENB for automotive OEMs from standard grades serving general industrial compounding.
- Tire Manufacturing:Ozone-resistant sidewall compounds require precise ENB incorporation levels metallocene catalyst systems now deliver with reduced extractables. Southeast Asian specialty tire producers scale purchases as electric vehicle platforms demand higher thermal stability in rubber formulations.
- Automotive:Direct ENB purity requirements now flow from automotive OEMs unbundled from traditional tire manufacturer specifications. Tier-1 suppliers in Thailand respond by qualifying grades against OEM-specific test protocols for battery platform thermal management.
- Electronics:Adhesive formulations serving semiconductor packaging and display bonding require ultra-low moisture specifications.
- Coatings:Protective and industrial coatings utilize ENB-modified resins for enhanced weatherability and chemical resistance.
Tire manufacturing dominates volume consumption; automotive applications are climbing the fastest on electric vehicle thermal management specifications.
End User:
Customer type determines procurement sophistication, with OEMs imposing direct purity standards while distributors aggregate fragmented demand.
- Manufacturers:EPDM rubber compounders and specialty chemical producers purchase ENB in bulk quantities with certified purity documentation. China's GB standards for industrial chemical purity tighten feedstock specifications, elevating capital requirements for quality assurance systems at purchasing facilities.
- OEMs:Automotive original equipment manufacturers now specify ENB grades directly rather than delegating to tire suppliers, concentrating qualification activity in Southeast Asian supply chains.
- Distributors:Regional chemical distributors aggregate demand from mid-scale compounders lacking direct producer relationships.
- Retailers:Specialty chemical retailers serve small-volume adhesive and coatings formulators with packaged ENB derivatives.
Manufacturers capture the largest procurement volume; OEMs are gaining share fastest on unbundled specification authority.
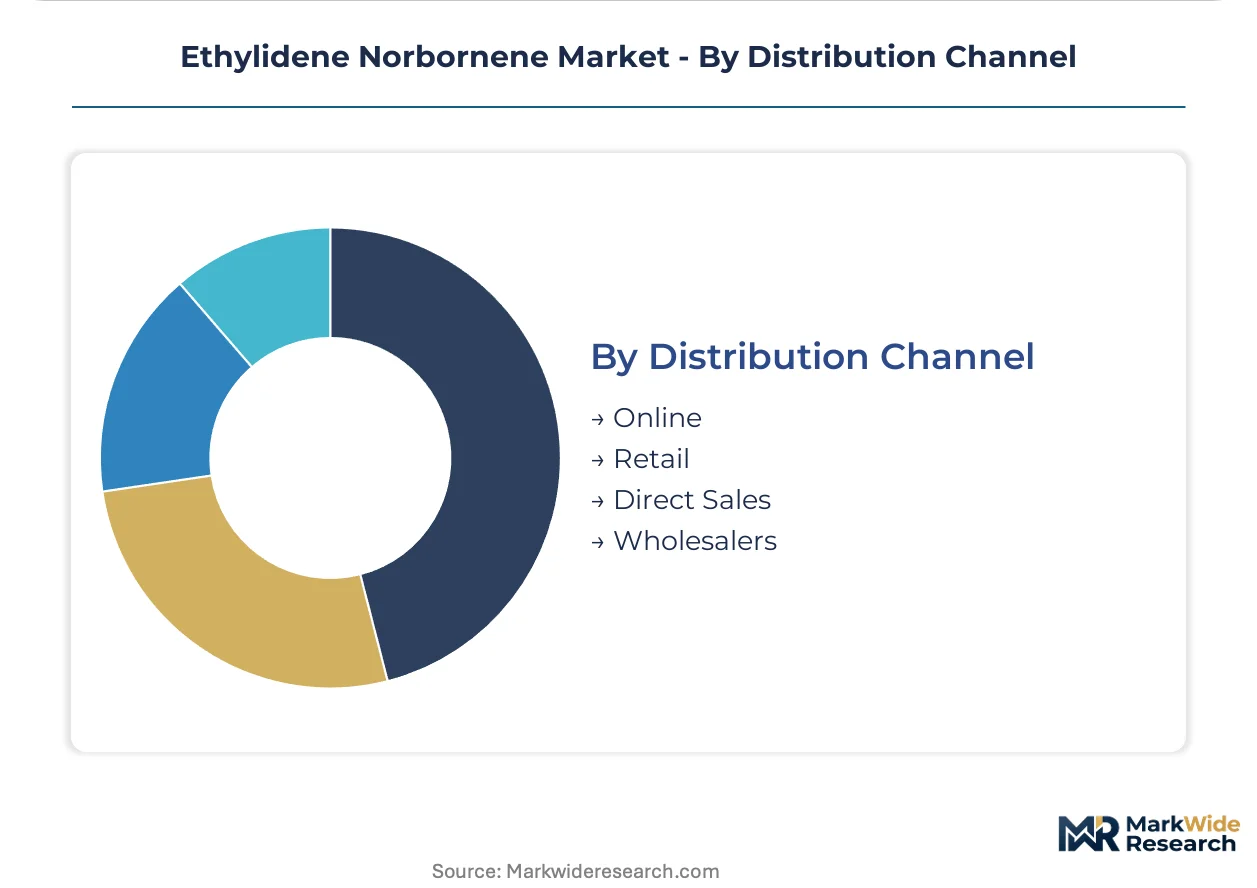
Distribution Channel:
Supply concentration shapes channel selection, with direct sales dominating bulk polymer volumes while online platforms fragment specialty adhesive trade.
- Direct Sales:Long-term supply agreements anchor ENB procurement for major EPDM producers with backward-integrated petrochemical complexes. Exxon Mobil's Baton Rouge polymer complex sustains captive supply relationships with specialty rubber manufacturers.
- Wholesalers:Regional chemical wholesalers bridge geographic gaps between European producers and Asian compounders, with Belgium and Germany serving as logistics hubs.
- Online:Digital platforms expand access for small-volume pharmaceutical and agrochemical synthesis customers seeking ENB-derived building blocks.
- Retail:Specialty chemical retailers serve adhesive formulators requiring technical consultation alongside product supply.
Direct sales holds the largest share; online channels show steepest expansion trajectory for specialty synthesis segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium and Germany export ENB derivatives to Southeast Asian tire compounders through integrated petrochemical corridors, while Japanese producers supply METI-registered grades to domestic pharmaceutical formulators.
United States
Specialty rubber manufacturers along the Gulf Coast purchase high-purity ENB for electric vehicle thermal management compounds. EPA Toxic Substances Control Act enforcement tightens emissions monitoring at Diels-Alder production facilities. Exxon Mobil's Baton Rouge polymer complex sustains captive supply relationships with regional EPDM compounders.
Germany
Automotive OEMs in Baden-Württemberg specify direct ENB purity requirements unbundled from tire supplier procurement. REACH registration mandates elevate competitive barriers for monomer import and polymer production. INEOS Group Holdings anchors European demand through integrated crackers and downstream compounding facilities in Belgium and Germany.
China
Industrial chemical producers scale ENB purchases for EPDM rubber serving domestic electric vehicle battery platforms. GB standards for industrial chemical purity tighten feedstock specifications, elevating capital requirements for quality assurance infrastructure. Petrochemical complexes in Shandong Province serve expanding regional automotive supply chains with backward-integrated cyclopentadiene streams.
Japan
Pharmaceutical and agrochemical formulators consolidate supply around METI-registered ENB producers to avoid Chemical Substances Control Law restrictions. METI enforces classification systems that lock out unregistered derivatives from industrial applications. Domestic specialty chemical producers in the Chubu region qualify multiple ENB grades against OEM-specific test protocols.
Thailand
Specialty tire manufacturers in the Eastern Economic Corridor scale high-purity ENB purchases as electric vehicle platforms demand enhanced thermal stability in sidewall compounds. Thailand's Board of Investment incentives attract petrochemical investments serving regional automotive supply chains. Tier-1 suppliers respond to unbundled OEM specifications by qualifying grades against battery platform thermal management protocols.
Ethylidene Norbornene Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors with captive feedstock positions and backward-integrated cyclopentadiene access. Three strategic archetypes dominate: integrated oil majors with polymer complexes, Asian chemical conglomerates with regional distribution networks, and European diversified industrials with REACH-registered purity grades. Competitive moves center on metallocene catalyst technology licensing and geographic expansion into Thailand's Eastern Economic Corridor.
Within the integrated major tier, Exxon Mobil Corporation and INEOS Group Holdings exemplify producers leveraging captive supply chains. Mitsui Chemicals and JXTG Nippon Oil & Energy Corporation represent Japanese conglomerates navigating METI registration requirements. Dow Chemical Company and LyondellBasell Industries occupy positions bridging American production scale with European regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| INEOS Group Holdings |
| Dow Chemical Company |
| Mitsui Chemicals |
| JXTG Nippon Oil & Energy Corporation |
| Zeon Corporation |
| LyondellBasell Industries |
| Evonik Industries |
| Jilin City Dayu Chemical Industrial |
| Others |
Supply Flow & Price Mechanics
Thailand's Eastern Economic Corridor concentrates specialty ENB capacity serving electric vehicle tire compounders, translating feedstock security into pricing leverage over downstream automotive OEMs. This geographic clustering compresses logistics costs while elevating purity-grade premiums for producers with metallocene catalyst capabilities.
Pricing Analysis
The technology-generation pricing gap separates legacy Ziegler-Natta grades from metallocene-catalyzed specialty ENB, with next-generation ultra-low-extractables formulations commanding substantial premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and volume scale, with REACH-registered purity grades drawing sustained premiums. Cost compression in standard grades intensifies as Chinese producers expand cyclopentadiene-integrated capacity. Tire manufacturers exhibit highest price sensitivity, while pharmaceutical formulators prioritize METI registration compliance over unit cost.
Supply Chain Analysis
Upstream feedstock dynamics center on cyclopentadiene availability from naphtha cracker operations, with butadiene co-product streams anchoring cost structures. Supply concentrates in Belgium, Germany, and Thailand, where integrated petrochemical complexes draw from captive Diels-Alder inputs. Raw material dependencies rest on cyclopentadiene dimer supply, butadiene monomer availability, and metallocene catalyst precursor access. Single-source vulnerability characterizes pharmaceutical-grade ENB, where Japanese METI registration creates effective supply exclusivity. Distribution runs through long-term offtake agreements for polymer volumes, with spot channels serving specialty synthesis customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story, where REACH and METI registration requirements erect structural barriers that protect incumbent positions through compliance switching costs.
For Market Incumbents: Insulate market position by deepening captive cyclopentadiene integration at Thailand's Eastern Economic Corridor complexes, securing feedstock cost advantage against emerging Chinese producers. Accelerate metallocene catalyst R&D to widen the technology-generation pricing gap, defending premium-tier margins from Ziegler-Natta commoditization. Prioritize METI derivative registration ahead of Japanese Chemical Substances Control Law enforcement timelines. For New Entrants and Emerging Players: India's underpenetrated pharmaceutical synthesis segment offers white-space entry, with domestic formulators seeking ENB-derived building blocks outside Japanese and European supply consolidation. Target adhesive applications in electronics packaging, where thermal cycling specifications create specification-driven procurement less sensitive to scale economies. Pursue digital platform distribution to aggregate fragmented specialty synthesis demand without direct sales infrastructure investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core ENB assets lacking REACH registration completeness. Long-term viability frames around regulatory compliance infrastructure as the scarce asset, with five-to-ten year value accretion tied to registration moat maintenance. Watch metallocene catalyst patent expiration schedules as inflection indicators for technology-generation pricing compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclopentadiene | Captive Diels-Alder feedstock at Thailand's Eastern Economic Corridor locks in cost position against naphtha volatility. |
| Metallocene Catalyst Licensing Agreement | Technology transfer from Exxon Mobil or Dow enables premium-grade ENB production with reduced extractables. |
| REACH Registration Completion | Full toxicological dossier submission to ECHA secures European market access ahead of unregistered competitor lockout. |
| Long-term Supply Agreement with Tier-1 Tire Manufacturer | Multi-year offtake with Thai specialty tire producers anchors volume through electric vehicle platform ramp. |
| Joint Venture with Japanese Pharmaceutical Formulator | METI-registered partnership structure navigates Chemical Substances Control Law restrictions on unregistered derivatives. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC petrochemical division filings, and ECHA registration databases. Primary interviews engaged plant managers at European ENB production facilities, procurement leads at Thai specialty tire manufacturers, and technical R&D directors at EPDM compounders. Secondary validation drew from Cefic chemical industry reports, Japan Chemical Industry Association regulatory bulletins, and Thailand Board of Investment project disclosures. Bottom-up demand modeling triangulated against top-down petrochemical capacity assessments.
Forecast inputs incorporate grade-tier segmentation, end-use industry demand patterns, and regional production hub capacity utilization. Volume and value outputs reflect analytical framework integration across polymer, chemical intermediate, and adhesive application segments. CAGRs derive from regression analysis against electric vehicle production trajectories and metallocene catalyst adoption curves. Industry-specific inputs include naphtha cracker operating rate correlations and METI registration timeline assumptions.
Practitioners should monitor cyclopentadiene feedstock price volatility, METI enforcement schedule acceleration, and metallocene catalyst patent landscape shifts for early signals requiring forecast revision. Cross-checking against IHS Markit petrochemical price benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Allyl Heptanoate Market
Flavor and Fragrance Chemicals
Asia-Pacific Aroma Chemicals Market
Flavor and Fragrance Chemicals
Natural Aroma Chemicals Market
Flavor and Fragrance Chemicals
Fragrance Concentrates Market
Flavor and Fragrance Chemicals
Anethole Market
Flavor and Fragrance Chemicals
Semiochemicals Market
Flavor and Fragrance Chemicals
Arborvitae Oil Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Estragole Market
Flavor and Fragrance Chemicals
Fragrance Wax Melts Market
Flavor and Fragrance Chemicals
Tangerine Oil Market
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market