
 Aroma Chemicals Market | 2026-2036
Aroma Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Aroma Chemicals Market Analysis
Pharma-grade purity specifications is unwinding cost structures across the aroma chemicals supply base. Givaudan leverages captive biotechnology platforms to secure rare natural-identical molecules. Symrise anchors European production through specialized extraction facilities in Germany and Spain. Takasago International Corporation differentiates via asymmetric catalysis leadership in menthol and related terpenoids.
Aroma chemicals constitute volatile and semi-volatile organic compounds—esters, aldehydes, ketones, and terpenoids—synthesized through fractional distillation, catalytic hydrogenation, or microbial fermentation to deliver olfactory functionality in consumer products. Synthetic molecules dominate volume throughput due to batch consistency and supply security, though natural isolates command premium positioning in certified clean-label fragrances. Within applications, fine fragrances capture the highest value per kilogram while household products and cleaning agents absorb the greatest absolute tonnage. Food and beverage flavorings represent a structurally distinct margin pool with tighter safety dossier requirements.
REACH registration in Europe, FDA food additive clearances in the United States, and IFRA standards globally constrain permissible substance lists and reformulation cycles. China's NMPA and GB standards impose additional testing protocols for imported aroma materials entering cosmetics and pharmaceutical channels. Stakeholders must monitor regulatory divergence between fragrance allergen labeling regimes and biotech-derived novel molecule approval pathways to anticipate compliance costs and first-molecule advantages.
Market Dynamics
Biotechnology-derived production routes are fragmenting the incumbent petrochemical supply base for aroma molecules, as fermentation platforms achieve cost parity with synthetic pathways while satisfying clean-label procurement mandates from European and North American fragrance houses.
Growth Catalysts
- REACH registration deadlines:ECHA's substance evaluation timeline is accelerating consolidation among compliant suppliers, advantaging firms with complete dossiers for high-volume aroma molecules.
- Clean-label certification demand:Personal care brands in France and Germany now specify bio-based content thresholds, pulling natural-identical molecules through dedicated supply contracts.
- Fermentation scale-up:Microbial production of vanillin and nootkatone is decomposing cost barriers that previously constrained volume deployment in mass-market applications.
Market Restraints
- Feedstock volatility:Crude turpentine and citrus oil prices swing with Brazilian and Florida harvest conditions, compressing margins for terpenoid producers.
- Supplier concentration:Three integrated houses control asymmetric catalysis capacity for menthol, creating single-source risk for downstream formulators.
- Allergen labeling expansion:EU fragrance allergen disclosure requirements now cover 80+ substances, forcing reformulation cycles that freeze SKU portfolios.
Strategic Opportunities
- China domestic brand growth:Shanghai and Guangzhou-based perfumery houses are building in-house compounding labs, creating demand for technical-grade aroma chemical partnerships.
- Biotech-fragrance convergence:CRISPR-engineered yeast strains producing rare sesquiterpenes are opening previously inaccessible odor profiles for niche fragrance development.
- Direct-to-formulator platforms:Digital sample ordering and technical documentation portals are bypassing traditional distributor layers in specialty aroma chemical procurement.
Industry Challenges
- Bioprocess scale-up expertise:Fermentation engineers with GMP aroma chemical experience command premium compensation, constraining capacity expansion timelines.
- Cross-border dossier harmonization:Divergent safety data requirements between REACH, FDA food additive clearances, and China's NMPA cosmetics filings multiply registration costs for novel molecules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aroma Chemicals Market |
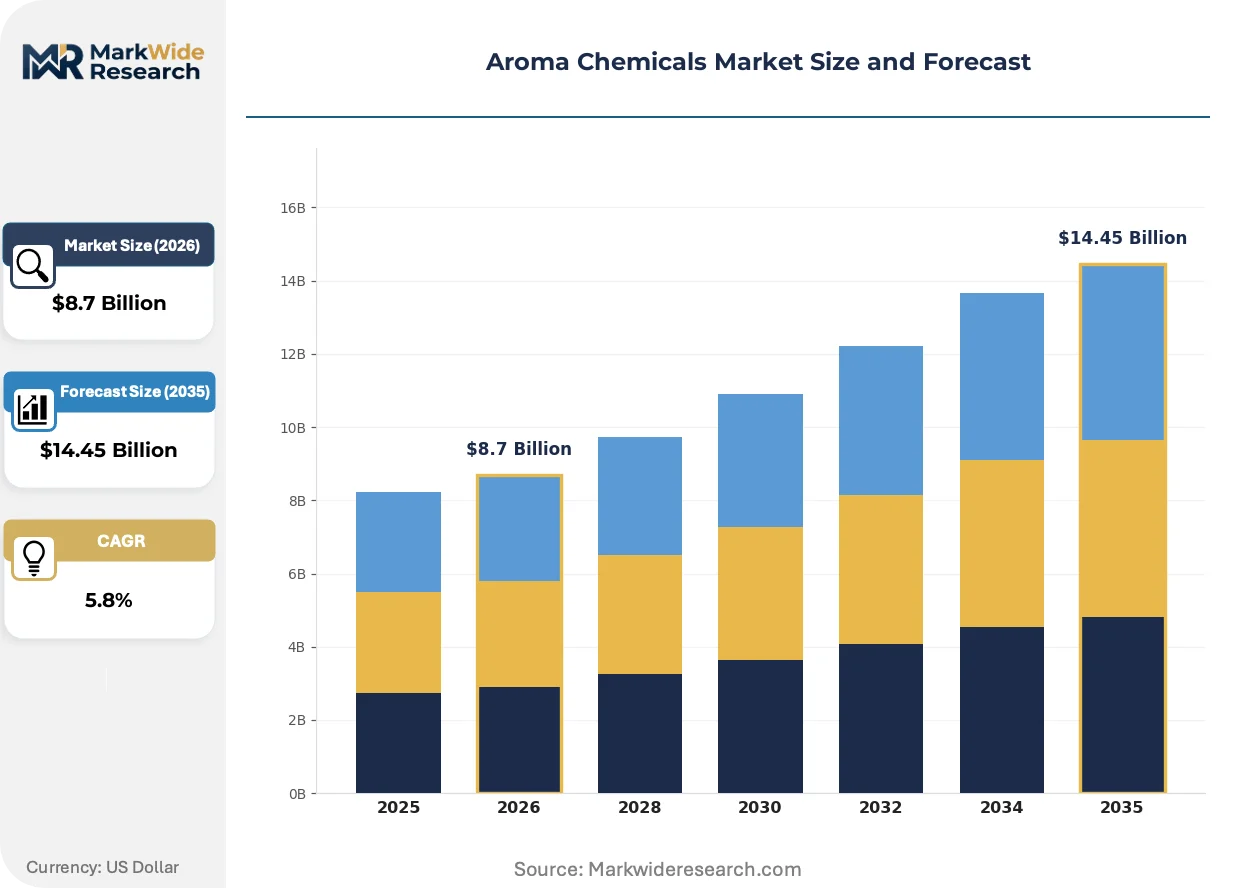
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Blends, Isolates Application: Fragrances, Personal Care, Household Products, Food & Beverages End User: Cosmetics, Flavorings, Cleaning Agents, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | International Flavors & Fragrances Inc., Takasago International Corporation, BASF SE, Kao Corporation, Robertet SA, Givaudan, Firmenich SA, Privi Speciality Chemicals, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aroma Chemicals Market Emerging Trajectories
Continuous processing technologies and AI-guided molecular discovery are compressing development cycles for aroma chemicals, while regulatory pressure on synthetic precursors accelerates capital redeployment toward bio-based platforms.
Precision fermentation using engineered microbes is decomposing the traditional extraction-dependent supply model for high-value molecules. Fine fragrance houses in France now specify fermentation-derived sandalwood substitutes in 40% of new launches. This biotechnology shift is collapsing the price premium that natural isolates previously commanded while expanding volume availability.
REACH authorization requirements for persistent organic pollutants are eliminating certain synthetic musks from European formulations. Fragrance houses must reformulate legacy fine fragrance SKUs by substitution deadlines, diverting R&D spending toward compliant alternatives. The household products segment faces parallel pressure as ECHA evaluates additional substances for restriction.
Formulation houses now demand block-chain traceability for palm oil derivatives and petrochemical feedstocks used in aroma chemical synthesis. Third-party sustainability auditors verify chain-of-custody documentation before contract execution. This verification requirement is most pronounced in German and Dutch procurement specifications for personal care applications.
Aroma Chemicals Market Segmentation
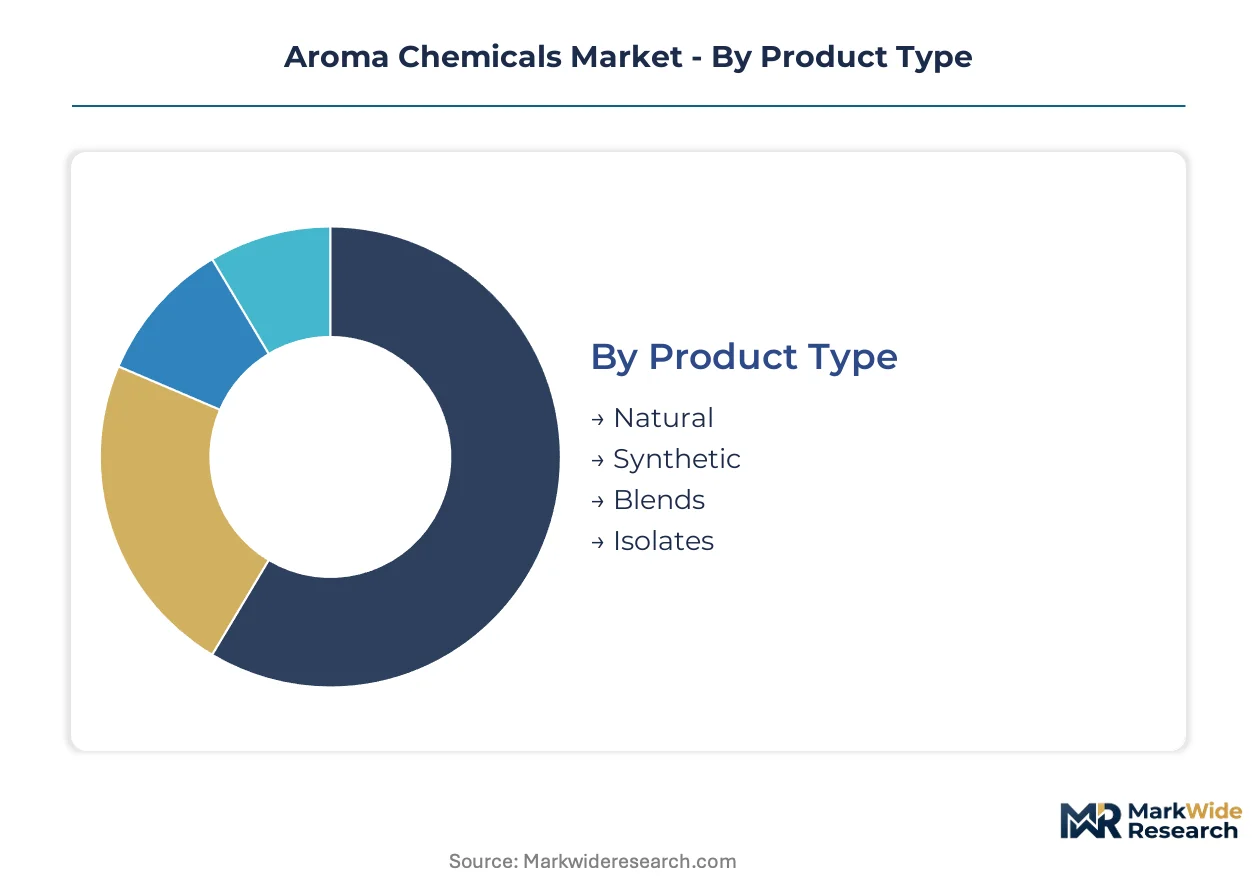
Aroma chemicals flow through distinct procurement channels depending on purity grades and application criticality. Segmentation reveals how fine fragrance houses, mass-market formulators, and pharmaceutical manufacturers access differentiated molecule portfolios through specialized supply routes.
Product Type:
Channel mix varies sharply by production origin. Natural isolates and fermentation-derived molecules move through dedicated distributor networks with chain-of-custody documentation. Synthetic volumes flow direct to large formulators. Blends and isolates split between technical distributors and direct technical partnerships.
- Natural:Extracted from botanical sources including citrus oils, flower absolutes, and resinous materials. French fine fragrance houses in Grasse specify natural isolates for certified clean-label launches, though harvest volatility constrains volume commitments.
- Synthetic:Petrochemical-derived molecules manufactured through catalytic hydrogenation and fractional distillation. Household product manufacturers in Germany absorb the greatest absolute tonnage through direct supply contracts with integrated producers.
- Blends:Pre-formulated accords combining multiple aroma chemicals for specific olfactory profiles. Mid-tier personal care brands in the United States procure these through distributors to reduce in-house compounding complexity.
- Isolates:Single-molecule purity grades separated from natural sources or fermentation broths. Pharmaceutical channels in Switzerland demand GMP-certified isolates for excipient applications.
By volume, Synthetic leads. By growth pace, Natural is ahead.
Application:
Cost tier stratification separates premium fragrance compounding from commodity absorption applications. Fine fragrances command the highest value per kilogram. Household products and food formulations operate on tighter specification tolerances with volume-driven procurement.
- Fragrances:Fine and mass-market perfume formulations requiring high-purity molecules with batch consistency. Paris-based fragrance houses now specify bio-based content thresholds, pulling natural-identical molecules through dedicated supply contracts.
- Personal Care:Deodorants, shampoos, and skincare formulations with skin-safety dossier requirements. German and Dutch procurement specifications now mandate blockchain traceability for palm oil derivatives used in aroma chemical synthesis.
- Household Products:Cleaning agents, laundry care, and air fresheners absorbing the greatest absolute tonnage. REACH authorization requirements for persistent organic pollutants are eliminating certain synthetic musks from European formulations in this segment.
- Food & Beverages:Flavorings with tighter safety dossier requirements and FDA or EFSA clearance protocols. This structurally distinct margin pool demands pharma-grade purity specifications that unwind cost structures across the supply base.
Fragrances capture peak margins per kilogram. Food & Beverages face the steepest regulatory compliance burden.
End User:
Customer type determines technical service intensity and contract structure. Pharmaceutical and cosmetics channels demand GMP documentation and audit trails. Flavoring and cleaning applications prioritize volume scale and supply security.
- Cosmetics:Skin-contact applications requiring IFRA compliance and allergen disclosure documentation. EU fragrance allergen disclosure requirements now cover 80+ substances, forcing reformulation cycles that freeze SKU portfolios for cosmetics manufacturers.
- Flavorings:Food-grade molecules with FSSAI, FDA, or EFSA clearances and GRAS status verification. India's domestic flavor houses are scaling formulation capabilities, creating demand for technical-grade aroma chemical partnerships.
- Cleaning Agents:Industrial and consumer cleaning formulations with cost-optimized molecule selection. ECHA evaluations of additional substances for restriction are pressuring this segment toward compliant alternative sourcing.
- Pharmaceuticals:Excipient and active ingredient applications demanding GMP manufacturing and validated analytical methods. Swiss and German regulators impose the most stringent purity specifications for pharma-grade aroma materials.
Pharmaceuticals command the highest purity premiums. Flavorings are expanding most quickly in emerging markets.
Distribution Channel:
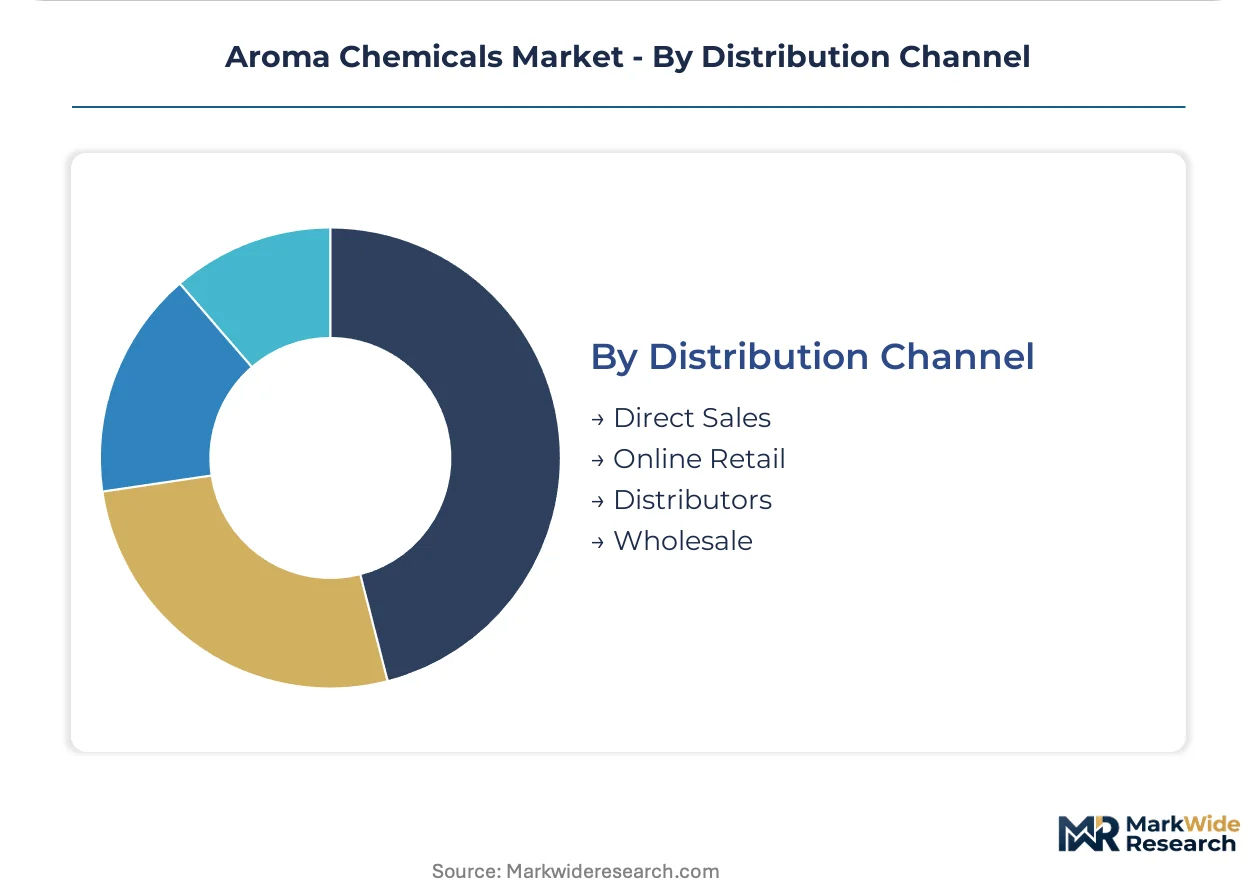
Supply concentration shapes access patterns. Large integrated houses serve direct accounts. Specialty distributors handle smaller volume, higher technical service requirements. Digital platforms are fragmenting traditional wholesale structures.
- Direct Sales:Long-term supply contracts between integrated aroma chemical producers and large formulation houses. Givaudan, Symrise, and Firmenich leverage captive biotechnology platforms to secure rare natural-identical molecules through direct technical partnerships.
- Online Retail:Digital sample ordering and technical documentation portals targeting independent perfumers and small-scale formulators. These platforms are bypassing traditional distributor layers in specialty aroma chemical procurement.
- Distributors:Technical specialists providing formulation support, regulatory documentation, and smaller volume fulfillment. Regional distributors in Asia-Pacific bridge Chinese domestic brand growth with international specialty molecule suppliers.
- Wholesale:Volume-based procurement for commodity-grade synthetic molecules in standard specifications. Brazilian and Florida harvest conditions drive crude turpentine and citrus oil price swings that compress margins for wholesale terpenoid distribution.
Direct Sales dominates value concentration. Online Retail is gaining share fastest among independent formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated aroma chemical production clusters in Switzerland, Germany, and France supply formulation houses across Western Europe, while Chinese domestic brands scale compounding capabilities in Shanghai and Guangzhou. Biotechnology fermentation platforms in the United States and Japanese precision catalysis operations complete the supply-side map.
United States
Fine fragrance houses in New York and Los Angeles expand procurement of sustainable aroma molecules through dedicated supply contracts. FDA food additive clearances constrain permissible substance lists for flavoring applications. New Jersey-based fermentation facilities achieve cost parity with synthetic pathways for vanillin production.
Germany
Household product manufacturers absorb the greatest absolute tonnage through direct supply contracts with integrated producers. ECHA's REACH authorization requirements eliminate certain synthetic musks from European formulations by substitution deadlines. Specialized extraction facilities in North Rhine-Westphalia anchor Symrise's European production network.
China
Domestic perfumery and personal care brands in Shanghai and Guangzhou scale formulation capabilities, creating demand for technical-grade aroma chemical partnerships. NMPA and GB standards impose additional testing protocols for imported aroma materials entering cosmetics channels. Yangtze River Delta biotechnology parks deploy CRISPR-engineered yeast strains for rare sesquiterpene production.
France
Grasse-based fine fragrance houses specify natural isolates for certified clean-label launches, with fermentation-derived sandalwood substitutes appearing in 40% of new launches. EU fragrance allergen disclosure requirements now cover 80+ substances, forcing reformulation cycles. Parisian procurement teams mandate blockchain traceability for palm oil derivatives before contract execution.
Switzerland
Pharmaceutical channels demand GMP-certified isolates for excipient applications with the most stringent purity specifications globally. Swissmedic imposes validated analytical methods for pharma-grade aroma materials. Basel-area manufacturing clusters supply Givaudan's captive biotechnology platforms for rare natural-identical molecules.
Aroma Chemicals Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with biotechnology platforms commanding premium positioning while petrochemical-scale operations absorb volume. The market structure consolidates around integrated houses with complete REACH dossiers, mid-tier distributors with technical service capabilities, and emerging fermentation specialists. Swiss and German integrated producers anchor the premium tier, while Asian chemical conglomerates dominate commodity synthetics. Competitive moves concentrate on asymmetric catalysis capacity expansion and strategic biotechnology licensing partnerships.
Among the integrated houses named in raw data, Givaudan, Symrise, and Firmenich SA occupy positions exemplifying the biotechnology-anchored archetype with captive fermentation platforms. Takasago International Corporation represents asymmetric catalysis specialization in terpenoid production. BASF SE and Kao Corporation sit within the diversified chemical conglomerate tier with scale-driven synthetic operations. International Flavors & Fragrances Inc. and Robertet SA span both natural extraction and synthetic capabilities. Privi Speciality Chemicals anchors the India-based specialty distributor position serving domestic brand growth.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Takasago International Corporation |
| BASF SE |
| Kao Corporation |
| Robertet SA |
| Givaudan |
| Firmenich SA |
| Privi Speciality Chemicals |
| Symrise |
| Others |
Supply Flow & Price Mechanics
Batch consistency at petrochemical scale anchors cost floors for synthetic aroma molecules, concentrating pricing power among integrated houses with captive hydrogenation capacity while fermentation-derived alternatives reset premium benchmarks for natural-identical grades. REACH dossier completeness and FDA food additive clearances stratify supplier tiers, with compliant producers commanding contract premiums from fragrance houses facing reformulation deadlines.
Pricing Analysis
REACH registration dictates the pricing tier structure across European procurement channels, separating GMP-certified isolates for pharmaceutical applications from technical-grade synthetics absorbed by household product manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with fine fragrance houses in France and Germany least price-sensitive due to clean-label procurement mandates. Cost compression in commodity terpenoids intensifies because Brazilian and Florida harvest volatility swings crude turpentine and citrus oil feedstock costs. Mass-market cleaning agents in Germany absorb the greatest absolute tonnage at tightest margins, while Swiss pharmaceutical channels pay purity premiums validated by Swissmedic analytical protocols.
Supply Chain Analysis
Strait of Hormuz transit underwrites petrochemical feedstock flows for synthetic aroma production, though biotechnology fermentation platforms in the United States and Chinese Yangtze River Delta parks are displacing extraction-dependent models. Supply concentrates in Switzerland, Germany, and France for integrated fine fragrance molecules, while China and India dominate commodity-grade synthetics and domestic brand technical partnerships. Raw material dependencies center on crude turpentine, citrus oils, and palm oil derivatives with blockchain traceability now mandated by Dutch and German procurement specifications. Single-source vulnerability concentrates in asymmetric catalysis capacity for menthol controlled by three integrated houses. Distribution runs through direct technical partnerships for premium grades, specialty distributors for mid-tier blends, and digital platforms fragmenting wholesale structures for independent formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation engineering talent with GMP aroma chemical experience commands premium compensation, constraining capacity expansion timelines and creating acquisition targets for firms with scalable bioprocess platforms. Cross-border dossier harmonization expertise represents a scarce asset as REACH, FDA, and NMPA filing requirements diverge.
For Market Incumbents: Fortify asymmetric catalysis capacity for menthol and related terpenoids against biotechnology substitution threats by securing captive fermentation platforms through strategic licensing partnerships. Add extraction capacity in Spain and Germany to anchor European production networks against supply disruption. Invest in blockchain traceability infrastructure to satisfy Parisian procurement mandates for palm oil derivative chain-of-custody documentation before contract execution. For New Entrants and Emerging Players: Anchor in Shanghai and Guangzhou-based perfumery houses building in-house compounding labs, where technical-grade aroma chemical partnerships remain underpenetrated by incumbent distributor networks. Target India's domestic flavor houses scaling formulation capabilities under FSSAI clearance protocols as the most penetrable geography. Deploy direct-to-formulator digital platforms with technical documentation portals to bypass traditional wholesale layers in specialty molecule procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-anchored specialists with CRISPR-engineered yeast strains over petrochemical-scale commodity synthetics facing REACH authorization elimination pressure. Long-term viability across the projection horizon rests on fermentation scale-up expertise and complete regulatory dossiers rather than extraction-dependent natural isolate models. The signal to watch is ECHA substance evaluation timelines accelerating consolidation among compliant suppliers, advantaging firms with validated analytical methods for rare sesquiterpene production.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Platform Licensing | CRISPR-engineered yeast strains unlock rare sesquiterpene odor profiles previously inaccessible to fine fragrance houses. |
| Backward Integration into Fermentation | Captive bioprocess capacity secures natural-identical molecule supply against petrochemical feedstock volatility. |
| REACH Dossier Completion | Full substance registration prevents market exclusion as ECHA authorization deadlines eliminate non-compliant competitors. |
| Blockchain Traceability Implementation | Third-party verified chain-of-custody documentation satisfies German and Dutch procurement specifications for personal care applications. |
| Direct-to-Formulator Digital Platform | Technical sample ordering portals bypass distributor layers to capture independent perfumer and small-scale formulator demand. |
Methodological Framework
Desk research of customs and trade data, SEC and European chemical industry association filings, and regulatory submission databases preceded structured interviews with plant managers at integrated aroma chemical producers, procurement leads at downstream fragrance and household product OEMs, distribution channel partners in Asia-Pacific technical specialties, and technical R&D directors overseeing fermentation scale-up operations. Primary fieldwork combined with secondary validation through FDA food additive clearance records, ECHA REACH registration databases, and Swissmedic GMP certification listings. Bottom-up volume modeling across product grades and applications triangulated against top-down market sizing from production capacity disclosures and import-export flows.
Variance decomposition separates volume growth drivers from price-mix effects across the projection horizon, with segmentation dimensions spanning natural-synthetic-fermentation production origin, fine fragrance versus household product versus pharmaceutical application criticality, and direct-distributor-digital channel mix. CAGRs derive from capacity expansion announcements, regulatory substitution timelines, and biotechnology cost-parity achievement curves. Industry-specific forecast inputs include Brazilian and Florida citrus harvest projections, CRISPR strain development pipelines, and ECHA substance evaluation schedules.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label procurement mandates and stable REACH enforcement intensity; material deviation in biotechnology scale-up timelines or regulatory divergence acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as fermentation platform cost-parity achievement and ECHA persistent organic pollutant restriction expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Ethyl Vanillin Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Carnosic Acid Market
Flavor and Fragrance Chemicals
Pocket Perfume Market
Flavor and Fragrance Chemicals
Camphor Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Hydroxycitronellal Market
Flavor and Fragrance Chemicals
Aromatic Compounds Market
Flavor and Fragrance Chemicals
Global Perfume Ingredients Chemicals Market
Flavor and Fragrance Chemicals
Global Cinnamaldehyde Market
Flavor and Fragrance Chemicals
Linalool Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Herbal Fragrance Ingredients Market