
 Bio-Based Flavors and Fragrances Market | 2026-2036
Bio-Based Flavors and Fragrances Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Flavors and Fragrances Market Outlook
Modular fragrance blending kits for artisan perfumers and small-batch cosmetics makers is hardening as a mainstream procurement pattern. Givaudan leverages captive botanical sourcing across Madagascar and Haiti to secure rare raw materials. Firmenich anchors European supply through its Geneva-based biotechnology campus, while Symrise competes via fermentation-derived molecules that bypass agricultural volatility.
Bio-based flavors and fragrances comprise volatile and semi-volatile organic compounds extracted or biotechnologically produced from renewable biomass, typically exhibiting purity thresholds above 95 percent for food-grade applications and meeting ISO 9235 definitions for natural aromatic raw materials. Their primary commercial purpose is to deliver scent or taste profiles in finished consumer goods while satisfying regulatory and consumer preference for petroleum-free ingredient lists. Essential oils retain the largest revenue pool within product type segmentation due to established extraction infrastructure, though biodegradable fragrances command expanding premium positioning as home care brands reformulate for aquatic toxicity compliance. Across application dimensions, personal care and cosmetics absorb the fastest volume growth as Korean and French beauty houses replace synthetic musks with fermented alternatives.
REACH registration requirements and the EU Green Deal's chemical sustainability targets now mandate hazard profiling for fragrance allergens above 0.01 percent concentration, directly elevating compliance costs for synthetic portfolios and redirecting R&D budgets toward bio-based pathways. FDA oversight of flavoring substances under 21 CFR 172, alongside EPA Safer Choice criteria for home care formulations, creates parallel compliance architecture in North America that favors disclosed botanical supply chains. Stakeholders must monitor fermentation yield breakthroughs against extraction scalability to calibrate capital allocation between biotech and agronomic supply models.
Market Dynamics
REACH registration thresholds and EU Green Deal hazard profiling mandates are redirecting capital from synthetic portfolios toward fermentation-derived and botanical extraction pathways, compressing approval timelines for petroleum-free alternatives.
Growth Catalysts
- EU Green Deal chemical sustainability targets:REACH compliance costs for synthetic allergens above 0.01 percent concentration are accelerating reformulation budgets toward bio-based pathways.
- Fermentation yield breakthroughs:Biotechnology advances in precision fermentation are reducing agricultural volatility exposure for aroma molecule suppliers.
- Grasse extraction cluster concentration:French fragrance houses anchor European natural supply infrastructure, drawing downstream brand investment.
Market Restraints
- Vanillin feedstock volatility:Fermentation-derived alternatives face price pressure from petrochemical vanilla substitutes in mass-market applications.
- Madagascar botanical concentration:Captive sourcing of ylang-ylang and clove leaf oil creates single-origin exposure for rare raw material portfolios.
- ISO 9235 certification friction:Natural aromatic raw material definitions impose extraction method restrictions that limit process innovation.
Strategic Opportunities
- Home care aquatic toxicity compliance:Biodegradable fragrance positioning commands premium shelf space as EPA Safer Choice criteria tighten.
- Korean beauty house demand rotation:Fermented musk alternatives displace synthetic variants in personal care formulations at accelerated pace.
- Modular blending kit channel emergence:Artisan perfumers and small-batch cosmetics makers are bypassing traditional compounder relationships.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in Geneva and Basel corridor, constraining facility expansion.
- Dual supply model integration complexity:Capital allocation calibration between agronomic extraction and biotech fermentation requires concurrent capability building.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Flavors and Fragrances Market |
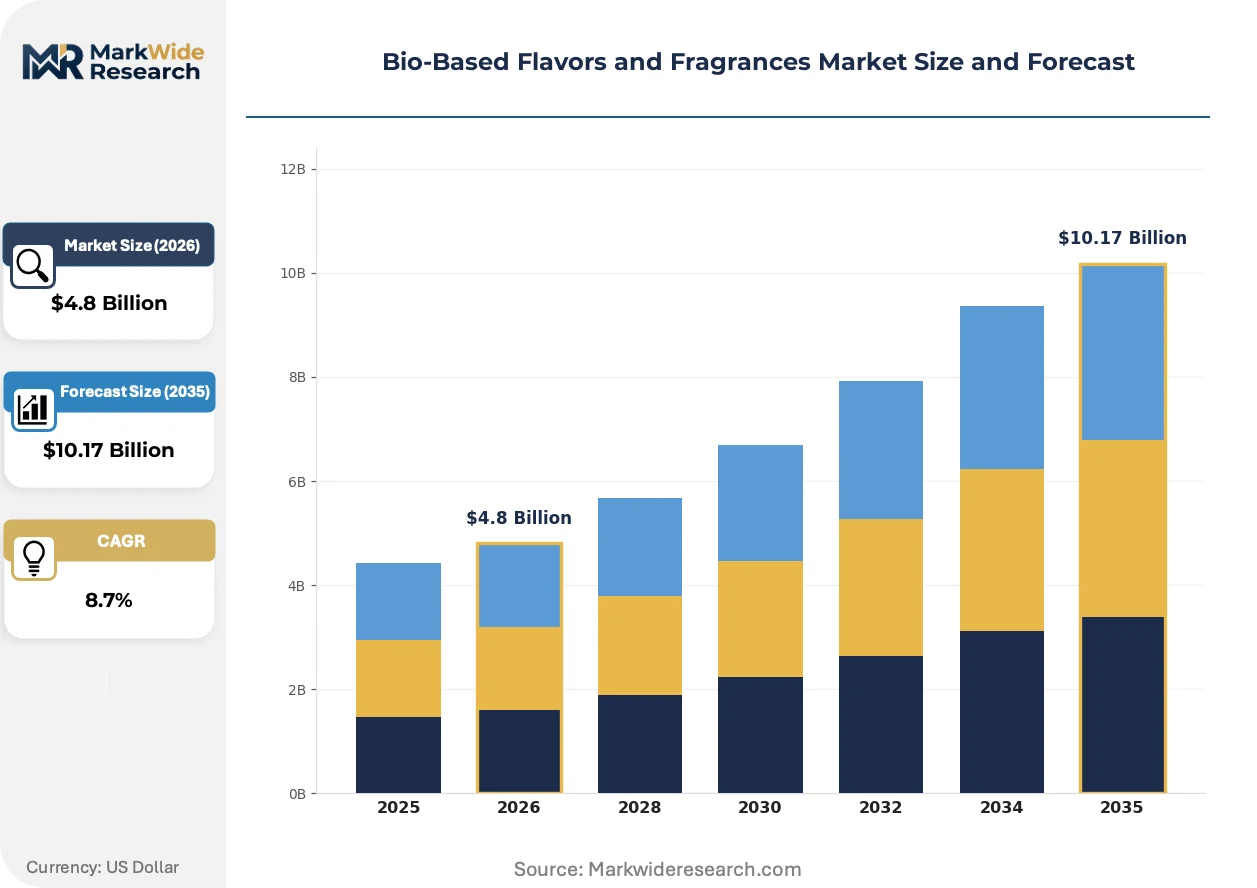
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Natural Flavorings, Aromatic Compounds, Biodegradable Fragrances Application: Food & Beverages, Personal Care, Home Care, Cosmetics Form: Liquid, Powder, Concentrate, Paste Source: Plant Extracts, Fruits, Spices, Flowers |
| Companies Covered | Firmenich, ADM, Givaudan, Takasago International Corporation, DSM, Symrise, Sensient Technologies Corporation, Robertet Group, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Flavors and Fragrances Market Strategic Shifts
Fermentation technology and modular production systems are fragmenting traditional compounder dominance while regulatory chemistry is redefining acceptable molecular pathways.
Precision fermentation for aroma molecules is decentralizing production geography away from agricultural growing regions. Korean and French cosmetics manufacturers are adopting biotech-derived musks at triple the pace of conventional extraction alternatives. This technology is decentralizing supply risk concentration that previously tied fragrance houses to Madagascar and Haitian harvest cycles.
REACH fragrance allergen thresholds now mandate hazard profiling above 0.01 percent concentration across EU member states. Synthetic portfolios face elevated compliance documentation burdens that extend registration timelines by eighteen to twenty-four months. Personal care brands with EU distribution exposure are accelerating bio-based reformulation programs to preempt labeling restrictions.
Direct-to-formulator ingredient platforms are compressing traditional distributor layers. Small-batch cosmetics makers and independent perfumers now source botanical isolates through digital marketplaces that bypass Givaudan and Firmenich compounder networks. France and South Korea exhibit the fastest channel fragmentation as artisan brand density concentrates in these markets.
Bio-Based Flavors and Fragrances Market Segmentation
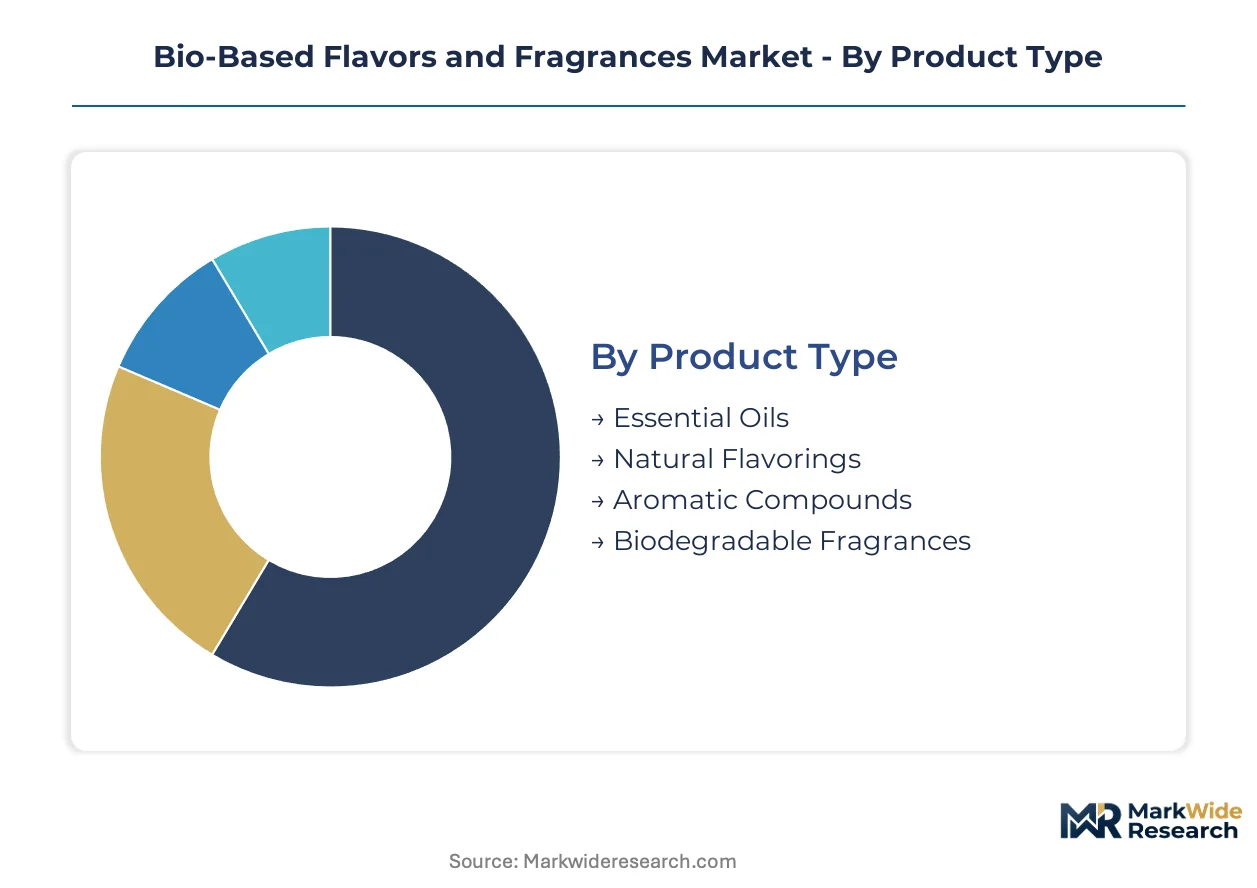
Segmentation in bio-based flavors and fragrances reflects divergent technical requirements across end-use industries. Food-grade applications demand ISO 9235 purity thresholds above 95 percent, while personal care brands prioritize aquatic toxicity compliance and allergen disclosure.
Product Type:
Buyers differentiate by extraction infrastructure maturity versus biotechnology scalability.
- Essential Oils:Steam-distilled or cold-pressed volatile compounds retaining complete botanical terpene profiles. Established extraction infrastructure in Grasse and Geneva anchors European supply, though Madagascar harvest volatility constrains ylang-ylang and clove leaf availability.
- Natural Flavorings:Compounds meeting FDA 21 CFR 172 and EFSA food-grade specifications for taste delivery. Korean fermentation facilities now supply precision-derived alternatives to agricultural extracts for beverage applications.
- Aromatic Compounds:Isolated molecules such as limonene and linalool standardized for consistent performance.
- Biodegradable Fragrances:Formulations engineered for rapid aquatic degradation per EPA Safer Choice criteria.
Volume sits with Essential Oils; growth tilts toward Biodegradable Fragrances.
Application:
Regulatory chemistry and consumer disclosure expectations reshape procurement priorities by end-use.
- Personal Care:Fermented musk alternatives displace synthetic variants in Korean and French beauty formulations. REACH allergen thresholds above 0.01 percent concentration accelerate bio-based reformulation budgets for EU-distributed brands.
- Food & Beverages:Flavoring substances governed by FDA 21 CFR 172 and EFSA positive lists. Clean-label momentum drives botanical sourcing with disclosed supply chains from Madagascar and Haiti.
- Home Care:Biodegradable fragrance positioning commands premium shelf space as aquatic toxicity compliance tightens.
- Cosmetics:Small-batch artisan makers bypass traditional compounders through direct-to-formulator digital platforms.
Personal Care captures the steepest expansion trajectory; Food & Beverages retains the largest installed volume base.
Form:
Processing economics and stability requirements determine format selection across supply chains.
- Liquid:Standard carrier for essential oils and aromatic compounds in industrial compounding. Bulk liquid infrastructure dominates Grasse-based extraction facilities.
- Concentrate:High-potency formats reducing transport costs for international fragrance houses. Precision fermentation yields enable consistent concentrate specification.
- Powder:Encapsulated formats for bakery and confectionery heat stability.
- Paste:Viscous matrices for specific confectionery and savory applications.
Liquid forms anchor current production; concentrate formats gain share fastest on logistics efficiency.
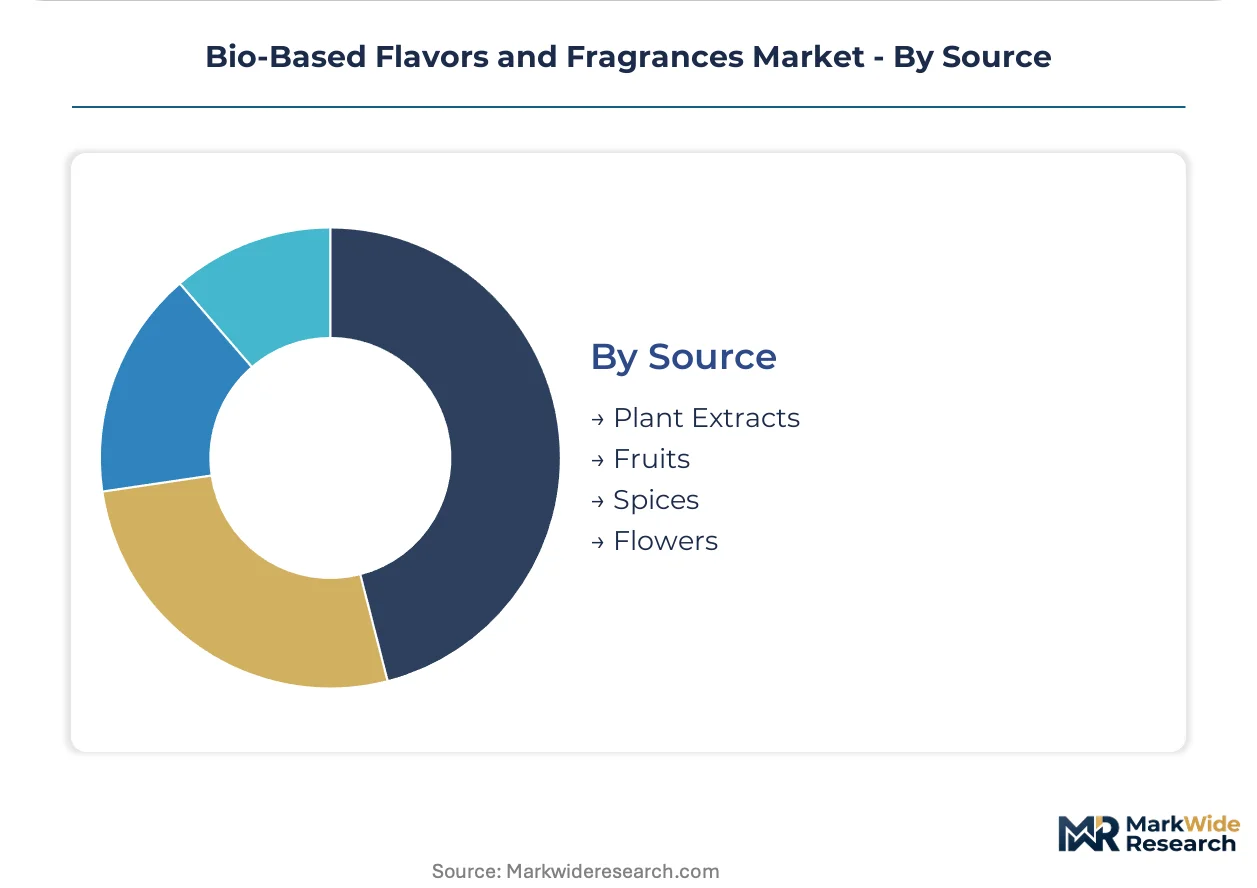
Source:
Geographic concentration of biomass supply creates divergent risk profiles for procurement teams.
- Plant Extracts:Leaf, bark, and resin derivatives processed through solvent or supercritical extraction. Madagascar and Haitian sourcing concentration creates single-origin exposure for rare raw material portfolios.
- Flowers:Rose, jasmine, and tuberose harvested in Grasse and Morocco for fine fragrance applications. Seasonal harvest cycles drive working capital intensity.
- Fruits:Citrus terpenes from Mediterranean and Florida growing regions.
- Spices:Clove, cinnamon, and nutmeg derivatives standardized for flavor consistency.
Plant Extracts dominate current throughput; Flowers command the highest premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in France and Madagascar supply raw materials to formulation centers in Switzerland and South Korea, while consumption concentrates in cosmetics-intensive markets across Western Europe and East Asia.
France
Grasse-based extraction facilities anchor European natural fragrance supply, with rose and jasmine harvests driving seasonal working capital cycles. REACH compliance costs for synthetic allergens above 0.01 percent concentration redirect reformulation budgets toward bio-based pathways. The Provence-Alpes-Côte d'Azur cluster draws downstream brand investment from Korean and French beauty houses seeking disclosed botanical supply chains.
Switzerland
Geneva-based biotechnology campuses concentrate precision fermentation expertise for aroma molecule production. ECHA registration requirements extend timelines for petroleum-based alternatives, favoring domestic biotech capacity. The Basel-Geneva corridor houses scarce bioprocess engineering talent that constrains facility expansion across European competitors.
South Korea
Korean beauty manufacturers adopt fermented musk alternatives at triple the pace of conventional extraction methods. MFDS cosmetic safety standards align with EU allergen disclosure expectations, accelerating bio-based procurement. Seoul Capital Area formulation labs source precision-derived isolates through direct-to-formulator digital platforms bypassing traditional compounder networks.
Madagascar
Ylang-ylang and clove leaf oil harvests create single-origin exposure for rare raw material portfolios serving European fragrance houses. Agricultural volatility from cyclone patterns disrupts extraction schedules and pricing consistency. Antananarivo-based collectors face working capital intensity from seasonal harvest compression and EU importer certification requirements.
United States
EPA Safer Choice criteria for home care formulations drive biodegradable fragrance positioning in mass-market applications. FDA oversight of flavoring substances under 21 CFR 172 creates parallel compliance architecture favoring disclosed botanical supply chains. California-based clean beauty brands source plant-derived aromatic compounds to preempt tightening state-level chemical disclosure mandates.
Bio-Based Flavors and Fragrances Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across extraction infrastructure and biotechnology platforms. The vendor base organizes around captive botanical sourcing, precision fermentation capabilities, and modular ingredient distribution channels. Three archetypes dominate: integrated fragrance houses with Madagascar and Haitian supply control, biotech platforms leveraging Geneva and Basel corridor expertise, and direct-to-formulator marketplaces fragmenting traditional compounder relationships. Capacity expansion in fermentation facilities and strategic partnerships for rare raw material access represent the dominant competitive moves.
Within the integrated fragrance house tier, Givaudan and Firmenich exemplify archetypes built on geographic supply concentration and biotechnology campus investment respectively. Symrise occupies a position representing fermentation-derived molecule specialists that bypass agricultural volatility. These three Swiss and French entities anchor competitive dynamics through their control over Grasse extraction infrastructure and Geneva-based precision fermentation scale.
| Leading Market Players |
|---|
| Firmenich |
| ADM |
| Givaudan |
| Takasago International Corporation |
| DSM |
| Symrise |
| Sensient Technologies Corporation |
| Robertet Group |
| International Flavors & Fragrances |
| Others |
Value Chain & Pricing Dynamics
Vanillin feedstock indices cascade through bio-based flavor and fragrance supply chains, compressing margins at the fermentation-derived tier while elevating premiums for Grasse-sourced botanical isolates. REACH compliance documentation costs for synthetic allergens above 0.01 percent concentration redirect procurement budgets toward disclosed agricultural supply chains, widening price spreads between certified natural and petroleum-derived alternatives.
Pricing Analysis
Margin tightening in mass-market vanillin reflects petrochemical substitute competition, while premium-mid-economy pricing differentiation separates ISO 9235-certified botanical extracts from fermentation-derived alternatives. Price differentiation hinges on extraction method disclosure and EU allergen compliance certification. Cost-down pressure on Madagascar-sourced ylang-ylang accelerates because cyclone-disrupted harvest cycles compress availability windows. Mass-market food and beverage manufacturers exhibit highest price sensitivity; fine fragrance houses in France and South Korea absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Regional distribution centers in Geneva, Basel, and Seoul fragment traditional hub-and-spoke patterns as direct-to-formulator platforms bypass compounder networks. Geographic supply concentration centers on Madagascar for ylang-ylang and clove leaf, Haiti for vetiver, and France for rose and jasmine absolutes. Raw material dependencies rest on agricultural harvest cycles, fermentation feedstock sugars, and supercritical CO2 extraction solvents. Single-origin vulnerability from Madagascar cyclone exposure threatens rare raw material portfolios. Distribution runs through Grasse-based extraction facilities to Swiss biotechnology campuses and Korean formulation labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology is displacing conventional extraction infrastructure, creating asymmetric capability gaps between biotechnology platforms and agronomic supply houses. This transition phase favors capital deployment toward yield optimization and modular production systems.
For Market Incumbents: To counter fermentation-derived molecule specialists, Givaudan and Firmenich should deepen captive botanical sourcing in Madagascar and Haiti while expanding Geneva-based precision fermentation capacity. Certification investment in ISO 9235-compliant extraction methods preserves premium positioning against biotech alternatives. For New Entrants and Emerging Players: Launch via direct-to-formulator digital marketplaces targeting South Korean and French artisan cosmetics makers bypassing traditional compounder relationships. Modular fragrance blending kits for small-batch perfumers represent the most penetrable white-space segment, with clean-label disclosure as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioprocess engineering platforms in the Basel-Geneva corridor with demonstrated fermentation scale-up capability. Long-term viability across the analysis window rests on dual supply model integration between agronomic extraction and biotechnology pathways. Watch for fermentation yield breakthroughs above commercial thresholds as the inflection signal triggering consolidation momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Botanical Sourcing Expansion | Madagascar and Haitian supply control secures rare raw material access for EU REACH compliance. |
| Precision Fermentation Scale-Up | Geneva-based biotechnology campuses reduce agricultural volatility exposure for aroma molecule production. |
| Direct-to-Formulator Platform Launch | Digital marketplaces bypass Givaudan and Firmenich distributor layers for artisan perfumers. |
| ISO 9235 Certification Investment | Natural aromatic raw material definitions command premium positioning in Korean beauty formulations. |
| Modular Blending Kit Distribution | Small-batch cosmetics makers in France and South Korea fragment traditional compounder relationships. |
Study Parameters
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with fragrance house procurement directors, bioprocess engineering leads at Swiss biotechnology campuses, Madagascar-based botanical collectors, and Korean cosmetics formulation managers. Bottom-up and top-down triangulation validated volume estimates across extraction infrastructure and fermentation facility outputs.
Bottom-up modeling aggregated capacity utilization at Grasse extraction facilities, Geneva fermentation campuses, and Antananarivo collection points against downstream demand from personal care and food and beverage formulators. Top-down analysis calibrated CAGRs against REACH compliance cost trajectories and EU Green Deal chemical sustainability targets. Segmentation dimensions spanned product type, application, form, and source, with regulatory framework clusters as an additional cross-cutting dimension. Yield breakthroughs in precision fermentation and Madagascar harvest volatility served as scenario inputs.
Fermentation yield stagnation, Madagascar cyclone intensity, and REACH threshold tightening are the dominant revision risks that could compress or extend bio-based adoption timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
3-Methyl Valeric Acid Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
4-Allylanisole Market
Flavor and Fragrance Chemicals
Citral Market
Flavor and Fragrance Chemicals
Perillaldehyde Market
Flavor and Fragrance Chemicals
Dihydrocitronellol Market
Flavor and Fragrance Chemicals
North America Aroma Chemicals Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Ferulic Acid Market
Flavor and Fragrance Chemicals
Europe Essential Oils Market
Flavor and Fragrance Chemicals
Encapsulated Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Deodorization Systems Market