
 Phenethyl Alcohol Market | 2026-2036
Phenethyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Phenethyl Alcohol Market Analytics
Biotechnology-derived fermentation pathways for aroma chemicals is rewriting production economics for phenethyl alcohol suppliers. BASF leverages its integrated aroma ingredients platform to sustain cost advantages across European and Asian supply corridors. Evonik Industries AG anchors its position through specialty chemical R&D intensity in industrial biotechnology applications. Kunshan Odowell competes on regional manufacturing scale, serving fragrance compound blenders with consistent synthetic-grade output.
Phenethyl alcohol is a primary aromatic alcohol with the molecular formula C8H10O, typically produced through Grignard reaction of benzene derivatives or via biotechnological fermentation of L-phenylalanine; it functions as a fragrance raw material, flavoring agent, and antimicrobial preservative across consumer goods. The natural product type segment commands premium positioning in clean-label cosmetics, though synthetic grades dominate volume throughput in mass-market personal care formulations. Fragrance applications absorb the largest share of output, while flavoring agent demand in food and beverages is expanding fastest as regulators approve broader usage thresholds.
REACH registration requirements in Europe and FDA fragrance allergen disclosure rules in the United States compel suppliers to document supply chain purity and origin credentials. China's SAMR national food safety standards and GB specifications for food-grade additives shape export eligibility for domestic manufacturers. Stakeholders must monitor divergence between natural-certification premiums and synthetic-grade cost efficiency as regulatory stringency escalates across multiple jurisdictions.
Market Dynamics
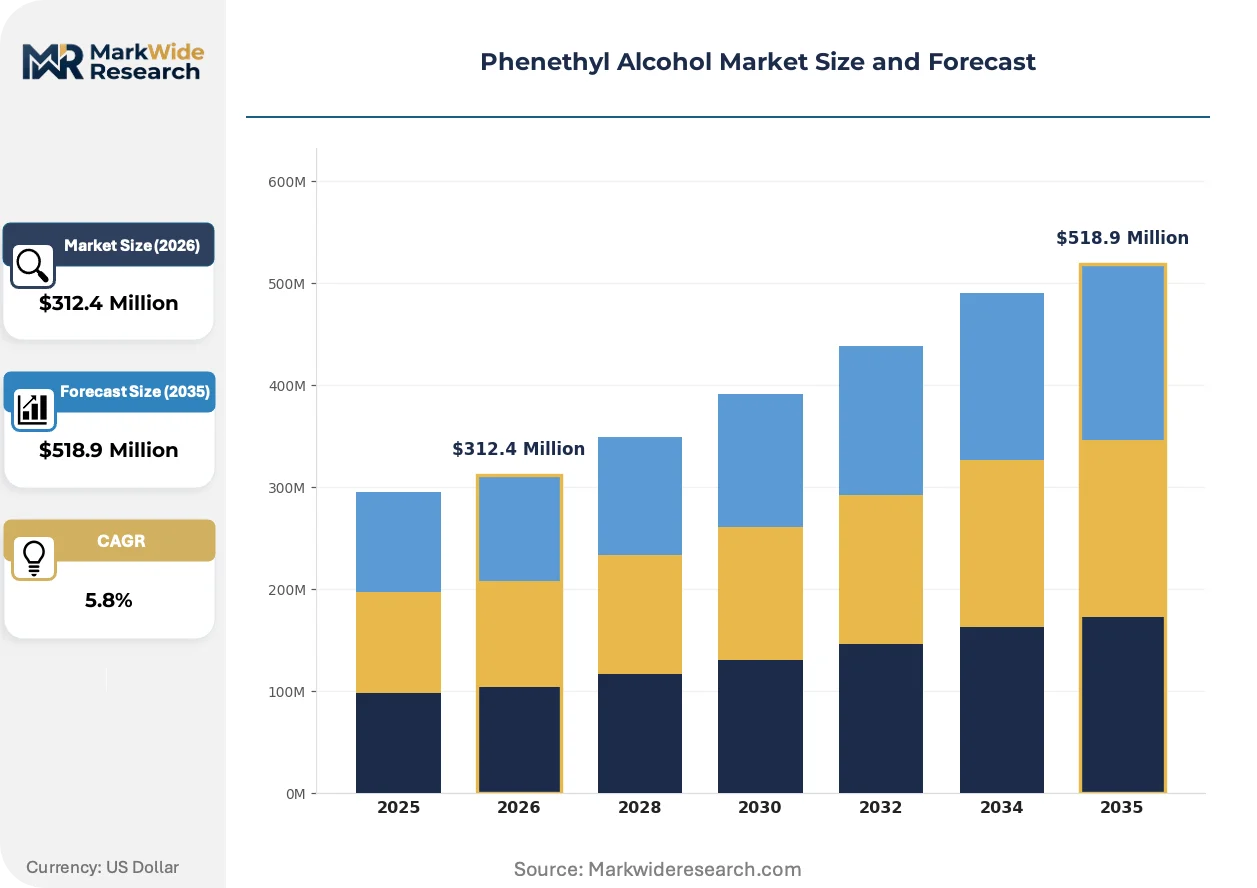
Biotechnology-derived fermentation pathways are compressing synthetic production margins while REACH and FDA allergen disclosure rules force dual-track compliance investments across supply chains.
Growth Catalysts
- Clean-label cosmetics procurement:Fragrance formulators in personal care are expanding natural-derived phenethyl alcohol sourcing as consumer preference for ingredient transparency intensifies in premium skincare segments.
- REACH purity thresholds:European chemical registration requirements are compelling suppliers to document supply chain credentials, creating competitive differentiation for compliant manufacturers.
- Food-grade flavor expansion:Broader regulatory approvals for phenethyl alcohol usage thresholds in beverages are unlocking new volume absorption in the flavoring agent segment.
Market Restraints
- L-phenylalanine feedstock volatility:Amino acid input costs fluctuate with agricultural commodity cycles, squeezing fermentation pathway economics against petroleum-derived benzene alternatives.
- China supply concentration:Yinghai (Cangzhou) Aroma Chemical Company and domestic aroma clusters control regional output, creating single-source vulnerability for international fragrance houses.
- Synthetic allergen substitution:Natural-identical phenethyl alcohol faces displacement risk from biosynthetic alternatives as clean-label standards tighten beyond current certification frameworks.
Strategic Opportunities
- India flavor and fragrance manufacturing:CDSCO regulatory harmonization and PLI scheme incentives for specialty chemicals are attracting contract manufacturing investment from European aroma houses.
- Antimicrobial preservation convergence:Phenethyl alcohol's dual function as fragrance raw material and antimicrobial agent is opening formulation integration opportunities in clean-label personal care products.
- SAMR export pathway alignment:Chinese manufacturers achieving GB food-grade additive specifications are capturing expanded eligibility in Asia-Pacific flavor distribution networks.
Industry Challenges
- Fermentation scale-up engineering:Industrial biotechnology talent scarcity in bioprocess engineering is constraining capacity expansion timelines for natural-derived production lines.
- Dual certification burden:Simultaneous REACH registration and FDA fragrance allergen documentation requirements are extending product launch timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenethyl Alcohol Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Aroma Chemicals, Fragrance Compounds End Use Industry: Cosmetics, Personal Care, Food & Beverages, Pharmaceuticals Application: Fragrances, Flavoring Agents, Solvent, Preservative Packaging Type: Bottles, Drums, Cans, Totes |
| Companies Covered | Actylis, BASF, Evonik Industries AG, Kunshan Odowell, Penta Manufacturing Company, Koninklijke DSM NV, Harmony Organics Private Ltd, Foreverest Resources Ltd, Yinghai (Cangzhou) Aroma Chemical Company Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenethyl Alcohol Market Evolving Landscape
Production technology substitution and regulatory documentation requirements are restructuring competitive advantage around bioprocess capability and supply chain traceability systems.
Microbial cell factory engineering for L-phenylalanine conversion is rendering obsolete traditional Grignard synthesis routes for premium-grade phenethyl alcohol. Specialty fragrance houses in France and Switzerland are adopting fermentation-derived supply for natural-certification compliance. Synthetic-grade producers face margin compression as biotechnology pathways achieve cost parity at commercial scale.
EU F-Gas Regulation amendments and REACH substance evaluation updates are tightening volatile organic compound thresholds for aroma chemical manufacturing. European formulators are reformulating product lines to preempt restriction list inclusions. Natural-derived phenethyl alcohol with documented fermentation origin is gaining preference in German and Nordic cosmetic markets.
Direct supplier relationships are replacing distributor intermediation in procurement patterns for large fragrance compound blenders. BASF and Evonik are establishing captive supply agreements with biotechnology partners to secure fermentation capacity. This channel consolidation is most advanced in European personal care manufacturing clusters where traceability requirements are most stringent.
Phenethyl Alcohol Market Segmentation
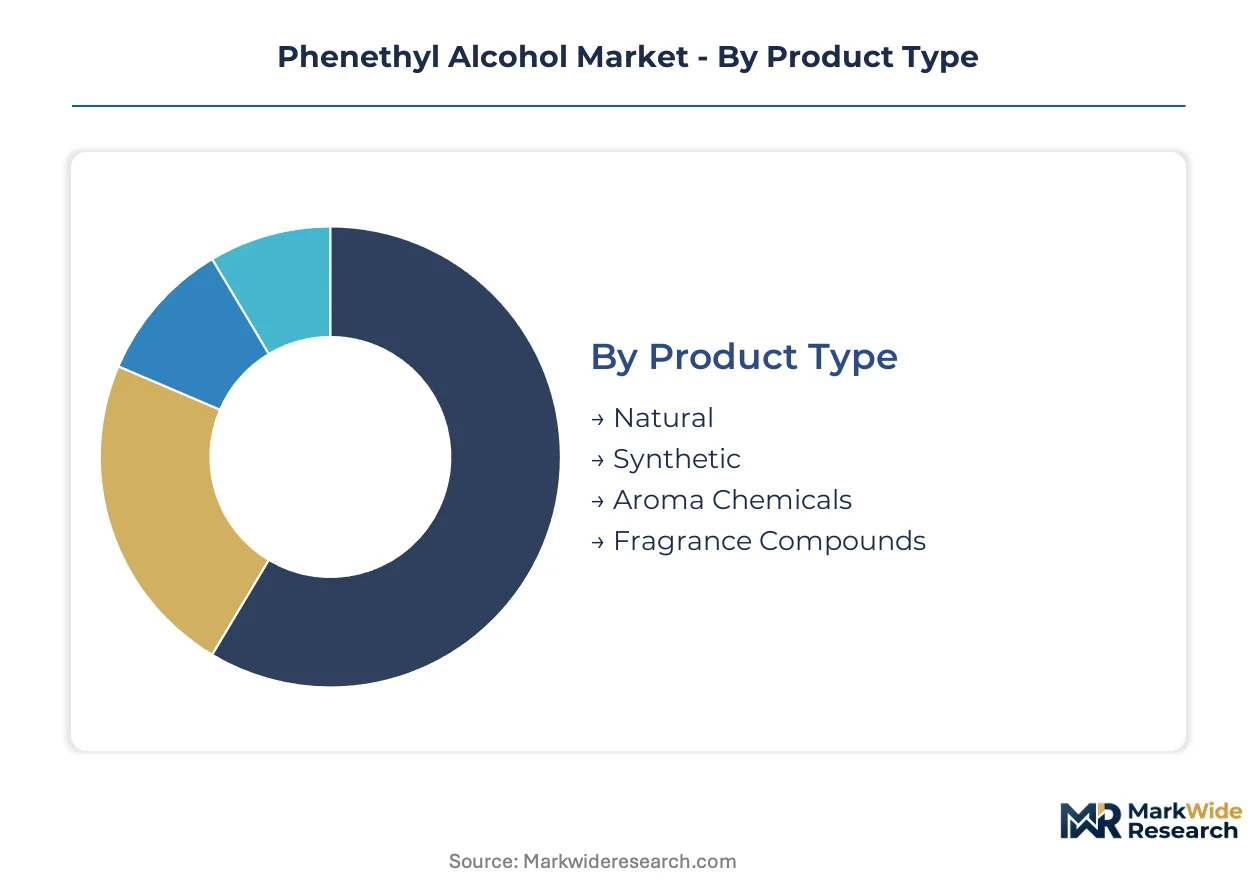
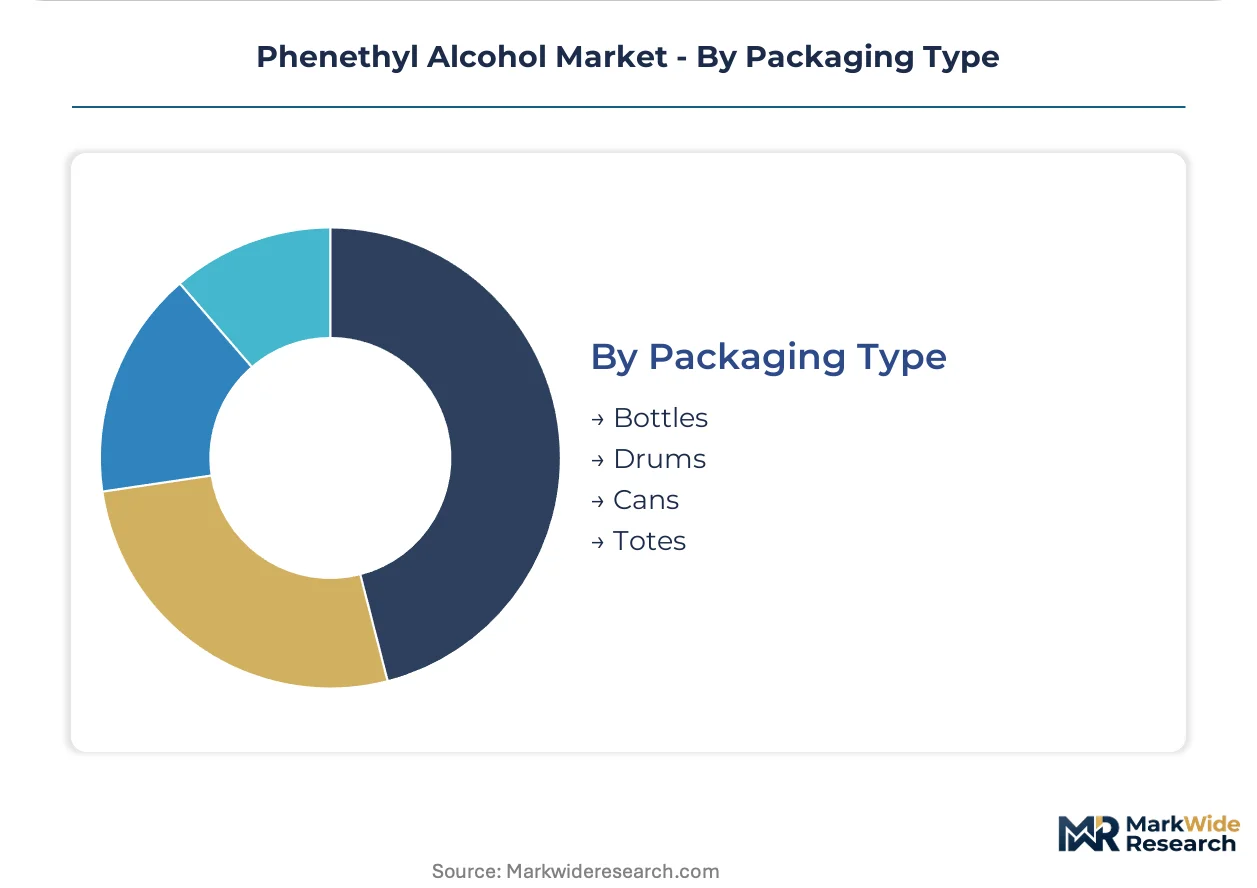
Phenethyl alcohol procurement patterns diverge sharply across certification grades and end-use specifications. Formulators select product types based on regulatory compliance requirements, while packaging configurations respond to volume scale and handling protocols in fragrance compounding facilities.
Product Type:
Mature synthetic production dominates volume economics, though emerging fermentation pathways are capturing premium positioning in certified-natural supply chains.
- Natural:Fermentation-derived from L-phenylalanine using engineered microbial cell factories. Fragrance houses in France and Switzerland source this grade for EU natural-certification compliance in premium skincare lines.
- Synthetic:Petroleum-based Grignard synthesis of benzene derivatives yields consistent purity specifications. Mass-market personal care manufacturers in China and India absorb the bulk of this output for cost-sensitive formulations.
- Aroma Chemicals:Intermediate-grade material for downstream fragrance compound blending.
- Fragrance Compounds:Pre-formulated blends incorporating phenethyl alcohol as a primary note.
Synthetic grades handle the majority of throughput; natural certification is the fastest mover on share.
End Use Industry:
Application intensity varies by regulatory exposure and consumer transparency expectations across consumer goods sectors.
- Cosmetics:High-purity requirements for facial skincare and color cosmetics drive specification premiums. German and Nordic markets demand documented fermentation origin for clean-label compliance.
- Personal Care:Volume absorption concentrates in mass-market shampoo and body wash formulations. Chinese contract manufacturers supply regional brands with synthetic-grade material at scale.
- Food & Beverages:Flavoring agent applications expand as SAMR and FDA approve broader usage thresholds in beverages.
- Pharmaceuticals:Antimicrobial preservation functions in topical formulations require pharmacopeia-grade documentation.
Personal Care captures the largest volume allocation; Food & Beverages posts the steepest expansion trajectory.
Application:
Functional versatility creates cross-segment demand with divergent purity and documentation requirements.
- Fragrances:Primary aromatic alcohol function in fine fragrance and functional perfumery. European formulators reformulate lines to preempt REACH restriction list inclusions.
- Flavoring Agents:Rose-honey odor profile suits beverage and confectionery applications. Regulatory harmonization across FDA, EFSA, and SAMR unlocks multi-jurisdictional formulation deployment.
- Solvent:Carrier function in fragrance oil dilution and extraction processes.
- Preservative:Dual-use antimicrobial properties gain traction in clean-label personal care as paraben alternatives face displacement.
Fragrances command the dominant share; preservative applications are climbing the fastest as clean-label standards tighten.
Packaging Type:
Handling configurations align with customer scale and inventory turnover patterns in aroma chemical distribution.
- Bottles:Laboratory and pilot-scale sampling for fragrance compound development.
- Drums:Standard unit for mid-volume fragrance house procurement.
- Cans:Aerosol-compatible packaging for specific solvent applications.
- Totes:Bulk liquid handling for large-scale personal care manufacturing lines.
Drums represent the most widely utilized format; totes are gaining share fastest with contract manufacturing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports fermentation-derived phenethyl alcohol to European fragrance houses seeking REACH-compliant natural certification. German and Swiss formulators source directly from Asian biotechnology partners to secure documented supply chain credentials.
China
Domestic aroma chemical clusters in Hebei Province supply synthetic-grade material to regional personal care manufacturers. SAMR national food safety standards and GB specifications for food-grade additives shape export eligibility for producers targeting Asia-Pacific flavor networks. Yinghai (Cangzhou) Aroma Chemical Company anchors production concentration in Cangzhou, serving contract manufacturers at volume scale.
Germany
Fine fragrance houses in Hamburg and Düsseldorf procurement zones drive specification premiums for fermentation-origin phenethyl alcohol. ECHA REACH registration requirements and EU F-Gas Regulation amendments tighten volatile organic compound thresholds for aroma chemical manufacturing. BASF leverages integrated aroma ingredients platforms across Ludwigshafen production corridors to sustain cost advantages in European supply chains.
United States
Mass-market personal care brands in New Jersey and California manufacturing clusters absorb synthetic-grade volumes for cost-sensitive shampoo and body wash formulations. FDA fragrance allergen disclosure rules compel suppliers to document supply chain purity and origin credentials. Penta Manufacturing Company exemplifies domestic blending capacity serving regional fragrance compounders.
India
Flavor and fragrance manufacturing investments accelerate in Maharashtra and Gujarat specialty chemical zones. CDSCO regulatory harmonization and PLI scheme incentives attract contract manufacturing commitments from European aroma houses. Harmony Organics Private Ltd occupies a position within domestic fermentation-derived supply development.
Switzerland
Premium skincare formulators in Geneva and Basel clusters procure natural-certified phenethyl alcohol for clean-label compliance. Swissmedic pharmaceutical-grade documentation requirements support antimicrobial preservation applications in topical formulations. Koninklijke DSM NV biotechnology platforms anchor industrial fermentation capability serving regional demand.
Phenethyl Alcohol Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply configurations. Integrated chemical conglomerates with captive biotechnology platforms face independent aroma chemical manufacturers with regional manufacturing scale. Three archetypes dominate: fermentation-technology leaders, petroleum-derived synthesis specialists, and regional contract manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure L-phenylalanine feedstock arrangements and bioprocess engineering talent.
Within the integrated-conglomerate tier, BASF and Evonik Industries AG exemplify European-based players with biotechnology R&D intensity. Kunshan Odowell occupies a position among China-based regional manufacturers competing on synthetic-grade output consistency. Actylis represents the specialty-distributor archetype bridging formulation-grade supply with fragrance house procurement networks.
| Leading Market Players |
|---|
| Actylis |
| BASF |
| Evonik Industries AG |
| Kunshan Odowell |
| Penta Manufacturing Company |
| Koninklijke DSM NV |
| Harmony Organics Private Ltd |
| Foreverest Resources Ltd |
| Yinghai (Cangzhou) Aroma Chemical Company Ltd |
| Others |
Value Network & Pricing Analysis
L-phenylalanine feedstock volatility compresses fermentation pathway margins while expanding the spread between natural-certified and synthetic-grade phenethyl alcohol. This input cost instability forces buyers toward petroleum-derived alternatives or long-term supply contracts that reshape procurement patterns across fragrance house tiers.
Pricing Analysis
The biotechnology-synthesis pricing gap separates fermentation-derived natural grades from Grignard-processed synthetic output, with three-tier pricing structure across premium, standard, and economy levels stratifying by certification grade and volume scale. Price differentiation hinges on REACH documentation completeness and FDA fragrance allergen disclosure compliance, with European formulators absorbing premium positioning for traceable supply chains. Cost compression in synthetic grades intensifies as Chinese manufacturers achieve production scale, while natural certification premiums hold firm in German and Swiss cosmetic markets. Mass-market personal care manufacturers in China and India exhibit highest price sensitivity, whereas premium skincare formulators in Geneva and Basel clusters prioritize origin credentials over unit economics.
Supply Chain Analysis
Yinghai (Cangzhou) Aroma Chemical Company and domestic aroma clusters in Hebei Province anchor contract-manufacturing concentration for synthetic-grade phenethyl alcohol, with China, Germany, and Switzerland forming the geographic supply backbone for distinct certification tiers. Raw material dependencies center on L-phenylalanine amino acid inputs, petroleum-derived benzene derivatives, and engineered microbial cell factory capacity. Single-source vulnerability concentrates risk in Cangzhou production corridors, where international fragrance houses lack qualified alternative suppliers at comparable scale. Distribution runs through direct supplier relationships replacing distributor intermediation, with BASF and Evonik establishing captive fermentation capacity agreements to secure biotechnology-derived output for European personal care manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The phenethyl alcohol market functions as a service-attach opportunity where compliance documentation and certification auditing expand faster than base chemical throughput, with fragrance houses paying recurring premiums for supply chain traceability systems.
For Market Incumbents: Harden defensibility by securing captive L-phenylalanine feedstock arrangements through backward integration into amino acid suppliers, and accelerate bioprocess engineering talent acquisition to compress fermentation scale-up timelines against synthetic-grade displacement. BASF and Evonik must preempt emerging biotechnology specialists by locking multi-year capacity agreements with microbial cell factory developers before cost parity erodes petroleum-derived margins. For New Entrants and Emerging Players: Build out fermentation-derived production capacity targeting India's Maharashtra and Gujarat specialty chemical zones, where CDSCO regulatory harmonization and PLI scheme incentives create penetrable white-space for contract manufacturing investment. Target European fragrance houses seeking REACH-compliant natural certification by offering documented supply chain credentials that incumbent petroleum-based producers cannot replicate, leveraging direct supplier relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: REACH substance evaluation updates and FDA fragrance allergen disclosure rule expansions reshape the acquisition landscape toward biotechnology-anchored targets with demonstrated fermentation scale and regulatory documentation infrastructure. Long-term viability centers on industrial biotechnology capability rather than petroleum-derived synthesis assets, with acquisition target archetypes clustering around microbial cell factory engineering specialists and regional aroma chemical manufacturers achieving dual certification status. Monitor ECHA restriction list proposals and SAMR GB specification amendments as inflection indicators for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into L-Phenylalanine Supply | Secures fermentation pathway economics against agricultural commodity volatility for biotechnology leaders. |
| REACH Dual-Certification Investment | Unlocks premium positioning in German and Nordic cosmetic markets demanding documented origin credentials. |
| India Contract Manufacturing Scale-Up | Captures PLI scheme incentives and CDSCO harmonization benefits for European aroma house outsourcing. |
| Direct Supplier Relationship Consolidation | Replaces distributor intermediation with traceability-compliant procurement for large fragrance compound blenders. |
| Microbial Cell Factory Partnership | Accelerates natural-grade cost parity achievement against synthetic alternatives through engineered strain development. |
Research Methodology
A spread of perspectives from fragrance house procurement directors, biotechnology R&D leads, aroma chemical plant managers, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with downstream formulators and upstream fermentation specialists, validated against customs trade data, ECHA REACH registration databases, SEC 10-K filings from integrated chemical conglomerates, and SAMR food-grade additive certification records. Bottom-up volume triangulation across synthetic and natural production corridors was cross-checked with top-down demand modeling from personal care and food flavor end-use segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning certification grade tier, end-use industry intensity, packaging format scale, and regional production hub concentration. CAGRs were derived from production capacity expansion timelines, regulatory approval velocity for food-grade applications, and substitution elasticity between petroleum-derived and biotechnology pathways. Forecast inputs incorporated L-phenylalanine feedstock price trajectories and REACH substance evaluation update schedules.
Sensitivities concentrate around ECHA restriction list inclusions, SAMR export specification amendments, and fermentation scale-up engineering bottlenecks that could compress natural-grade supply expansion. Forecasts reflect documented assumptions on biotechnology cost parity achievement and regulatory harmonization pace. Quarterly review of amino acid commodity indices, REACH substance evaluation announcements, and CDSCO regulatory guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Flavors for Pharmaceutical and Healthcare Applications Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Perfumes and Deodorants Market
Flavor and Fragrance Chemicals
Sage Essential Oil Market
Flavor and Fragrance Chemicals
Musk Aroma Chemicals Market
Flavor and Fragrance Chemicals
Gel Air Fresheners Market
Flavor and Fragrance Chemicals
Guaiacwood Essential Oil Market
Flavor and Fragrance Chemicals
Europe Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Natural Vanillin Market
Flavor and Fragrance Chemicals
Neryl Acetate Market
Flavor and Fragrance Chemicals
Smoke Ingredients Market
Flavor and Fragrance Chemicals
Bio-Based Flavors and Fragrances Market
Flavor and Fragrance Chemicals
Global Solid Perfume Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
Asia Pacific Essential Oils Market