
 Pyruvate Market | 2026-2036
Pyruvate Market Size, Share, and Industry Trends Forecast 2026-2036
Pyruvate Market Analytics
Sports nutrition is decoupling from general wellness as the dominant demand vector for pyruvate suppliers. Minakem leverages its European manufacturing footprint to serve pharmaceutical-grade pyruvate contracts. Shanghai Jinli Bio-tech anchors the Asia-Pacific supply base through fermentation-derived production scale. Musashino competes on biochemical synthesis expertise for research-grade material.
Pyruvate is a three-carbon alpha-keto acid (CH3COCOO−) produced through glycolytic metabolism and manufactured industrially via enzymatic conversion of lactic acid or glucose fermentation, serving primarily as a cellular energy intermediate and nutritional supplement active. Sodium pyruvate dominates clinical and cell-culture applications due to superior solubility profiles, while calcium pyruvate captures the weight management segment through its mineral-chelated stability in tablet formulations. The powder form leads production volumes, though capsules command margin premiums in direct-to-consumer channels.
FDA dietary supplement regulations under DSHEA govern pyruvate labeling and health claims in the United States, while China's NMPA and GB standards enforce import purity thresholds for nutritional intermediates. EFSA novel food assessments shape market access pathways for new pyruvate salt variants in Europe. Stakeholders must monitor evolving pharmacovigilance requirements for metabolic intermediates reclassified as active ingredients.
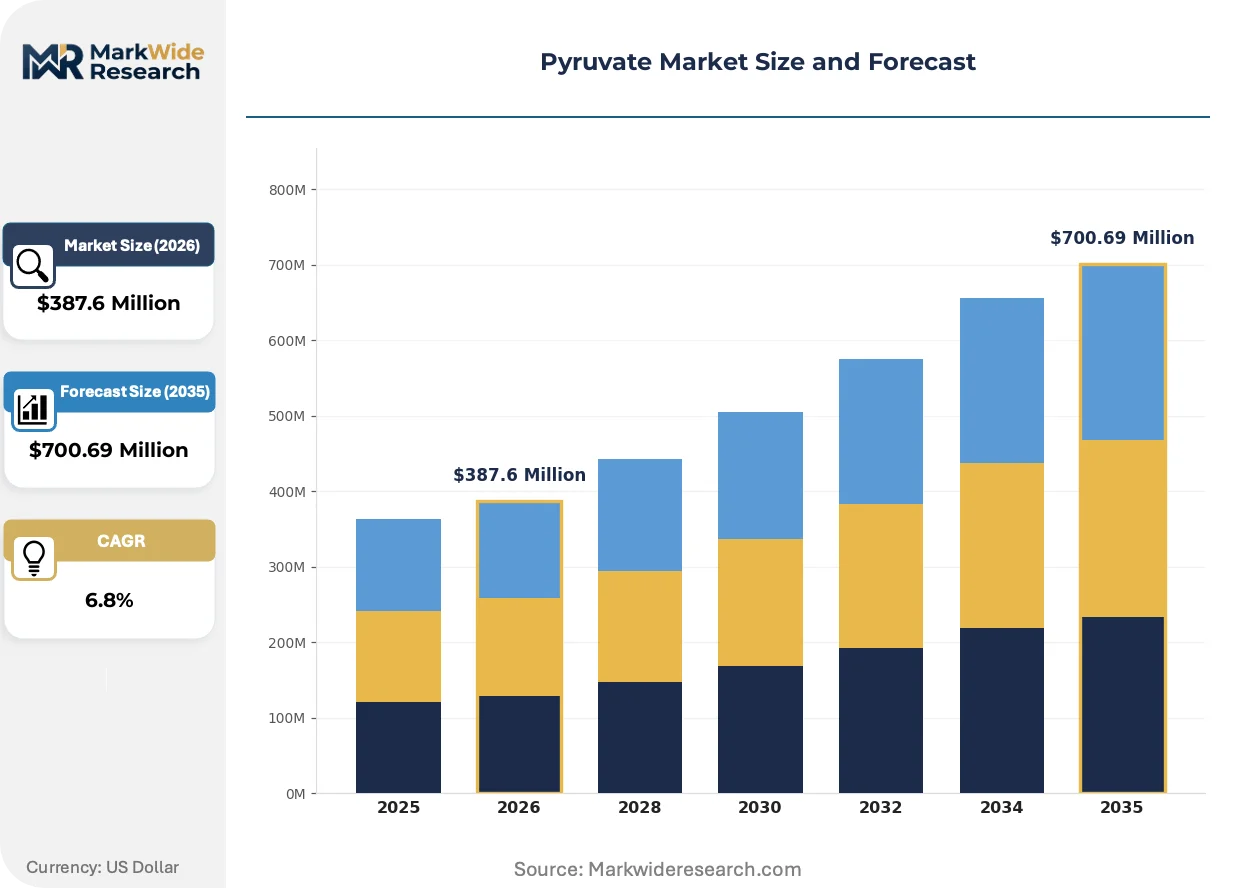
Market Dynamics
Sports nutrition procurement is decoupling from general wellness as the dominant structural force, with fitness-focused consumers driving specification upgrades that ripple back through fermentation and enzymatic production tiers.
Growth Catalysts
- DSHEA framework clarity:FDA dietary supplement regulations provide stable labeling pathways for pyruvate health claims in United States direct-to-consumer channels.
- Cell-culture media expansion:Biopharmaceutical contract manufacturers are standardizing sodium pyruvate in serum-free formulations for mammalian cell lines.
- Weight management tablet demand:Calcium pyruvate's mineral-chelated stability is capturing formulation share in mineral-supplement compounding.
Market Restraints
- Glucose feedstock volatility:Corn-derived glucose price swings compress margins for fermentation-based producers.
- Asia-Pacific supply concentration:China's NMPA purity benchmarks create import friction for non-domestic fermentation capacity.
- Enzymatic lactic acid conversion limits:Stereoselectivity constraints in biocatalytic routes restrict pharmaceutical-grade yield rates.
Strategic Opportunities
- EFSA novel food pathway:New pyruvate salt variants can access European markets through centralized safety assessments.
- Direct-to-consumer capsule channels:Margin premiums in subscription wellness models reward branded formulation differentiation.
- Bioreactor automation convergence:Sensor-integrated fermentation is compressing batch-to-batch variability for research-grade material.
Industry Challenges
- Pharmacovigilance skill scarcity:Metabolic intermediate reclassification as active ingredients demands toxicology expertise that outpaces training pipelines.
- Dual-use certification timelines:Food-grade and pharmaceutical-grade GMP compliance for the same production line extends facility qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyruvate Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Pyruvate, Sodium Pyruvate, Potassium Pyruvate, Magnesium Pyruvate End User: Healthcare Providers, Dietary Supplement Manufacturers, Fitness Industry, Academic Institutions Form: Powder, Capsules, Tablets, Liquids Application: Weight Management, Sports Nutrition, Energy Supplementation, Muscle Recovery |
| Companies Covered | Minakem, Tianjin Shengdao Technology, Shanghai Jinli Bio-tech, Musashino, Toray, Jiangyin Kangda Chemical, Shanghai Lianlu Industrial, Zhonglan Industry, Jinan Pengbo Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyruvate Market Evolving Landscape
Fermentation process control, regulatory divergence across major economies, and channel specialization are actively restructuring how pyruvate specifications propagate from production to end-use.
Continuous bioprocessing technology is automating real-time metabolite monitoring in glucose-to-pyruvate conversion. Contract fermentation houses in the United States and Germany are adopting these sensor-integrated systems to reduce batch failure rates. The technology is automating quality assurance checkpoints that previously required manual sampling and offline chromatography.
REACH substance registration requirements are tightening documentation burdens for pyruvate salt imports into European Union member states. ECHA compliance costs are filtering smaller traders from the nutritional intermediate supply base. Pharmaceutical-grade sodium pyruvate contracts are consolidating among registrants with existing dossier infrastructure.
Fitness-focused consumers are fragmenting procurement across specialized sports nutrition platforms rather than general wellness retailers. Direct-to-consumer brands are capturing margin by bypassing traditional supplement distribution. This behavioral pivot concentrates in United States metropolitan markets with established CrossFit and functional fitness studio density.
Pyruvate Market Segmentation
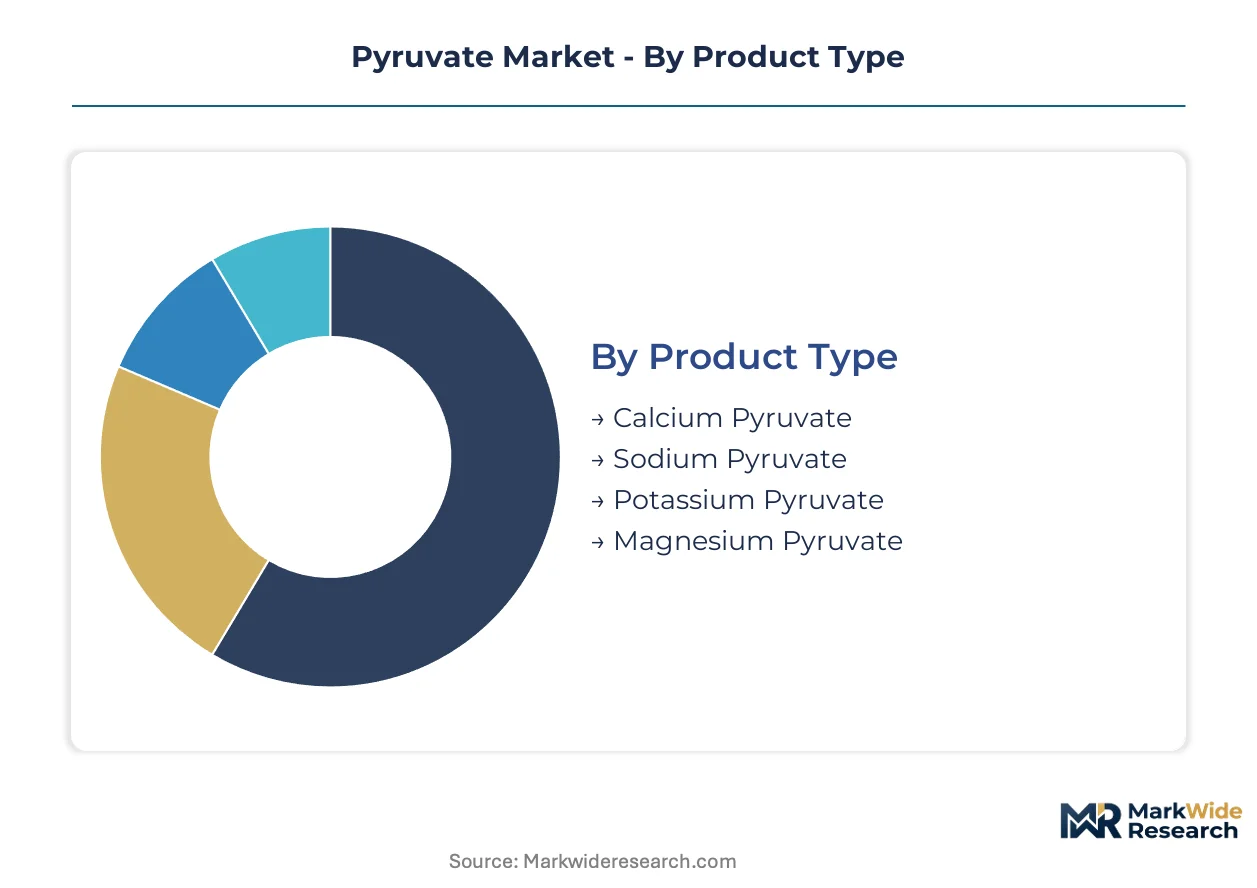
Pyruvate specifications diverge sharply across end-use requirements, with pharmaceutical-grade sodium salts demanding fermentation traceability while sports nutrition favors mineral-chelated forms for tablet stability. Manufacturers configure production lines around these purity and formulation thresholds rather than chasing universal grades.
Product Type:
Sodium pyruvate anchors the customization end of this spectrum with GMP-certified fermentation batches, while calcium and magnesium variants standardize for mass-market supplement compounding.
- Sodium Pyruvate:Superior aqueous solubility drives specification in serum-free cell-culture media and intravenous formulations. Biopharmaceutical contract manufacturers in the United States standardize this grade for mammalian cell-line propagation. FDA DSHEA labeling pathways reinforce its position in clinical nutrition.
- Calcium Pyruvate:Mineral-chelated stability enables direct compression into weight management tablets without excipient overload. Fitness-focused consumer cohorts in United States metropolitan markets drive procurement volumes through subscription wellness channels. China's NMPA import purity benchmarks create friction for non-domestic fermentation capacity serving this segment.
- Potassium Pyruvate:Electrolyte-balanced variant targeting hydration-focused sports formulations with mineral-repletion positioning.
- Magnesium Pyruvate:Dual-action mineral delivery combining pyruvate metabolism support with magnesium cofactor functions in energy pathway supplements.
Most installed capacity flows through Sodium Pyruvate. Expansion is steepest in Calcium Pyruvate.
End User:
Volume concentration sits with formulation houses serving fitness consumers, while margin capture concentrates in healthcare procurement governed by pharmacovigilance requirements.
- Dietary Supplement Manufacturers:Direct-to-consumer brands bypass traditional distribution through subscription models and specialized sports nutrition platforms. CrossFit studio density in United States metropolitan markets correlates with regional procurement intensity. EFSA novel food assessments shape European market access for new pyruvate salt variants.
- Healthcare Providers:Clinical nutrition protocols and metabolic disorder management drive pharmaceutical-grade sodium pyruvate contracts. Parenteral formulations require fermentation traceability and endotoxin documentation that enzymatic routes struggle to deliver. Dual-use GMP compliance extends facility qualification timelines for suppliers serving both food and pharmaceutical tiers.
- Fitness Industry:Functional fitness studios and performance coaching networks fragment procurement across branded supplement lines rather than generic wellness retailers.
- Academic Institutions:Research-grade material for cell-culture and metabolism studies with batch-to-batch variability tolerance higher than clinical applications.
Procurement volume concentrates with Dietary Supplement Manufacturers. Margin expansion is most pronounced in Healthcare Providers.
Form:
Production economics favor bulk powder throughput, while finished goods differentiation drives capsule and tablet premiums in branded channels.
- Powder:Dominates fermentation output volumes with cost-efficient bulk handling for industrial compounding and research-scale procurement. Continuous bioprocessing automation is compressing batch-to-batch variability through real-time metabolite monitoring.
- Capsules:Command margin premiums in direct-to-consumer subscription wellness models through dosing convenience and brand differentiation. United States fitness-focused consumers fragment procurement toward specialized platforms over general wellness retailers.
- Tablets:Calcium pyruvate's mineral-chelated stability enables direct compression without complex excipient systems for weight management positioning.
- Liquids:Ready-to-drink sports nutrition applications with solubility advantages for rapid absorption claims in endurance athlete segments.
Manufacturing throughput centers on Powder. Revenue per kilogram peaks in Capsules.
Application:
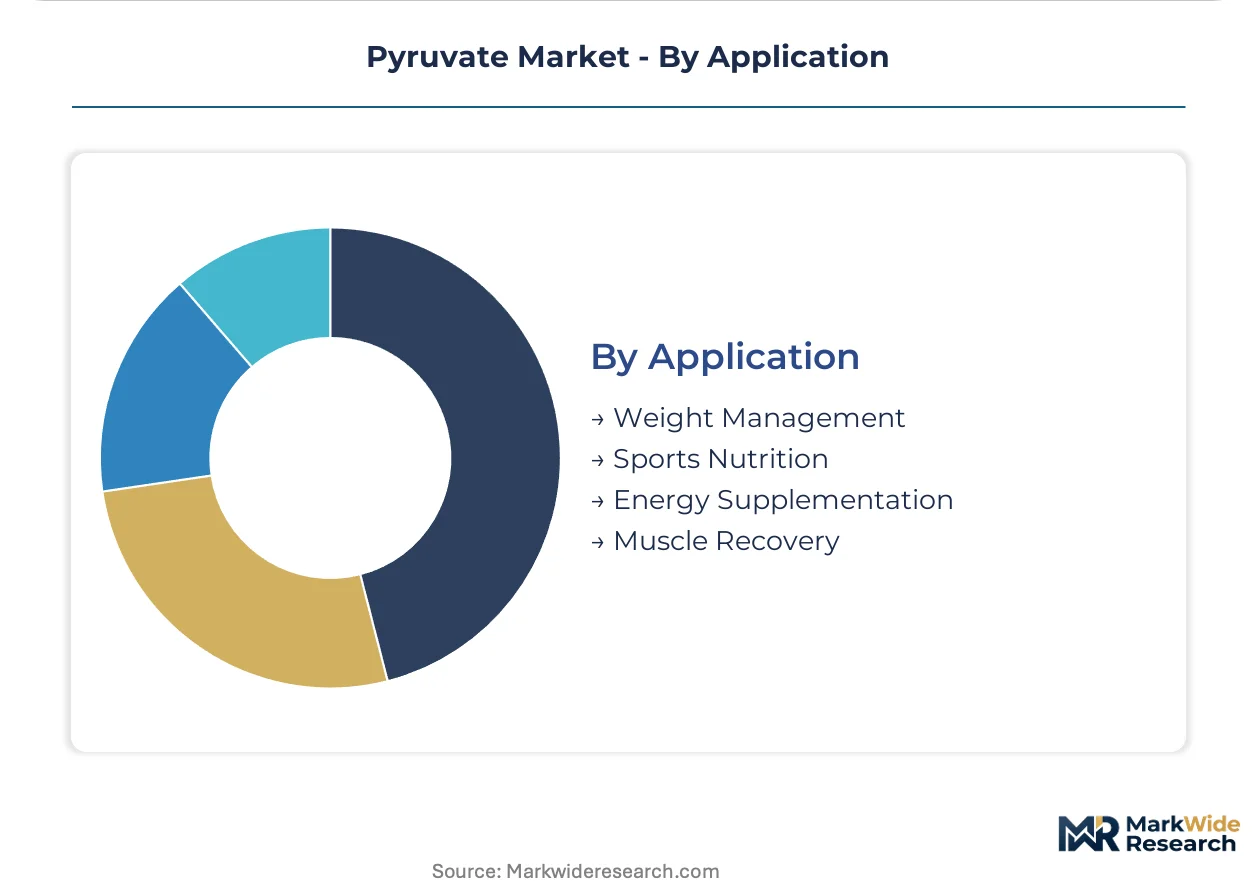
Sports nutrition is decoupling from general wellness as the dominant demand vector, with muscle recovery and energy supplementation fragmenting into distinct formulation specifications.
- Sports Nutrition:Pre-workout and intra-workout formulations drive sodium pyruvate procurement for rapid cellular energy intermediate replenishment. Fitness studio density in United States metropolitan markets concentrates demand. Sensor-integrated fermentation automation is reducing batch failure rates for contract manufacturers serving this segment.
- Weight Management:Calcium pyruvate's tablet stability and mineral-chelated positioning capture formulation share in mineral-supplement compounding. Direct-to-consumer brands extract margin through subscription models bypassing traditional distribution.
- Energy Supplementation:General wellness positioning with broader consumer reach but lower per-unit pricing power than sports-specific formulations.
- Muscle Recovery:Post-exercise metabolic support with emerging differentiation from protein-centric recovery products through cellular energy pathway claims.
Formulation activity concentrates in Sports Nutrition. Steepest expansion trajectory is occurring in Muscle Recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping pyruvate production geography as manufacturers relocate fermentation capacity to jurisdictions with streamlined GMP certification pathways and lower compliance overhead.
United States
Fitness-focused consumer cohorts in metropolitan markets drive sodium pyruvate procurement for sports nutrition formulations. FDA DSHEA regulations provide stable labeling frameworks for direct-to-consumer health claims. CrossFit studio density in Austin, Denver, and Miami concentrates demand fragmentation toward specialized subscription platforms.
China
Shanghai Jinli Bio-tech anchors Asia-Pacific supply through fermentation-derived production scale serving domestic and export markets. NMPA tightened purity benchmarks for imported nutritional intermediates, creating friction for foreign capacity. Yangtze River Delta chemical clusters in Jiangsu and Zhejiang provinces host enzymatic conversion facilities for research-grade material.
Germany
Minakem leverages its European manufacturing footprint for pharmaceutical-grade pyruvate contracts requiring fermentation traceability. REACH substance registration requirements filter smaller traders from the nutritional intermediate supply base. Bavarian biotech clusters around Munich and Heidelberg specialize in cell-culture media formulations.
Japan
Musashino competes on biochemical synthesis expertise for research-grade pyruvate serving academic and biopharmaceutical end-users. PMDA pharmacovigilance requirements demand toxicology documentation that outpaces training pipelines. Kanto region manufacturing around Tokyo-Yokohama concentrates high-purity salt production for parenteral applications.
India
Dietary supplement manufacturers scale procurement for domestic sports nutrition and export formulation houses. CDSCO import regulations for active pharmaceutical ingredients create documentation burdens for metabolic intermediate reclassification. Maharashtra and Gujarat chemical corridors develop fermentation capacity for mineral-chelated pyruvate variants.
Pyruvate Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation houses automate sensor-integrated bioprocessing to compress batch-to-batch variability. The vendor base stratifies across three tiers: pharmaceutical-grade specialists with GMP-certified traceability, mass-market mineral-chelated form suppliers, and research-grade biochemical synthesis operators. Strategic archetypes include European contract manufacturers leveraging REACH dossier infrastructure, Asia-Pacific fermentation scale players, and Japanese precision synthesis specialists. Competitive moves center on bioreactor automation convergence and dual-use facility qualification for simultaneous food-grade and pharmaceutical-grade production.
Among European GMP-certified operators, Minakem exemplifies the pharmaceutical-grade archetype through its fermentation traceability capabilities. Shanghai Jinli Bio-tech represents the Asia-Pacific scale-driven tier with domestic fermentation infrastructure. Musashino occupies the precision synthesis position for research-grade material requirements.
| Leading Market Players |
|---|
| Minakem |
| Tianjin Shengdao Technology |
| Shanghai Jinli Bio-tech |
| Musashino |
| Toray |
| Jiangyin Kangda Chemical |
| Shanghai Lianlu Industrial |
| Zhonglan Industry |
| Jinan Pengbo Biotechnology |
| Others |
Value Network & Pricing Analysis
Sensor-integrated fermentation automation is compressing batch-to-batch variability while simultaneously concentrating production economics among operators with capital-intensive bioreactor infrastructure, reshaping how cost advantages accrue to scale players versus specialized GMP-certified houses.
Pricing Analysis
Direct-to-consumer subscription margins reward branded formulation differentiation over commodity powder sales. Three-tier pricing structure across pharmaceutical-grade, food-grade, and research-grade levels reflects certification investment and endotoxin documentation burdens. Pricing pressure stems from glucose feedstock volatility compressing fermentation margins. Dietary supplement manufacturers exhibit highest price sensitivity, while biopharmaceutical contract manufacturers prioritize traceability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification pyruvate batches remain underdeveloped, with most material diverted to lower-grade applications rather than reclamation. Supply concentrates in China, Germany, and the United States, with Yangtze River Delta and Bavarian biotech clusters anchoring regional capacity. Corn-derived glucose, lactic acid feedstock, and mineral chelation agents constitute critical input dependencies. Tariff exposure on Chinese fermentation capacity creates single-source vulnerability for European and North American formulation houses. Distribution runs through specialized nutritional intermediate distributors and direct pharmaceutical-grade contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where fermentation capacity relocation to jurisdictions with streamlined dual-use GMP certification and lower REACH compliance overhead captures structural margin expansion unavailable to legacy European operators.
For Market Incumbents: Cement pharmaceutical-grade positioning through endotoxin documentation capabilities that enzymatic competitors cannot replicate. Invest in backward integration into glucose feedstock sourcing to buffer corn price volatility. Defend against Asia-Pacific scale players by emphasizing fermentation traceability for parenteral applications where regulatory scrutiny is intensifying. For New Entrants and Emerging Players: Begin with mineral-chelated pyruvate variants for weight management tablets, where formulation stability requirements create formulation-switching costs. Target United States metropolitan fitness markets with direct-to-consumer subscription models bypassing traditional supplement distribution. Pursue EFSA novel food assessments for European market access before incumbent dossier consolidation hardens. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation houses with existing dual-use GMP infrastructure because facility qualification timelines extend competitive moats against greenfield entrants. Long-term viability hinges on bioreactor automation convergence compressing batch failure rates. Monitor NMPA purity benchmark tightening as inflection indicator for import friction benefiting domestic Chinese capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Automation Convergence | Sensor-integrated fermentation reduces batch failure rates for contract manufacturers serving sports nutrition. |
| Dual-Use GMP Facility Qualification | Simultaneous food-grade and pharmaceutical-grade certification extends competitive moats against specialized competitors. |
| Backward Integration into Glucose Sourcing | Corn supply chain control buffers margin compression from feedstock price volatility in fermentation economics. |
| EFSA Novel Food Dossier Investment | Centralized safety assessments enable European market access for new pyruvate salt variants before incumbent consolidation. |
| Direct-to-Consumer Channel Development | Subscription wellness models capture margin premiums unavailable through traditional supplement distribution networks. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with fermentation plant managers, dietary supplement procurement leads, biopharmaceutical contract manufacturing executives, and regulatory affairs specialists informed supply-side and demand-side dynamics. Secondary sources included FDA DSHEA guidance documents, EFSA novel food assessment registers, NMPA import purity benchmarks, customs trade data, and SEC filings from publicly traded nutritional ingredient suppliers. Bottom-up volume modeling triangulated against top-down market sizing.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects. Segmentation dimensions modeled included pyruvate salt type, end-user industry, grade certification tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical production data and forward projection of fitness-focused consumer cohort expansion. Industry-specific inputs incorporated glucose feedstock price forecasting and biopharmaceutical cell-culture media demand curves.
Several conditions sit outside the modeled scope, including potential reclassification of pyruvate as an active pharmaceutical ingredient requiring pharmacovigilance infrastructure, and disruptive synthetic biology routes bypassing traditional fermentation. Forecasts reflect assumptions about regulatory stability and consumer behavior continuity that material shifts could invalidate. Practitioners should monitor NMPA enforcement actions, EFSA assessment timelines, and glucose futures volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Chemicals
Green Chemical and Material Market
Renewable Chemicals
Pink Hydrogen Market
Renewable Chemicals
Bio-Based Ethylene Market
Renewable Chemicals
Renewable Chemicals Market
Renewable Chemicals
Global Bio-Renewable Chemicals Market
Renewable Chemicals
Natural L-Lactic Acid Market
Renewable Chemicals
Global Green Chemicals Market
Renewable Chemicals
Green Ammonia Manufacturing Market
Renewable Chemicals
Butyraldehyde Market
Renewable Chemicals
Renewable Fuel Materials Market
Renewable Chemicals
Renewable Solvent Market
Renewable Chemicals
Seaweed Biomass Waste Market