
 Ethernet Switch Market | 2026-2036
Ethernet Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Ethernet Switch Market Intelligence
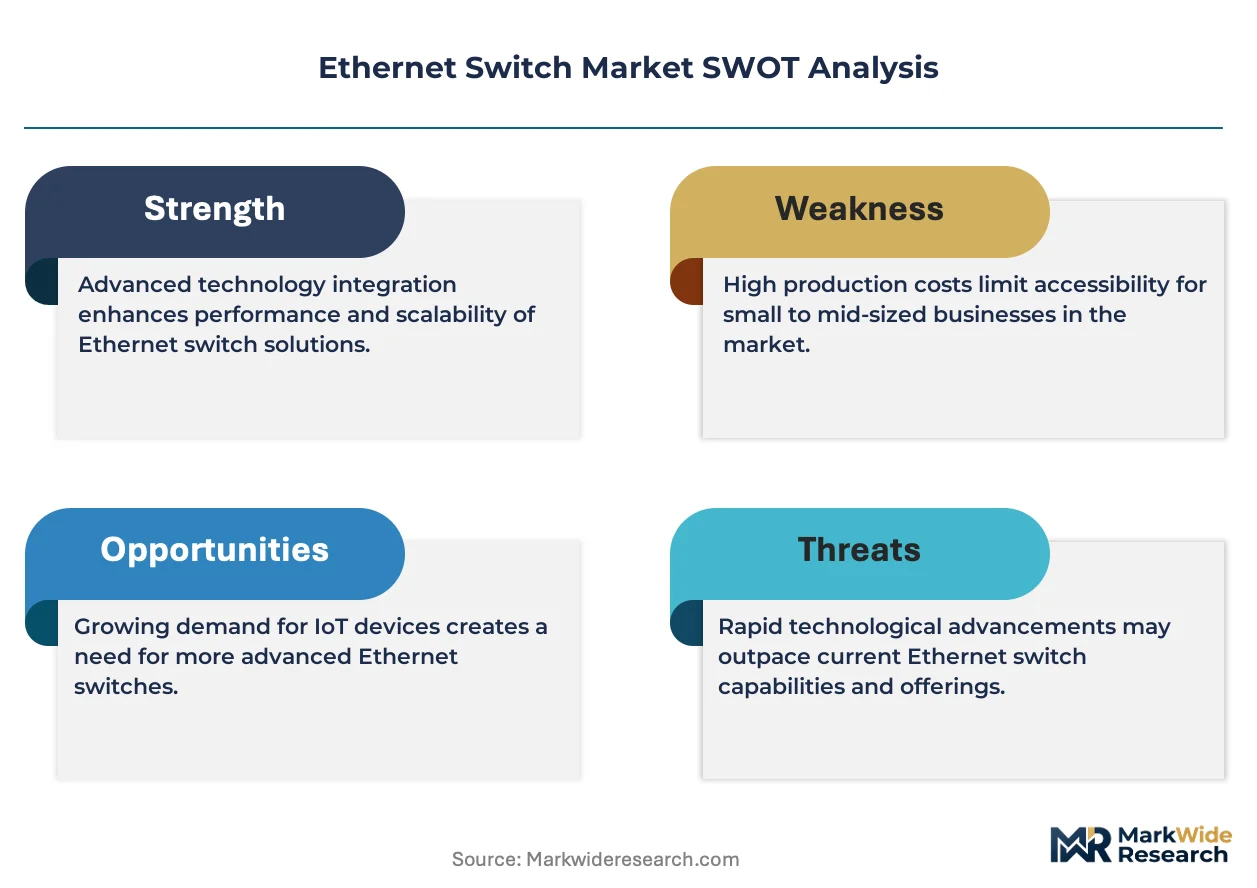
White-box switching and merchant silicon is fragmenting traditional vendor hierarchies in Ethernet switch procurement. Cisco Systems anchors enterprise campus deployments through proprietary ASIC roadmaps and deep channel entrenchment. Arista Networks specializes in cloud-optimized platforms with lean software stacks that appeal to hyperscale operators. Huawei Technologies competes aggressively in price-sensitive geographies through captive semiconductor sourcing and integrated optical modules.
An Ethernet switch is a Layer 2 networking device that forwards data frames between connected devices using MAC address tables, with modern implementations supporting switching capacities from 100 Gbps to 51.2 Tbps in chassis-based systems. Its primary purpose is to reduce collision domains and enable deterministic traffic flows across enterprise, cloud, and telecommunications infrastructure. Managed switches command premium positioning through programmability and telemetry features that network operators require for zero-touch provisioning. Gigabit Ethernet and 100 Gigabit Ethernet represent the fastest-expanding technology tiers as edge aggregation and spine-leaf architectures drive port speed transitions. Data centers and cloud computing applications concentrate capital expenditure where power-per-bit efficiency dictates procurement decisions.
FCC equipment authorization requirements govern electromagnetic emissions for switches deployed in US commercial environments, while the EU AI Act and CSRD disclosure rules shape procurement criteria for European enterprise buyers prioritizing sustainable supply chains. IEEE 802.3 working group standards define interoperability baselines that determine which speed tiers achieve economies of scale. Stakeholders must monitor merchant silicon roadmaps from Broadcom and Marvell against proprietary ASIC investments to calibrate platform refresh timing and partnership strategies.
Market Dynamics
The IEEE 802.3 standards evolution toward 800G and 1.6T PHY layers is compressing refresh cycles across hyperscale data centers, forcing procurement teams to recalibrate depreciation schedules against backward compatibility requirements.
Growth Catalysts
- Hyperscale buildouts:Cloud computing providers in China are expanding port density requirements for spine-leaf architectures, driving chassis-based system upgrades.
- Merchant silicon roadmaps:Broadcom and Marvell are accelerating 51.2 Tbps switching capacity availability, enabling white-box alternatives to proprietary ASIC platforms.
- FCC equipment authorization:Streamlined electromagnetic emissions testing for US commercial deployments reduces time-to-market for new speed tiers.
Market Restraints
- Semiconductor supply concentration:Advanced 7nm and 5nm fabrication for switch ASICs depends on Taiwan-based foundry capacity, creating geographic risk exposure.
- Power density constraints:800G port rollouts face thermal management limitations in existing data center cooling infrastructure, requiring facility retrofits.
- Proprietary software lock-in:Cisco's IOS and NX-OS ecosystems create switching friction for enterprises evaluating alternative vendors.
Strategic Opportunities
- Edge computing expansion:5G base station buildouts in India under TRAI spectrum allocations are creating distributed switching demand outside traditional data centers.
- EU CSRD disclosure rules:European enterprise buyers are prioritizing sustainable supply chains, creating procurement preference for vendors with verified Scope 3 emissions data.
- Co-packaged optics convergence:Integration of silicon photonics with switch ASICs is enabling power-per-bit efficiency gains for cloud operators.
Industry Challenges
- Legacy protocol integration:Enterprises maintaining Spanning Tree Protocol environments face complexity migrating to EVPN-VXLAN fabrics without service disruption.
- Specialized talent scarcity:Network engineering teams with expertise in P4 programming and SONiC deployment command premium compensation, constraining vendor implementation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethernet Switch Market |
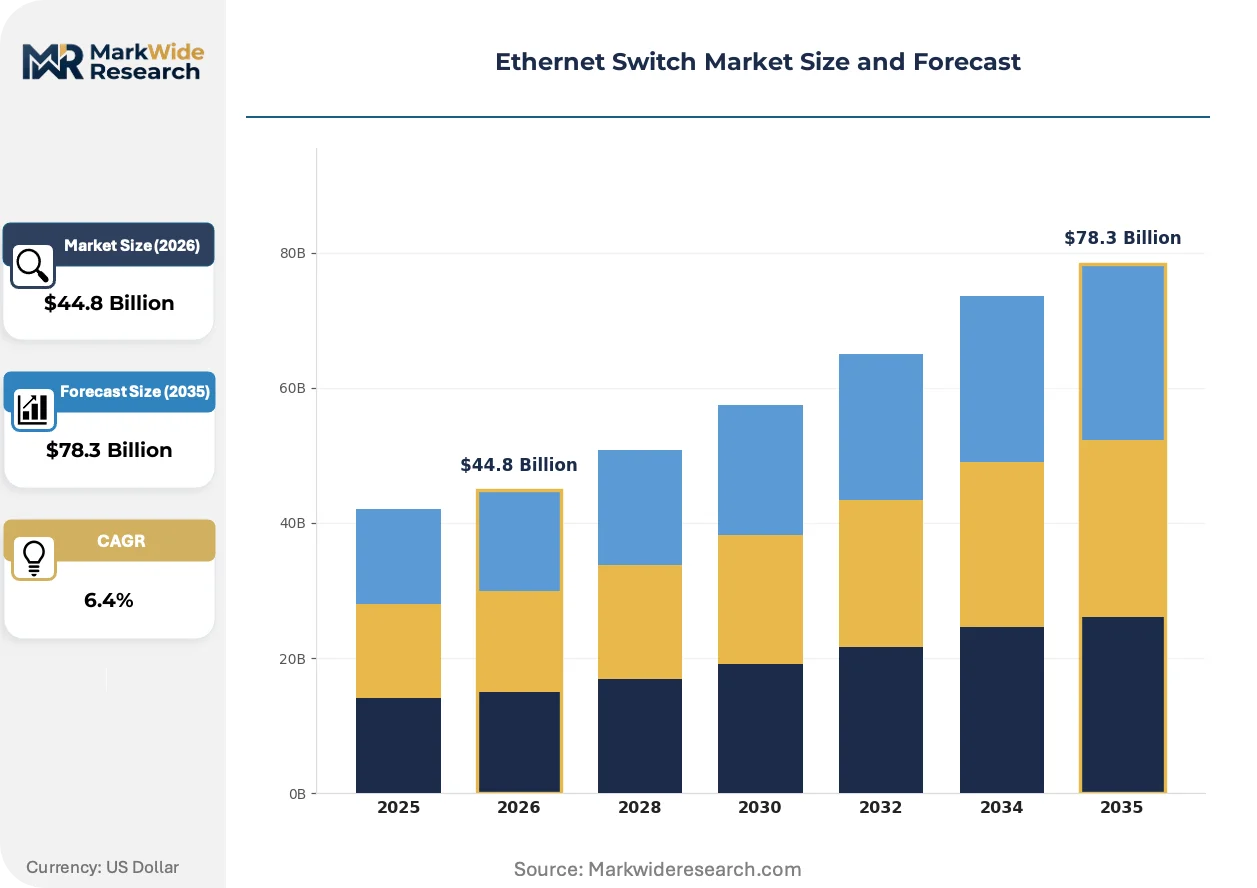
| Market Size in 2026 | $44.8 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Managed Switches, Unmanaged Switches, Smart Switches, Modular Switches Technology: Fast Ethernet, Gigabit Ethernet, 10 Gigabit Ethernet, 40 Gigabit Ethernet, 100 Gigabit Ethernet Application: Data Centers, Enterprise Networks, Cloud Computing, Telecommunications, Campus Networks End User: Telecom Providers, Data Center Operators, Financial Institutions, Educational Institutions, Government Agencies |
| Companies Covered | Hewlett Packard Enterprise, Belden, Cisco Systems, Moxa, Siemens, Huawei Technologies, Juniper Networks, Extreme Networks, Arista Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethernet Switch Market Strategic Shifts & Innovations
Software-defined networking principles are penetrating hardware procurement decisions, collapsing traditional distinctions between silicon, operating system, and network management layers.
SmartNIC and DPU offloading architectures are digitizing packet processing workflows that previously consumed host CPU cycles. Hyperscale operators are deploying these accelerators at rack scale to reclaim compute resources for revenue-generating workloads. This architecture is digitizing the boundary between server and network infrastructure, forcing switch vendors to expose programmable pipeline stages.
The EU AI Act risk classification framework is reshaping procurement criteria for switches deployed in high-risk AI training clusters. European enterprise buyers now require documentation of supply chain provenance and energy consumption transparency. German automotive manufacturers and French pharmaceutical groups are imposing these standards on global vendor selection processes.
Hyperscale operators are consolidating procurement through direct merchant silicon relationships, bypassing traditional OEM channel structures. Cloud providers now negotiate directly with Broadcom and Marvell for volume allocations, treating switch vendors as integration partners rather than technology sources. This pattern concentrates most visibly among US-based cloud operators with captive engineering organizations.
Ethernet Switch Market Segmentation
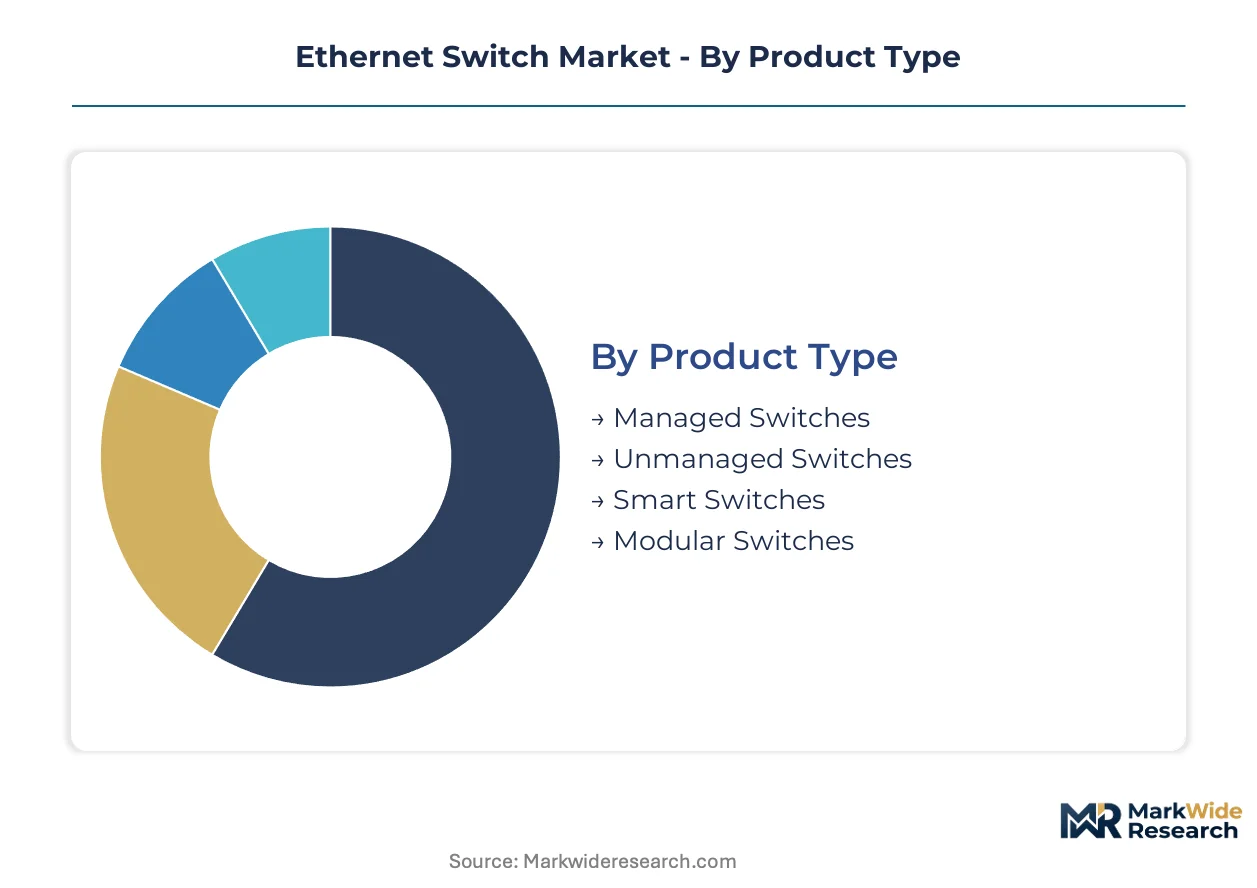
Ethernet switch procurement patterns diverge sharply across deployment contexts, with refresh cycles spanning three years in hyperscale facilities to seven years in campus edge closets. Understanding these temporal rhythms helps vendors calibrate platform roadmaps against depreciation schedules and interoperability requirements.
Product Type:
Refresh velocity varies dramatically: unmanaged units turn over fastest at commodity price points, while modular chassis systems persist through multiple speed-generation upgrades.
- Managed Switches:Programmable platforms with telemetry, zero-touch provisioning, and EVPN-VXLAN fabric support command enterprise premiums. Demand concentrates in US financial services and German automotive manufacturing where FCC equipment authorization and EU CSRD disclosure rules shape procurement workflows.
- Unmanaged Switches:Plug-and-play Layer 2 devices with fixed configurations serve cost-sensitive edge deployments. Volume clusters in India small-office environments under TRAI spectrum allocation-driven connectivity expansion.
- Smart Switches:Web-managed hybrids offering VLAN segmentation without full CLI complexity address mid-market budget constraints.
- Modular Switches:Chassis-based systems with line-card upgrade paths protect capital investment across IEEE 802.3 speed transitions.
Modular switches dominate installed base value. Managed switches are where expansion concentrates.
Technology:
Cost tier stratification separates legacy access-layer deployments from spine-leaf aggregation demanding power-per-bit efficiency.
- Fast Ethernet:100 Mbps legacy infrastructure persists in industrial control systems and building automation where protocol stability outweighs bandwidth requirements.
- Gigabit Ethernet:Per-port costs below $50 enable mass desktop connectivity refresh in educational institutions and government agencies.
- 10 Gigabit Ethernet:Server access-layer standard in enterprise data centers facing storage traffic consolidation.
- 40 Gigabit Ethernet:Transitional speed tier displaced by 100G economics in new hyperscale construction.
- 100 Gigabit Ethernet:100 Gbps ports with PAM4 signaling and QSFP28/QSFP-DD form factors anchor spine-layer aggregation. Deployment concentrates in China hyperscale buildouts where port density requirements per rack exceed 128 100G interfaces.
Gigabit Ethernet dominates shipped volume. 100 Gigabit Ethernet is climbing the fastest.
Application:
Customer type determines margin structure: cloud operators negotiate direct merchant silicon relationships while enterprise campuses tolerate OEM channel markups.
- Data Centers:Hyperscale facilities with 100,000+ port counts drive 51.2 Tbps switching capacity demand. Procurement teams in US cloud providers bypass traditional vendor hierarchies through Broadcom and Marvell direct allocation agreements.
- Enterprise Networks:Distributed branch-office connectivity with centralized policy enforcement characterizes multi-site retail and healthcare deployments.
- Cloud Computing:Elastic compute environments require programmable pipelines exposing P4 and SONiC interfaces for custom forwarding logic.
- Telecommunications:5G fronthaul and midhaul timing synchronization via IEEE 1588 PTP governs cell site Ethernet switch selection.
- Campus Networks:Wi-Fi 6E and 7 access-point aggregation drives multi-gigabit edge port upgrades in university and corporate environments.
Enterprise Networks dominate installed base. Cloud Computing is gaining share fastest.
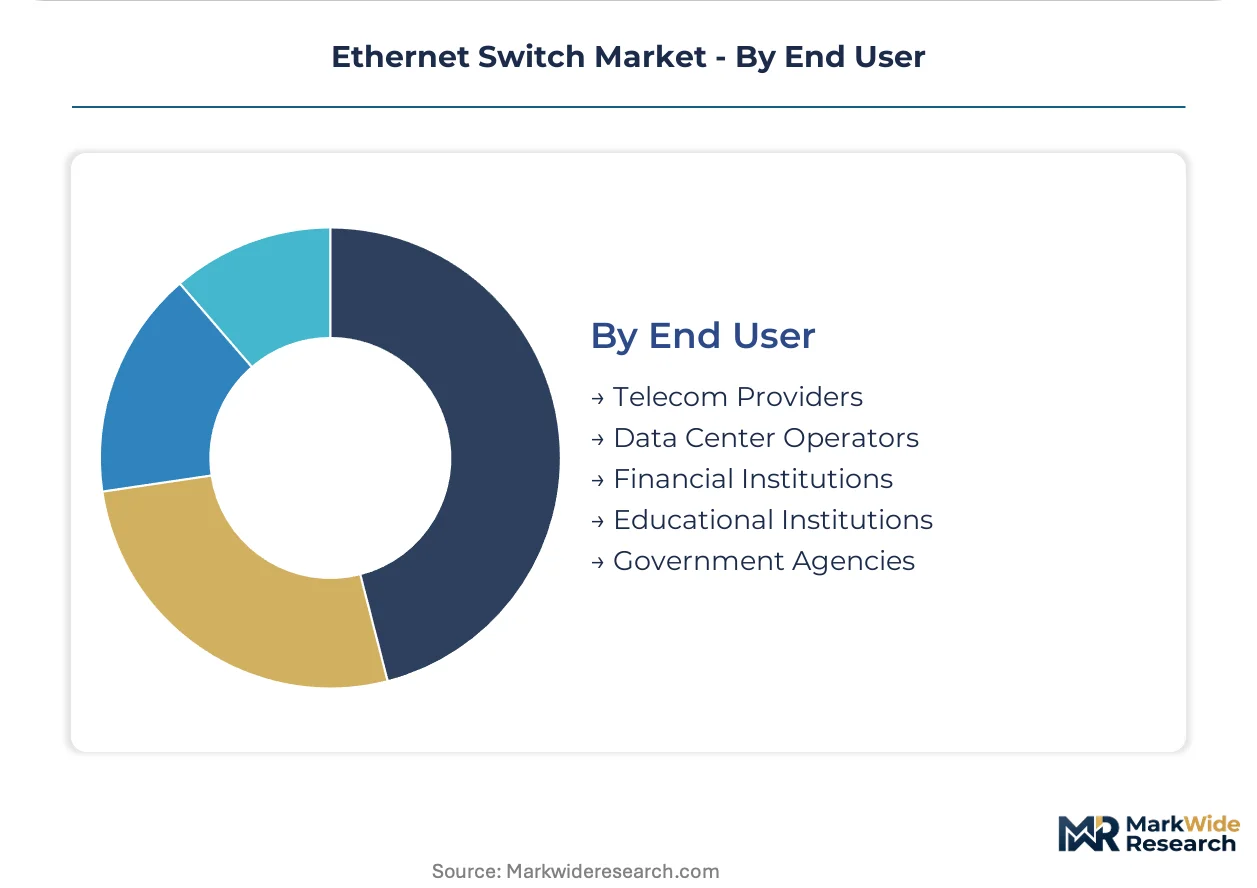
End User:
Supply concentration aligns with geographic clustering of procurement authority.
- Telecom Providers:National carriers with spectrum licenses aggregate radio access network traffic through timing-aware switching platforms.
- Data Center Operators:Colocation providers and hyperscale self-builders differentiate through power usage effectiveness metrics tied to switch efficiency.
- Financial Institutions:Low-latency trading infrastructure in Chicago, London, and Singapore requires cut-through switching with sub-500 nanosecond port-to-port latency.
- Educational Institutions:K-12 and university networks prioritize E-rate funding compliance and multi-vendor interoperability over advanced features.
- Government Agencies:FedRAMP authorization and FIPS 140-2 cryptographic module validation constrain vendor selection for US federal deployments.
Data Center Operators dominate capital deployment. Financial Institutions show the steepest expansion trajectory for ultra-low-latency platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports merchant silicon and chassis-based systems to hyperscale operators across the United States and Europe, while Taiwan supplies advanced ASIC fabrication capacity that underpins switching platforms worldwide.
United States
Hyperscale cloud operators in Virginia and Oregon drive 100G and 400G spine-layer procurement through direct merchant silicon negotiations. FCC equipment authorization requirements govern electromagnetic emissions testing for commercial deployments. The Ashburn-Loudoun County corridor hosts the world's densest concentration of data center switching capacity.
China
Domestic hyperscale buildouts by Alibaba, Tencent, and ByteDance consume half of global 100G port shipments annually. MIIT cybersecurity regulations and GB standards compliance shape vendor qualification workflows. The Yangtze River Delta cluster around Shanghai anchors domestic switching equipment manufacturing and captive semiconductor sourcing.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg impose EU CSRD disclosure requirements on network infrastructure suppliers. The EU AI Act risk classification framework governs procurement for AI training clusters. Frankfurt's financial district demands sub-500 nanosecond latency switching for algorithmic trading infrastructure.
India
TRAI spectrum allocations for 5G are accelerating distributed edge switching deployments outside traditional data centers. The PLI scheme for telecom equipment manufacturing is attracting switch assembly investments. Karnataka's Bengaluru cluster concentrates enterprise networking procurement for IT services exporters.
Japan
METI industrial digitization programs are refreshing manufacturing floor Ethernet infrastructure with deterministic timing capabilities. JIS standards interoperability requirements protect incumbent vendor relationships in enterprise segments. The Tokyo-Osaka corridor maintains legacy Gigabit Ethernet deployments with seven-year refresh cycles.
Ethernet Switch Market Key Industry Players
On the supply side, the industry is consolidating around three distinct capability tiers. Proprietary ASIC vendors, merchant silicon integrators, and white-box assemblers each command differentiated margin structures. Strategic archetypes include full-stack incumbents with channel entrenchment, cloud-native specialists with lean software stacks, and price-aggressive challengers with captive component sourcing. Competitive moves center on co-packaged optics partnerships and direct hyperscale procurement relationships that bypass traditional OEM channels.
Within the proprietary ASIC tier, Cisco Systems exemplifies full-stack integration through IOS and NX-OS ecosystem lock-in. Arista Networks occupies a cloud-optimized position with programmable platforms appealing to hyperscale operators. Huawei Technologies anchors price-sensitive geographies through integrated optical module sourcing and domestic semiconductor supply chains.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Belden |
| Cisco Systems |
| Moxa |
| Siemens |
| Huawei Technologies |
| Juniper Networks |
| Extreme Networks |
| Arista Networks |
| Others |
Cost & Logistics Intelligence
Taiwan foundry concentration for 7nm and 5nm switch ASICs compresses margin buffers across all pricing tiers while simultaneously dictating supply chain resilience strategies. This single-source dependency for advanced fabrication creates asymmetric pricing power for merchant silicon vendors and forces procurement teams to accept longer lead times or premium allocation fees.
Pricing Analysis
100G-to-400G generation transitions create three-tier pricing structure across premium, standard, and economy levels. Proprietary ASIC platforms from Cisco and Arista command brand premiums and certification-grade positioning for financial services buyers, while white-box alternatives with Broadcom Tomahawk silicon compete on per-port cost for hyperscale operators. Cost compression in 100G spine-layer deployments is intensifying because merchant silicon roadmaps from Marvell and Broadcom accelerate 51.2 Tbps availability. Cloud computing providers show least price sensitivity due to power-per-bit efficiency mandates, whereas educational institutions dependent on E-rate funding exhibit highest sensitivity to per-port acquisition costs.
Supply Chain Analysis
Silicon wafer feedstock draws from Taiwan, South Korea, and the United States for advanced switch ASIC production. Optical transceiver components source from China and Malaysia, while chassis assembly concentrates in Mexico and Eastern European facilities serving regional demand clusters. Single-source vulnerability at the 5nm foundry tier represents the dominant structural risk, with TSMC capacity allocation decisions directly determining switch vendor shipment schedules. Distribution runs through OEM channel partners for enterprise campus deployments, whereas hyperscale operators procure through direct merchant silicon relationships bypassing traditional vendor hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethernet switch procurement fragmentation creates specialized vendor niches as hyperscale operators bypass traditional OEM channels through direct silicon negotiations. This demand-side disintermediation rewards players with captive engineering capabilities and programmable platform expertise.
For Market Incumbents: Harden proprietary software ecosystems through deeper IOS and NX-OS integration with cloud-native telemetry stacks, defending against white-box encroachment in enterprise segments. Expand captive semiconductor sourcing relationships beyond Taiwan foundries to mitigate geographic concentration risk. Prioritize co-packaged optics R&D partnerships to maintain power-efficiency leadership against merchant silicon alternatives. For New Entrants and Emerging Players: Build out SONiC-compatible platforms targeting Indian 5G edge computing deployments under TRAI spectrum expansion, where distributed switching demand outpaces incumbent vendor coverage. Focus on mid-market smart switch positioning with web-managed VLAN capabilities for cost-sensitive educational and small-office environments. Pursue channel partnerships with regional systems integrators lacking direct hyperscale procurement access. For Investors and Strategic Acquirers: EU CSRD disclosure rules reshape the acquisition landscape by elevating vendors with verified Scope 3 emissions data and sustainable supply chain documentation. Frame long-term viability around programmable pipeline expertise and merchant silicon integration capabilities rather than proprietary ASIC development. Monitor co-packaged optics commercialization timelines as the critical inflection signal for platform refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Silicon Partnership | Direct Broadcom and Marvell allocation agreements bypass OEM channel markups for hyperscale operators. |
| Co-packaged Optics Integration | Silicon photonics convergence with switch ASICs reduces power-per-bit metrics for cloud infrastructure. |
| SONiC Platform Certification | Open-source network operating system compatibility unlocks programmable pipeline customization for elastic compute environments. |
| EU CSRD Compliance Investment | Verified Scope 3 emissions documentation secures procurement preference from German automotive and French pharmaceutical buyers. |
| Edge Computing Expansion | 5G base station switching deployments in India under TRAI allocations create distributed infrastructure demand outside traditional data centers. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings across the Ethernet switch value chain. Network engineering directors at hyperscale operators, procurement leads at financial services firms, channel sales executives at OEM vendors, and semiconductor product managers at merchant silicon suppliers provided operational perspectives. SEC 10-K filings, IEEE 802.3 standards documentation, FCC equipment authorization databases, and hyperscaler capital expenditure disclosures supplied quantitative benchmarks. Bottom-up port shipment estimates and top-down infrastructure spending analyses were reconciled through iterative triangulation.
Calibration against historical refresh cycle patterns and speed transition elasticities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, port speed tier, deployment context, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves for 100G, 400G, and 800G transitions, with specific weighting applied to China hyperscale buildout trajectories and India 5G edge deployment timelines.
Stress conditions across Taiwan foundry capacity constraints, IEEE 802.3 standards ratification delays, and power density limitations in legacy cooling infrastructure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about merchant silicon roadmap execution and hyperscale capital deployment continuity. Cross-checking against hyperscaler public infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Paralleling Switchgear Market
Switches
Global Switchgear Market
Switches
Optical Switches Market
Switches
Fixed Switch Cabinet Market
Switches
Smart Circuit Breaker Market
Switches
Membrane Switch Market
Switches
UK Reed Sensors Switches Market
Switches
Carrier Router Switch Market
Switches
Temperature and Pressure Switches Market
Switches
Analog Switches Market
Switches
Cross Point Switch Market
Switches
Canada Switch Gear Market
Switches
Low Voltage Switchgear Market
Switches
China Switchgear Market
Switches
Pressure Switch Market
Switches
Antenna Switch Module Market