
 China Furniture Market | 2026-2036
China Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
China Furniture Market Analysis
Dongguan is reconfiguring its furniture manufacturing footprint through automated panel-processing zones and design incubators. OPPEIN sustains vertical integration from particleboard production to finished cabinetry, controlling cost structures across its Guangdong base. Kuka Home dominates premium sofa exports through dedicated upholstery R&D centers in Hangzhou. QuanU leverages mass-market retail density, operating over two thousand branded stores across third and fourth-tier Chinese cities.
China furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically fabricated from engineered wood panels, metal tubing, or polymer composites using CNC routing, hot-press lamination, and robotic upholstery stitching for residential, commercial, and institutional environments. Wood material segments anchor the value chain through oak and walnut solid-wood dining sets commanding premium positioning, while metal frames in commercial office seating compete on durability specifications and recyclability credentials. Residential end users generate the dominant volume pool, though hospitality procurement for branded hotel chains is accelerating fastest as developers standardize room-fit specifications across property portfolios.
China's SAMR enforces GB standards for furniture structural safety and chemical emissions, with MEE oversight extending to factory-level VOC discharge permits that constrain lacquer-finishing capacity. The country's dual carbon goals are forcing manufacturers to substitute solvent-based coatings with waterborne alternatives, raising capital requirements for compliance. METI-equivalent provincial bureaus in Guangdong and Zhejiang are piloting digital product passport traceability for export-bound upholstery. Stakeholders must monitor whether GB standard revisions on flame-retardant additives will bifurcate domestic and export product lines.
Market Dynamics
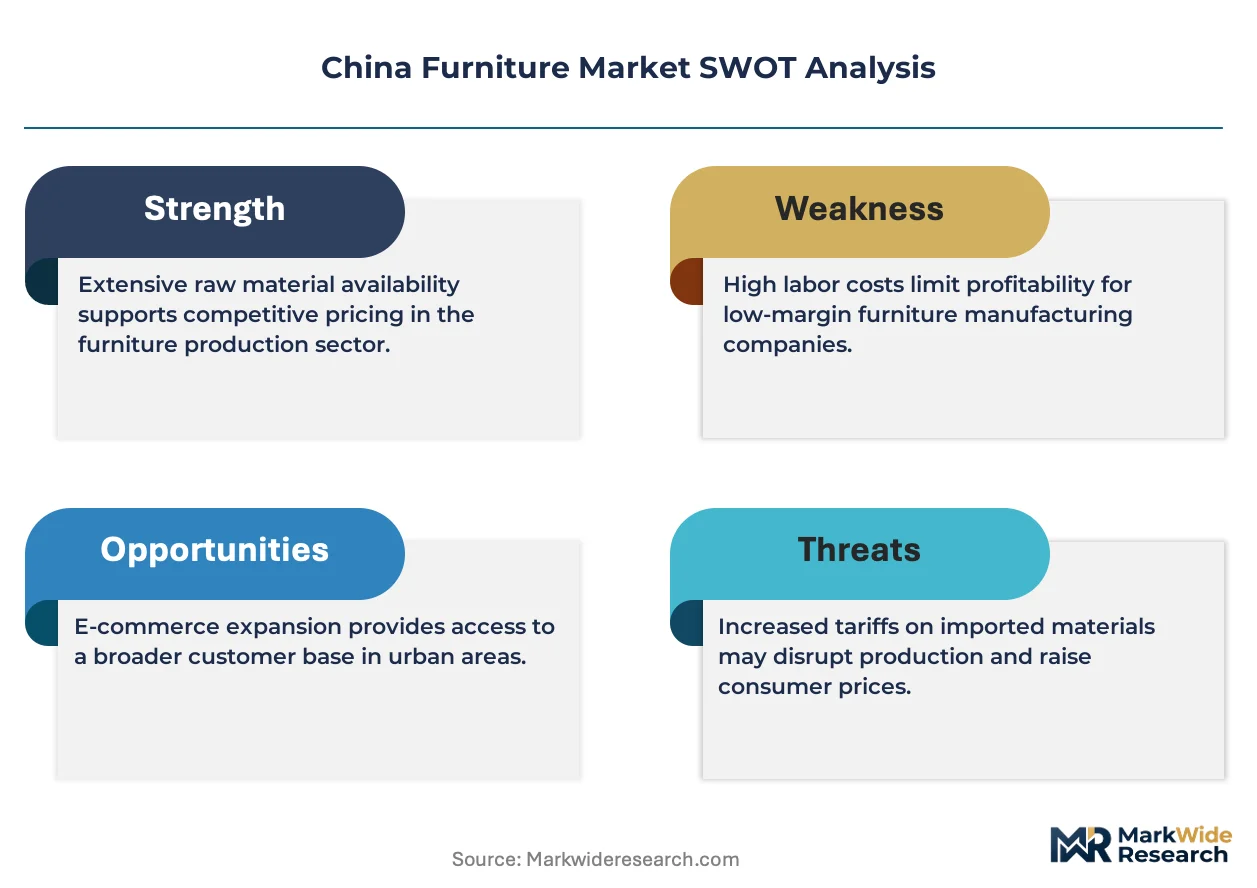
China's updated GB standards for formaldehyde emissions in wood-based panels are compressing finishing capacity and forcing solvent-to-waterborne coating transitions across the Yangtze River Delta manufacturing cluster.
Growth Catalysts
- Urban residential procurement:Tier-two cities are expanding modular living-room set orders as residential complexes standardize fit-out specifications.
- Dual carbon policy enforcement:MEE oversight of factory-level VOC discharge permits is accelerating waterborne coating adoption among export-oriented manufacturers.
- Hospitality vertical expansion:Branded hotel chains are standardizing room-fit specifications across property portfolios, creating volume pull for upholstered seating.
Market Restraints
- Input cost volatility:Oak and walnut solid-wood prices fluctuate with temperate forest harvest cycles, squeezing margin on premium dining sets.
- Supply concentration risk:Particleboard substrate production clusters heavily in Guangdong, creating exposure to regional logistics disruptions.
- Technical coating limitation:Waterborne lacquers still underperform solvent-based alternatives in scratch resistance for high-traffic commercial seating.
Strategic Opportunities
- Digital product passport traceability:METI-equivalent provincial bureaus in Guangdong and Zhejiang are piloting export-bound upholstery tracking systems.
- Third and fourth-tier city penetration:Mass-market retail density remains underdeveloped in inland provincial capitals beyond Chengdu and Xi'an.
- Flame-retardant additive bifurcation:Pending GB standard revisions may create parallel domestic and export product lines with differentiated certification requirements.
Industry Challenges
- CNC programming talent scarcity:Automated panel-processing zones in Dongguan face recruitment gaps for five-axis routing specialists.
- Capital intensity of compliance:Waterborne coating line retrofits require substantial capex for spray-booth ventilation and wastewater treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Furniture Market |
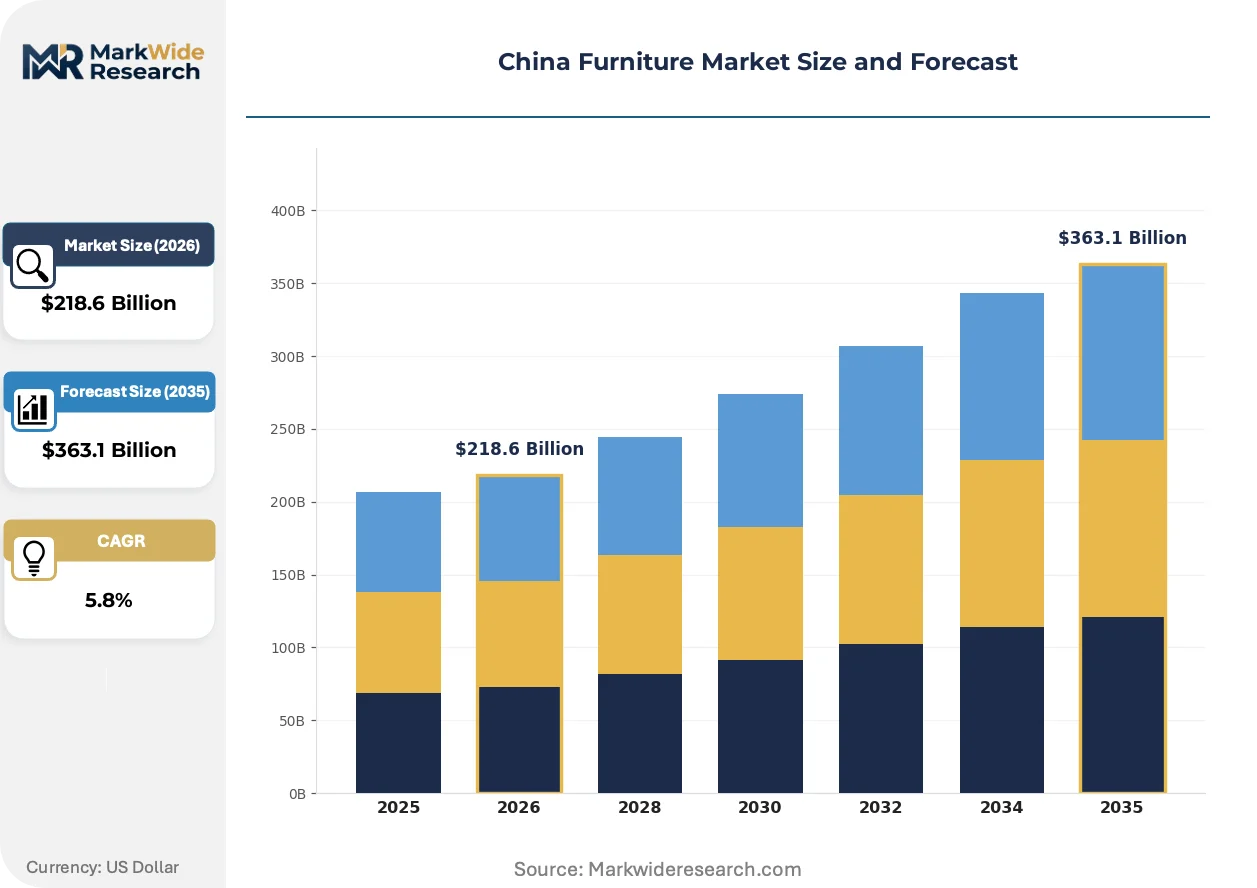
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $363.1 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Chairs, Cabinets Material: Wood, Metal, Plastic, Fabric End User: Residential, Commercial, Hospitality, Offices Distribution Channel: Online, Retail Stores, Wholesale, Distributors |
| Companies Covered | RedApple, M&Z Furniture, OPPEIN, ZUOYOU, Kuka Home, QuanU, Landbond, Shuangye, QM Furniture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Furniture Market Emerging Trajectories
Automation and regulatory digitization are restructuring how furniture moves from panel processing to finished goods, compressing traditional craftsmanship timelines while embedding compliance into production workflows.
Robotic upholstery stitching systems are digitizing the final assembly stage for premium sofa manufacturing. Dedicated R&D centers in Hangzhou are deploying computer-vision-guided needle positioning to reduce seam variance below two millimeters. This precision is digitizing quality consistency that previously required master craftspeople, enabling Hangzhou-based exporters to meet European retail chain specifications without manual rework.
GB standards revision processes are tightening formaldehyde emission thresholds for wood-based panels. SAMR enforcement is extending to factory-level batch testing rather than certificate-based compliance. Upholstery manufacturers serving hospitality procurement are responding by qualifying alternative particleboard suppliers with third-party SGS certification to preempt production halts.
Branded hotel chains are consolidating room-fit specifications into master procurement agreements with direct manufacturer relationships. Traditional furniture distributors in Shanghai and Jiangsu are losing volume to specification-driven sourcing teams embedded within property development groups. This consolidation is most visible in the Yangtze River Delta, where Marriott and Hilton franchise operators now issue unified tender documents across fifty-plus property developments annually.
China Furniture Market Segmentation
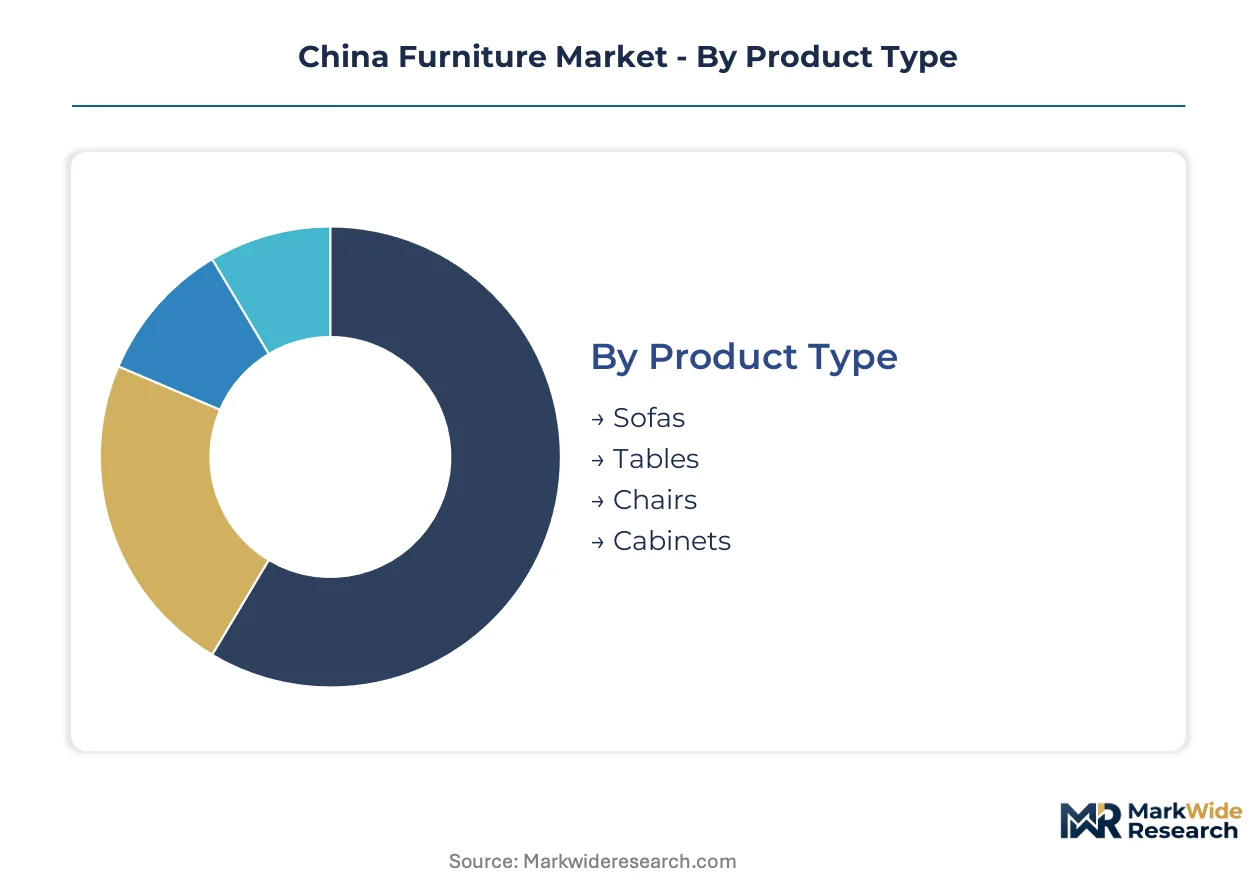
Segmentation reveals divergent replacement cycles across China's furniture market, with upholstered seating demanding refresh every 5-7 years while solid-wood dining sets persist across decades. Understanding these temporal patterns shapes inventory planning and margin capture strategies for manufacturers serving distinct buyer profiles.
Product Type:
Sofas turn inventory fastest among living-room categories, while cabinets lock capital longest through extended specification-to-delivery timelines.
- Sofas:Multi-density foam cores wrapped in synthetic or natural fiber upholstery dominate production volume. Hangzhou's dedicated R&D centers supply Marriott and Hilton franchise operators across the Yangtze River Delta with standardized room-fit specifications.
- Tables:Dining and conference surfaces fabricated from engineered wood panels or solid oak and walnut anchor premium positioning. Tier-two urban residential complexes are expanding procurement of modular sets as fit-out specifications standardize across new developments.
- Chairs:Metal-framed commercial seating competes on durability specifications and recyclability credentials for office environments. Waterborne coating transitions under MEE oversight are compressing finishing capacity for high-traffic applications.
- Cabinets:Particleboard-based storage systems from Guangdong producers face SAMR enforcement of GB formaldehyde emission standards. OPPEIN's vertical integration from substrate to finished goods controls cost structures amid compliance pressures.
Sofas anchor the volume base while cabinets gain share at the steepest rate as kitchen renovation cycles accelerate in third and fourth-tier cities.
Material:
Cost tier separation runs sharpest here, with solid hardwood commanding 3-4x particleboard price multiples and metal capturing commercial durability premiums.
- Wood:Oak and walnut solid-wood dining sets command premium positioning through temperate forest harvest cycles that introduce input cost volatility. Robotic CNC routing in Dongguan's automated panel-processing zones compresses craftsmanship timelines for engineered alternatives.
- Metal:Tubular steel and aluminum frames in commercial office seating compete on durability specifications and recyclability credentials. GB standard revisions on flame-retardant additives may bifurcate domestic and export product lines for metal-intensive categories.
- Plastic:Polymer composites serve mass-market outdoor and children's furniture segments with injection-molded production efficiency. QuanU's retail density across inland provincial capitals moves volume through price-accessible plastic-accented collections.
- Fabric:Natural and synthetic upholstery textiles undergo computer-vision-guided stitching in Hangzhou facilities to reduce seam variance below two millimeters. Digital product passport traceability pilots in Zhejiang target export-bound compliance documentation.
Wood materials capture the revenue concentration while fabric climbs the fastest as hospitality procurement standardizes upholstered specifications.
End User:
Application context determines specification intensity, with hospitality demanding fire-rated certifications that residential buyers rarely require.
- Residential:Urban residential complexes across tier-two cities drive modular living-room set orders through standardized fit-out specifications. Kuka Home dominates premium sofa exports through dedicated upholstery R&D centers serving this segment's quality expectations.
- Commercial:Office and retail environments prioritize metal-frame durability and waterborne coating compliance under MEE VOC discharge permit enforcement. Capital intensity of spray-booth ventilation upgrades constrains mid-tier manufacturer participation.
- Hospitality:Branded hotel chains consolidate room-fit specifications into master procurement agreements with direct manufacturer relationships. Traditional Shanghai and Jiangsu distributors lose volume to specification-driven sourcing teams embedded within property development groups.
- Offices:Post-pandemic workspace reconfigurations are accelerating ergonomic seating replacement cycles. Dual carbon goals force solvent-to-waterborne coating transitions that raise capital requirements for compliance.
Residential anchors the volume base while hospitality expands most quickly as developers standardize specifications across fifty-plus property developments annually.
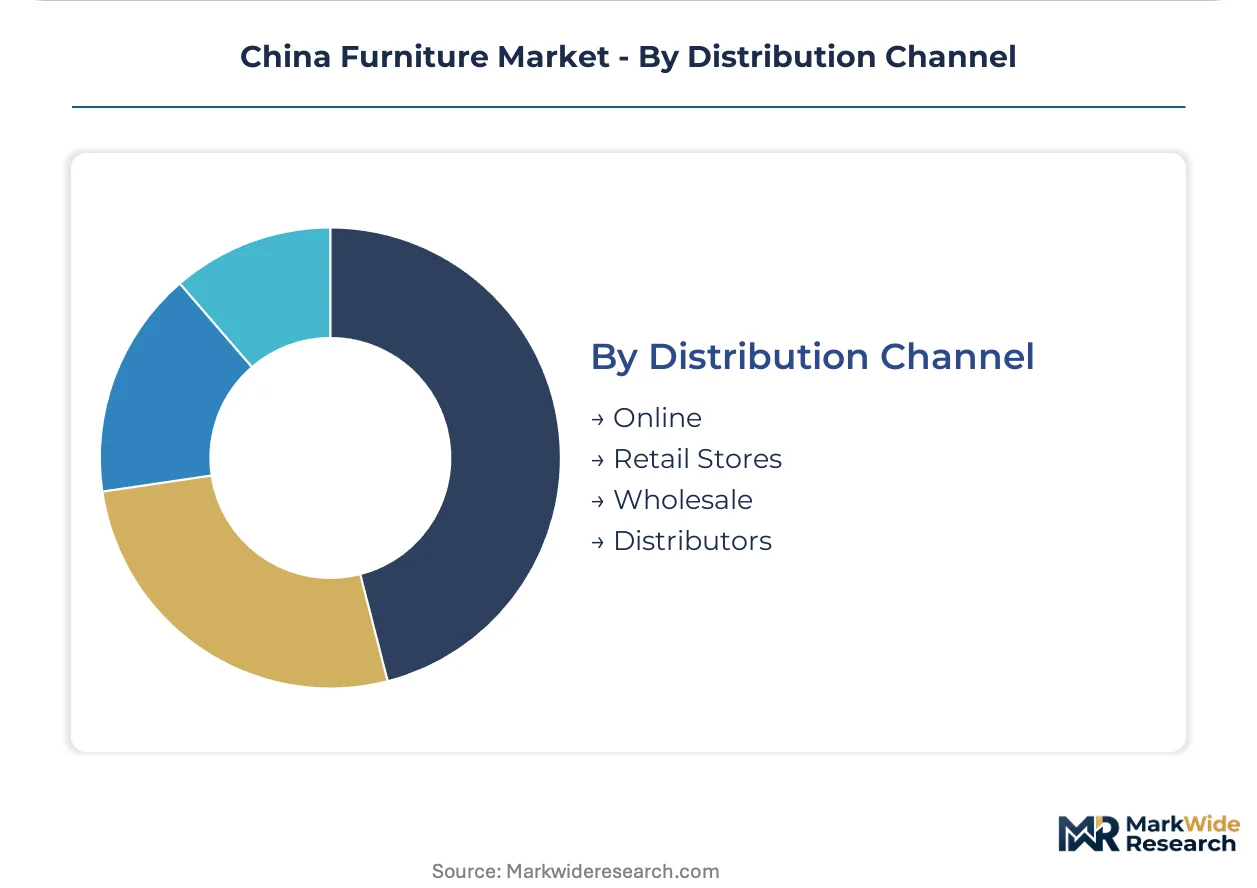
Distribution Channel:
Customer type separates channel preference, with project developers favoring direct manufacturer relationships while individual buyers fragment across touchpoints.
- Online:E-commerce platforms aggregate mass-market demand for flat-pack and ready-to-assemble furniture with compressed delivery timelines. Third and fourth-tier city penetration remains underdeveloped beyond Chengdu and Xi'an in this channel.
- Retail Stores:Branded showroom networks enable tactile evaluation of upholstery comfort and wood grain quality. QuanU operates over two thousand branded stores across inland provincial capitals to capture this preference.
- Wholesale:Volume aggregation for property developers and hotel chains bypasses retail markup through direct tender processes. Dongguan design incubators are reconfiguring manufacturing footprints to serve this procurement consolidation.
- Distributors:Traditional furniture distributors in Shanghai and Jiangsu face volume erosion as hospitality procurement consolidates. METI-equivalent provincial bureaus in Guangdong and Zhejiang are piloting digital traceability systems for export-bound upholstery flowing through this channel.
Retail stores anchor the volume base while wholesale gains share at the steepest rate as master procurement agreements consolidate developer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's deepwater port network at Ningbo-Zhoushan underwrites Shanghai's dominance in finished furniture exports, while high-speed rail freight corridors connect Pearl River Delta manufacturing to interior markets.
Guangdong Province
Dongguan's automated panel-processing zones absorb rising labor costs through robotic CNC routing systems. SAMR enforcement of updated GB formaldehyde standards is compressing finishing capacity among small-scale lacquer shops. OPPEIN's vertical integration from particleboard production to finished cabinetry anchors cost control in this manufacturing cluster.
Jiangsu Province
Suzhou's upholstery textile suppliers feed Shanghai hospitality procurement teams standardizing room-fit specifications across fifty-plus annual property developments. MEE oversight of VOC discharge permits is accelerating waterborne coating adoption among export-oriented manufacturers. Changzhou's metal-frame fabricators compete on durability specifications for commercial office seating.
Zhejiang Province
Hangzhou's dedicated R&D centers deploy computer-vision-guided stitching to reduce seam variance below two millimeters for premium sofa exports. METI-equivalent provincial bureaus pilot digital product passport traceability for export-bound upholstery. Ningbo's port infrastructure enables direct container loading for European retail chain specifications.
Sichuan-Chongqing
Chengdu anchors western China's furniture distribution, with mass-market retail density expanding into third and fourth-tier provincial capitals. Dual carbon policy enforcement is raising capital requirements for waterborne coating line retrofits among inland manufacturers. Chongqing's rail-river intermodal terminals reduce logistics costs for Yangtze River Delta-sourced components.
Shandong Peninsula
Qingdao's port facilities serve Korean and Japanese export markets with compressed transit times versus southern competitors. GB standard revisions on flame-retardant additives may bifurcate domestic and export product lines for manufacturers serving both markets. Yantai's engineered wood panel producers face input cost volatility from temperate forest harvest cycles.
China Furniture Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on material and fabrication competencies. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers controlling substrate-to-finished-goods cost structures, design-forward exporters capturing premium hospitality procurement, and mass-market retailers optimizing store density across inland cities. Consolidation pressures favor players with captive particleboard supply or direct developer relationships over traditional distributor-dependent models.
Among Guangdong-based fabricators, OPPEIN exemplifies the integrated-manufacturer archetype through captive particleboard production, while Hangzhou-centered Kuka Home occupies the premium-export tier serving standardized hospitality specifications. QuanU represents the mass-market retail density model with extensive branded store networks across interior provincial capitals. These three anchors illustrate how competitive positioning separates across cost control, specification compliance, and geographic penetration vectors.
| Leading Market Players |
|---|
| RedApple |
| M&Z Furniture |
| OPPEIN |
| ZUOYOU |
| Kuka Home |
| QuanU |
| Landbond |
| Shuangye |
| QM Furniture |
| Others |
Supply Flow & Price Mechanics
Ningbo-Zhoushan port freight corridors compress export logistics costs for Yangtze River Delta manufacturers while amplifying price differentiation between Guangdong particleboard clusters and Zhejiang upholstery specialists. This corridor dynamic concentrates supply-side bargaining power among vertically integrated producers controlling substrate-to-finished-goods flows, forcing price stratification across premium solid-wood dining sets, standard engineered-panel collections, and economy-grade particleboard furniture.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates oak and walnut solid-wood dining sets from engineered-panel alternatives and mass-market particleboard collections. Price differentiation rests on certification grade under GB formaldehyde emission standards and volume-scale procurement relationships with hospitality developers. Pricing pressure stems from MEE-mandated waterborne coating retrofits raising capital requirements for compliance. Mass-market retailers in third and fourth-tier cities exhibit highest price sensitivity, while hospitality procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Export-control regime limitations on VOC discharge permits under MEE oversight constrain lacquer-finishing capacity and compress supply availability for solvent-dependent manufacturers. Geographic supply concentration centers on China, with particleboard substrate production clustering heavily in Guangdong and upholstery fabrication anchoring in Zhejiang. Raw material dependencies draw from temperate oak and walnut harvest cycles, synthetic foam cores, and textile upholstery inputs. Single-source vulnerability runs through Guangdong particleboard concentration exposed to regional logistics disruptions. Distribution runs through wholesale master procurement agreements consolidating developer relationships and direct manufacturer channels bypassing traditional retail markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's furniture market fragments across compliance tiers, coating technologies, and geographic penetration depths, creating niches as hospitality procurement consolidates around standardized room-fit specifications while mass-market retail density remains underdeveloped in inland provincial capitals.
For Market Incumbents: Pre-empt margin compression from MEE waterborne coating mandates by accelerating captive particleboard supply integration and qualifying alternative substrate suppliers with third-party SGS certification. Defend positioning against emerging automated panel-processing entrants in Dongguan by embedding compliance documentation into production workflows before SAMR batch-testing enforcement tightens.
For New Entrants and Emerging Players: Mid-market hospitality upholstery in tier-two Yangtze River Delta cities represents the most penetrable entry point, with standardized Marriott and Hilton franchise specifications creating volume pull without brand premium requirements. Unbranded retail density gaps in Sichuan and Chongqing provincial capitals beyond Chengdu offer second-mover advantage through flat-pack e-commerce fulfillment. Target direct tender participation in property developer procurement teams rather than distributor-dependent channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned enterprise manufacturing divisions and family-owned Guangdong particleboard producers facing succession transitions without compliance capital reserves. Long-term viability favors assets with captive substrate supply or direct hospitality procurement relationships over distributor-dependent models. Monitor GB standard revision timing on flame-retardant additives as inflection indicator for parallel domestic-export product line bifurcation.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Coating Line Retrofit | MEE VOC permit compliance enables continued participation in export-bound hospitality procurement. |
| Digital Product Passport Implementation | METI-equivalent Zhejiang bureau pilots embed traceability for European retail chain specifications. |
| Automated Panel Processing Expansion | Dongguan robotic CNC zones compress craftsmanship timelines and reduce five-axis routing talent dependency. |
| Direct Developer Relationship Cultivation | Master procurement agreements with property development groups displace traditional Shanghai-Jiangsu distributors. |
| Inland Retail Network Penetration | Third and fourth-tier city store density captures mass-market preference for tactile upholstery evaluation. |
Methodological Framework
Initial hypotheses were tested against primary input from furniture manufacturing executives, hospitality procurement directors, coating technology specialists, and retail channel managers and refined through secondary validation against SAMR regulatory filings, MEE discharge permit databases, customs export records, and provincial industrial cluster reports. Bottom-up demand modeling across residential, commercial, hospitality, and office end-use segments was triangulated with top-down value chain analysis of particleboard substrate, upholstery textile, and metal frame component flows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material composition, end-use application, and distribution channel. CAGRs were derived from installed base replacement cycles, new construction fit-out specifications, and hospitality property development pipelines. Forecast inputs incorporated GB standard revision schedules, dual carbon policy enforcement trajectories, and waterborne coating technology adoption curves.
Practitioners should monitor SAMR formaldehyde threshold adjustments, MEE VOC permit allocation changes, and hospitality developer consolidation patterns for early signals of forecast deviation. Forecasts reflect assumptions regarding continued enforcement of existing regulatory frameworks and stable temperate forest harvest cycles. Material shifts in GB flame-retardant additive requirements or Pearl River Delta logistics disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Portering Chair Market
Furniture
Ergonomic Chair for Children Market
Furniture
Global Multifunctional Home Furniture Market
Furniture
Spain Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Vietnam Home Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
Global Multifunctional Furniture Market
Furniture
North America Smart Furniture Market
Furniture
Kids Storage Furniture Market
Furniture
Kids and Nursery Furniture Market
Furniture
United States Home Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
High End Furnitures Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Children Furniture Market