
 Treasury and Risk Management Market | 2026-2036
Treasury and Risk Management Market Size, Share, and Industry Trends Forecast 2026-2036
Treasury and Risk Management Market Analysis
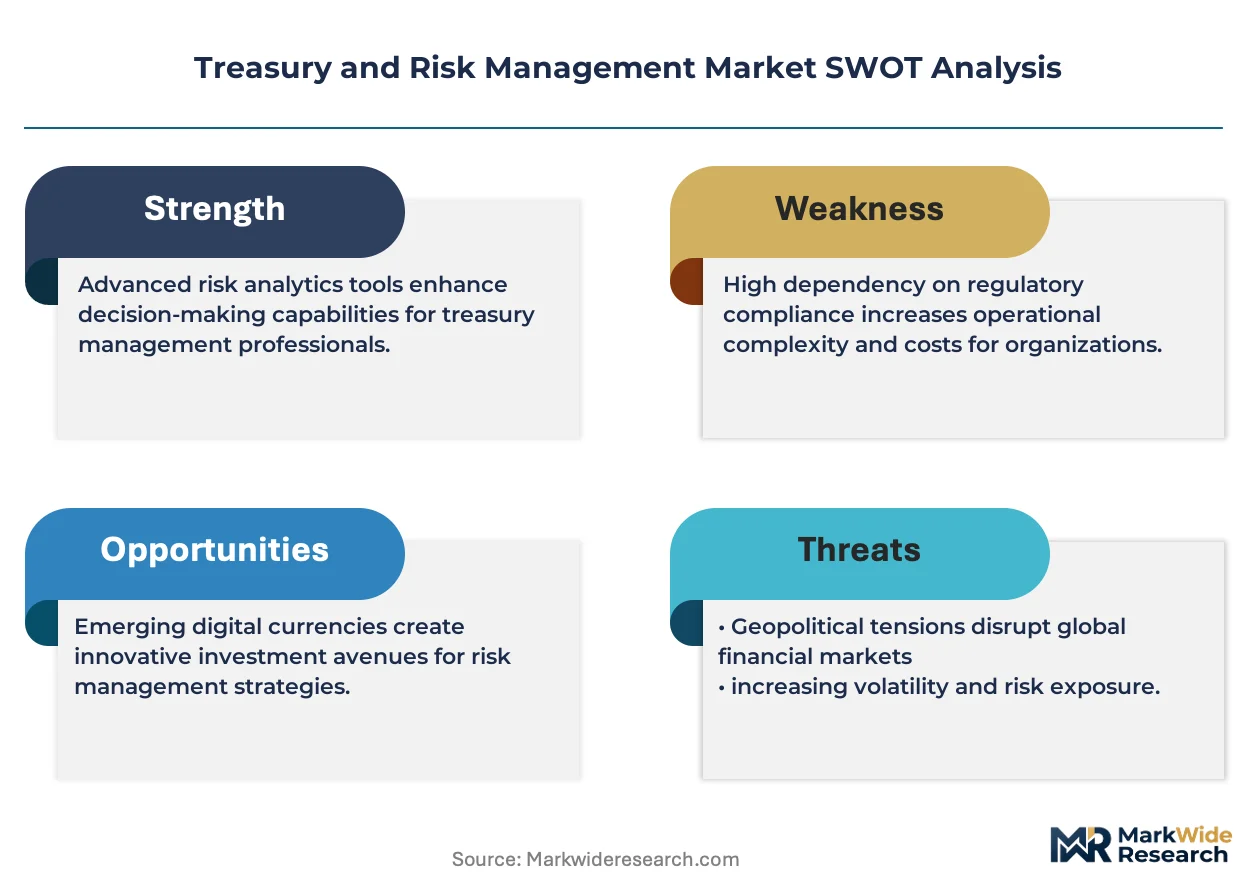
Basel III liquidity coverage ratio mandates are recalibrating the cost-of-entry calculus for treasury technology vendors. SAP leverages its embedded ERP footprint to anchor treasury workflows inside broader financial operations. Kyriba specializes in multi-bank connectivity and API-driven cash visibility, competing against legacy SWIFT-dependent architectures. Nasdaq Financial Technology sustains technology leadership in real-time risk analytics for sell-side institutions.
Treasury and risk management encompasses software platforms, data infrastructure, and advisory services that monitor cash positions, hedge currency and interest rate exposures, and ensure regulatory compliance across multinational operations. These systems integrate real-time bank feeds, Monte Carlo simulations for value-at-risk, and automated hedge accounting to reduce manual reconciliation errors and regulatory penalties. Cloud-based deployment now leads adoption curves as corporate treasurers demand elastic scalability without capital-intensive infrastructure commitments, while SaaS pricing models concentrate margin pools among vendors with multi-tenant architectures. Liquidity management solutions represent the fastest-growing solution segment as zero-interest-rate environments have ended and working capital optimization has regained strategic priority.
The European Banking Authority's prudential requirements and the US Federal Reserve's stress testing frameworks shape product standards by mandating auditable risk measurement and reporting capabilities. FINRA examination priorities and SEC disclosure rules further tighten compliance obligations for investment banks and hedge funds operating across jurisdictions. ISO 20022 migration timelines are forcing infrastructure upgrades that ripple through vendor roadmaps and buyer procurement cycles. Stakeholders must monitor whether regional regulatory divergence fragments platform development or creates consolidation opportunities for vendors with cross-border certification depth.
Market Dynamics
Cloud-native treasury platforms are absorbing workloads from legacy on-premise installations as corporate treasurers prioritize elastic scalability over capital-intensive infrastructure commitments. This architectural shift compresses vendor margins for single-tenant providers while concentrating margin pools among multi-tenant SaaS operators.
Growth Catalysts
- Basel III Liquidity Coverage Ratio:The prudential framework mandates real-time cash visibility and stress-testing capabilities, forcing banks to upgrade treasury infrastructure and creating downstream demand for integrated risk analytics platforms.
- API-First Architectures:Open banking standards and ISO 20022 migration timelines are accelerating multi-bank connectivity projects, displacing legacy SWIFT-dependent message formats with real-time data feeds.
- Singapore Hub Formation:Regional treasury center migration to Singapore concentrates demand for cross-border liquidity management solutions serving Asia-Pacific manufacturing operations.
Market Restraints
- Implementation Cost Concentration:Enterprise-grade treasury transformation projects require substantial professional services expenditure, compressing ROI timelines for mid-market manufacturers with limited IT budgets.
- Data Sovereignty Fragmentation:Divergent national requirements for financial data residency create architectural complexity for cloud deployments spanning Germany, the United States, and Singapore simultaneously.
- Legacy System Entrenchment:Deep ERP integration with decades-old general ledger systems creates switching friction that extends procurement cycles beyond typical SaaS sales timelines.
Strategic Opportunities
- Embedded Finance Convergence:Treasury functionality is absorbing into broader ERP and banking-as-a-service platforms, creating white space for API-native vendors to serve mid-market manufacturers without standalone procurement.
- ESG Reporting Integration:The EU Corporate Sustainability Reporting Directive mandates auditable sustainability disclosures that treasury systems must support through carbon-adjusted cash forecasting and green liquidity metrics.
- India Manufacturing Expansion:Production-linked incentive schemes are attracting multinational manufacturers establishing regional treasury operations requiring rupee-denominated hedging and working capital optimization tools.
Industry Challenges
- Quantitative Talent Scarcity:Treasury technology vendors face acute shortages of professionals combining derivatives pricing expertise with cloud engineering capabilities, elongating product development timelines.
- Regulatory Certification Lag:ISO 20022 compliance validation across multiple national payment infrastructures creates bottlenecks that delay go-live dates for real-time liquidity platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treasury and Risk Management Market |
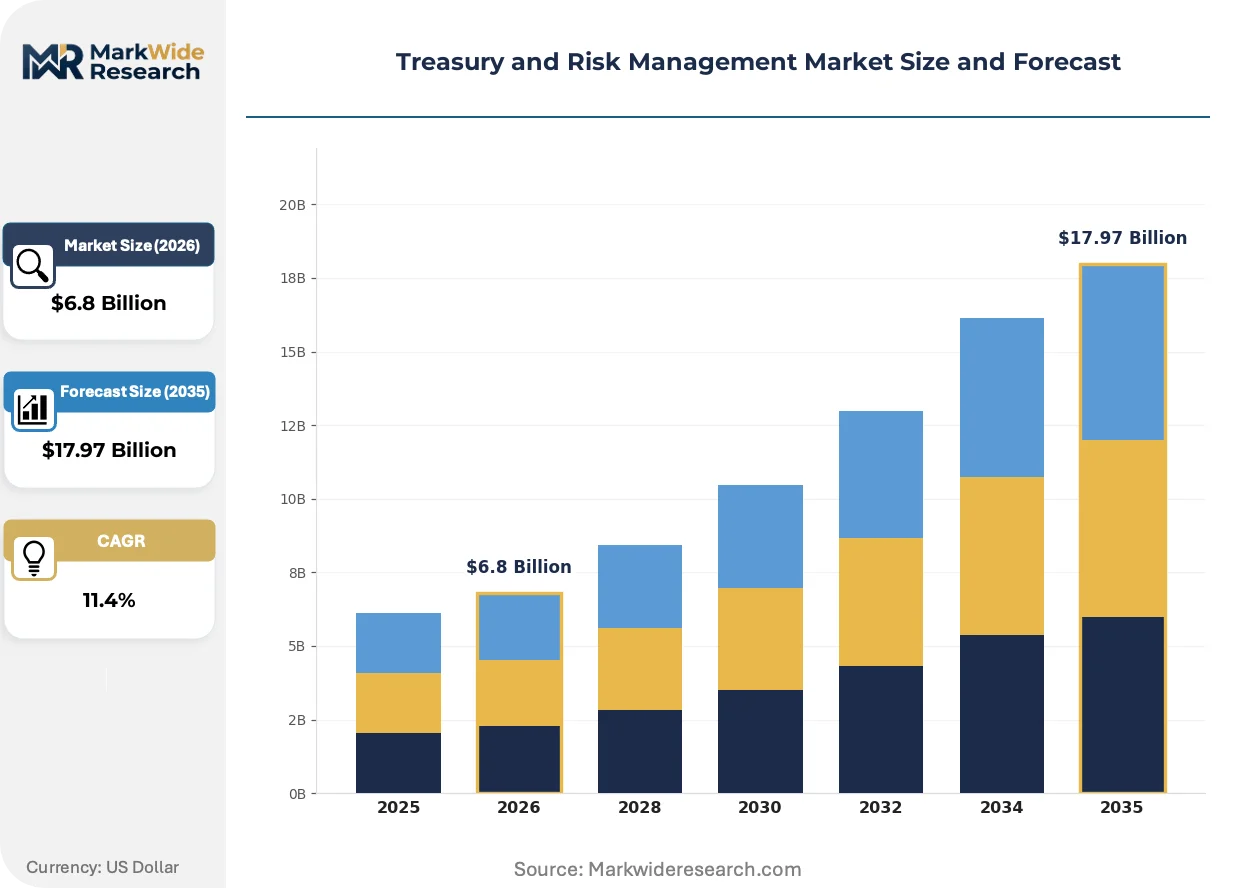
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cash Management, Currency Risk, Credit Risk, Liquidity Management Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Corporate Treasurers, Investment Banks, Financial Institutions, Hedge Funds Service Type: Consulting, Software Development, Compliance Services, Managed Services |
| Companies Covered | ION Group, Nasdaq Financial Technology, SAP, FIS Global, SS&C Technologies, GTreasury, Kyriba, Finastra, Coupa Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treasury and Risk Management Market Emerging Trajectories
Artificial intelligence is penetrating core treasury workflows, compressing decision cycles for cash positioning and risk measurement while forcing architectural redesigns of platforms built on deterministic rule engines. These shifts are redrawing competitive boundaries between specialized treasury vendors and broader financial technology suites.
Machine learning models for cash flow forecasting are absorbing variance analysis and scenario simulation tasks previously handled by spreadsheet-based treasury workstations. Corporate treasurers at capital-intensive manufacturers are deploying these tools to reduce forecasting error rates and optimize liquidity buffers. The technology is absorbing margin from traditional treasury management system providers unable to embed predictive capabilities natively.
The European Banking Authority's prudential requirements for internal liquidity adequacy assessment are mandating granular cash flow categorization and stress-testing documentation. Banks operating across EU jurisdictions must upgrade data infrastructure to support 30-day liquidity coverage calculations under supervisory scrutiny. Sell-side institutions are responding by consolidating vendor relationships with platforms offering pre-validated regulatory reporting modules.
Subscription pricing models are displacing perpetual license structures across the buyer base, compressing upfront revenue recognition and forcing vendors to restructure professional services delivery. Mid-market manufacturers in Germany and the United States are driving this transition, prioritizing operational expenditure treatment over capital allocation. Procurement teams now evaluate total cost of ownership across three-to-five-year horizons rather than initial license fees.
Treasury and Risk Management Market Segmentation
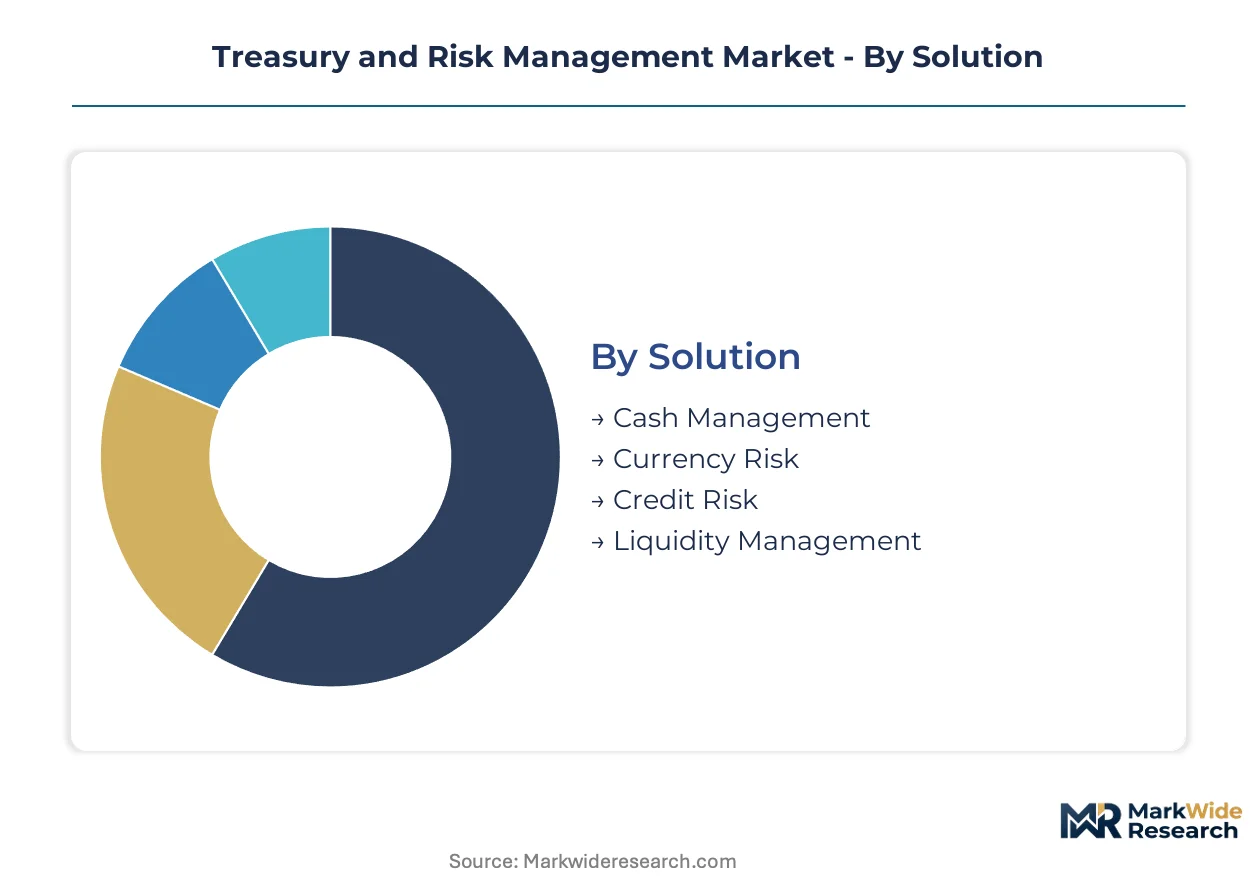
Treasury and risk management technology vendors structure product portfolios around distinct buyer workflows and infrastructure constraints. Procurement patterns diverge sharply between capital-intensive manufacturers prioritizing liquidity optimization and sell-side institutions demanding real-time risk analytics.
Solution:
Corporate treasurers select modules based on regulatory pressure intensity and working capital complexity rather than bundled suite economics.
- Liquidity Management:Real-time cash positioning tools aggregate multi-bank balances through API connectivity, replacing spreadsheet-based forecasting. Demand concentrates among United States-based multinational manufacturers navigating post-zero-interest-rate working capital optimization. Basel III liquidity coverage ratio mandates force banks to upgrade stress-testing infrastructure, creating downstream vendor opportunities.
- Currency Risk:Automated hedge accounting and Monte Carlo simulation engines reduce manual reconciliation errors for cross-border operations. Singapore-based regional treasury centers drive adoption as Asia-Pacific manufacturing footprints expand and rupee-denominated hedging requirements intensify.
- Cash Management:Bank feed integration and reconciliation automation serve mid-market manufacturers with limited IT budgets.
- Credit Risk:Counterparty exposure monitoring and collateral management tools address sell-side institution requirements.
Volume sits with Cash Management; growth tilts toward Liquidity Management.
Deployment:
Infrastructure architecture decisions hinge on data sovereignty requirements and capital expenditure treatment preferences across procurement cycles.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic scalability without capital-intensive infrastructure commitments, compressing vendor margins for single-tenant providers. Germany-based manufacturers prioritize operational expenditure treatment, accelerating subscription pricing displacement of perpetual licenses.
- SaaS:Subscription models concentrate margin pools among vendors with pre-validated regulatory reporting modules and ISO 20022 compliance. United States corporate treasurers evaluate total cost of ownership across three-to-five-year horizons rather than initial license fees.
- Hybrid:Split deployments address data residency fragmentation across Germany, the United States, and Singapore simultaneously.
- On-Premises:Legacy installations persist where deep ERP integration with decades-old general ledger systems creates switching friction.
Revenue concentrates in Cloud-Based; expansion is steepest in SaaS.
End User:
Buyer sophistication and regulatory scrutiny levels determine platform complexity requirements and professional services intensity.
- Corporate Treasurers:Capital-intensive manufacturers deploy integrated liquidity and risk platforms to optimize working capital across dispersed operations. United States and Germany anchor demand as regional treasury hub formation accelerates and ESG reporting integration mandates tighten.
- Investment Banks:Real-time risk analytics and stress-testing documentation requirements drive vendor consolidation toward platforms with pre-validated regulatory modules. SEC disclosure rules and FINRA examination priorities tighten compliance obligations.
- Financial Institutions:Basel III mandates force infrastructure upgrades supporting 30-day liquidity coverage calculations.
- Hedge Funds:Cross-jurisdiction operations require auditable risk measurement capabilities spanning multiple national payment infrastructures.
Deployment scale favors Corporate Treasurers; complexity premiums align with Investment Banks.
Service Type:
Services attach rates vary with implementation complexity and ongoing regulatory certification requirements.
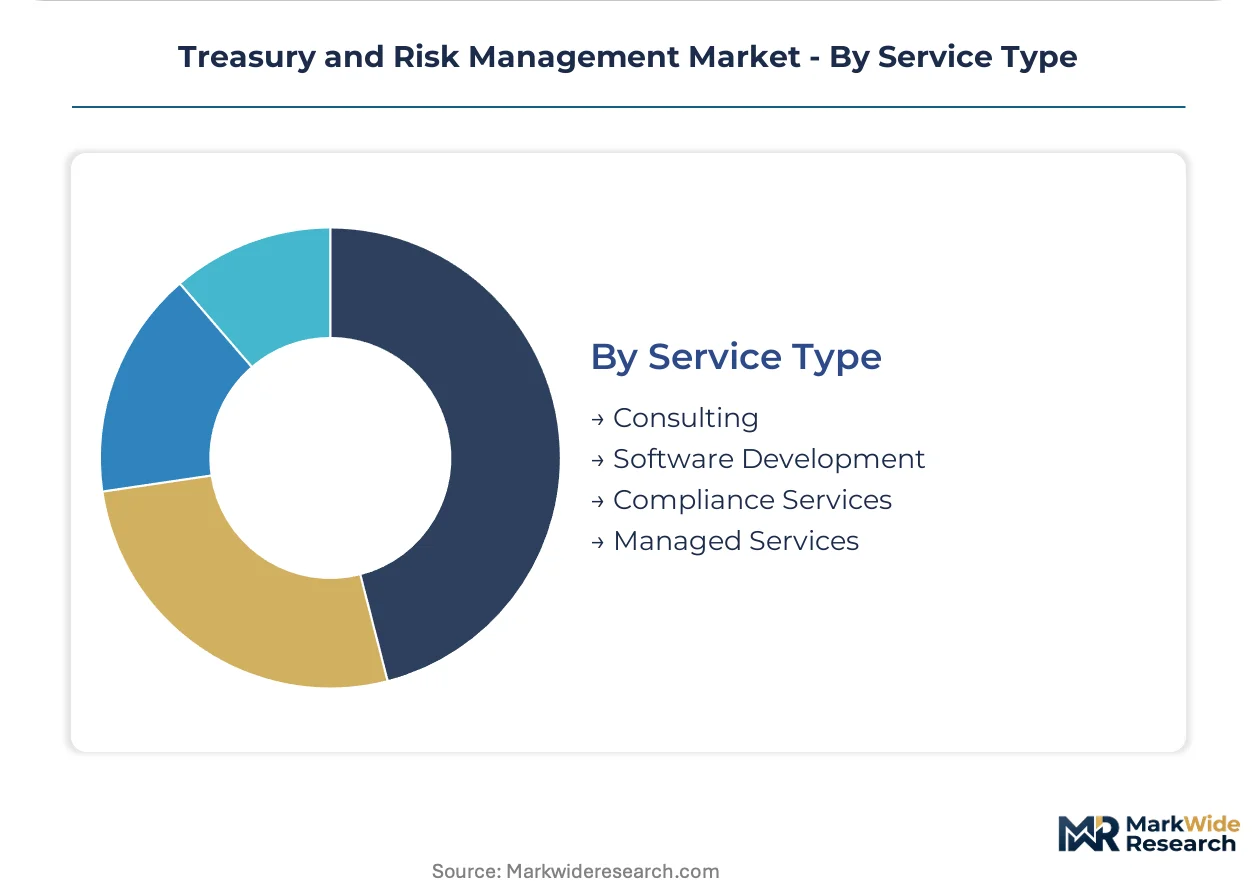
- Managed Services:Outsourced treasury operations absorb variance analysis and scenario simulation tasks previously handled internally. Singapore and India manufacturing expansion creates demand for rupee-denominated hedging expertise without captive talent investment.
- Compliance Services:ISO 20022 migration timelines and EU Corporate Sustainability Reporting Directive mandates force infrastructure upgrades with auditable documentation requirements. Validation bottlenecks across multiple national payment infrastructures elongate procurement cycles.
- Consulting:Treasury transformation projects require substantial professional services expenditure, compressing ROI timelines for mid-market buyers.
- Software Development:Custom integration with legacy ERP systems extends implementation timelines beyond typical SaaS sales cycles.
Attach rates are highest in Managed Services; margin expansion concentrates in Compliance Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Asia-Pacific regional treasury hub incentives concentrate multinational liquidity management demand, while Basel III implementation timelines across the United States, Germany, and Singapore reshape infrastructure procurement patterns.
United States
Corporate treasurers at capital-intensive manufacturers drive cloud-native platform adoption for real-time cash visibility. SEC disclosure rules and Federal Reserve stress testing frameworks mandate auditable risk measurement capabilities. New York and Chicago financial centers anchor sell-side institution procurement of integrated risk analytics.
Germany
Mid-market manufacturers prioritize operational expenditure treatment through SaaS subscription models over perpetual licenses. The European Banking Authority's prudential requirements for internal liquidity adequacy assessment force granular cash flow categorization. Frankfurt's banking cluster concentrates vendor relationships with pre-validated regulatory reporting modules.
Singapore
Regional treasury center migration concentrates demand for cross-border liquidity management serving Asia-Pacific manufacturing operations. Monetary Authority of Singapore payment infrastructure standards accelerate ISO 20022 migration timelines. The city-state's hub status attracts rupee-denominated hedging and working capital optimization requirements from India manufacturing expansion.
India
Production-linked incentive schemes attract multinational manufacturers establishing captive treasury operations requiring localized hedging instruments. RBI guidelines on foreign exchange management shape platform compliance requirements. Mumbai and Bangalore financial centers develop specialized managed services capabilities for outsourced treasury operations.
United Kingdom
Post-Brexit regulatory divergence creates demand for platforms with cross-border certification depth spanning EU and UK jurisdictions. Prudential Regulation Authority liquidity standards maintain alignment with Basel III frameworks. London's sell-side concentration sustains procurement of real-time risk analytics for investment banking operations.
Treasury and Risk Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment architectures and regulatory certification depth. The vendor base stratifies between ERP-embedded platforms and standalone treasury suites. Three archetypes dominate: enterprise software conglomerates leveraging existing customer relationships, cloud-native specialists driving API-first connectivity, and financial infrastructure providers with pre-validated compliance modules. Competitive moves concentrate on strategic partnerships for ISO 20022 certification acceleration and portfolio diversification into ESG reporting integration.
Within the cloud-native specialist tier, Kyriba and GTreasury exemplify API-first architectures displacing legacy SWIFT-dependent message formats. SAP anchors the ERP-embedded archetype, leveraging existing customer footprints to anchor treasury workflows inside broader financial operations. Nasdaq Financial Technology occupies a position among financial infrastructure providers with real-time risk analytics capabilities for sell-side institutions.
| Leading Market Players |
|---|
| ION Group |
| Nasdaq Financial Technology |
| SAP |
| FIS Global |
| SS&C Technologies |
| GTreasury |
| Kyriba |
| Finastra |
| Coupa Software |
| Others |
Supply Flow & Price Mechanics
SaaS subscription mandates from United States corporate treasurers are compressing vendor margins and forcing infrastructure providers toward multi-tenant architectures that sacrifice customization depth for operational expenditure treatment.
Pricing Analysis
Short lead-time deployments command premium pricing from mid-market manufacturers facing Basel III compliance deadlines, while spot inventory of pre-certified modules trades at discounts. Three-tier pricing structure across premium, standard, and economy levels segments buyers by regulatory complexity and integration depth. Price differentiation rests on ISO 20022 certification status and multi-bank API connectivity density. Cost compression in the economy tier is intensifying because cloud-native specialists are absorbing market share from legacy SWIFT-dependent providers. Mid-market manufacturers in Germany exhibit highest price sensitivity due to elongated ROI timelines; investment banks in New York show lowest sensitivity given regulatory penalty exposure.
Supply Chain Analysis
Dual-sourcing requirements from United States and German corporate treasurers mandate multi-vendor qualification for API connectivity infrastructure and stress-testing modules, fragmenting procurement across cloud-native specialists and ERP-embedded platforms. Supply concentrates in the United States, Germany, and Singapore as regional treasury hub formation accelerates. The vendor ecosystem draws from specialized quant talent pools, hyperscaler compute infrastructure, and pre-validated regulatory reporting libraries. Single-source vulnerability sits with ISO 20022 certification bottlenecks across multiple national payment infrastructures. Distribution runs through direct enterprise sales teams, systems integrators, and banking-as-a-service platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: Basel III liquidity coverage ratio mandates create a barrier-to-entry moat for vendors with pre-validated regulatory reporting modules, freezing out undercapitalized entrants.
For Market Incumbents: Anchor multi-tenant SaaS architectures with elastic scalability to defend against cloud-native specialists absorbing mid-market share. Deepen backward integration into API connectivity infrastructure to reduce hyperscaler dependency. Prioritize ISO 20022 certification acceleration across Singapore and Germany payment infrastructures to extend regulatory moat duration. For New Entrants and Emerging Players: EU Corporate Sustainability Reporting Directive in Germany opens a window for ESG-integrated treasury modules targeting mid-market manufacturers with carbon-adjusted cash forecasting requirements. White space sits with rupee-denominated hedging tools for India manufacturing expansion and outsourced treasury operations for Singapore regional hub migration. Go-to-market through embedded finance partnerships with ERP and banking-as-a-service platforms bypasses standalone procurement friction. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native specialists given API-first architecture displacement of legacy SWIFT-dependent message formats. Long-term viability favors vendors combining multi-tenant SaaS delivery with pre-validated compliance modules across United States, Germany, and Singapore jurisdictions. Signal to watch: consolidation velocity among mid-tier vendors unable to fund ISO 20022 certification across multiple national payment infrastructures.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Certification Acceleration | Pre-validated modules across United States, Germany, and Singapore payment infrastructures compress competitor entry timelines. |
| API-First Architecture Migration | Real-time multi-bank connectivity displaces legacy SWIFT-dependent message formats for corporate treasury operations. |
| ESG Reporting Integration | Carbon-adjusted cash forecasting aligns with EU Corporate Sustainability Reporting Directive mandates for German manufacturers. |
| India Market Entry | Rupee-denominated hedging tools capture production-linked incentive scheme treasury demand from multinational manufacturers. |
| Managed Services Expansion | Outsourced treasury operations absorb variance analysis tasks without captive talent investment from Singapore hub migrants. |
Methodological Framework
Multi-period observation of vendor pricing migrations, API connectivity deployment timelines, and regulatory certification bottlenecks anchored the trend analysis, supplemented by interviews with corporate treasury directors, cloud platform engineers, regulatory compliance officers, and banking-as-a-service partnership leads. Secondary validation drew from SEC filings, European Banking Authority prudential requirement updates, Monetary Authority of Singapore payment infrastructure standards, and ISO 20022 migration timeline disclosures. Bottom-up segment sizing triangulated against top-down market boundary analysis.
The input-output matrix framed demand-side procurement patterns against supply-side certification capacity constraints across deployment models, solution modules, end-user sophistication tiers, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure upgrade cycle analysis. Forecast inputs incorporated Basel III implementation timelines, cloud migration velocity at multinational manufacturers, and ESG reporting mandate enforcement intensity.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence penetration into cash flow forecasting would alter the outlook for traditional treasury management system displacement velocity. Deviation in ISO 20022 certification validation timelines across national payment infrastructures would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Risk Management and Compliance
Global Strategy Consulting Market
Risk Management and Compliance
Clinical Risk Grouping Solutions Market
Risk Management and Compliance
Global Compliance Management Software Market
Risk Management and Compliance
Fraud Detection and Prevention (FDP) Market
Risk Management and Compliance
Global Management Decision Market
Risk Management and Compliance
BFSI Crisis Management Market
Risk Management and Compliance
Europe Strategy Consulting Market
Risk Management and Compliance
Treasury and Risk Management Application Market
Risk Management and Compliance
Certificates Market
Risk Management and Compliance
United States Strategic Consulting Services Market
Risk Management and Compliance
Risk Analytics Market
Risk Management and Compliance
Europe Sustainable Finance Market
Risk Management and Compliance
BFSI Security Market
Risk Management and Compliance
Vendor Risk Management Market
Risk Management and Compliance
Revenue Assurance Market
Risk Management and Compliance
Global Risk and Compliance Consulting Services Market