
 Artificial Intelligence As a Service Market | 2026-2036
Artificial Intelligence As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence As a Service Market Intelligence
Mid-market enterprises is bifurcating from large-cap technology buyers as the fastest-growing procurement segment for managed AI infrastructure. Amazon Web Services leverages its hyperscale data center footprint to dominate enterprise-grade GPU provisioning. Microsoft anchors its position through deep integration with productivity software workflows. Google specializes in pre-trained large language models accessible through standardized API endpoints.
Artificial Intelligence As a Service denotes the cloud-hosted delivery of machine learning inference, model training, and data analytics capabilities through subscription or usage-based pricing, typically provisioned via REST APIs or containerized microservices running on virtualized GPU clusters. The primary commercial purpose is to democratize access to computationally intensive AI capabilities without requiring capital expenditure on specialized hardware or in-house ML engineering teams. Public cloud deployment captures the dominant revenue share due to elastic scalability and minimal upfront commitment, while hybrid cloud configurations are gaining traction among BFSI and healthcare end users with stringent data residency mandates. Natural language processing solutions command premium pricing relative to predictive analytics, reflecting higher computational requirements and scarcer specialized talent.
The EU AI Act imposes risk-tiered compliance obligations on providers of high-stakes AI systems, directly affecting product architecture decisions and market access conditions for services deployed across European member states. The FDA maintains active oversight of AI-enabled medical devices, creating a dual-track regulatory environment that healthcare-focused vendors must navigate. ISO and IEC standards for AI risk management are converging toward de facto baseline requirements for enterprise procurement. Stakeholders must monitor evolving liability frameworks governing automated decision-making to anticipate shifts in vendor accountability and insurance structures.
Market Dynamics
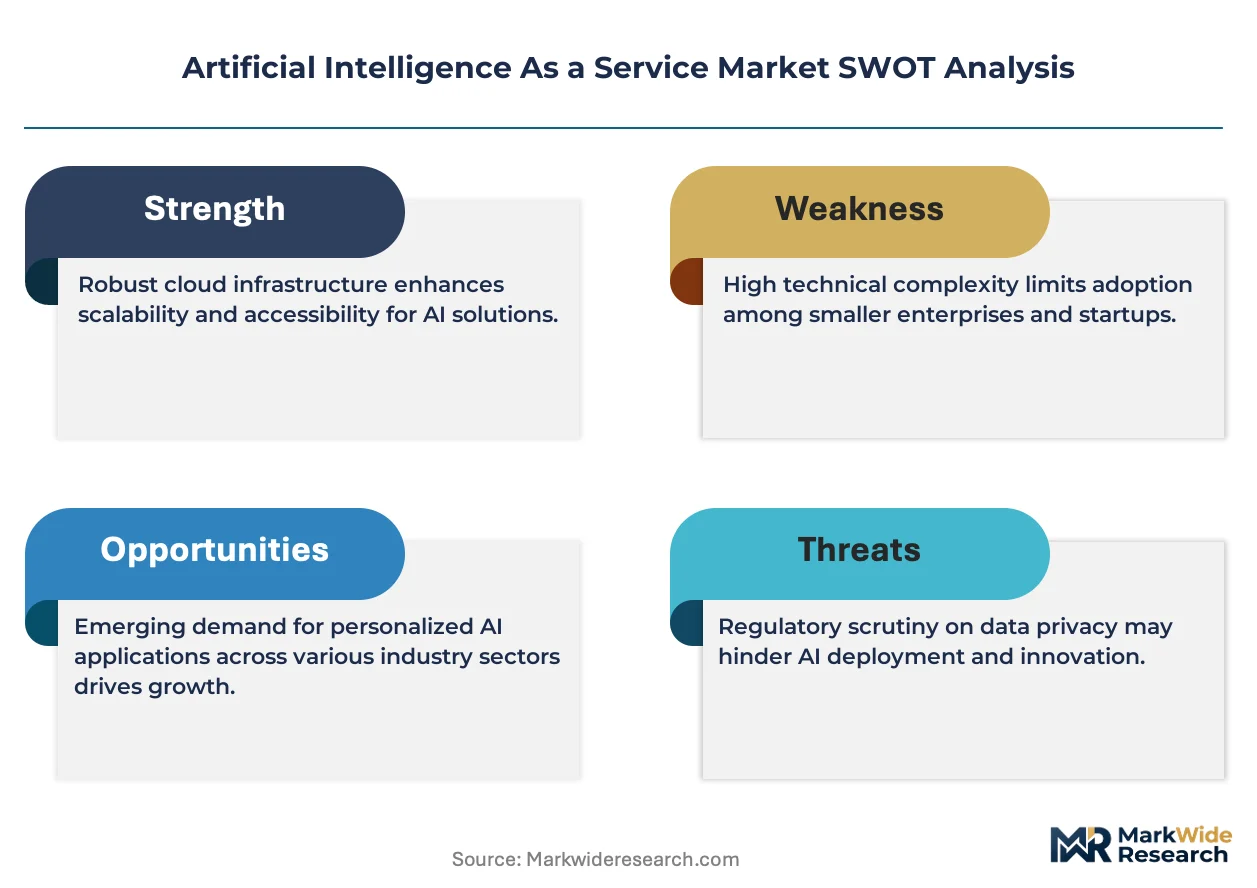
Hyperscaler concentration in GPU cloud infrastructure is compressing margins for independent AI service providers while accelerating commoditization of base inference workloads. This supply-side consolidation forces mid-market vendors toward specialized vertical applications or proprietary model architectures to escape price competition.
Growth Catalysts
- EU AI Act compliance mandates:Risk-tiered obligations for high-stakes AI systems are generating managed compliance service revenue streams across European member states.
- Healthcare diagnostic imaging:FDA-cleared algorithms for radiology and pathology are expanding reimbursable AI-assisted interpretation into community hospital networks.
- Generative API standardization:REST endpoint normalization is lowering integration friction for enterprise developers without machine learning expertise.
Market Restraints
- NVIDIA GPU supply concentration:Foundry capacity constraints at TSMC limit accelerator availability, creating allocation bottlenecks for training-intensive workloads.
- Energy cost volatility:Data center power consumption for large model training faces input cost pressure from regional electricity market fluctuations.
- Cross-border data localization:China's Cybersecurity Law and EU GDPR divergence fragment training dataset assembly across jurisdictional boundaries.
Strategic Opportunities
- German Mittelstand manufacturing:Quality inspection and predictive maintenance AI services remain underpenetrated among mid-sized industrial exporters.
- Edge inference deployment:Containerized model serving on factory-floor hardware converges 5G connectivity with localized GPU acceleration.
- US Inflation Reduction Act incentives:Domestic clean energy manufacturing investments are stimulating demand for supply chain optimization AI.
Industry Challenges
- MLOps engineering scarcity:Production-grade model monitoring and drift detection expertise commands premium compensation, constraining service scalability.
- ISO 42001 certification timelines:AI management system audits require 12-18 month implementation cycles, delaying enterprise procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence As a Service Market |
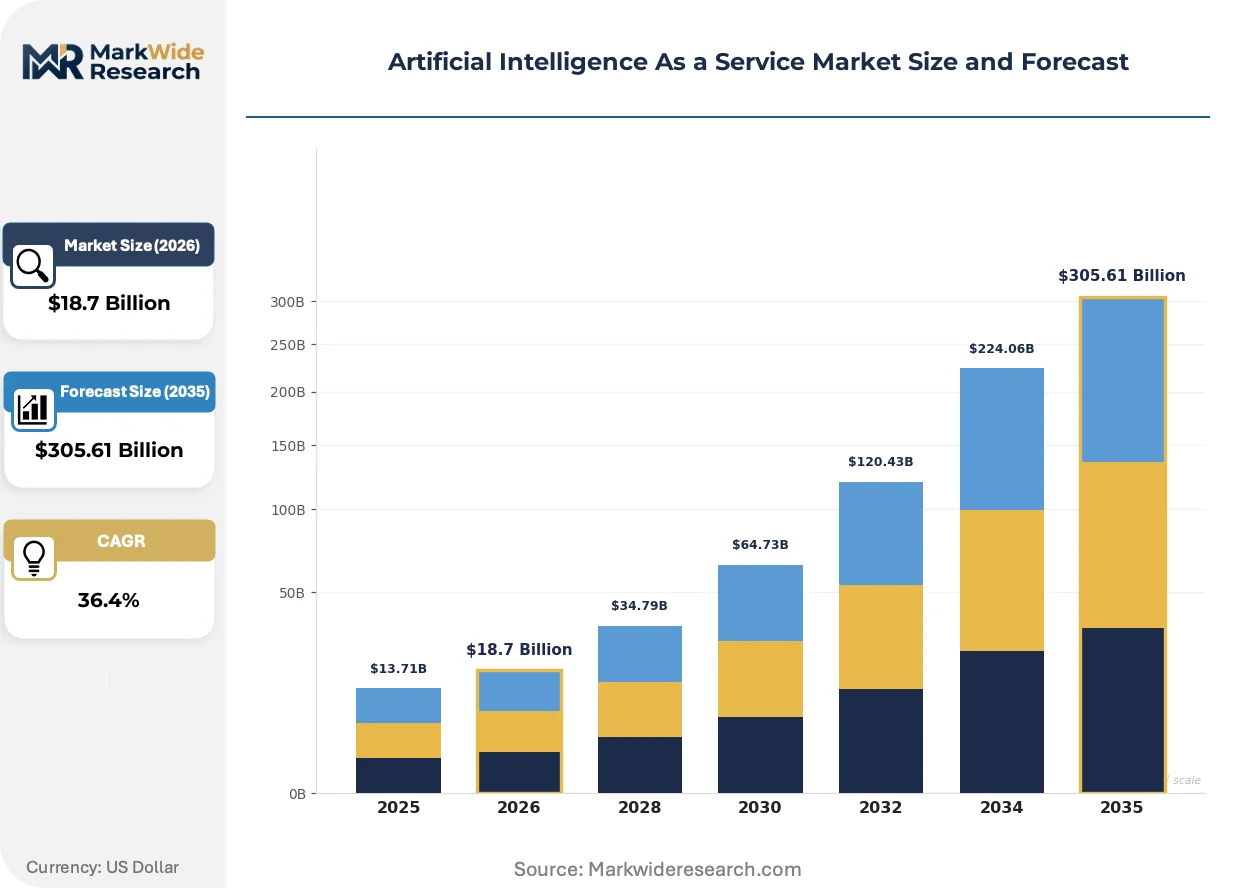
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $305.61 Billion |
| CAGR (2026 – 2036) | 36.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: BFSI, Healthcare, Retail, Manufacturing Solution: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics Service Type: Model Training, Data Management, API Services, Consulting |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Salesforce, Oracle, SAP, Intel Corporation, BigML, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence As a Service Market Strategic Shifts & Innovations
Foundation model APIs are commoditizing natural language capabilities while specialized vertical models capture premium pricing in regulated domains. This bifurcation is restructuring vendor economics toward outcome-based contracts and away from raw compute resale.
Small language models optimized for domain-specific tasks are supplanting general-purpose GPT-class APIs in production enterprise deployments. Financial services compliance teams and healthcare clinical decision support units are adopting these compressed architectures for latency-sensitive applications. The shift is compressing addressable margins for undifferentiated large model hosting while opening subscription revenue for fine-tuned vertical variants.
EU AI Act risk classification requirements are mandating algorithmic transparency documentation for high-stakes systems deployed across European member states. Product teams must embed explainability mechanisms and human oversight interfaces into service architectures from initial design. Healthcare diagnostic and credit scoring applications face the steepest compliance burden, with vendors restructuring European go-to-market strategies around conformity assessment body partnerships.
Enterprise buyers are consolidating AI service procurement through existing cloud infrastructure contracts rather than standalone vendor relationships. Procurement functions at Fortune 500 industrials and mid-market healthcare systems are bundling GPU compute, pre-trained models, and implementation support under unified master service agreements. This pattern concentrates volume with hyperscale platforms in the United States and Germany while squeezing independent AI specialists into niche consulting roles.
Artificial Intelligence As a Service Market Segmentation
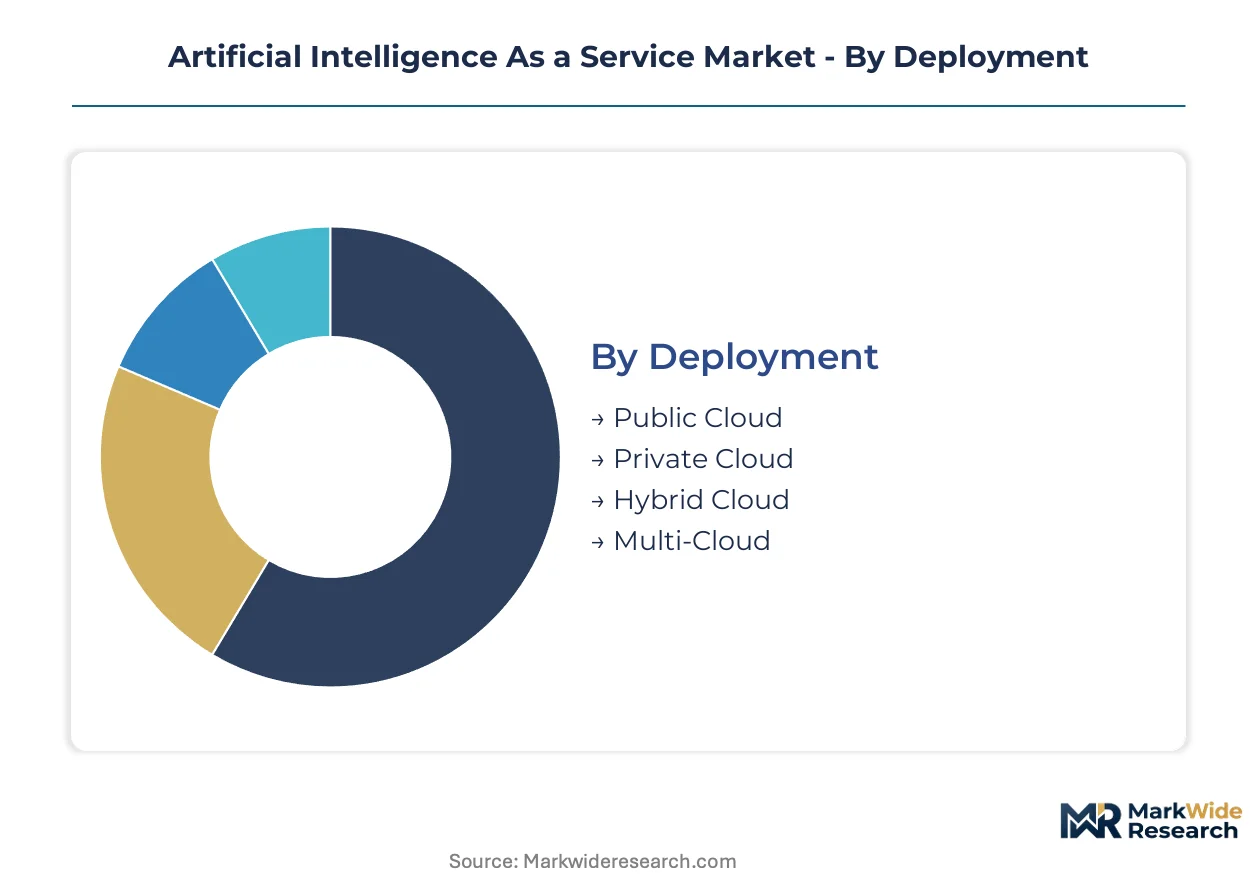
AI-as-a-Service segmentation reveals divergent margin structures across deployment architectures and solution types. Procurement patterns vary sharply between regulated verticals seeking compliance-heavy implementations and digital-native sectors prioritizing speed-to-deployment.
Deployment:
Substitution pressure from on-premise GPU clusters intensifies as enterprise capital expenditure constraints ease, challenging cloud-hosted delivery models.
- Public Cloud:Elastic GPU provisioning on shared infrastructure enables pay-per-inference economics for variable workloads. Demand concentrates among mid-market software vendors in the United States seeking to avoid NVIDIA hardware procurement delays.
- Private Cloud:Dedicated virtualized environments isolate tenant workloads on single-tenant hardware with customizable security postures. German automotive manufacturers and Swiss pharmaceutical groups deploy these configurations to satisfy EU AI Act data sovereignty requirements.
- Hybrid Cloud:Split architectures train models in public environments while sensitive inference executes on localized infrastructure.
- Multi-Cloud:Portability frameworks distribute workloads across competing hyperscaler platforms to mitigate vendor lock-in.
Public Cloud anchors the volume base while Hybrid Cloud gains share at the steepest rate.
End User:
Cost tier stratification separates budget-constrained experimentation from production-grade procurement with stringent uptime guarantees.
- BFSI:Real-time fraud detection and algorithmic trading systems require sub-millisecond inference latency on encrypted transaction streams. Large US banks and EU systemic institutions drive premium pricing for explainable credit scoring models compliant with GDPR automated decision-making rules.
- Healthcare:FDA-cleared diagnostic algorithms and clinical decision support tools command specialized compliance premiums. Community hospital networks across the United States and diagnostic imaging centers in Germany expand reimbursable AI-assisted interpretation.
- Retail:Demand forecasting and visual search applications prioritize cost efficiency over regulatory certification.
- Manufacturing:Predictive maintenance and quality inspection AI services remain underpenetrated among German Mittelstand exporters.
Healthcare commands the highest per-seat pricing while Manufacturing shows the steepest expansion trajectory among industrial adopters.
Solution:
Application maturity varies dramatically, with production deployment rates diverging between experimental pilots and scaled enterprise implementations.
- Machine Learning:Custom model development pipelines encompass data preprocessing, feature engineering, hyperparameter optimization, and deployment orchestration. Financial services quantitative teams in London and Singapore leverage these capabilities for proprietary trading signal generation.
- Natural Language Processing:Pre-trained transformer APIs for sentiment analysis, document summarization, and conversational interfaces carry premium pricing reflecting scarce specialized talent. Enterprise legal departments and contract management functions in the United States and Germany adopt these tools for due diligence automation.
- Computer Vision:Image classification, object detection, and video analytics APIs serve manufacturing quality control and retail inventory management.
- Predictive Analytics:Statistical forecasting and anomaly detection tools target supply chain optimization and equipment failure prediction.
Predictive Analytics anchors the volume base while Natural Language Processing captures the steepest pricing expansion.
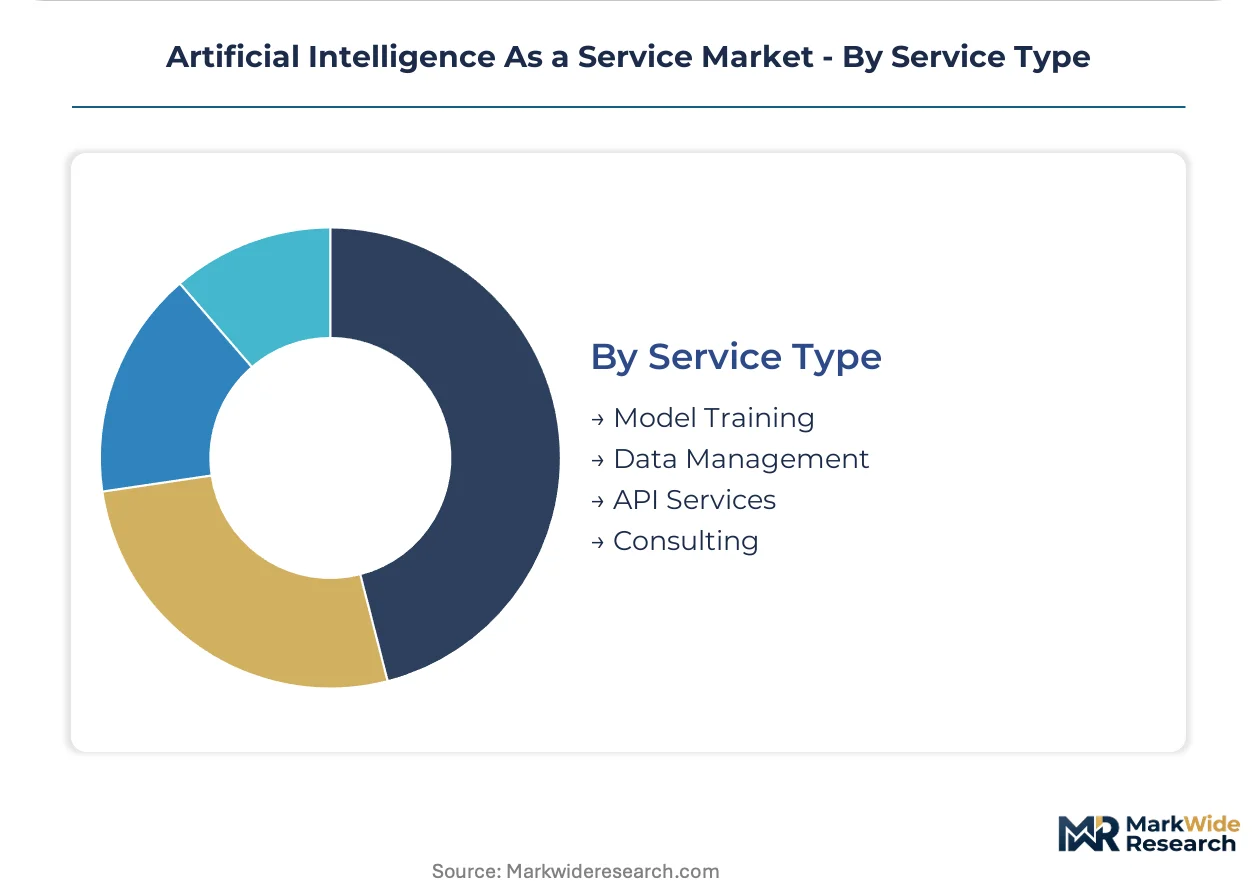
Service Type:
Customer type stratification separates self-service developers from enterprise buyers requiring full implementation support and managed operations.
- API Services:Standardized REST endpoints deliver pre-trained model inference without infrastructure management overhead. Software engineering teams at US SaaS startups and German e-commerce platforms integrate these capabilities for rapid feature deployment.
- Consulting:Advisory engagements span use case identification, data readiness assessment, model selection, and organizational change management. Healthcare systems navigating FDA device classification and EU AI Act conformity assessment drive sustained demand for regulatory-specialized consultants.
- Model Training:Managed GPU clusters with distributed training frameworks accelerate custom model development.
- Data Management:Labeling pipelines, synthetic data generation, and feature stores support ML operations.
API Services anchor the volume base while Consulting expands most quickly as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler GPU provisioning concentrates in the United States, China, and Germany, with regulatory divergence across jurisdictions fragmenting training dataset assembly and compliance architectures.
United States
Community hospital networks are expanding FDA-cleared diagnostic imaging algorithms into reimbursable clinical workflows. The Inflation Reduction Act stimulates domestic clean energy manufacturing investments, driving supply chain optimization AI procurement. Seattle and San Francisco Bay Area clusters anchor hyperscale model training infrastructure for enterprise SaaS integration.
Germany
Mid-sized industrial exporters in the Mittelstand segment remain underpenetrated for quality inspection and predictive maintenance AI services. EU AI Act risk-tiered obligations mandate algorithmic transparency documentation for high-stakes systems deployed across member states. Munich and Stuttgart automotive manufacturing hubs deploy private cloud configurations to satisfy data sovereignty requirements.
China
Domestic cloud providers accelerate GPU cluster provisioning for large language model training amid TSMC foundry allocation constraints. The Cybersecurity Law imposes cross-border data localization requirements that fragment international training dataset assembly. Beijing and Shenzhen technology corridors concentrate government-backed AI research commercialization.
United Kingdom
Financial services quantitative teams in London leverage custom machine learning development pipelines for proprietary trading signal generation. GDPR automated decision-making rules drive premium pricing for explainable credit scoring models among systemic institutions. The Thames Valley corridor hosts specialized consulting firms navigating EU AI Act conformity assessment for dual-market vendors.
Japan
Manufacturing quality control applications prioritize latency-sensitive small language model deployments over general-purpose GPT-class APIs. METI industrial policy supports edge inference containerization on factory-floor hardware converged with 5G connectivity. Nagoya automotive suppliers and Osaka electronics fabricators adopt hybrid cloud architectures for sensitive inference localization.
Artificial Intelligence As a Service Market Key Industry Players
Concentration sits with hyperscale cloud platforms that leverage captive data center footprints and productivity software integration to dominate enterprise GPU provisioning. The vendor base separates into three strategic archetypes: infrastructure-scale platforms with elastic compute resale, vertical specialists with proprietary model architectures, and compliance-heavy consultancies navigating FDA and EU AI Act certification. Dominant competitive moves include strategic partnerships with conformity assessment bodies and portfolio diversification into edge inference hardware.
Within the infrastructure-scale tier, Amazon Web Services, Microsoft, and Google exemplify distinct positioning vectors. Amazon Web Services anchors the GPU provisioning volume base through hyperscale data center economics. Microsoft occupies a position centered on productivity workflow integration. Google sits within the pre-trained large language model specialization, offering standardized API endpoints for developer accessibility.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Salesforce |
| Oracle |
| SAP |
| Intel Corporation |
| BigML |
| Others |
Cost & Logistics Intelligence
Hyperscale GPU cluster utilization rates above 80 percent compress unit economics for training workloads while elevating price floors for spot inference capacity across United States, China, and Germany. This capacity-concentration dynamic concentrates pricing power with cloud infrastructure providers who control TSMC-foundry allocation, forcing mid-market AI service vendors toward vertical specialization or margin erosion.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise commitment levels, with reserved instance pricing commanding 40-60 percent discounts against on-demand inference rates for multi-year contracts. Premium pricing attaches to FDA-cleared diagnostic algorithms and EU AI Act high-risk system compliance documentation, while commodity natural language API access faces sustained cost compression from foundation model commoditization. Price differentiation hinges on certification grade and vertical integration depth, with hyperscalers capturing margin from proprietary silicon and managed MLOps tooling. Healthcare providers and BFSI institutions show lowest price sensitivity due to regulatory liability exposure, whereas retail demand forecasting buyers prioritize cost efficiency over performance guarantees.
Supply Chain Analysis
Just-in-time GPU provisioning dominates hyperscaler operations, though strategic stockpiling of NVIDIA H100 accelerators has intensified among Chinese cloud providers facing TSMC allocation constraints. Supply concentration centers on Taiwan for advanced semiconductor foundry capacity, the United States for chip design and cloud infrastructure deployment, and China for domestic alternative accelerator development. Raw material dependencies span high-bandwidth memory from South Korea, advanced packaging substrates from Japan and Taiwan, and rare earth elements for magnetics in cooling systems. Single-source vulnerability at TSMC's 4nm node creates systemic risk for training-intensive workload availability. Distribution runs through direct hyperscaler enterprise sales teams and specialized systems integrators serving regulated verticals in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Artificial Intelligence As a Service Market represents a high-growth disruption anchored by foundation model API commoditization and EU AI Act regulatory inflection, restructuring vendor economics toward compliance-heavy vertical specialization.
For Market Incumbents: Compound defensive positioning through proprietary silicon development and captive conformity assessment body partnerships to escape hyperscaler price compression. Prioritize backward integration into edge inference hardware for manufacturing quality control applications in Germany. ISO 42001 certification investment creates switching costs among enterprise procurement functions navigating 12-18 month audit timelines.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for radiology diagnostic algorithms open reimbursable revenue streams in underpenetrated United States community hospital networks. Target German Mittelstand predictive maintenance deployments through containerized small language model offerings converged with 5G factory-floor infrastructure. Go-to-market execution should anchor on specialized consulting engagements for EU AI Act high-risk system documentation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertical specialists with proprietary model architectures and regulatory certification depth over undifferentiated compute resale. Long-term viability concentrates on vendors demonstrating sustained gross margin expansion through outcome-based contracting in healthcare and financial services. Watch NVIDIA GPU allocation priority tiers as inflection indicator for hyperscaler competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Conformity Assessment Body Partnership | EU AI Act high-risk system certification accelerates market access across German automotive and healthcare verticals. |
| Proprietary Small Language Model Development | Domain-specific compressed architectures capture premium pricing in latency-sensitive manufacturing quality inspection applications. |
| Edge Inference Hardware Integration | Containerized model serving on factory-floor GPU clusters converges 5G connectivity with localized data sovereignty compliance. |
| FDA 510(k) Diagnostic Algorithm Clearance | Reimbursable AI-assisted radiology interpretation expands addressable market into United States community hospital networks. |
| ISO 42001 Management System Certification | Enterprise procurement approval timelines compress competitive positioning for audited AI service vendors. |
Research Approach
The analysis maps public cloud GPU provisioning, private cloud sovereign deployments, hybrid edge inference, and managed MLOps consulting, each validated through CTOs at mid-market SaaS vendors, IT procurement officers at Fortune 500 industrials, platform engineers at hyperscale cloud providers, and regulatory affairs leads navigating FDA device classification. Primary interview intelligence combined with secondary validation from SEC hyperscaler capex disclosures, EU AI Act implementation guidance, FDA 510(k) clearance databases, and hospital GPO contract repositories. Bottom-up service-type demand modeling and top-down cloud infrastructure spend analysis underwent cross-reference triangulation.
Consistency checks validated segment-level outputs against external hyperscaler revenue reporting and enterprise AI procurement survey benchmarks across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, solution type, end-user vertical, and regional regulatory framework cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating GPU supply constraints and compliance timeline friction. Forecast inputs include TSMC foundry capacity allocation schedules and EU AI Act conformity assessment body certification throughput estimates.
Underlying assumptions cover sustained hyperscaler GPU supply prioritization, stable EU AI Act enforcement timelines, and continued FDA diagnostic algorithm clearance velocity, with deviation risk concentrated in TSMC geopolitical disruption or EU regulatory scope expansion. Revision becomes warranted when NVIDIA allocation priority tier thresholds shift materially or ISO 42001 audit backlogs exceed 24-month queues.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Europe Synthetic Data Generation Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Global Ambient Intelligence Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
Global Voice Cloning Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market