
 Global Deep Learning Neural Networks (Dnns) Market | 2026-2036
Global Deep Learning Neural Networks (Dnns) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Deep Learning Neural Networks (Dnns) Market Foresight
The capital-intensity divergence between chip designers and cloud service operators is rotating competitive dynamics across the sector. NVIDIA Corporation leverages its GPU fabrication partnerships to dominate training workloads for large-scale models. Microsoft Corporation anchors enterprise adoption through Azure's integrated machine learning pipelines. Alphabet Inc. sustains leadership in foundational research while competing aggressively on inference cost efficiency.
Deep learning neural networks constitute layered computational architectures with interconnected nodes that automatically extract hierarchical features from raw data through backpropagation-driven weight optimization. These systems process inputs across multiple abstraction levels, enabling pattern recognition without explicit programmed rules for feature engineering. Convolutional neural networks capture the largest margin pools in computer vision deployments, while natural language processing applications expand fastest among enterprise buyers. Cloud-based deployment models attract the majority of new capital commitments, though edge computing configurations gain traction for latency-sensitive autonomous vehicle and industrial inspection workloads.
The FDA software-as-medical-device framework and EU AI Act risk classification system impose divergent compliance burdens on healthcare and high-stakes applications, forcing vendors to maintain parallel regulatory tracks. China's NMPA and MIIT coordinate national AI standards through GB certification requirements that restrict market access for non-compliant foreign architectures. Stakeholders must monitor how divergent national AI governance regimes fragment model deployment strategies and data residency requirements across jurisdictions.
Market Dynamics
The capital-intensity divergence between GPU fabrication and cloud infrastructure is fragmenting competitive dynamics across the deep learning supply stack. Training workload economics now hinge on specialized accelerator access rather than general-purpose compute scaling.
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:The FDA's streamlined SaMD classification accelerates clinical AI deployment for diagnostic imaging, reducing premarket review timelines for convolutional neural network-based radiology tools.
- Edge Computing Architectures:Autonomous vehicle manufacturers and industrial inspection operators deploy federated learning configurations to process inference workloads locally, bypassing latency constraints of centralized cloud pipelines.
- United States Federal AI R&D Concentration:Cloud infrastructure spending and national laboratory partnerships in the US outpace other markets, anchoring demand for large-scale model training capacity.
Market Restraints
- High-Bandwidth Memory Supply Concentration:GPU training clusters depend on HBM3E supply from South Korean memory fabricators, creating input cost volatility and allocation bottlenecks during demand surges.
- EU AI Act Risk Classification:High-risk AI system designations impose conformity assessment burdens on healthcare and biometric applications, forcing parallel compliance tracks that extend commercialization timelines.
- Deterministic Inference Limitations:Probabilistic neural network outputs face substitution pressure from symbolic AI and physics-informed models in safety-critical control systems requiring guaranteed behavioral bounds.
Strategic Opportunities
- India PLI Scheme for Electronics Manufacturing:Production-linked incentives for semiconductor assembly and testing create localized supply chain nodes for inference accelerator packaging serving South Asian cloud deployments.
- Neuromorphic-Photonic Convergence:Hybrid architectures combining spiking neural networks with silicon photonics interconnects promise order-of-magnitude efficiency gains for edge inference in drone and robotics applications.
- China GB Standards Harmonization:Foreign vendors achieving NMPA and MIIT GB certification compliance unlock access to hospital procurement networks and national AI infrastructure tenders.
Industry Challenges
- MLops Talent Scarcity:Production deployment of transformer architectures requires specialized expertise in distributed training orchestration and quantization optimization that outstrips current workforce supply.
- Multi-Jurisdiction Model Governance:Divergent data residency mandates across the EU, China, and Middle Eastern markets force architectural fragmentation and redundant training runs on geographically siloed datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Deep Learning Neural Networks (Dnns) Market |
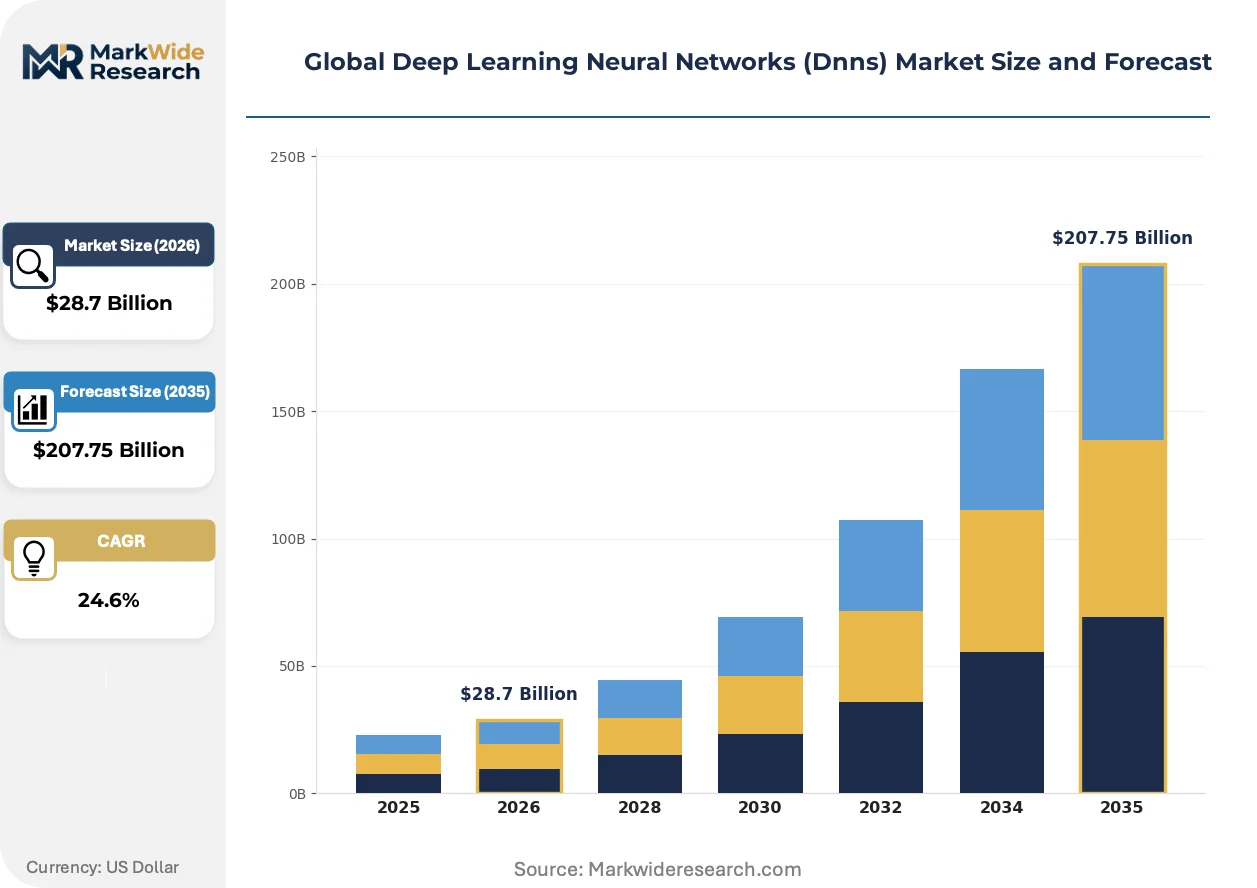
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $207.75 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Architecture Type: Convolutional Neural Networks, Recurrent Neural Networks, Generative Adversarial Networks, Autoencoders Application: Image Recognition, Natural Language Processing, Speech Synthesis, Fraud Detection, Autonomous Vehicles Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User Industry: Banking, Telecommunications, Government, Transportation, Energy |
| Companies Covered | NVIDIA Corporation, Microsoft Corporation, Alphabet Inc., Amazon Web Services, Inc., IBM Corporation, Intel Corporation, Meta Platforms, Inc., Advanced Micro Devices, Inc., Baidu, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Deep Learning Neural Networks (Dnns) Market Shifts & Advancements
Transformer-based architectures are compressing development cycles across natural language and multimodal applications. Competitive differentiation now hinges on inference cost efficiency rather than raw parameter scale.
Mixture-of-experts routing is displacing dense transformer configurations in production deployments. Enterprise buyers at financial services and legal technology firms adopt sparse activation patterns to slash serving costs per token. This architectural shift is displacing capital-intensive monolithic model training with modular, selectively-activated parameter pools.
The EU AI Act's high-risk system obligations took effect in phases through 2024, mandating conformity assessments for biometric identification and medical diagnostic tools. Healthcare AI vendors must maintain technical documentation and human oversight protocols that extend commercialization timelines by twelve to eighteen months. European hospital procurement committees now require CE-marked AI components, filtering non-compliant North American and Asian suppliers from radiology and pathology tenders.
Consumption patterns among enterprise buyers are consolidating around API-first procurement rather than self-managed infrastructure. Mid-market software vendors and industrial automation operators now access foundation models through managed inference endpoints, bypassing capital expenditure for dedicated GPU clusters. This shift is most visible in Germany and Japan, where manufacturing equipment makers embed neural network capabilities through cloud API integration rather than on-premise model training.
Global Deep Learning Neural Networks (Dnns) Market Segmentation
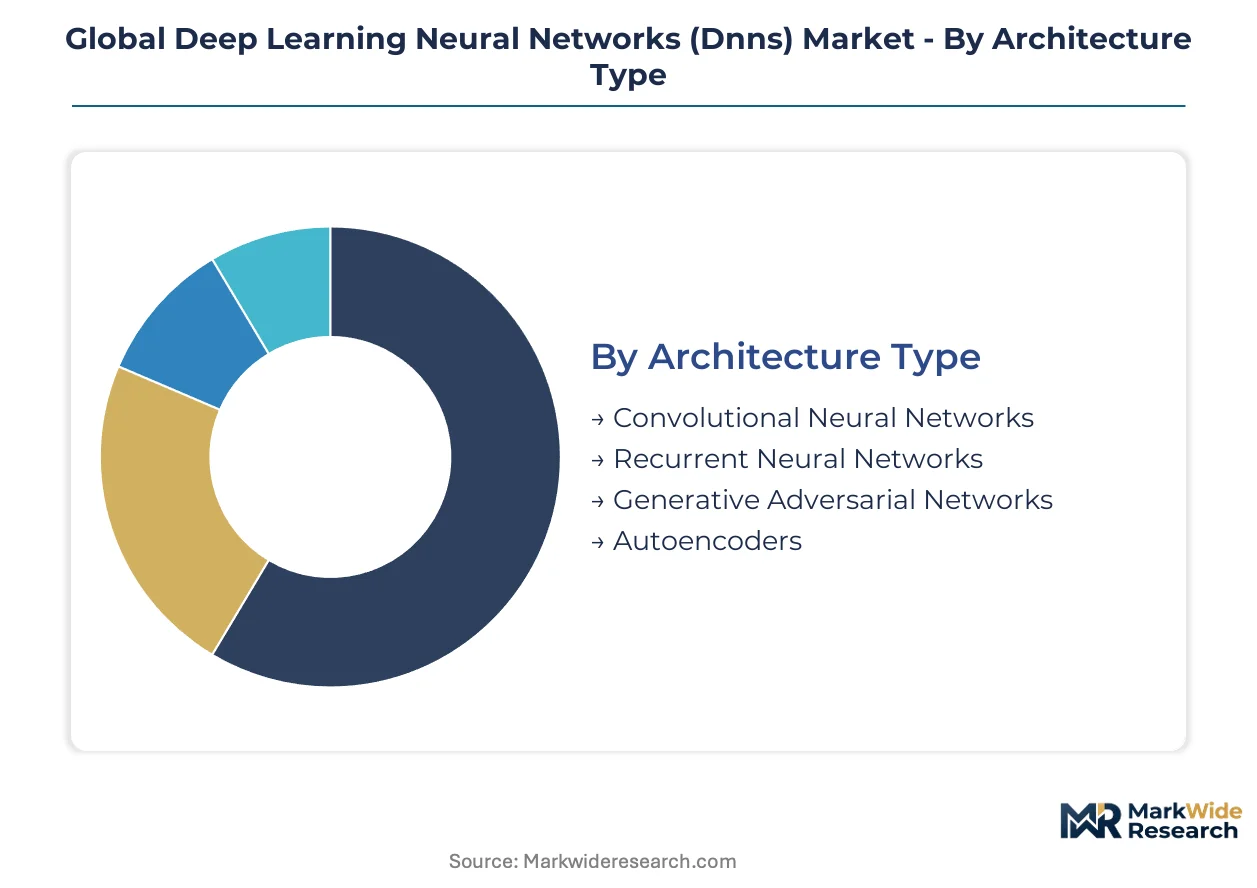
Deep learning neural networks fragment across four intersecting dimensions that determine procurement patterns and vendor positioning. Architecture type dictates hardware requirements and training economics. Deployment model selection hinges on latency constraints and data sovereignty mandates across national jurisdictions.
Architecture Type:
Substitution pressure from transformer-based and state-space architectures is compressing growth trajectories for legacy recurrent designs, while convolutional variants face efficiency challenges from vision transformers in high-resolution imaging workloads.
- Convolutional Neural Networks:Layered architectures applying learnable filters to spatial data hierarchies, with parameter sharing reducing computational load versus fully-connected alternatives. Diagnostic imaging systems in United States hospitals deploy these for radiology screening, though FDA software-as-medical-device pathways impose documentation burdens that extend validation cycles.
- Recurrent Neural Networks:Sequential processing units with hidden state persistence enabling temporal pattern modeling across variable-length inputs. Demand concentrates in legacy speech recognition installations at telecommunications operators, where long short-term memory variants still process time-series forecasting despite transformer displacement in greenfield deployments.
- Generative Adversarial Networks:Adversarial training frameworks pitting generator against discriminator networks for synthetic data generation. Fashion and media buyers in European markets utilize these for product visualization, navigating EU AI Act transparency obligations for synthetic content disclosure.
- Autoencoders:Encoder-decoder structures learning compressed latent representations for anomaly detection and denoising. Industrial inspection systems at Japanese automotive plants deploy variational variants for defect identification in manufacturing pipelines.
Convolutional Neural Networks retain volume leadership; Generative Adversarial Networks hold the steepest expansion curve in creative industry applications.
Application:
Cost tier stratification separates high-volume inference workloads from capital-intensive training pipelines, with natural language commanding premium API pricing while image recognition commoditizes at scale.
- Image Recognition:Pixel-level classification and object detection systems processing visual inputs across multiple abstraction scales. Retail loss prevention and agricultural monitoring in Brazil and India drive edge deployment, where latency requirements favor localized inference over cloud round-trips.
- Natural Language Processing:Transformer-based architectures processing token sequences for understanding, generation, and translation tasks. Enterprise buyers at financial services firms in Singapore and Switzerland access foundation models through managed endpoints, slashing per-token serving costs via mixture-of-experts routing.
- Speech Synthesis:Neural vocoders and acoustic models generating human-like audio from text or latent representations. Audiobook production studios and accessibility technology vendors in Germany adopt these for multilingual content generation, facing GDPR scrutiny over voice biometric data processing.
- Fraud Detection:Anomaly identification systems flagging transactional patterns deviating from behavioral baselines. Payment processors in Nigeria and South Africa deploy graph neural networks for real-time authorization scoring, constrained by central bank data localization mandates.
- Autonomous Vehicles:Multi-modal perception stacks fusing camera, lidar, and radar inputs for navigation decisions. Testing programs in Arizona and Bavaria run inference on vehicle-mounted accelerators, though deterministic safety requirements limit neural network penetration in braking control systems.
Image Recognition dominates current deployment volumes; Autonomous Vehicles command the highest infrastructure investment intensity per implementation.
Deployment Model:
Customer type segmentation reveals divergent procurement logic: hyperscale operators optimize for utilization efficiency while regulated industries prioritize auditability and data residency compliance.
- Cloud-Based:Centralized training and inference pipelines leveraging third-party GPU clusters with pay-per-use economics. United States federal research laboratories and mid-market software vendors anchor demand, though export control restrictions on advanced accelerators fragment cross-border model development.
- On-Premises:Dedicated hardware installations within organizational boundaries for sensitive workload isolation. Healthcare systems in France and Canada mandate these configurations for patient data processing, complying with national health information privacy statutes and PIPEDA requirements.
- Hybrid:Orchestrated workloads splitting training and inference across cloud and local infrastructure. Manufacturing equipment makers in Japan and South Korea adopt these for predictive maintenance, training on aggregated fleet data while running inference on plant-floor edge nodes.
- Edge Computing:Decentralized processing on device-mounted accelerators bypassing network latency. Drone operators and industrial robotics vendors in Israel and Australia deploy federated learning configurations, synchronizing model updates without raw data centralization.
Cloud-Based deployments retain volume leadership; Edge Computing is climbing the fastest as autonomy applications proliferate.
End User Industry:
Supply concentration in specialized accelerators and high-bandwidth memory creates divergent procurement power across verticals, with banking and telecommunications commanding allocation priority during supply crunches.
- Banking:Algorithmic trading, credit scoring, and anti-money-laundering surveillance systems. Investment banks in London and New York deploy transformer architectures for document analysis, subject to SEC and FCA model risk management guidelines.
- Telecommunications:Network optimization, predictive maintenance, and customer churn prediction workloads. Operators in Saudi Arabia and UAE leverage these for 5G radio resource allocation, coordinating with national spectrum regulators on infrastructure deployment timelines.
- Government:Surveillance, document processing, and public service automation applications. Defense and intelligence agencies in Australia and South Korea drive classified workload demand, restricted by domestic content requirements for sensitive system components.
- Transportation:Route optimization, predictive maintenance, and autonomous system development. Logistics providers in Netherlands and logistics platforms in India utilize these for fleet dispatch optimization, integrating with national freight corridor digitization initiatives.
- Energy:Grid load forecasting, equipment failure prediction, and renewable generation optimization. Utility operators in Denmark and Texas deploy physics-informed neural networks for wind and solar output prediction, blending data-driven patterns with meteorological simulation constraints.
Banking retains volume leadership in premium accelerator procurement; Energy is gaining share fastest as grid modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States cloud infrastructure markets while Chinese accelerator procurement faces GB certification cost premiums. European conformity assessment burdens extend commercialization timelines by twelve to eighteen months. Divergent data residency mandates fragment model deployment strategies across jurisdictions.
United States
Federal AI R&D budgets and national laboratory partnerships anchor demand for large-scale training capacity. FDA software-as-medical-device pathways streamline clinical AI deployment for diagnostic imaging tools. Arizona hosts autonomous vehicle testing programs running inference on vehicle-mounted accelerators.
China
NMPA and MIIT coordinate national AI standards through GB certification requirements that restrict market access. Hospital procurement networks and national AI infrastructure tenders favor compliant domestic architectures. Beijing-Tianjin-Hebei cluster concentrates hyperscale operator investments in specialized accelerator deployment.
Germany
Manufacturing equipment makers embed neural network capabilities through cloud API integration rather than on-premise training. EU AI Act high-risk system obligations mandate technical documentation and human oversight protocols for biometric tools. Bavaria runs autonomous vehicle testing programs with deterministic safety requirements limiting neural network penetration in braking control.
India
Production-linked incentives for semiconductor assembly and testing create localized supply chain nodes for inference accelerator packaging. Central bank data localization mandates constrain payment processor deployment of graph neural networks for real-time authorization. Maharashtra and Karnataka anchor cloud infrastructure expansion serving South Asian enterprise buyers.
Japan
Automotive plants deploy variational autoencoders for defect identification in manufacturing pipelines. METI standards coordination shapes industrial AI procurement specifications for predictive maintenance systems. Kansai region manufacturing equipment makers adopt hybrid cloud-edge configurations for fleet data aggregation.
Global Deep Learning Neural Networks (Dnns) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the deep learning supply stack. GPU fabrication specialists command premium pricing for training workloads while cloud service operators compete on inference cost efficiency. Three archetypes dominate: specialized accelerator designers, hyperscale cloud platforms, and enterprise software integrators. Capacity expansion in high-bandwidth memory and strategic partnerships for model distribution represent the dominant competitive moves.
Within the specialized accelerator tier, NVIDIA Corporation and Advanced Micro Devices, Inc. occupy positions defined by fabrication partnerships and memory subsystem integration. Microsoft Corporation anchors enterprise adoption through Azure's integrated machine learning pipelines, representing the hyperscale platform archetype. These three companies exemplify the divergence between hardware-centric and service-centric value capture in deep learning infrastructure markets.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Microsoft Corporation |
| Alphabet Inc. |
| Amazon Web Services, Inc. |
| IBM Corporation |
| Intel Corporation |
| Meta Platforms, Inc. |
| Advanced Micro Devices, Inc. |
| Baidu, Inc. |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with South Korean HBM3E fabricators lock in supply allocation for GPU training clusters while anchoring price visibility eighteen months forward. NVIDIA Corporation and hyperscale cloud operators negotiate these arrangements to bypass spot-market volatility during demand surges for large-scale model training.
Pricing Analysis
The customization-premium spread between configured-to-order accelerator clusters and standard cloud inference instances runs wide. SaaS-tiered API pricing dominates enterprise procurement, with differentiation driven by model performance tier and data residency certification level. Cost compression in standard inference APIs is intensifying because mixture-of-experts architectures slash per-token serving economics. Mid-market software vendors exhibit highest price sensitivity, while defense and intelligence agencies absorb premium pricing for sovereign-cloud configurations.
Supply Chain Analysis
Inventory lead times for advanced GPU accelerators stretch to thirty-six weeks during allocation crunches. Supply concentrates in Taiwan for TSMC fabrication, South Korea for SK Hynix and Samsung HBM3E supply, and the United States for NVIDIA and AMD design operations. Raw material dependencies span silicon wafers, CoWoS packaging substrates, and rare earth elements for magnetics. Single-source vulnerability in high-bandwidth memory creates allocation bottlenecks. Distribution runs through direct OEM partnerships and cloud service operator procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale cloud operators as procurement consolidates around API-first consumption models. Mid-market software vendors and industrial automation operators now pool demand through managed inference endpoints.
For Market Incumbents: Secure HBM3E supply commitments through multi-year offtake agreements with South Korean memory fabricators to defend against allocation shortages. Anchor enterprise retention by embedding machine learning pipelines into vertical-specific compliance workflows for FDA software-as-medical-device and EU AI Act high-risk system obligations. Capacity addition in India for semiconductor assembly and testing addresses geopolitical risk exposure.
For New Entrants and Emerging Players: MLOps tooling gaps in distributed training orchestration and quantization optimization present white-space entry points. Target European healthcare systems facing twelve-to-eighteen-month commercialization delays from conformity assessment burdens, offering pre-validated documentation packages. Pursue neuromorphic-photonic convergence for drone and robotics edge inference as a differentiated hardware-software bundling play.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hyperscale cloud platforms with managed inference endpoint penetration. Long-term viability over the next decade favors vendors with dual-track regulatory compliance across FDA, EU AI Act, and China GB certification frameworks. Acquisition targets should demonstrate NMPA and MIIT compliance progress for hospital procurement network access. Monitor EU AI Act enforcement intensity as an inflection signal for European market entry costs.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Compliance Investment | Unlocks access to China's hospital procurement networks and national AI infrastructure tenders. |
| Mixture-of-Experts Architecture Deployment | Slashes per-token serving costs for financial services and legal technology enterprise buyers. |
| India PLI Scheme Localization | Creates captive supply chain nodes for inference accelerator packaging serving South Asian cloud deployments. |
| Neuromorphic-Photonic Convergence R&D | Promises order-of-magnitude efficiency gains for latency-sensitive drone and robotics applications. |
| Federated Learning Edge Configuration | Enables autonomous vehicle and industrial inspection operators to bypass centralized cloud latency constraints. |
Research Methodology
Operator-level perspectives from cloud infrastructure procurement officers, MLOps platform engineers, healthcare AI deployment leads, semiconductor supply chain managers, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from SEC hyperscaler capex disclosures, FDA software-as-medical-device filing databases, EU AI Act implementation guidance, and NMPA GB certification registries. Bottom-up model training capacity estimates triangulated against top-down cloud infrastructure spending projections.
Sensitivity analysis tested forecast robustness across accelerator supply scenarios and regulatory enforcement intensities. Segmentation dimensions modeled encompass architecture type, deployment model, application workload, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical cloud infrastructure spend patterns and federal AI R&D budget trajectories. Industry-specific inputs included GPU cluster utilization rates and inference cost efficiency improvement curves from mixture-of-experts adoption.
Underlying assumptions cover sustained HBM3E supply scaling, phased EU AI Act enforcement, and continued United States federal R&D concentration, with deviation risk concentrated in export control expansion and China GB standards fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Cognitive Collaboration Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
AI Orchestration Market
Artificial Intelligence (AI)
Brain Machine Interface Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
Edge AI Market