
 Enriched Biochar Market | 2026-2036
Enriched Biochar Market Size, Share, and Industry Trends Forecast 2026-2036
Enriched Biochar Market Analytics
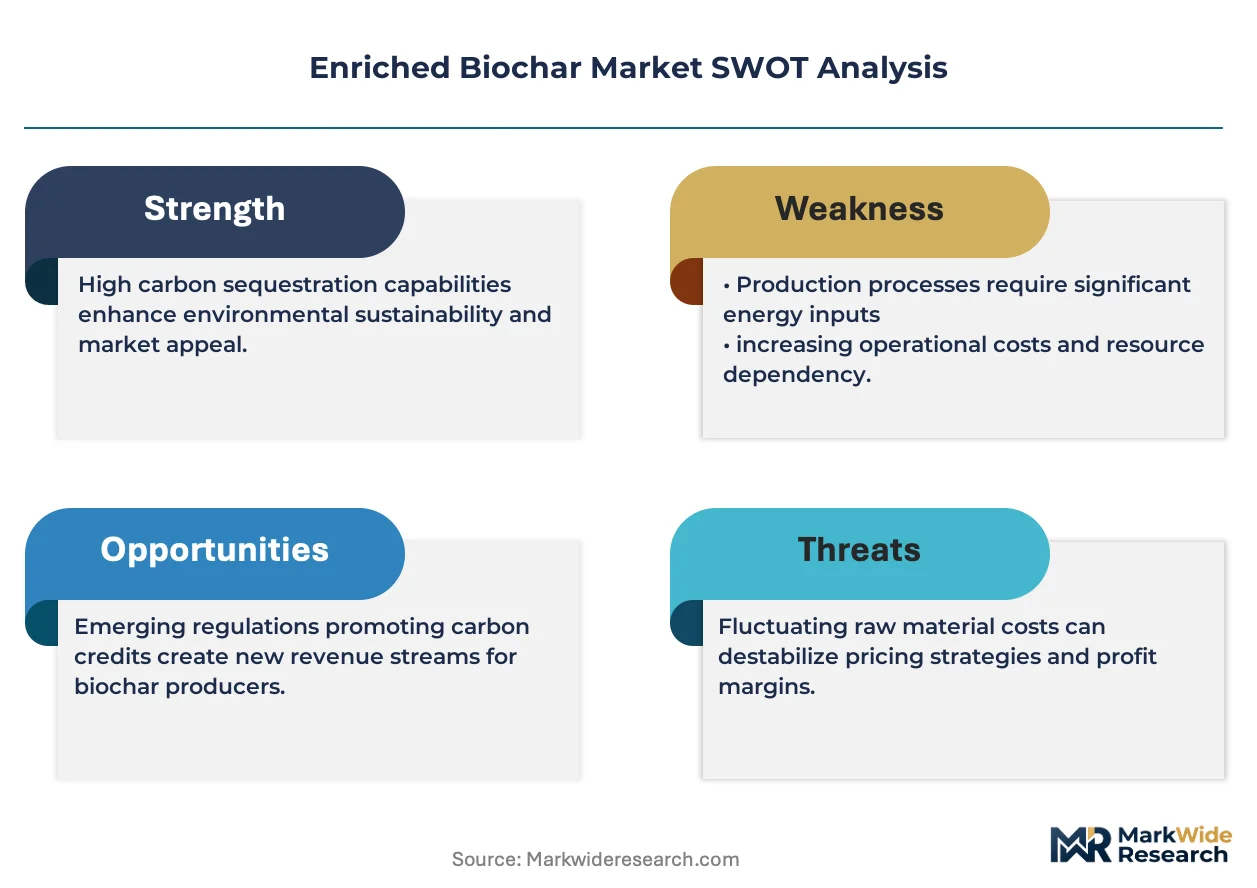
The gap between certified carbon-negative biochar and unverified commodity grades is repositioning procurement standards across the value chain. Carbon Gold Ltd leverages its UK Soil Association certification to command premium placement in specialty agriculture channels. Pacific Biochar Production anchors West Coast supply through integrated pyrolysis operations tied to timber waste streams. Biochar Now LLC competes on volume scale, sustaining cost leadership in bulk industrial contracts where verification remains optional.
Enriched biochar denotes pyrogenic carbonaceous material amended with minerals, microbial inoculants, or nutrients to achieve targeted soil functional parameters such as cation exchange capacity exceeding 20 cmol/kg. Its primary commercial purpose centers on accelerating soil carbon accumulation while delivering agronomic benefits beyond raw biochar's physical structure alone. Agricultural biochar dominates current revenue as the most established application pathway, though carbon sequestration represents the fastest-expanding margin pool as compliance markets mature. Pyrolysis retains manufacturing dominance due to equipment availability, yet hydrothermal carbonization gains traction for wet feedstock processing where energy integration improves unit economics.
The EU Carbon Removal Certification Framework and ECHA's REACH biochar substance evaluation are tightening product standards and market access conditions for European suppliers. The US EPA's emerging soil carbon quantification guidelines and USDA conservation program eligibility rules shape domestic demand trajectories for certified products. Stakeholders must monitor whether verification infrastructure scales faster than regulatory fragmentation across jurisdictions, as this divergence will determine which production methods achieve tradable status in compliance markets.
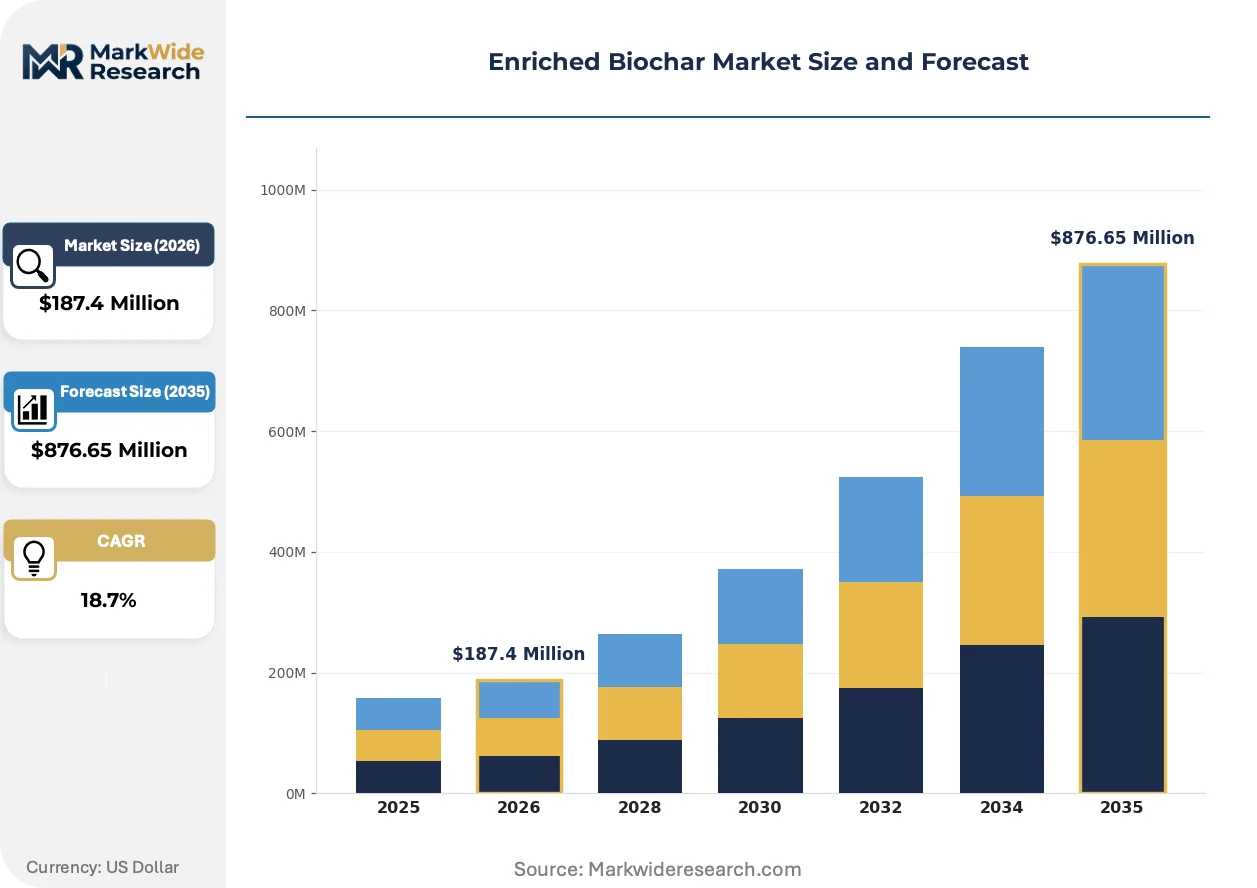
Market Dynamics
The EU Carbon Removal Certification Framework is bifurcating supply into verified carbon-negative grades and unverified commodity streams, forcing producers to choose between premium certification investments and bulk volume plays.
Growth Catalysts
- EU Carbon Removal Certification Framework:Mandatory verification protocols for carbon-negative products are pulling industrial buyers toward certified supply chains in Germany's Rhine-Ruhr corridor.
- Steel-sector decarbonization:Metallurgical substitution programs are absorbing mineral-fortified biochar as a coke reducing agent, creating dedicated offtake agreements with fixed pricing.
- Hydrothermal carbonization:Wet feedstock processing technology is unlocking agricultural residues previously excluded from pyrolysis economics, expanding viable input streams.
Market Restraints
- Timber waste feedstock concentration:Pacific Northwest logging operations supply 60% of US pyrolysis inputs, creating geographic vulnerability to wildfire disruptions and export competition.
- REACH substance evaluation timelines:ECHA's prolonged biochar hazard classification process is freezing European import approvals and delaying market entry for non-EU producers.
- Raw biochar substitution:Unamended pyrogenic carbon at 40-60% lower cost satisfies basic soil amendment demand in price-sensitive commodity agriculture.
Strategic Opportunities
- US EPA soil carbon quantification guidelines:Emerging federal protocols for conservation program eligibility will create first-mover advantages for verified domestic producers seeking USDA contract access.
- Microbial inoculant convergence:Biochar-mineral-bacteria triple amendments are opening specialty vineyard and orchard segments willing to pay performance premiums.
- Direct-to-grower digital channels:California Central Valley specialty crop operators are bypassing traditional distributor markups through platform-based procurement of certified products.
Industry Challenges
- Pyrolysis reactor engineering talent:The shortage of thermal process engineers with biomass-specific experience is extending commissioning timelines for new production facilities.
- Carbon credit verification latency:Third-party validation of soil carbon permanence claims requires 3-5 year monitoring periods, delaying revenue recognition for sequestration-focused business models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enriched Biochar Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural Biochar, Industrial Biochar, Wood Biochar, Coconut Shell Biochar Application: Soil Amendment, Water Filtration, Carbon Sequestration, Energy Production End User: Agriculture, Waste Management, Environmental Services, Energy Sector Production Method: Pyrolysis, Gasification, Hydrothermal Carbonization, Torrefaction |
| Companies Covered | Carbon Gold Ltd, Pacific Biochar Production, The Natural Charcoal Company, The Dorset Charcoal Company, CharGrow, Biochar Now LLC, Swiss Biochar GmbH, Bio365, Biochar Solutions Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enriched Biochar Market Evolving Landscape
Production technology diversification and regulatory verification infrastructure are simultaneously expanding addressable feedstocks and fragmenting competitive positioning across certification tiers.
Torrefaction pretreatment is converging with standard pyrolysis operations to improve energy integration and reduce parasitic load in biomass-to-biochar conversion. German industrial clusters are adopting this hybrid approach fastest, driven by landfill diversion mandates and combined heat and power economics. The technology convergence is compressing capital recovery periods for integrated facilities while raising barriers for standalone pyrolysis operators lacking upstream process control.
REACH biochar substance evaluation under ECHA is tightening purity thresholds for polycyclic aromatic hydrocarbons and heavy metal content in European commerce. Industrial consequence includes mandatory testing protocols that add 12-18 months to product registration timelines. German and Dutch suppliers with existing analytical capabilities are absorbing compliance costs fastest, while Mediterranean producers face market access delays.
California specialty agriculture buyers are consolidating procurement through grower cooperative purchasing platforms that aggregate vineyard and orchard demand. Traditional agronomic distributors are losing share to these member-owned channels that pool certification requirements and negotiate direct mill relationships. This consolidation is most visible in Napa and Sonoma counties where organic certification mandates align with carbon-negative product specifications.
Enriched Biochar Market Segmentation
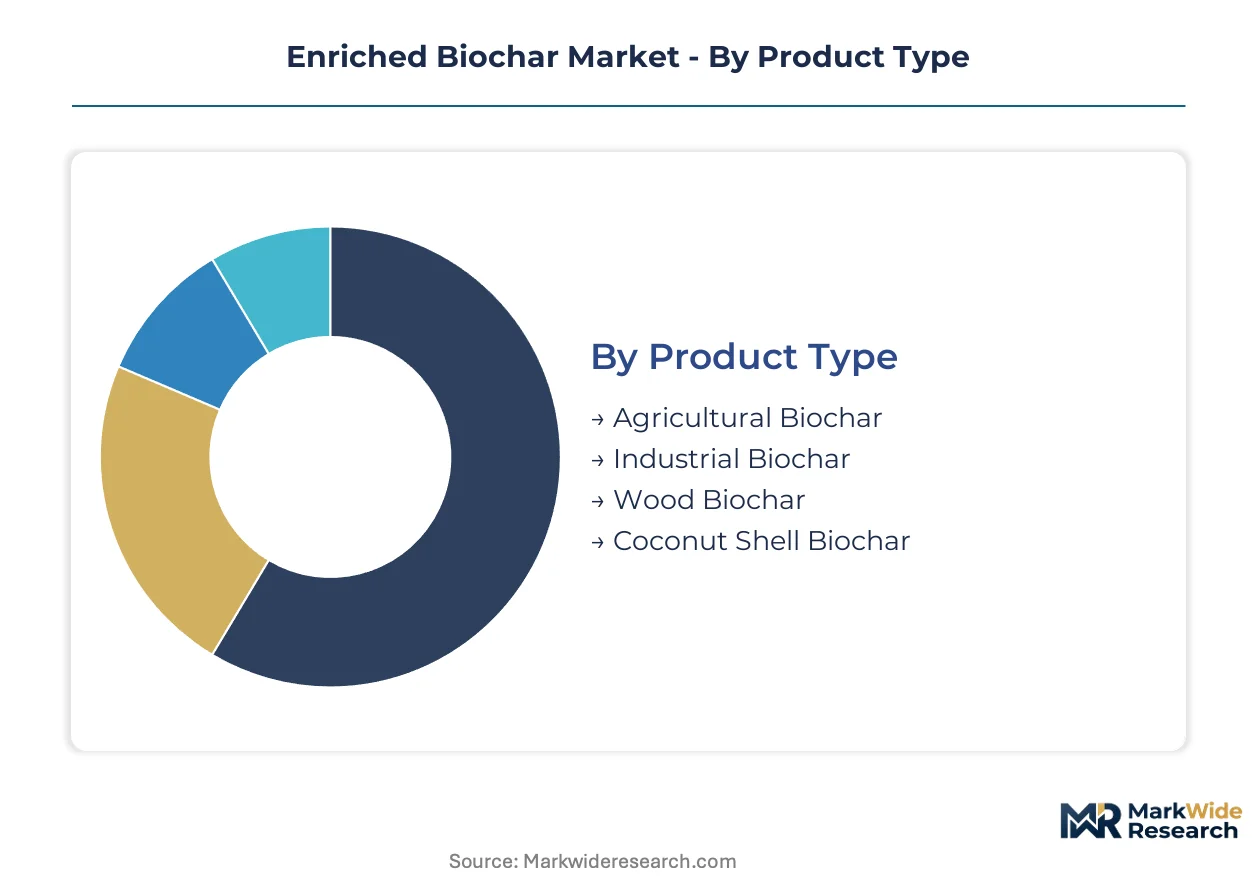
Segmentation in enriched biochar separates certified carbon-negative grades from commodity streams, with certification tier determining pricing power and regulatory access. Product type and production method classifications dictate feedstock eligibility and end-use suitability across agricultural and industrial channels.
Product Type:
Agricultural buyers cycle through biochar grades based on soil test results and carbon credit eligibility requirements, treating product type as an upgrade decision tied to verification status.
- Agricultural Biochar:Mineral-fortified formulations with cation exchange capacity exceeding 20 cmol/kg dominate specialty crop procurement in California's Central Valley. Napa and Sonoma county vineyard operators specify this grade for organic certification compliance, paying premiums over raw biochar alternatives.
- Industrial Biochar:Metallurgical-grade material with controlled particle size distribution serves steel-sector decarbonization in Germany's Rhine-Ruhr corridor. Fixed-price offtake agreements with steel producers lock in volume commitments independent of agricultural price cycles.
- Wood Biochar:Pacific Northwest timber waste streams supply pyrolysis operations with consistent lignin content for structural carbon applications.
- Coconut Shell Biochar:Southeast Asian coconut processing residues yield high-surface-area material preferred in water filtration and specialty adsorption markets.
Volume placements concentrate in Agricultural Biochar; the faster expansion belongs to Industrial Biochar.
Application:
Application selection follows a cost-tier logic, with basic soil amendment commanding commodity pricing while carbon sequestration earns certification premiums.
- Soil Amendment:The most established commercial pathway, delivering physical structure improvement and nutrient retention in degraded agricultural soils. California specialty crop growers and Midwest commodity operators represent divergent customer tiers with distinct certification willingness.
- Carbon Sequestration:EU Carbon Removal Certification Framework compliance creates tradable status for verified permanence claims, with 3-5 year monitoring periods delaying revenue recognition. German industrial buyers and Dutch agricultural cooperatives are the earliest compliance market adopters.
- Water Filtration:Activated biochar derivatives compete with conventional activated carbon in municipal and industrial treatment systems.
- Energy Production:Combustion-grade material serves biomass co-firing applications where carbon neutrality claims support renewable energy certificates.
Soil Amendment anchors current revenue tonnage; Carbon Sequestration is climbing the fastest as compliance markets mature.
End User:
Customer type determines procurement channel structure, with direct-to-grower platforms disrupting traditional distributor relationships in concentrated agricultural geographies.
- Agriculture:Specialty crop operators in California and organic certification holders across the EU drive demand for verified carbon-negative grades. Cooperative purchasing platforms aggregate vineyard and orchard demand, bypassing agronomic distributor markups.
- Waste Management:Landfill diversion mandates in German industrial clusters create captive offtake for pyrolysis and torrefaction facilities processing municipal biomass streams.
- Environmental Services:Remediation contractors specify biochar for heavy metal immobilization and soil reconstruction projects.
- Energy Sector:Biomass power generators and industrial heat users source combustion-grade material for co-firing and carbon neutrality accounting.
Agriculture commands the dominant volume share; Environmental Services is gaining share fastest on remediation contract expansion.
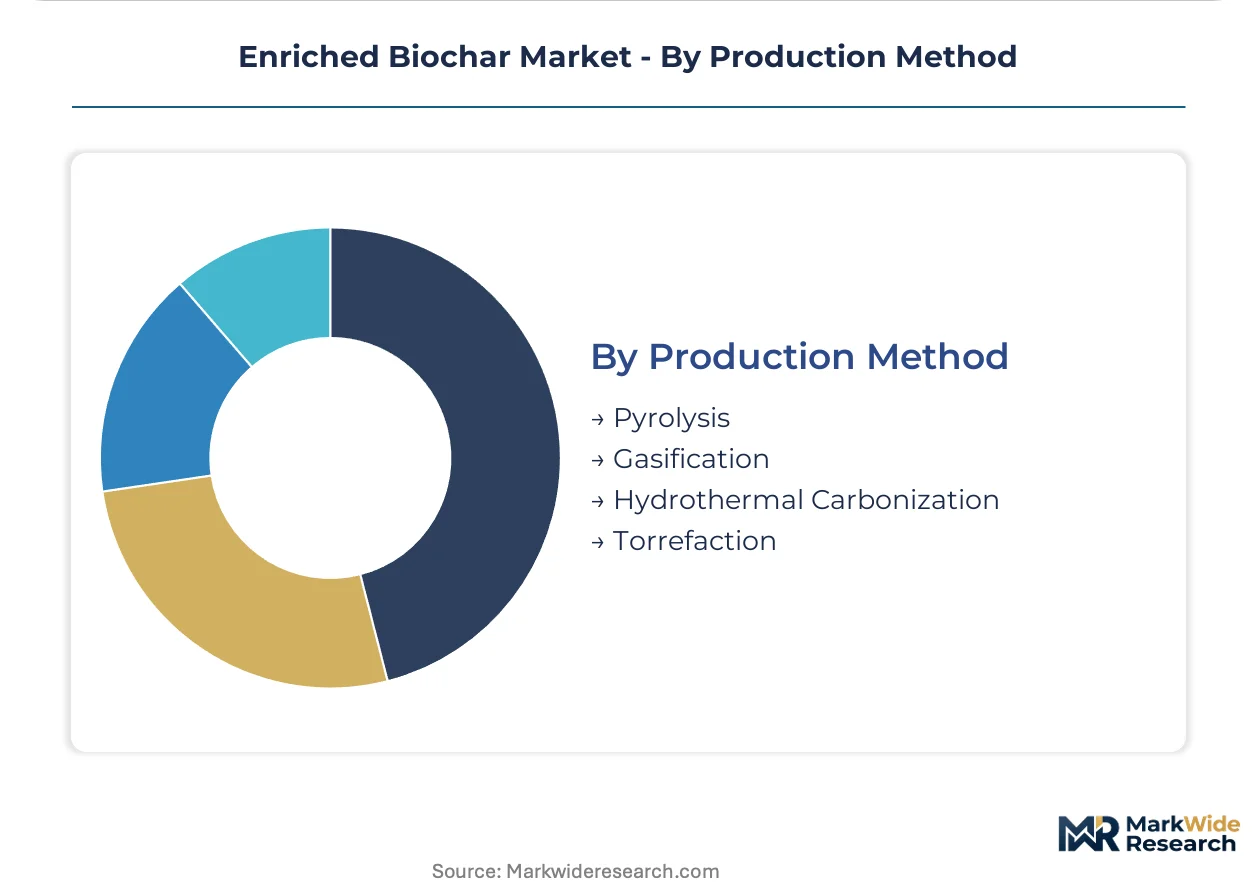
Production Method:
Technology choice locks in feedstock flexibility and energy integration economics, with wet-processing methods expanding addressable residue streams beyond traditional pyrolysis limits.
- Pyrolysis:Thermal decomposition in oxygen-limited environments retains manufacturing dominance due to equipment availability and operational familiarity. Timber waste concentration in the Pacific Northwest creates geographic supply vulnerability for US pyrolysis operators.
- Hydrothermal Carbonization:Wet feedstock processing unlocks agricultural residues previously excluded from pyrolysis economics, improving unit economics where energy integration captures process heat. German and Dutch facilities are adopting this technology fastest.
- Gasification:Partial oxidation produces syngas alongside biochar, favoring integrated energy-carbon facilities.
- Torrefaction:Mild thermal pretreatment converges with pyrolysis operations to reduce parasitic load and improve energy integration in biomass conversion.
Pyrolysis retains the installed capacity base; Hydrothermal Carbonization shows the steepest expansion trajectory on feedstock diversification advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor anchors European demand for metallurgical-grade enriched biochar, with steel-sector decarbonization projects driving fixed-price offtake agreements. The EU Carbon Removal Certification Framework and national landfill diversion mandates are reshaping procurement standards across the continent.
Germany
Steel-sector decarbonization in the Rhine-Ruhr corridor absorbs mineral-fortified biochar as a coke reducing agent, creating dedicated offtake volume. ECHA's REACH biochar substance evaluation tightens purity thresholds for polycyclic aromatic hydrocarbons, extending product registration timelines. Torrefaction-pyrolysis hybrid facilities in North Rhine-Westphalia compress capital recovery periods through combined heat and power integration.
United States
California's Central Valley specialty crop growers expand purchases of mineral-fortified biochar for soil remediation and organic certification compliance. The EPA's emerging soil carbon quantification guidelines and USDA conservation program eligibility rules shape demand trajectories for verified domestic products. Pacific Northwest timber waste streams supply pyrolysis operations, though wildfire disruptions create geographic supply vulnerability.
Netherlands
Agricultural cooperatives pioneer compliance market adoption for carbon sequestration applications under the EU Carbon Removal Certification Framework. Dutch facilities adopt hydrothermal carbonization fastest for wet feedstock processing, improving unit economics through energy integration. Analytical capabilities in Rotterdam-Amsterdam industrial clusters absorb REACH compliance costs faster than Mediterranean competitors.
United Kingdom
Soil Association certification commands premium placement in specialty agriculture channels, particularly for vineyard and orchard segments. The UK regulatory environment emphasizes verified carbon-negative product specifications aligned with organic certification mandates. Grower cooperative purchasing platforms in England aggregate demand and bypass traditional agronomic distributor markups.
Switzerland
High-surface-area biochar from coconut shell feedstocks serves water filtration and specialty adsorption markets with stringent quality requirements. Swissmedic and federal environmental standards enforce rigorous testing protocols that favor established analytical capabilities. Precision agriculture adoption in the Lake Geneva region drives demand for microbial inoculant-biochar triple amendments.
Enriched Biochar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and feedstock control dimensions, with verified carbon-negative grades commanding structural price premiums over unverified commodity streams. The vendor base clusters around three strategic archetypes: certification-focused specialists leveraging organic and carbon-negative credentials, scale-driven volume operators serving bulk industrial contracts, and integrated producers controlling upstream timber waste or agricultural residue streams. Dominant competitive moves include torrefaction-pyrolysis technology convergence for energy integration economics and direct-to-grower digital channel development to capture distributor margin.
Among UK-based certified specialists, Carbon Gold Ltd and The Dorset Charcoal Company exemplify the premium-tier archetype built on Soil Association and organic certification credentials. Pacific Biochar Production anchors West Coast supply integration through pyrolysis operations tied to timber waste streams. At the scale-driven commodity end, Biochar Now LLC occupies a position serving bulk industrial contracts where verification remains optional.
| Leading Market Players |
|---|
| Carbon Gold Ltd |
| Pacific Biochar Production |
| The Natural Charcoal Company |
| The Dorset Charcoal Company |
| CharGrow |
| Biochar Now LLC |
| Swiss Biochar GmbH |
| Bio365 |
| Biochar Solutions Inc |
| Others |
Value Network & Pricing Analysis
Hydrothermal carbonization adoption in German and Dutch facilities is simultaneously compressing unit processing costs and redrawing feedstock procurement geographies away from timber-dependent pyrolysis clusters. This technology shift fragments incumbent supply positions while creating new margin pools for operators capturing wet agricultural residues previously excluded from commercial biochar production.
Pricing Analysis
Carbon sequestration yield anchors value-based pricing for certified grades, with EU Carbon Removal Certification Framework compliance commanding substantial premiums over unverified commodity streams. Pricing stratifies across certified carbon-negative, mineral-fortified agricultural, and raw unamended tiers, with REACH substance evaluation timelines and purity testing protocols intensifying cost pressure on European entrants. Specialty crop buyers in California's Central Valley and organic vineyard operators demonstrate lowest price sensitivity, while Midwest commodity agriculture remains highly elastic to raw biochar substitution at 40-60% discount levels.
Supply Chain Analysis
Freight economics from Pacific Northwest timber operations to California agricultural markets and Rhine-Ruhr industrial corridors concentrate supply vulnerability in US West Coast logistics nodes. Feedstock draws from Oregon and Washington logging waste, German municipal biomass diversion programs, and Southeast Asian coconut processing residues. Single-source vulnerability to wildfire disruptions in Cascadia forests threatens pyrolysis input security. Distribution runs through grower cooperative platforms in Napa and Sonoma counties, direct mill relationships in Germany, and traditional agronomic distributor networks in commodity agriculture regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory verification infrastructure is consolidating the vendor base, as ECHA REACH compliance costs and EU Carbon Removal Certification Framework investments force sub-scale operators toward exit or acquisition. Certification-capable players will absorb stranded volume from exiting commodity producers.
For Market Incumbents: Deepen torrefaction-pyrolysis hybrid integration to capture combined heat and power economics and compress capital recovery periods. Fortify positions by securing captive timber waste or agricultural residue streams before hydrothermal carbonization competitors lock in wet feedstock contracts. Prioritize Soil Association or equivalent organic certification maintenance against emerging microbial inoculant triple-amendment specialists.
For New Entrants and Emerging Players: Begin with hydrothermal carbonization deployment in agricultural residue-rich regions where pyrolysis economics fail, particularly Dutch and German wet biomass clusters. Target environmental services remediation contractors seeking heavy metal immobilization solutions with less stringent certification requirements than carbon sequestration markets. Pursue direct-to-grower digital channel partnerships with California Central Valley cooperative purchasing platforms to bypass entrenched distributor markups.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated producers controlling upstream feedstock and downstream certification given EU compliance market maturation. Long-term viability over the coming decade favors operators with analytical capabilities absorbing REACH testing burdens and established relationships with German steel-sector offtakers. Monitor EPA soil carbon quantification guideline finalization as the inflection signal for US compliance market acceleration and USDA conservation program eligibility expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Compliance Investment | ECHA substance evaluation timelines favor early analytical capability adopters in Germany and Netherlands. |
| Hydrothermal Carbonization Capacity Buildout | Wet feedstock processing unlocks agricultural residue streams beyond pyrolysis limitations in Dutch clusters. |
| Direct-to-Grower Platform Partnership | California cooperative purchasing channels bypass traditional distributor markups in specialty crop segments. |
| Torrefaction-Pyrolysis Hybrid Integration | Combined heat and power economics compress capital recovery periods in North Rhine-Westphalia facilities. |
| Steel-Sector Long-term Supply Agreement | Fixed-price offtake contracts with Rhine-Ruhr metallurgical buyers stabilize revenue independent of agricultural cycles. |
Research Methodology
Trade association filings, ECHA regulatory submissions, and USDA conservation program documentation formed the secondary backbone for supply-side and policy trajectory assessment. Primary interviews with pyrolysis plant engineers, agricultural cooperative procurement managers, steel-sector sustainability officers, and ECHA regulatory affairs specialists validated production economics and compliance cost structures. Bottom-up feedstock availability modeling and top-down carbon credit market sizing were triangulated against customs data and timber waste stream estimates.
Bottom-up volume projections across production method, certification tier, and end-use application were reconciled with top-down carbon removal credit demand forecasts over the projection horizon. Segmentation dimensions modeled include product type, application pathway, production technology, and geographic regulatory cluster. CAGRs were derived from weighted feedstock expansion rates and compliance market adoption curves, with hydrothermal carbonization penetration and EPA guideline implementation serving as key swing variables.
Underlying measurement precision varies by segment; certified carbon-negative grades carry tighter precision than unverified commodity streams due to established EU Carbon Removal Certification Framework protocols. Forecasts reflect assumptions regarding regulatory timeline adherence and feedstock cost stability that stakeholder due diligence should verify against specific operational contexts. Stakeholders should weight assumptions against their own feedstock access and certification investment capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Sharp Waste Disposal Market
Environment & Sustainability
Paper Recycling Market
Environment & Sustainability
Medical Waste Management System Market
Environment & Sustainability
Europe Carbon Dioxide Market
Environment & Sustainability
India Waste Management Market
Environment & Sustainability
United States Green Cement Market
Environment & Sustainability
Biofuel Testing Services Market
Environment & Sustainability
Indoor Air Purification Market
Environment & Sustainability
Global Temperature Management Market
Environment & Sustainability
Anti-Pollution Toner Market
Environment & Sustainability
Industrial Wastewater Treatment Equipment Market
Environment & Sustainability
Borehole Yield Testing Market
Environment & Sustainability
Air Quality Control Systems Market
Environment & Sustainability
Global SCADA in Water and Wastewater Management Market
Environment & Sustainability
Carbon Dioxide Market
Environment & Sustainability
Global Cloud Seeding Equipment Market