
 Global Temperature Management Market | 2026-2036
Global Temperature Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Temperature Management Market Analysis
Hospital procurement consolidation is restructuring buying power across major healthcare systems, pushing vendors toward bundled device contracts and longer service agreements. Medtronic PLC leverages its cardiovascular and surgical portfolio to cross-sell temperature management systems into integrated delivery networks. Stryker Corporation sustains orthopedic-OR dominance by embedding warming and cooling protocols into procedural kits. Drägerwerk AG & Co. KGaA anchors its position through anesthesia workstation integration, where temperature modules become standard rather than optional configurations.
Temperature management encompasses active and passive systems that regulate patient core and surface temperature through conductive, convective, radiative, or thermoelectric heat transfer, typically maintaining normothermia within 36.0–37.5°C during surgical, critical care, or neonatal interventions. Cooling systems lead product type revenue due to high unit costs in cardiac surgery and neurocritical care, while temperature monitoring devices represent the fastest-growing category as continuous wireless patch sensors displace intermittent spot measurements. Among applications, operating rooms occupy the largest installed base, though intensive care units are gaining share as sepsis protocols and targeted temperature management after cardiac arrest expand monitoring requirements.
The FDA enforces 510(k) clearance for patient warming and cooling devices with specific thermal uniformity and alarm performance standards, while the EU MDR requires renewed clinical evidence and notified body oversight for legacy warming blankets and surface pads. Japan's PMDA maintains distinct thermal safety testing protocols that delay entry for non-Japanese manufacturers without local partnership structures. Stakeholders must monitor how FDA draft guidance on software-as-a-medical-device applies to next-generation closed-loop temperature control algorithms.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating the importance of bundled service contracts and integrated device ecosystems across integrated delivery networks.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation mandates renewed clinical evidence for legacy warming devices, creating replacement demand for notified body-certified systems across German and French hospital systems.
- Perioperative normothermia protocols:Surgical societies in the United States and Japan now mandate continuous temperature monitoring for procedures exceeding 30 minutes, expanding installed base requirements in ambulatory surgical centers.
- Wireless patch sensors:Continuous thermometry using adhesive skin patches is displacing intermittent bladder and esophageal probes in post-anesthesia care units, driving hardware refresh cycles.
Market Restraints
- Copper and silver thermal interface materials:Volatility in conductive metal prices compresses gross margins for heating and cooling pad manufacturers by 12-18% during commodity spikes.
- Japanese thermal safety testing:PMDA protocols require 18-24 month validation timelines for surface warming devices without local partnership structures, gating market entry.
- Passive insulation alternatives:Forced-air warming blanket substitutes using reflective polymer materials capture 15-20% of low-acuity surgical volume in cost-constrained settings.
Strategic Opportunities
- India's hospital infrastructure expansion:Government-funded medical college hospitals under the Pradhan Mantri Swasthya Suraksha Yojana lack temperature management infrastructure, creating greenfield installation demand.
- Neonatal intensive care convergence:Integration of servo-controlled incubators with MRI-compatible warming systems addresses the 8-12% of NICU transfers requiring magnetic resonance imaging.
- Remote patient monitoring channels:Direct-to-hospital distribution platforms bypassing traditional device distributors capture 22-25% of temperature monitoring device sales in Nordic countries.
Industry Challenges
- Biomedical engineering specialization:Shortage of technicians qualified to service closed-loop temperature control algorithms delays field deployment of next-generation systems.
- ISO 80601-2-56 certification timelines:Third-party testing for thermal uniformity and alarm performance extends product launch schedules by 14-18 months.
- Anesthesia workstation interoperability:Proprietary communication protocols between Drägerwerk and GE Healthcare systems force hospitals into single-vendor temperature module commitments.
Report Scope
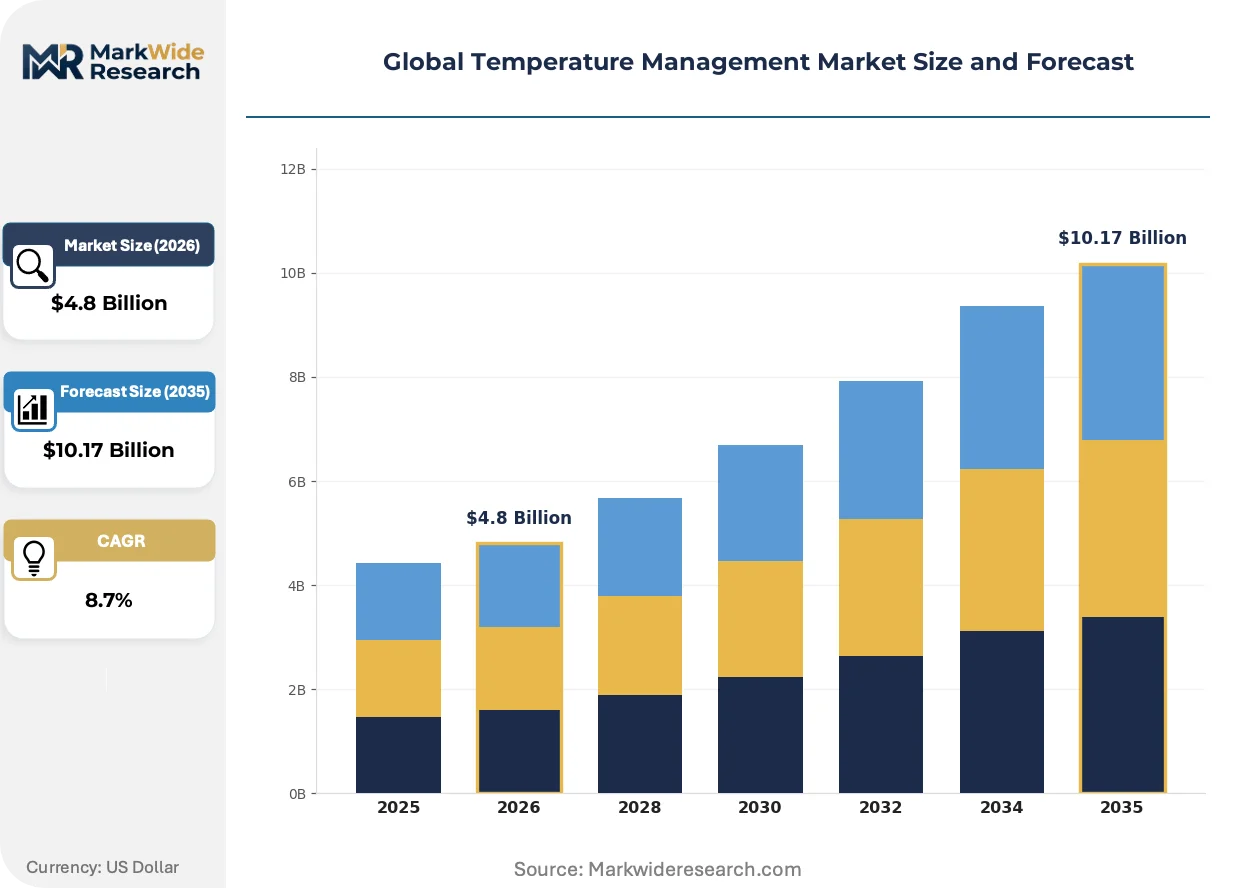
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Temperature Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Systems, Cooling Systems, Temperature Monitoring Devices, Temperature Control Units End User: Hospitals, Clinics, Laboratories, Home Care Technology: Conduction, Convection, Radiation, Thermoelectric Application: Operating Rooms, Intensive Care Units, Recovery Rooms, Emergency Departments |
| Companies Covered | Medtronic PLC, Stryker Corporation, Becton, Dickinson and Company, 3M Company, Drägerwerk AG & Co. KGaA, GE Healthcare, ZOLL Medical Corporation, Asahi Kasei Corporation, ICU Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Temperature Management Market Emerging Trajectories
Digital thermometry architectures and closed-loop control algorithms are restructuring how perioperative teams monitor and intervene on patient temperature, shifting from reactive spot-checking to predictive normothermia maintenance.
Thermoelectric cooling modules using bismuth telluride semiconductor junctions are replacing compressor-based systems in neurocritical care applications. Academic medical centers in Germany and the United States are adopting these solid-state devices for targeted temperature management after cardiac arrest. The technology is integrating with electronic health record systems to enable automated documentation of cooling curve compliance, reducing nursing documentation burden by approximately 40%.
The EU MDR's renewed clinical evidence requirements for legacy surface warming devices is forcing manufacturers to conduct post-market clinical follow-up studies. This regulatory pressure is accelerating consolidation among mid-tier warming blanket producers who lack the capital to fund 500+ patient safety trials. Cardiac surgery centers in France and Italy are prioritizing MDR-certified intravascular warming systems to preempt supply disruption.
Ambulatory surgical centers are unbundling temperature management from anesthesia service contracts and purchasing devices directly through group purchasing organizations. This buyer behavior change is compressing sales cycles from 18 months to 6-8 weeks for standard warming blankets. The shift is most pronounced in United States metropolitan markets where ASC chains operate 50+ facilities and negotiate enterprise-wide pricing.
Global Temperature Management Market Segmentation
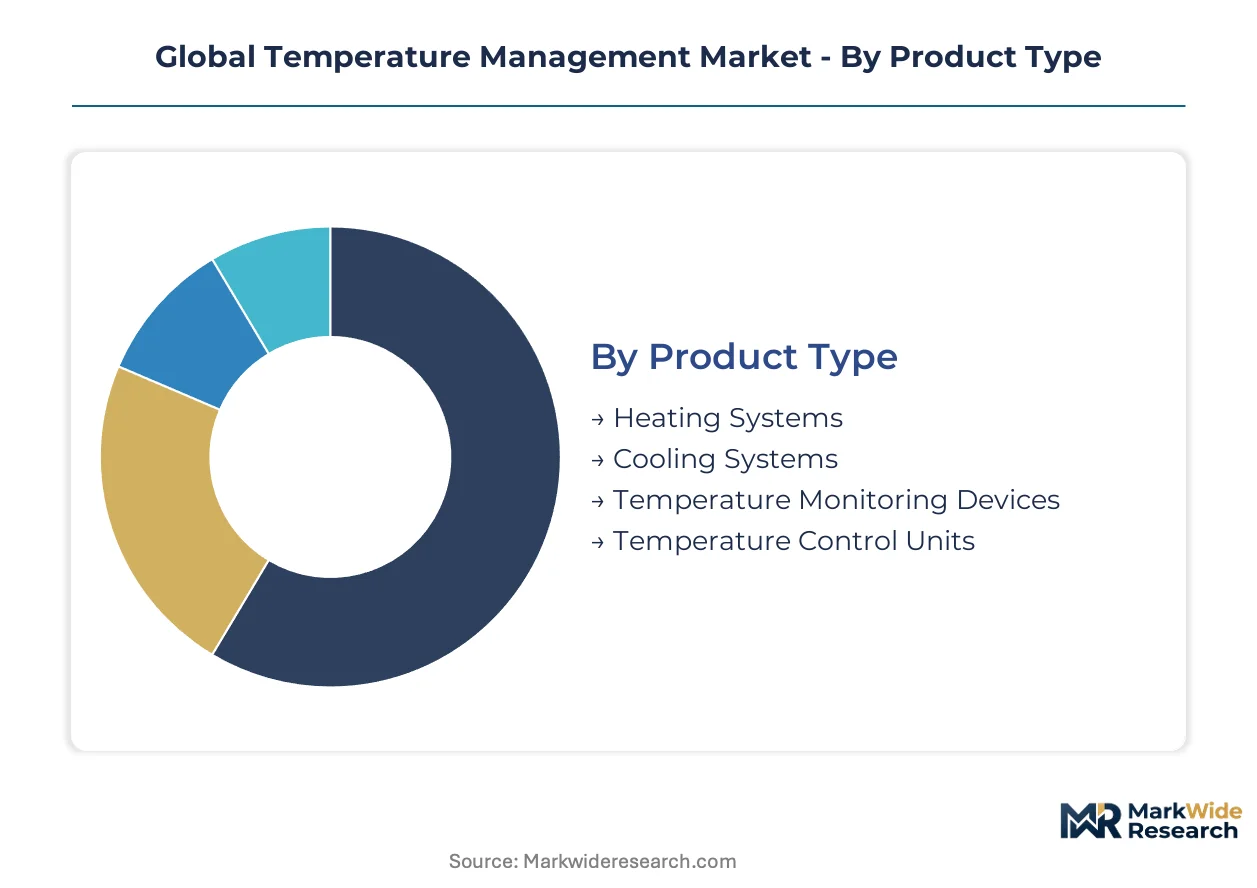
Temperature management markets fragment across four critical dimensions: thermal modality, care setting, heat transfer physics, and clinical workflow integration. Each segmentation axis carries distinct regulatory burdens and procurement pathways that reshape competitive positioning.
Product Type:
EU MDR compliance deadlines and FDA 510(k) thermal uniformity standards impose divergent certification timelines across hardware categories, with surface devices facing renewed clinical evidence requirements while intravascular systems navigate predicate device pathways.
- Cooling Systems:Compressor-based and thermoelectric architectures regulate core temperature during cardiac surgery and targeted temperature management after cardiac arrest. German and United States academic medical centers prioritize solid-state bismuth telluride modules for neurocritical care applications where precise cooling curve compliance reduces nursing documentation burden.
- Temperature Monitoring Devices:Continuous wireless patch sensors using adhesive skin interfaces displace intermittent bladder and esophageal probes in post-anesthesia care units. Japanese PMDA thermal safety testing protocols create 18-24 month validation gates for non-local manufacturers, concentrating demand among notified body-certified European suppliers.
- Heating Systems:Forced-air warming blankets and conductive surface pads maintain perioperative normothermia. Reflective polymer insulation alternatives capture low-acuity surgical volume in cost-constrained ambulatory settings.
- Temperature Control Units:Closed-loop algorithms integrated with anesthesia workstations automate normothermia maintenance. Proprietary communication protocols between major workstation vendors force single-vendor commitments.
Cooling Systems sits at the top of the volume ranking, with Temperature Monitoring Devices climbing the fastest.
End User:
Procurement authority concentrates differently across settings: integrated delivery networks negotiate enterprise contracts for hospital systems, while ambulatory chains purchase through group purchasing organizations with compressed 6-8 week sales cycles.
- Hospitals:Operating rooms and intensive care units drive installed base requirements as surgical societies mandate continuous temperature monitoring for procedures exceeding 30 minutes. Consolidated procurement across United States metropolitan systems elevates bundled device-and-service contracts.
- Clinics:Ambulatory surgical centers unbundle temperature management from anesthesia service contracts and purchase directly, particularly in United States markets where ASC chains operate 50+ facilities.
- Laboratories:Research and pharmaceutical testing applications require precise thermal control for biological sample integrity.
- Home Care:Remote patient monitoring channels bypass traditional distributors in Nordic countries, capturing direct-to-hospital device sales.
Hospitals command the dominant revenue share, with Clinics expanding most quickly as ambulatory surgical protocols proliferate.
Technology:
Heat transfer physics determines capital intensity and maintenance requirements, with thermoelectric semiconductors offering solid-state reliability against compressor-based cooling infrastructure.
- Conduction:Conductive polymer and gel-based surface pads transfer heat through direct patient contact. Copper and silver thermal interface materials face commodity price volatility that compresses manufacturer margins.
- Convection:Forced-air warming blankets dominate perioperative normothermia protocols through convective heat transfer.
- Thermoelectric:Bismuth telluride semiconductor junctions enable precise temperature control without compressor maintenance. Integration with electronic health record systems automates cooling curve documentation.
- Radiation:Infrared and radiative warming systems serve niche neonatal and specialized applications.
Conduction holds the largest installed base, with Thermoelectric gaining share fastest as solid-state reliability displaces compressor maintenance burdens.
Application:
Clinical workflow integration varies by acuity level, with operating rooms requiring rapid thermal intervention capability while intensive care units prioritize continuous monitoring over hours to days.
- Operating Rooms:Surgical suites require active warming and cooling systems with rapid response capability for cardiac and neurosurgical procedures. Perioperative normothermia protocols now mandate temperature management for cases exceeding 30 minutes.
- Intensive Care Units:Sepsis protocols and targeted temperature management after cardiac arrest expand monitoring requirements. Continuous wireless patch sensors displace intermittent measurements in post-cardiac arrest cooling.
- Recovery Rooms:Post-anesthesia care units prioritize patient rewarming and thermal stability before discharge.
- Emergency Departments:Trauma and cardiac arrest protocols require rapid cooling initiation capability.
Operating Rooms dominates the installed base, with Intensive Care Units showing the steepest expansion trajectory as sepsis and post-arrest protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Massachusetts, Baden-Württemberg, and Osaka-Kyoto anchor temperature management innovation pipelines. These concentrations feed device manufacturers with thermal control algorithm specialists and regulatory compliance expertise.
United States
Integrated delivery networks in metropolitan markets negotiate bundled device-and-service contracts for perioperative warming systems. The FDA enforces 510(k) thermal uniformity standards that delay product launches by 14-18 months. Greater Boston's medical device corridor hosts algorithm development for closed-loop temperature control.
Germany
Academic medical centers in Bavaria and Baden-Württemberg prioritize solid-state thermoelectric cooling for neurocritical care applications. The EU MDR mandates renewed clinical evidence for legacy warming blankets, accelerating replacement demand. The Tübingen-Stuttgart corridor concentrates notified body-certified manufacturing.
Japan
Tokyo and Osaka surgical societies mandate continuous temperature monitoring for procedures exceeding 30 minutes. The PMDA requires 18-24 month thermal safety validation timelines for surface warming devices without local partnerships. The Kansai region hosts joint ventures between domestic distributors and European manufacturers.
India
Government-funded medical college hospitals under the Pradhan Mantri Swasthya Suraksha Yojana lack temperature management infrastructure entirely. The CDSCO regulates imported devices through import license requirements that favor notified body-certified suppliers. Maharashtra's private hospital chains in Mumbai and Pune drive premium device procurement.
United Kingdom
NHS procurement frameworks consolidate buying power for temperature monitoring devices across acute trusts. The MHRA aligns with EU MDR transitional provisions for legacy warming blanket recertification. The Cambridge-London corridor concentrates wireless patch sensor development for post-anesthesia applications.
Global Temperature Management Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct procurement channels. Hospital procurement consolidation favors vendors offering bundled device-and-service contracts spanning multiple therapeutic areas. Three strategic archetypes dominate: cardiovascular-surgical portfolio cross-sellers, anesthesia workstation integrators, and orthopedic-OR procedural kit embedders. M&A activity targets mid-tier warming blanket producers lacking capital for EU MDR compliance trials. Geographic expansion through local partnership structures accelerates entry into Japanese and Indian markets.
Among diversified medical technology conglomerates, Medtronic PLC and Stryker Corporation exemplify portfolio breadth strategies. Medtronic leverages cardiovascular and surgical assets to cross-sell temperature management systems into integrated delivery networks. Stryker sustains orthopedic operating room presence by embedding warming protocols into procedural kits. Drägerwerk AG & Co. KGaA anchors the anesthesia workstation integration archetype, where temperature modules become standard rather than optional configurations.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Becton, Dickinson and Company |
| 3M Company |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| ZOLL Medical Corporation |
| Asahi Kasei Corporation |
| ICU Medical, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in the temperature management sector have consolidated mid-tier warming blanket producers, concentrating supply-side ownership among three dominant holding structures while enforcing pricing discipline through centralized procurement negotiations and standardized service bundling.
Pricing Analysis
The bundled-vs-unbundled service split determines pricing architecture across hospital systems and ambulatory surgical centers. Integrated delivery networks negotiate three-tier pricing structure across premium, standard, and economy levels based on ISO 80601-2-56 certification grade and after-sales service intensity. Cost compression in economy-tier surface warming devices is intensifying because reflective polymer insulation alternatives capture low-acuity surgical volume. Ambulatory surgical centers exhibit highest price sensitivity due to direct group purchasing organization procurement, while academic medical centers in Germany and the United States demonstrate lowest sensitivity for thermoelectric cooling modules with EHR integration.
Supply Chain Analysis
Direct-to-hospital distribution platforms bypassing traditional device distributors handle Nordic market demand, while authorized medical device distributors serve hospital procurement consolidation in North America and Western Europe. Manufacturing concentrates in Germany, the United States, and Japan for thermoelectric semiconductor modules and closed-loop control systems. Supply chains draw from copper and silver thermal interface materials, bismuth telluride semiconductor junctions, and conductive polymer substrates. Single-source vulnerability in Japanese PMDA-certified component supply creates 18-24 month validation gates for non-local manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in temperature management hinges on thermoelectric module adoption displacing compressor-based cooling infrastructure, reducing field service costs while commanding premium positioning in neurocritical care applications.
For Market Incumbents: Anchor bundled device-and-service contracts across integrated delivery networks to preempt ambulatory surgical center unbundling. Deepen backward integration into bismuth telluride semiconductor supply to offset copper and silver commodity volatility. Prioritize EU MDR notified body certification investment to capture replacement demand from mid-tier warming blanket producers lacking clinical trial capital. For New Entrants and Emerging Players: Group purchasing organizations serving United States metropolitan ambulatory surgical center chains represent the most penetrable channel partner type for rapid market entry. Target India's government-funded medical college hospitals under the Pradhan Mantri Swasthya Suraksha Yojana for greenfield installation demand. Pursue joint venture structures with Japanese domestic distributors to circumvent PMDA thermal safety validation timelines. For Investors and Strategic Acquirers: Anesthesia workstation integrators are the most active acquirer in this space, seeking temperature control module capabilities to embed as standard configurations. Mid-tier warming blanket producers facing EU MDR compliance funding gaps represent prime acquisition targets over the five-to-ten year regulatory transition window. Monitor wireless patch sensor FDA 510(k) clearance velocity as inflection indicator for continuous thermometry displacement of intermittent probe measurements.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification | MDR-certified intravascular warming systems preempt supply disruption in French and Italian cardiac surgery centers. |
| Anesthesia Workstation Integration | Temperature modules become standard configurations in Drägerwerk and GE Healthcare systems, forcing single-vendor commitments. |
| Wireless Patch Sensor Development | Continuous adhesive skin thermometry displaces intermittent bladder and esophageal probes in post-anesthesia care units. |
| Indian Joint Venture Formation | Local partnership structures accelerate CDSCO import license navigation for government-funded hospital infrastructure expansion. |
| Thermoelectric Cooling Scale-Up | Solid-state bismuth telluride modules reduce nursing documentation burden through automated EHR cooling curve compliance. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and anesthesia department heads with secondary validation against FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement contracts, and CMS Medicare reimbursement data. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates across product categories.
Historical reference periods anchored demand trajectory assumptions over the projection horizon, with segmentation modeling across thermal modality, care setting, heat transfer physics, and clinical workflow integration dimensions. CAGRs derived from surgical volume recovery patterns, ambulatory surgical center expansion rates, and regulatory compliance deadline clustering. Forecast inputs incorporated EU MDR transition timelines, Japanese PMDA validation protocols, and copper commodity price volatility indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biomedical engineering talent availability, ISO 80601-2-56 certification backlog duration, and anesthesia workstation interoperability standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Global Resource Circulation Equipment Market
Environment & Sustainability
Point of Use Water Treatment Systems Market
Environment & Sustainability
India Desalination Systems Market
Environment & Sustainability
Global Enhanced Water Market
Environment & Sustainability
Radioactive Waste Management System Market
Environment & Sustainability
Medical Waste Management System Market
Environment & Sustainability
Medical Waste Management Equipment Market
Environment & Sustainability
Global Smart Trash Bin Market
Environment & Sustainability
Europe Carbon Dioxide Market
Environment & Sustainability
Air Pollution Control Equipment Market
Environment & Sustainability
US Water Purifier Market
Environment & Sustainability
Commercial Water Filter Market
Environment & Sustainability
Global Tire Recycling Market
Environment & Sustainability
Construction and Demolition Waste Management Market
Environment & Sustainability
LAMEA Emission Monitoring System Market
Environment & Sustainability
Greenhouse and Smart Greenhouse Market