
 Enterprise Rights Management Solution Market | 2026-2036
Enterprise Rights Management Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Rights Management Solution Market Foresight
The gap between premium cloud-native rights management suites and commodity on-premises licensing is expanding across enterprise procurement cycles. Microsoft leverages its Azure ecosystem to anchor multi-tenant encryption services for Fortune 500 accounts. Seclore specializes in granular policy enforcement for regulated document workflows. Fasoo dominates Korean chaebol deployments through deep metadata classification capabilities.
Enterprise rights management solutions enforce persistent access controls, encryption, and usage policies across documents, emails, and unstructured data repositories through policy servers, client agents, and cryptographic wrappers. The primary commercial purpose is preventing unauthorized extraction, forwarding, or editing of sensitive intellectual property regardless of file location or recipient. Cloud-based deployment captures the fastest expansion trajectory as organizations retire legacy perimeter security models. Document security solutions command the deepest margin pools due to persistent renewal dynamics in legal and financial verticals. API integration capabilities increasingly determine vendor selection as enterprises embed rights logic directly into SaaS workflows.
FDA 21 CFR Part 11, HIPAA Security Rule, and EU GDPR collectively mandate audit-ready access trails for regulated documents, directly shaping product roadmaps and procurement checklists. The SEC's cybersecurity disclosure rules now require public companies to document data protection controls, extending compliance-driven demand beyond traditional privacy jurisdictions. Stakeholders must monitor how generative AI content generation reshapes exfiltration risk models and policy granularity requirements.
Market Dynamics
The migration from perimeter-based security to zero-trust architectures is compressing procurement cycles for persistent document protection, forcing enterprises to embed encryption and policy enforcement directly into cloud-native workflows rather than retrofitting legacy infrastructure.
Growth Catalysts
- EU AI Act enforcement:Automated content generation mandates audit-ready lineage tracking, accelerating investment in granular metadata classification systems across financial services and legal sectors in Germany and France.
- Automotive IP protection:German industrial conglomerates face intensifying industrial espionage targeting electric vehicle battery formulations and autonomous driving algorithms, driving classified document vault deployments.
- Cloud-native policy engines:API-first encryption services enable real-time rights enforcement within SaaS productivity suites, collapsing deployment timelines from months to weeks for mid-market legal practices.
Market Restraints
- Legacy system integration costs:On-premises document management repositories in regulated healthcare and government sectors require costly cryptographic wrapper development, inflating total cost of ownership by 40-60% versus greenfield cloud deployments.
- Key management complexity:Multi-cloud key escrow fragmentation across AWS, Azure, and Google Cloud environments creates operational overhead that stalls enterprise-wide standardization initiatives.
- Skilled workforce scarcity:Shortage of cryptographers and policy engine architects in North American and European labor markets extends implementation timelines and inflates professional services margins.
Strategic Opportunities
- Generative AI content governance:Synthetic media provenance tracking and LLM output watermarking represent unmet demand as enterprises deploy Copilot and ChatGPT Enterprise without adequate exfiltration controls.
- India's data localization mandates:RBI and SEBI compliance requirements for financial data residency create captive demand for sovereign cloud rights management infrastructure in Mumbai and Bangalore data center clusters.
- Embedded SDK licensing:ISV partnerships enable native rights enforcement within vertical SaaS applications for architecture, engineering, and construction document workflows without standalone client deployment.
Industry Challenges
- Cross-border key escrow fragmentation:Conflicting data sovereignty requirements between EU GDPR, China's PIPL, and Russia's data localization laws prevent unified global policy enforcement for multinational enterprises.
- User experience friction:Persistent encryption often degrades mobile document rendering and offline access, triggering shadow IT workarounds that undermine security posture in field sales and executive travel contexts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Rights Management Solution Market |
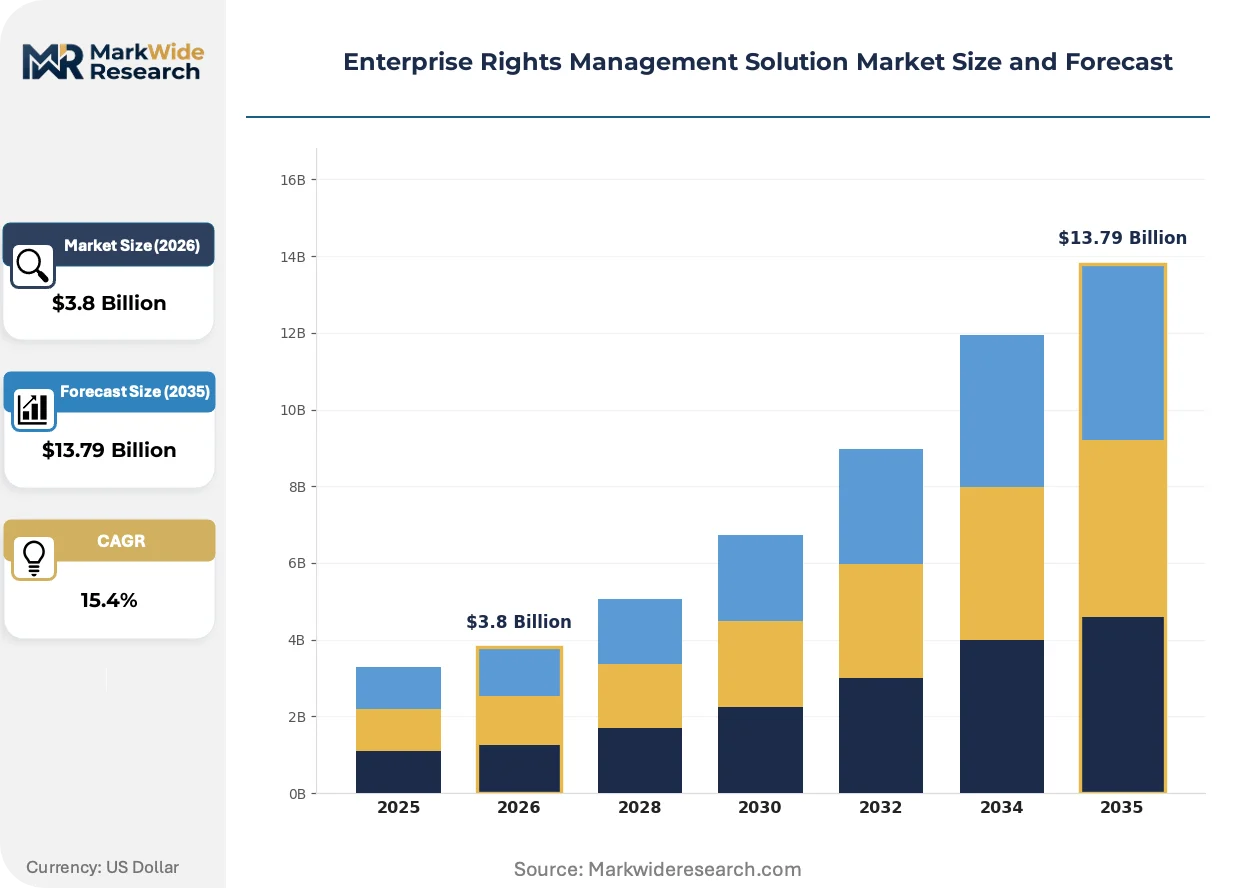
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $13.79 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service Solution Type: Document Security, Digital Rights Management, Access Control, Information Protection End User: Enterprises, Government Agencies, Educational Institutions, Healthcare Providers Integration Level: API Integration, User Interface, Third-Party Solutions, Sandbox Integration |
| Companies Covered | Microsoft, Adobe, Oracle, IBM, Seclore, Dell Technologies, SAP, OpenText, Fasoo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Rights Management Solution Market Shifts & Advancements
Attribute-based access control (ABAC) architectures are supplanting role-based models, enabling dynamic policy resolution from real-time user context, document sensitivity, and environmental risk signals rather than static entitlement matrices.
Confidential computing enclaves are rewriting how encryption keys and policy decisions are protected. Hardware-isolated execution environments in Azure Confidential Computing and AWS Nitro Enclaves enable key operations without cloud provider visibility. Financial services firms in London and Singapore are piloting enclave-based document decryption for M&A transaction rooms, compressing vendor security review cycles from quarters to weeks.
SEC cybersecurity disclosure rules now mandate public companies document data protection controls in 8-K filings, extending compliance-driven procurement beyond traditional privacy jurisdictions. The regulation forces CISOs to demonstrate persistent access control coverage across unstructured data repositories, directly shaping RFP requirements for audit-ready policy logs and automated compliance reporting dashboards in US capital markets.
Buyer concentration among Fortune 500 legal departments is compressing vendor switching cycles from multi-year enterprise agreements to annual subscription renewals with proof-of-concept gates. Procurement teams now demand API-native integration with existing matter management and e-discovery platforms, displacing standalone rights management suites that require client agent deployment. This pattern is most visible in New York and London legal markets where managing partners face malpractice carrier pressure to demonstrate document protection attestation.
Enterprise Rights Management Solution Market Segmentation
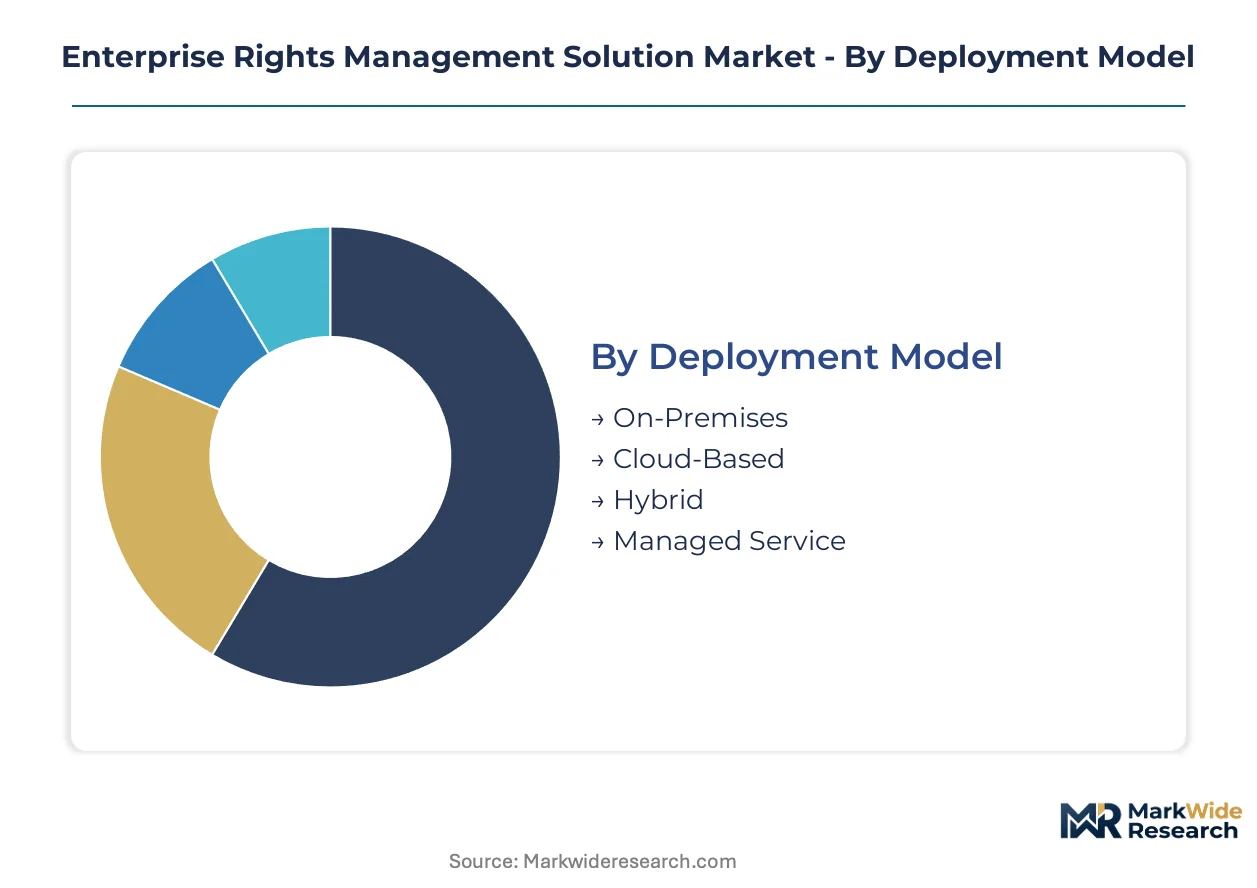
Enterprise rights management procurement splits sharply across infrastructure maturity and regulatory exposure. Deployment architecture determines total cost of ownership and implementation timelines. Solution specialization reflects vertical compliance intensity.
Deployment Model:
Capital intensity varies dramatically across deployment architectures, with cloud-native platforms requiring minimal upfront infrastructure versus on-premises builds demanding dedicated hardware and cryptographic modules.
- Cloud-Based:Multi-tenant encryption services eliminate data center provisioning. Financial services firms in Germany and France prioritize this model to compress EU AI Act compliance timelines.
- On-Premises:Dedicated policy servers and hardware security modules serve air-gapped environments. Healthcare providers under HIPAA Security Rule mandates retain this architecture for patient record vaults despite higher capital requirements.
- Hybrid:Split workloads between cloud policy engines and on-premises key escrow. Government agencies use this for classified-unclassified document workflows.
- Managed Service:Third-party operational responsibility for policy administration and key lifecycle. Mid-market legal practices adopt this to bypass cryptographer hiring constraints.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Managed Service as professional services margins deter in-house builds.
Solution Type:
Margin profiles diverge based on renewal persistence and integration depth, with document security commanding premium pricing due to legal sector dependency.
- Document Security:Persistent encryption and usage policy enforcement for unstructured files. Law firms in New York and London generate concentrated demand amid malpractice carrier pressure for protection attestation.
- Access Control:Identity verification and entitlement management for data repositories. Healthcare providers deploy this for HIPAA audit-ready access trails across electronic health record systems.
- Digital Rights Management:Media and software content protection through license enforcement. Publishing and entertainment verticals retain specialized demand here.
- Information Protection:Broad-spectrum data classification and loss prevention. Enterprises adopt this as a catch-all for shadow IT coverage.
Document Security captures the deepest margin pools. Information Protection is expanding most quickly as generative AI output governance creates new policy granularity requirements.
End User:
Procurement sophistication scales with regulatory scrutiny intensity and incident liability exposure.
- Enterprises:Fortune 500 legal departments and R&D divisions with global policy enforcement needs. Automotive conglomerates in Germany anchor demand for IP vaults protecting battery and autonomous driving algorithms.
- Government Agencies:Classified document handling with sovereign cloud requirements. Defense and intelligence sectors drive sandbox integration specifications.
- Healthcare Providers:HIPAA-covered entities requiring patient data encryption. Hospital systems prioritize audit-ready access logs for OCR enforcement actions.
- Educational Institutions:Research data protection and student record privacy. University technology transfer offices adopt limited deployments for patent filing workflows.
Enterprises host the majority of deployed seats. Healthcare Providers show the steepest expansion trajectory as SEC cybersecurity disclosure rules extend compliance requirements to hospital systems.
Integration Level:
Technical architecture choices determine vendor switching costs and workflow embedding depth.
- API Integration:Native rights enforcement within SaaS productivity suites and matter management platforms. Legal departments now mandate this capability for annual renewal decisions.
- User Interface:Standalone client applications for policy administration and document access. Legacy deployments in regulated manufacturing retain this model.
- Third-Party Solutions:Embedded rights logic within vertical SaaS applications. Architecture and engineering document workflows adopt this through ISV partnerships.
- Sandbox Integration:Isolated execution environments for high-assurance decryption. Financial services M&A transaction rooms in London and Singapore pilot confidential computing enclaves.
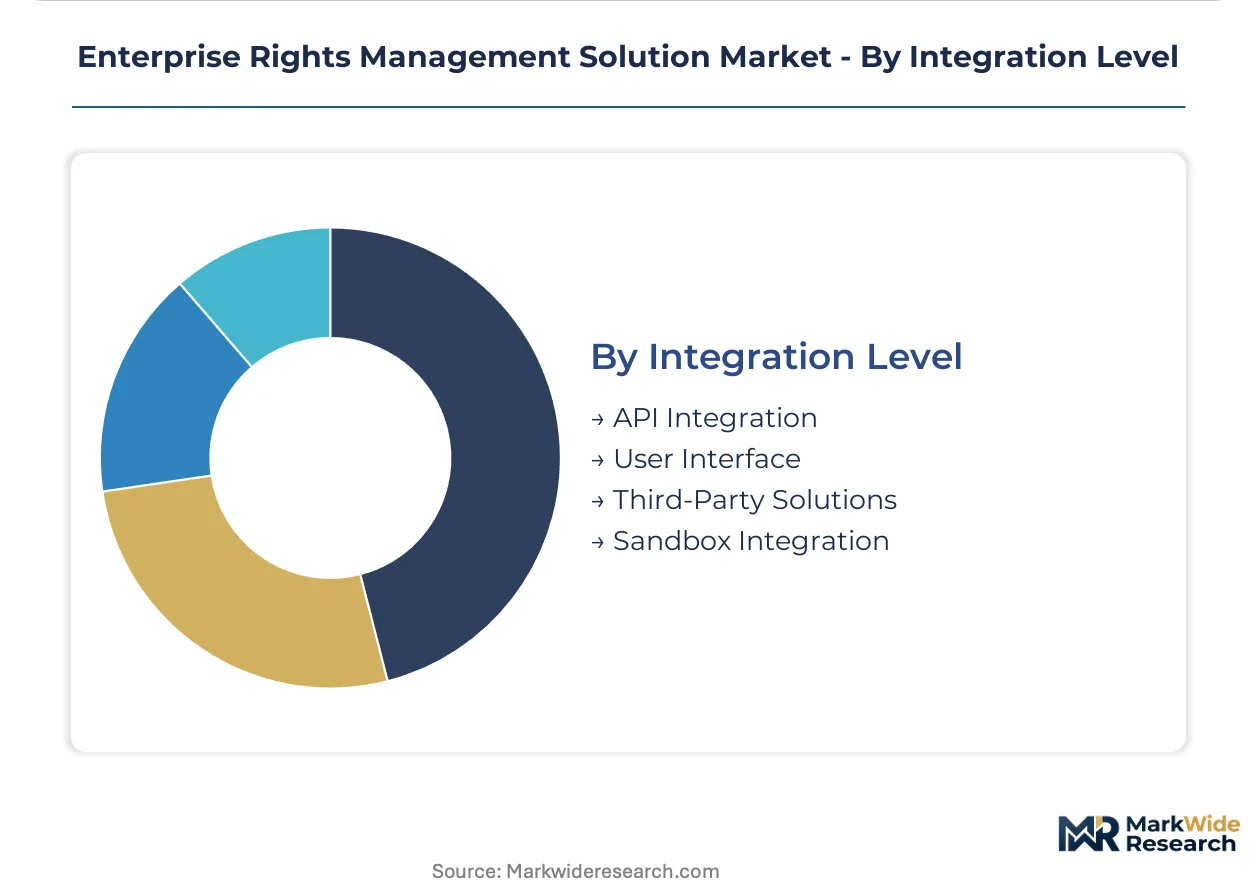
API Integration carries the dominant deployment share. Sandbox Integration is climbing the fastest as confidential computing hardware matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise rights management adoption diverges sharply between regulatory jurisdictions, with German automotive conglomerates deploying IP vaults at triple the per-capita investment rate of Japanese manufacturing peers. Compliance architecture—not market size—determines procurement velocity.
United States
SEC cybersecurity disclosure rules now mandate 8-K filings documenting data protection controls, forcing CISOs at Fortune 500 legal departments to demonstrate persistent access coverage. FDA 21 CFR Part 11 shapes product roadmaps for pharmaceutical document workflows. New York and London legal markets anchor demand as managing partners face malpractice carrier pressure for protection attestation.
Germany
EU AI Act enforcement mandates audit-ready lineage tracking for automated content generation, accelerating granular metadata classification investment across financial services. GDPR compliance requirements extend to synthetic media provenance. Stuttgart and Munich industrial clusters deploy classified document vaults protecting electric vehicle battery formulations from intensifying espionage targeting.
United Kingdom
Financial services firms in the City of London pilot confidential computing enclaves for M&A transaction rooms, compressing vendor security review cycles. The Information Commissioner's Office enforcement posture shapes audit-ready access log requirements. Legal technology clusters in London and Manchester drive API-native integration demands with matter management platforms.
India
RBI and SEBI data localization mandates for financial data residency create captive demand for sovereign cloud rights management infrastructure. Mumbai and Bangalore data center clusters host expanding policy engine deployments. Domestic IT services firms embed rights logic into vertical SaaS applications for architecture and engineering document workflows.
South Korea
Chaebol conglomerates anchor demand through deep metadata classification capabilities for intellectual property protection. MFDS pharmaceutical regulations shape audit trail requirements for clinical documentation. Seoul Capital Area technology clusters drive hybrid deployment architectures splitting cloud policy engines from on-premises key escrow.
Enterprise Rights Management Solution Market Competitive Landscape
Top-tier vendors anchor the cloud-native encryption services tier, while specialized policy engine architects occupy the mid-market professional services niche. The vendor base stratifies across three functional layers: hyperscale platform providers with multi-tenant infrastructure, regional specialists in granular metadata classification, and managed service operators bypassing enterprise hiring constraints. Competitive positioning crystallizes around API integration depth and confidential computing hardware partnerships. Dominant moves include ISV licensing agreements embedding rights logic into vertical SaaS workflows and M&A targeting cryptographic key management capabilities.
Within the cloud platform tier, Microsoft leverages Azure ecosystem anchoring for Fortune 500 multi-tenant encryption services. Seclore occupies a position exemplifying granular policy enforcement specialization for regulated document workflows. Fasoo represents the regional specialist archetype with Korean chaebol deployment concentration through metadata classification depth.
| Leading Market Players |
|---|
| Microsoft |
| Adobe |
| Oracle |
| IBM |
| Seclore |
| Dell Technologies |
| SAP |
| OpenText |
| Fasoo |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates for audit-ready lineage tracking gate qualified supply for premium-tier rights management platforms, compressing vendor eligibility to those with certified confidential computing partnerships while elevating pricing floors for cloud-native policy engines serving German automotive and French financial services buyers.
Pricing Analysis
Capacity additions in India's Mumbai and Bangalore data center clusters are reshaping price floors for sovereign cloud rights management infrastructure, intensifying cost competition against incumbent Azure and AWS multi-tenant services. Three-tier pricing structure across premium confidential computing enclaves, standard API-integrated policy engines, and economy managed service bundles dominates procurement. Price differentiation rests on certification depth for EU AI Act and GDPR audit readiness versus basic HIPAA Security Rule alignment. Cost compression in the mid-market tier is intensifying because domestic Indian IT services firms embed rights logic into vertical SaaS applications at fractional licensing cost. Mid-market legal practices exhibit highest price sensitivity due to cryptographer hiring constraints, while Fortune 500 legal departments in New York and London demonstrate lowest sensitivity amid malpractice carrier pressure.
Supply Chain Analysis
Dual-sourcing requirements from German automotive conglomerates and US financial services firms mandate multi-supplier qualification across cloud policy engines, hardware security modules, and cryptographic key management layers. Geographic supply concentration centers on the United States for hyperscale cloud infrastructure, Germany for industrial-grade hardware security modules, and India for sovereign cloud policy engine development. Raw material dependencies include specialized semiconductors for confidential computing enclaves, cryptographic accelerators for hardware-isolated execution, and rare earth elements for hardware security module fabrication. Supply chain risk runs through single-source vulnerability for confidential computing hardware from AWS Nitro and Azure isolated environments. Distribution feeds from direct enterprise sales for Fortune 500 accounts, ISV partnerships for embedded SDK licensing, and managed service operators for mid-market legal practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU AI Act enforcement accelerating premium pricing in Stuttgart and Munich versus India's data localization mandates creating cost-competitive sovereign cloud alternatives at 40-60% lower total cost of ownership.
For Market Incumbents: Extend confidential computing enclave partnerships to compress vendor security review cycles for financial services M&A transaction rooms in London and Singapore. Anchor multi-tenant encryption services through deeper API integration with matter management platforms to displace standalone client agent deployments. Vertical integration into cryptographic key management capabilities addresses multi-cloud key escrow fragmentation that stalls enterprise-wide standardization initiatives. Capacity additions in Indian data center clusters provide defensive cost positioning against domestic IT services firms embedding rights logic into vertical SaaS applications. For New Entrants and Emerging Players: API-native rights enforcement for generative AI output governance represents the most penetrable white-space target as enterprises deploy Copilot and ChatGPT Enterprise without adequate exfiltration controls. India's sovereign cloud infrastructure for RBI and SEBI data localization compliance offers geographic entry with captive financial services demand. Embedded SDK licensing partnerships with architecture, engineering, and construction SaaS vendors provide go-to-market velocity without standalone client deployment friction. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with deep metadata classification capabilities and concentrated chaebol or conglomerate customer relationships. Long-term viability over a 5-10 year window hinges on API integration depth and confidential computing hardware partnerships displacing legacy perimeter security models. Acquisition target archetype: policy engine architects with granular enforcement specialization for regulated document workflows and existing ISV partnership networks. The signal to watch is generative AI content governance procurement velocity as synthetic media provenance tracking reshapes policy granularity requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Partnership | Hardware-isolated execution environments in Azure and AWS compress vendor security review cycles for financial services M&A rooms. |
| API-Native Platform Integration | Native rights enforcement within SaaS productivity suites displaces standalone client agent deployments in legal technology procurement. |
| ISV Embedded SDK Licensing | Architecture and engineering SaaS partnerships enable rights logic embedding without standalone client deployment friction. |
| Sovereign Cloud Infrastructure Buildout | Mumbai and Bangalore data center clusters address RBI and SEBI data localization mandates for financial services compliance. |
| Generative AI Governance Capability | Synthetic media provenance tracking and LLM output watermarking address unmet exfiltration control demand in Copilot deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CISOs at Fortune 500 legal departments, cloud platform engineers at hyperscale providers, policy engine architects at specialized vendors, and procurement officers at German automotive conglomerates with secondary validation against SEC cybersecurity disclosure filings, EU AI Act regulatory texts, FDA 21 CFR Part 11 guidance documents, and RBI data localization circulars. Bottom-up seat deployment estimates across deployment architectures triangulated against top-down addressable market sizing for unstructured data protection spend.
Segment-weighting approaches modeled deployment architecture splits across cloud-native, on-premises, hybrid, and managed service tiers alongside solution type differentiation between document security, access control, digital rights management, and information protection categories. CAGRs derived from regression analysis of historical procurement velocity against regulatory enforcement timelines and cloud migration patterns. Forecast inputs incorporated EU AI Act implementation phases, SEC cybersecurity disclosure rule adoption curves, and confidential computing hardware availability roadmaps from AWS and Azure.
The model assumes a particular technology adoption path; alternative pathways for zero-trust architecture migration or generative AI content governance standardization would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement intensity, cloud provider capex allocation to confidential computing infrastructure, and enterprise willingness to retire legacy perimeter security investments. Deviation in EU AI Act audit requirement timelines or multi-cloud key escrow standardization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Smartphone Security Market
Security Software
Certificate Authority Market
Security Software
Business Email Compromise (BEC) Market
Security Software
Anti-Money Laundering (AML) Software Solution Market
Security Software
Stalkerware Market
Security Software
E Passport Market
Security Software
Geofencing Market
Security Software
Mass Notification System Market
Security Software
Cloud Intrusion Protection Software Market
Security Software
Secaas Market
Security Software
Spain Endpoint Detection and Response Market
Security Software
Global SMS Firewall Market
Security Software
Global Electronic Offender Monitoring Solutions Market
Security Software
Parental Monitoring Software Market
Security Software
Video Intercom Devices Market
Security Software
Endpoint Detection and Response [EDR] Market