
 Global Presentation Software Market | 2026-2036
Global Presentation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Presentation Software Market Foresight
The enterprise sales training vertical is repositioning budget toward interactive demo platforms over static slide decks. Microsoft Corporation anchors the productivity suite segment through deep integration with enterprise identity systems. Adobe Systems Incorporated differentiates via design-forward positioning among creative professionals. Canva Inc. extends its freemium engine into workplace teams with lightweight collaboration features.
Presentation software encompasses applications for creating, editing, and delivering visual content sequences, typically supporting vector graphics rendering at 60 frames per second and real-time multi-user editing protocols. These tools serve commercial persuasion, educational instruction, and organizational communication by structuring narrative flow around temporal visual progression. Cloud-Based Solutions capture the fastest expansion trajectory as IT departments prioritize zero-install deployment and automatic version synchronization across distributed workforces. Desktop Software retains margin concentration among power users requiring offline asset manipulation and advanced animation scripting. The Corporate Sector end-user category generates the highest per-seat annual contract values due to administrative control requirements and security audit compliance.
The EU AI Act and GDPR constrain how European-hosted presentation platforms train autocomplete and design-assist algorithms on user content, elevating compliance costs for SaaS providers. The FCC in the United States enforces net neutrality principles that affect bandwidth allocation for real-time collaborative streaming during peak usage intervals. ISO 27001 certification has become a non-negotiable procurement filter for government agencies across multiple jurisdictions. Stakeholders must weigh data sovereignty commitments against the engineering overhead of fragmented regional infrastructure deployments.
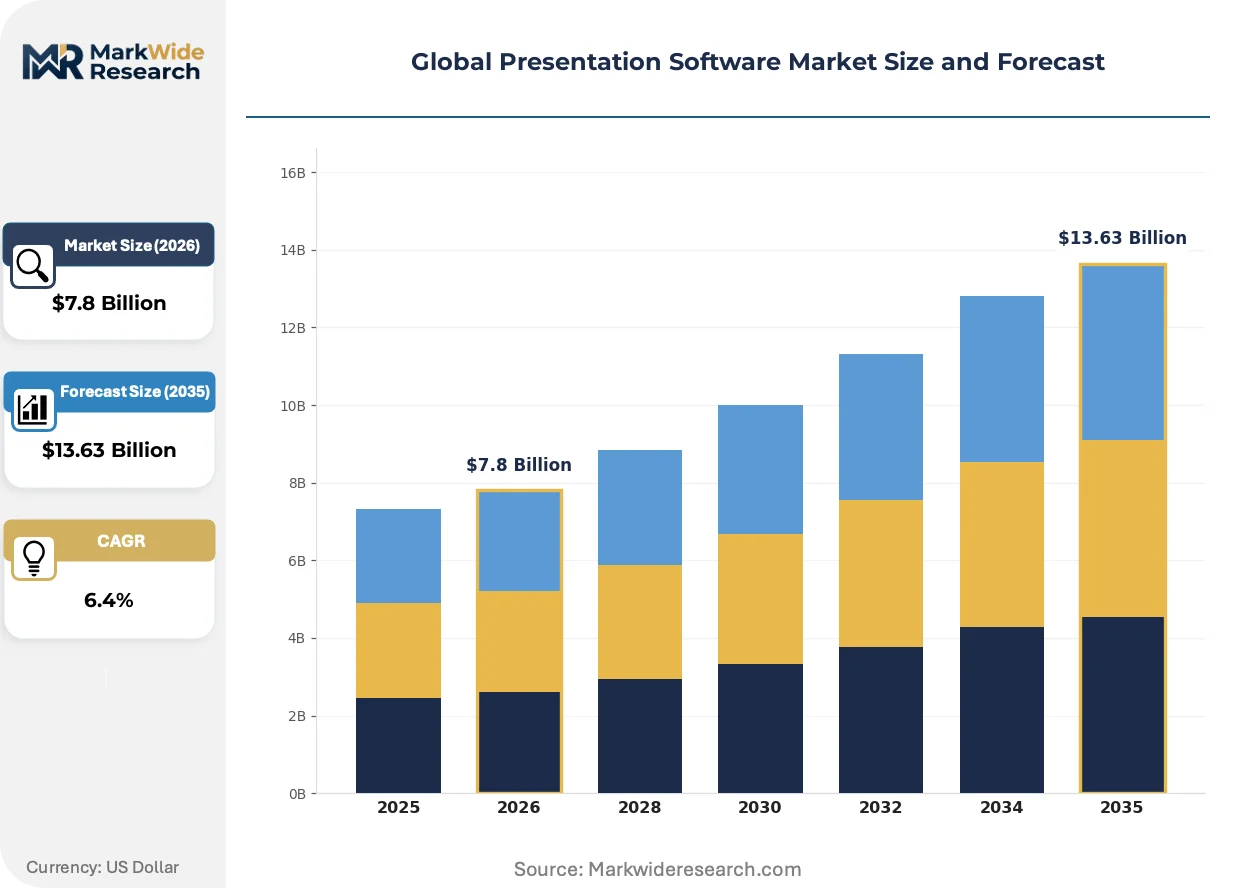
Market Dynamics
Cloud data residency mandates across the European Union are fragmenting vendor infrastructure and elevating compliance engineering costs for presentation software providers serving multinational enterprise accounts.
Growth Catalysts
- ISO 27001 Certification:Government procurement filters now mandate this security standard, creating pull-through demand from public sector agencies in Germany, Japan, and the United States.
- Hybrid Work Stabilization:Enterprise sales teams in the United States and Germany are expanding subscription volumes for interactive pitch platforms that support real-time remote collaboration.
- GDPR Enforcement:European data protection authorities are accelerating audit frequency, forcing vendors to invest in localized hosting that deepens customer retention through compliance lock-in.
Market Restraints
- EU AI Act Constraints:Algorithm training restrictions on European-hosted platforms limit autocomplete and design-assist feature development, compressing competitive differentiation.
- Bandwidth Allocation Volatility:FCC net neutrality principles create uncertainty for real-time collaborative streaming quality during peak usage intervals across United States enterprise networks.
- Cloud Infrastructure Concentration:Reliance on hyperscale providers in Ireland and Frankfurt creates single-point-of-failure exposure for vendors serving EU public sector clients.
Strategic Opportunities
- Japan Enterprise Penetration:METI digital transformation incentives are accelerating cloud migration among mid-market manufacturers previously dependent on desktop software.
- Zero-Install Deployment:IT departments in distributed workforces are prioritizing browser-native solutions that eliminate endpoint management overhead.
- CSRD Alignment:European corporate sustainability reporting requirements are creating demand for presentation tools with embedded carbon footprint visualization and ESG data integration.
Industry Challenges
- Animation Scripting Talent Scarcity:Power user segments require specialized motion design expertise that vendors struggle to recruit against creative agency competition.
- Legacy Identity System Integration:Enterprise customers demand seamless Active Directory and SAML connectivity, extending sales cycles and implementation timelines.
- Cross-Border Data Synchronization:Fragmented regional infrastructure complicates version control for teams collaborating across United States, German, and Japanese jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Presentation Software Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Cloud-Based Solutions, Mobile Applications, Collaboration Tools End User: Educational Institutions, Corporate Sector, Freelancers, Government Agencies Deployment: On-Premise, Software as a Service, Hybrid, Open Source Feature: Template Library, Real-Time Collaboration, Multimedia Integration, Data Visualization |
| Companies Covered | Adobe Systems Incorporated, Canva Inc., Microsoft Corporation, Pitch Software GmbH, Prezi Inc., Apple Inc., Zoho Corporation, Beautiful.ai, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Presentation Software Market Shifts & Advancements
Generative design assistance and real-time rendering pipelines are compressing production timelines for enterprise sales collateral while elevating baseline user expectations for automated visual polish.
Vector graphics rendering at 60 frames per second is absorbing computational overhead previously managed by dedicated GPU workstations. Mid-market sales teams in Germany and Japan are adopting these browser-native engines at accelerating pace. The technology is absorbing budget allocations formerly directed toward external design agencies and freelance motion specialists.
REACH chemical safety regulations in Europe are constraining data center cooling fluid selections for vendors operating localized infrastructure. Industrial consequence includes elevated facility construction costs and extended commissioning timelines for new EU hosting regions. Cloud-based solution providers are responding by retrofitting existing Frankfurt and Amsterdam facilities rather than greenfield expansion.
Enterprise buyers are consolidating vendor relationships around integrated productivity suites rather than standalone presentation tools. Channel partners in the United States are repositioning from resale to implementation services. This concentration is most visible among Fortune 500 procurement functions seeking single-source accountability for collaboration software spend.
Global Presentation Software Market Segmentation
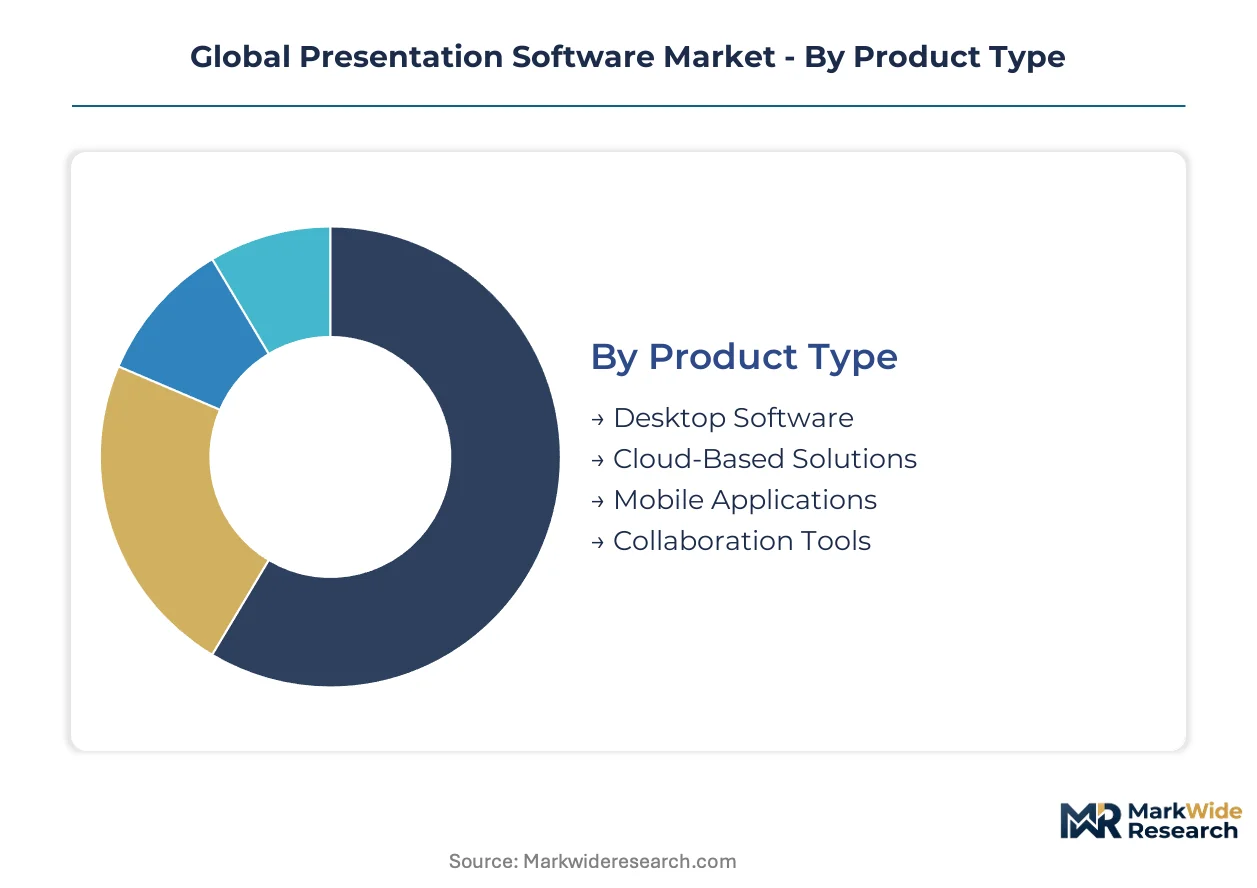
Presentation software purchasing decisions diverge sharply between standalone specialists and embedded productivity suite components. IT procurement teams evaluate integration depth, security architecture, and per-seat economics when mapping segments to organizational workflows.
Product Type:
Cloud-native architectures are displacing legacy desktop installations across enterprise environments, though power-user segments retain specialized offline tooling for complex animation pipelines.
- Cloud-Based Solutions:Browser-native rendering engines synchronize content across distributed workforces without endpoint installation. Enterprise sales teams in Germany and Japan are standardizing on these platforms as hybrid work stabilizes and IT departments eliminate version-control overhead.
- Desktop Software:Native applications provide offline asset manipulation and advanced scripting capabilities for motion designers. Creative professionals in the United States retain this segment for GPU-intensive rendering and proprietary plugin ecosystems that cloud architectures cannot replicate.
- Mobile Applications:Touch-optimized interfaces enable field sales teams to execute last-minute pitch modifications. These tools prioritize rapid slide reordering and presenter-view mirroring over full authoring functionality.
- Collaboration Tools:Embedded commenting and synchronous cursor tracking support distributed narrative development. These features increasingly ship as modules within broader cloud suites rather than standalone offerings.
Cloud-Based Solutions lead volumes today; Mobile Applications are gaining share fastest.
End User:
Contract value and security requirements stratify sharply across customer types, with public sector procurement imposing certification barriers that consumer segments ignore.
- Corporate Sector:Enterprise accounts demand SAML identity federation, administrative audit logs, and data residency guarantees. Annual contract values concentrate here due to compliance overhead and multi-year security review cycles that lock in vendor relationships.
- Government Agencies:ISO 27001 certification and GDPR-aligned data handling are non-negotiable procurement filters. German federal and Japanese prefectural entities are accelerating cloud migration while requiring localized hosting infrastructure.
- Educational Institutions:Volume licensing agreements prioritize cost efficiency over advanced feature sets. These deployments emphasize template libraries and plagiarism-detection integrations for student assessment workflows.
- Freelancers:Individual practitioners balance subscription costs against client-facing polish requirements. This segment drives freemium conversion metrics and viral template distribution through portfolio-sharing behaviors.
Corporate Sector dominates revenue concentration; Government Agencies are expanding contract volumes most rapidly.
Deployment:
Architecture choices reflect data sovereignty priorities and legacy infrastructure investments that vary by organizational maturity and geographic jurisdiction.
- Software as a Service:Multi-tenant cloud delivery eliminates capital expenditure and accelerates feature deployment. European enterprises select EU-hosted instances to satisfy GDPR data residency mandates and EU AI Act algorithm training restrictions.
- On-Premise:Self-managed installations persist in defense contractors and financial institutions with air-gapped security requirements. These deployments sacrifice automatic updates for complete data control and custom compliance reporting.
- Hybrid:Split architectures synchronize sensitive content through private infrastructure while leveraging cloud rendering for non-critical assets. Manufacturing enterprises in Japan are adopting this model to protect intellectual property while enabling supplier collaboration.
- Open Source:Community-maintained platforms attract academic researchers and privacy-conscious developers. These tools lack commercial support SLAs but enable unrestricted customization and algorithm transparency.
Software as a Service commands the largest installed base; Hybrid deployments are climbing the fastest among security-sensitive verticals.
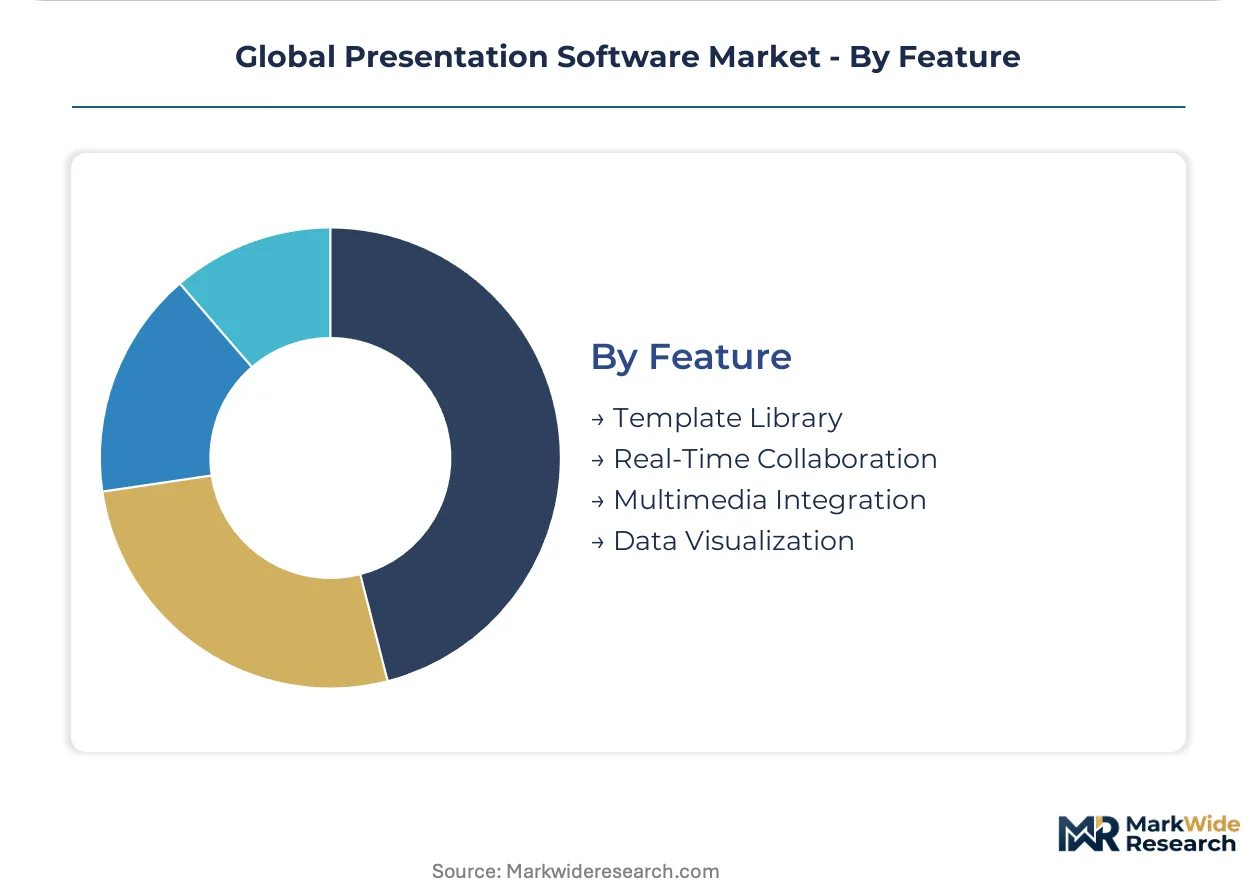
Feature:
Capability prioritization separates presentation software from generic document editors, with automated design assistance emerging as a competitive battleground constrained by regulatory training restrictions.
- Real-Time Collaboration:Synchronous multi-user editing with conflict resolution and presence indicators. FCC net neutrality principles in the United States create bandwidth allocation uncertainty for these streaming-intensive features during peak enterprise usage.
- Data Visualization:Native charting engines with live database connectors and CSRD-aligned carbon footprint templates. European corporate sustainability reporting requirements are accelerating demand for embedded ESG metrics and automated disclosure formatting.
- Template Library:Pre-designed slide frameworks with brand-consistent color and typography enforcement. These repositories reduce production timelines for mid-market sales teams lacking dedicated design resources.
- Multimedia Integration:Embedded video rendering and audio narration synchronization across devices. REACH chemical safety regulations in Europe are indirectly elevating data center costs for vendors hosting these storage-intensive assets.
Template Library functionality saturates baseline offerings; Data Visualization is expanding most quickly as regulatory disclosure requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley technology corridors anchor enterprise software adoption patterns across North America and Asia-Pacific. Hybrid work stabilization in knowledge-intensive metros is accelerating subscription renewals for collaborative platforms. Regulatory fragmentation between GDPR-aligned European markets and FCC-governed United States networks is reshaping vendor infrastructure deployment priorities.
United States
Enterprise sales teams in New York and San Francisco are expanding subscription volumes for interactive pitch platforms. FCC net neutrality principles create bandwidth allocation uncertainty for real-time collaborative streaming during peak usage intervals. Seattle and Austin technology clusters host the highest density of early-adopter firms standardizing on browser-native rendering engines.
Germany
ISO 27001 certification mandates from federal procurement offices are filtering vendor eligibility for public sector contracts. GDPR enforcement by state data protection authorities is accelerating localized hosting infrastructure investments. Frankfurt and Munich enterprise corridors are consolidating vendor relationships around EU-resident cloud instances with algorithm training transparency.
Japan
METI digital transformation incentives are accelerating cloud migration among mid-market manufacturers in Osaka and Nagoya. Prefectural government entities are expanding contract volumes for compliance-certified collaboration suites. Tokyo enterprise clusters are adopting hybrid deployment models to protect intellectual property while enabling supplier collaboration.
United Kingdom
Corporate sustainability reporting requirements are creating demand for presentation tools with embedded ESG data integration capabilities. The Information Commissioner's Office is enforcing data residency expectations for financial services firms in the City of London. Manchester and Edinburgh technology hubs are standardizing on zero-install deployment to eliminate endpoint management overhead.
India
IT departments in Bangalore and Hyderabad are prioritizing browser-native solutions for distributed engineering workforces. The country's national data protection framework is elevating compliance expectations for multinational SaaS providers serving domestic enterprises. Mumbai financial services clusters are driving freemium conversion metrics through portfolio-sharing behaviors among freelance consultants.
Global Presentation Software Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors seek integration depth with enterprise identity systems. The vendor base clusters around productivity suite incumbents, design-forward specialists, and freemium-native challengers. Three archetypes define competitive positioning: integrated platform providers, creative professional tools, and lightweight collaboration engines. M&A activity and geographic expansion represent the primary competitive moves as firms address data residency fragmentation.
Within the integrated platform tier, Microsoft Corporation and Alphabet Inc. occupy positions anchored to enterprise productivity ecosystems. Adobe Systems Incorporated exemplifies the design-forward archetype targeting creative professionals with GPU-intensive rendering capabilities. Canva Inc. represents the freemium-native model extending lightweight collaboration features into workplace teams. Pitch Software GmbH and Prezi Inc. sit within the interactive presentation specialist category, while Zoho Corporation and Beautiful.ai anchor mid-market segments with browser-native deployment emphasis.
| Leading Market Players |
|---|
| Adobe Systems Incorporated |
| Canva Inc. |
| Microsoft Corporation |
| Pitch Software GmbH |
| Prezi Inc. |
| Apple Inc. |
| Zoho Corporation |
| Beautiful.ai |
| Alphabet Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up cloud infrastructure specialists anchor supply-side consolidation across hyperscale data center networks, translating concentrated ownership into pricing discipline that resists margin erosion despite escalating compliance engineering costs for EU data residency mandates.
Pricing Analysis
Direct-to-enterprise subscription discounts dominate the pricing model, with three-tier pricing structure across premium, standard, and economy levels differentiating by ISO 27001 certification grade and administrative control depth. Price differentiation stems from data residency guarantees and SAML identity federation complexity. Cost compression in the mid-market tier is intensifying because browser-native rendering engines commoditize baseline functionality. Freelancers exhibit highest price sensitivity, while government agencies accept premium tiers for compliance lock-in.
Supply Chain Analysis
Refurbishment flows for GPU-intensive rendering hardware remain minimal, as cloud-native architectures displace capital-intensive workstation procurement. Supply concentrates in the United States, Ireland, and Germany for hyperscale data center infrastructure, with specialized motion design talent sourcing from Japan and the United Kingdom. Raw material dependencies span semiconductor substrates, liquid cooling fluids constrained by REACH regulations, and renewable energy certificates for carbon-neutral hosting claims. Single-source vulnerability persists in EU cloud regions dependent on Frankfurt and Amsterdam facilities. Distribution runs through direct SaaS provisioning with channel partners repositioning toward implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data residency engineering costs diverge sharply between GDPR-aligned European markets and FCC-governed United States networks, creating arbitrage opportunities for vendors optimizing infrastructure deployment across regulatory jurisdictions.
For Market Incumbents: To counter freemium-native challengers eroding mid-market share, deepen vertical integration into proprietary rendering engines that cloud architectures cannot replicate, and accelerate ISO 27001 certification investments to filter public sector procurement eligibility in Germany and Japan. For New Entrants and Emerging Players: EU AI Act algorithm training restrictions in Germany open a window for privacy-forward positioning with transparent on-device processing models, targeting underpenetrated mid-market manufacturers in Japan's Osaka-Nagoya corridor through METI-aligned digital transformation messaging and zero-install deployment simplicity. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone interactive presentation specialists lacking productivity suite integration depth. Long-term viability hinges on acquisition targets demonstrating sustainable freemium conversion mechanics and regional infrastructure fragmentation capabilities. Monitor FCC net neutrality enforcement intensity as bandwidth allocation uncertainty inflection indicator for real-time collaboration feature valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion | Localized EU hosting infrastructure deepens compliance lock-in for German federal contracts. |
| Platform Integration | Enterprise identity system connectivity extends sales cycles but secures multi-year renewals. |
| Strategic Partnership | Channel partner repositioning toward implementation services captures services revenue. |
| Product Launch | CSRD-aligned carbon footprint visualization modules address European sustainability reporting mandates. |
| Acquisition of Specialist Firm | Motion design talent scarcity makes animation scripting specialists strategic acquisition targets. |
Research Methodology
Direct dialogue with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie usage data, and government procurement databases. Bottom-up and top-down triangulation cross-validates segment-level demand with macroeconomic indicators across the analysis window.
Bottom-up modeling aggregates organization-level adoption patterns by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. Top-down constraints incorporate IT software spending elasticity and cloud migration velocity. CAGRs derive from regression against historical subscription renewal trajectories and workforce distribution metrics. Forecast inputs include hybrid work stabilization rates and GDPR enforcement intensity indices.
Revisions become necessary when regulatory enforcement patterns shift materially, hyperscale infrastructure concentration triggers antitrust intervention, or generative design assistance capabilities commoditize faster than projected. Practitioners should monitor EU AI Act implementation timelines and FCC net neutrality rulemaking proceedings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Managed File Transfer (MFT) Software and Service Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
United Arab Emirates (UAE) Cloud Accounting Software Market
Software & Services
Device Tracking Software Market
Software & Services
Global Nosql Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Courier Software Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Global Core Banking Software Market
Software & Services
Global Digital Signage Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
Global Nosql Database Market
Software & Services
Cloud Business Process Management (BPM) Software Market
Software & Services
Asia-Pacific Database Management Software Market