
 Electric Traction Motor Market | 2026-2036
Electric Traction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Traction Motor Market Analysis
Chinese motor manufacturing capacity is restructuring as CRRC scales permanent magnet traction systems for domestic high-speed rail and export markets. Siemens leverages its European rail heritage to sustain technology leadership in synchronous motor architectures for intercity trains. Nidec Corporation anchors Asian supply chains with specialized brushless traction motors for electric buses and compact urban transit vehicles.
An electric traction motor converts electrical energy into mechanical torque for vehicle propulsion, typically operating at voltages from 400V to 3,000V DC or up to 25kV AC in heavy rail configurations with liquid-cooled stator windings and laminated silicon steel cores. Permanent magnet motors now dominate premium urban transit applications for their superior power density and efficiency above 95%, while induction technology retains cost advantages in freight locomotives where maintenance simplicity outweighs efficiency gains. Gearless motor configurations are displacing traditional geared drives in metro systems, eliminating transmission losses and reducing acoustic emissions in tunnel environments.
The EPA, EU Green Deal transport protocols, and China's MIIT dual carbon standards collectively mandate fleet electrification timelines that lock in multi-year procurement contracts for traction motor suppliers. REACH substance restrictions and evolving F-Gas Regulation thresholds on cooling systems further constrain thermal management design choices, favoring suppliers with in-house magnet recycling and low-GWP coolant capabilities. Stakeholders must monitor rare earth supply concentration and emerging switched reluctance alternatives as magnet cost volatility threatens long-term contract economics.
Market Dynamics
Permanent magnet supply concentration in China and tightening EPA emissions rules for heavy-duty vehicles are compressing procurement timelines and forcing Western traction motor suppliers to reconfigure magnet sourcing strategies or pivot to induction architectures.
Growth Catalysts
- EPA Phase 3 GHG Standards:Mandates for heavy-duty truck fleets in the United States accelerate diesel-to-electric retrofits, driving procurement of high-torque AC induction systems for freight applications.
- Rare earth magnet recycling infrastructure:Emerging hydrometallurgical recovery facilities in Europe reduce virgin magnet dependence, stabilizing long-term contract economics for permanent motor suppliers.
- Urban transit electrification:Metro operators in São Paulo, Cairo, and Jakarta are replacing legacy DC motor fleets with gearless permanent magnet synchronous systems to cut tunnel noise and maintenance intervals.
Market Restraints
- Dysprosium and terbium price volatility:Heavy rare earth elements concentrated in Southern Chinese processing hubs expose permanent magnet motor margins to supply disruption and export quota fluctuations.
- REACH substance restrictions:ECHA classification of certain epoxy resin hardeners and insulating varnishes forces reformulation of stator winding encapsulants, extending qualification timelines by 18-24 months.
- Switched reluctance motor maturation:Magnet-free architectures from university spinouts and Tier 2 suppliers threaten permanent magnet dominance in cost-sensitive bus and light rail segments.
Strategic Opportunities
- India railway electrification:Indian Railways' 100% electrification target by 2024 creates captive demand for 25kV AC traction systems, with localization mandates favoring joint ventures with domestic component suppliers.
- EU Green Deal transport protocols:Carbon border adjustment mechanisms and fleet decarbonization mandates lock in multi-year procurement contracts for intercity and freight locomotive motor suppliers.
- Digital twin integration:Convergence of physics-based motor modeling with real-time thermal telemetry enables predictive maintenance contracts, shifting revenue from hardware sales to performance-guaranteed service agreements.
Industry Challenges
- High-voltage insulation expertise gap:Shortage of engineers experienced in 3,000V+ DC and 25kV AC winding design delays product qualification for next-generation high-speed rail platforms.
- Multi-standard certification complexity:Simultaneous compliance with IEC 60349, EN 50207, and customer-specific fire-safety protocols fragments testing resources and extends time-to-revenue for export-bound products.
- Legacy fleet integration friction:Retrofit of modern variable-frequency drives onto existing DC motor chassis requires mechanical adapter engineering and control system harmonization that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Traction Motor Market |
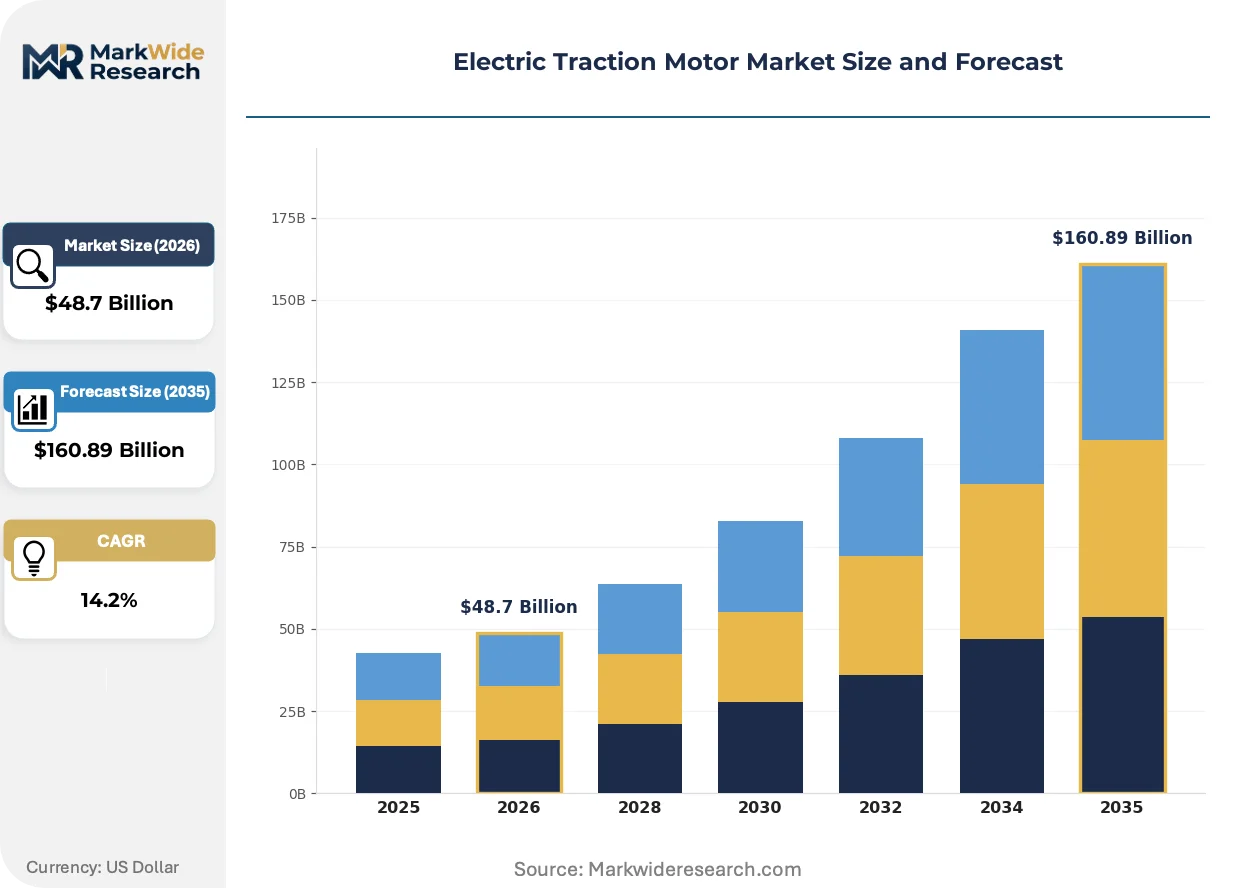
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motors, DC Motors, Gearless Motors, Permanent Magnet Motors End User: Railways, Electric Buses, Trams, Industrial Vehicles Technology: Induction, Synchronous, Brushless, Switched Reluctance Application: Urban Transit, Freight Transport, Off-Road Equipment, Heavy Machinery |
| Companies Covered | Siemens, ABB, CRRC, Nidec Corporation, Bosch, Alstom, Mitsubishi Electric, Toshiba Corporation, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Traction Motor Market Emerging Trajectories
Active thermal management architectures and magnet-free motor topologies are converging to reshape traction system design priorities, with efficiency optimization now competing against supply security as the primary engineering constraint.
Silicon carbide power modules are modularizing traction inverter architectures, enabling higher switching frequencies that reduce motor copper losses and shrink passive component volume. European intercity train manufacturers are adopting these modules for 25kV AC fed systems, cutting converter cabinet size by 40% and freeing underfloor space for battery augmentation. This compression of power electronics is modularizing the traditional integrated traction package, allowing motor and inverter suppliers to compete separately rather than as locked system integrators.
F-Gas Regulation thresholds on synthetic refrigerants are forcing liquid-cooled traction motor designs toward dielectric fluid alternatives and direct evaporative cooling loops. The industrial consequence is a qualification backlog at thermal test facilities as suppliers validate new coolant compatibility with winding insulation systems. Heavy rail applications in Germany and France are most affected, with Siemens and Alstom accelerating in-house low-GWP coolant development to avoid supply chain exposure.
Transit agencies are unbundling motor replacement from full vehicle procurement, creating standalone remanufacturing and service contract markets. Specialist rebuilders in Poland and Mexico are capturing mid-life motor overhaul volume that OEMs previously retained, compressing aftermarket pricing and forcing original suppliers to defend installed base through extended warranty offerings. This channel fragmentation is most visible in North American commuter rail, where public procurement rules favor small-business set-asides for maintenance contracts.
Electric Traction Motor Market Segmentation
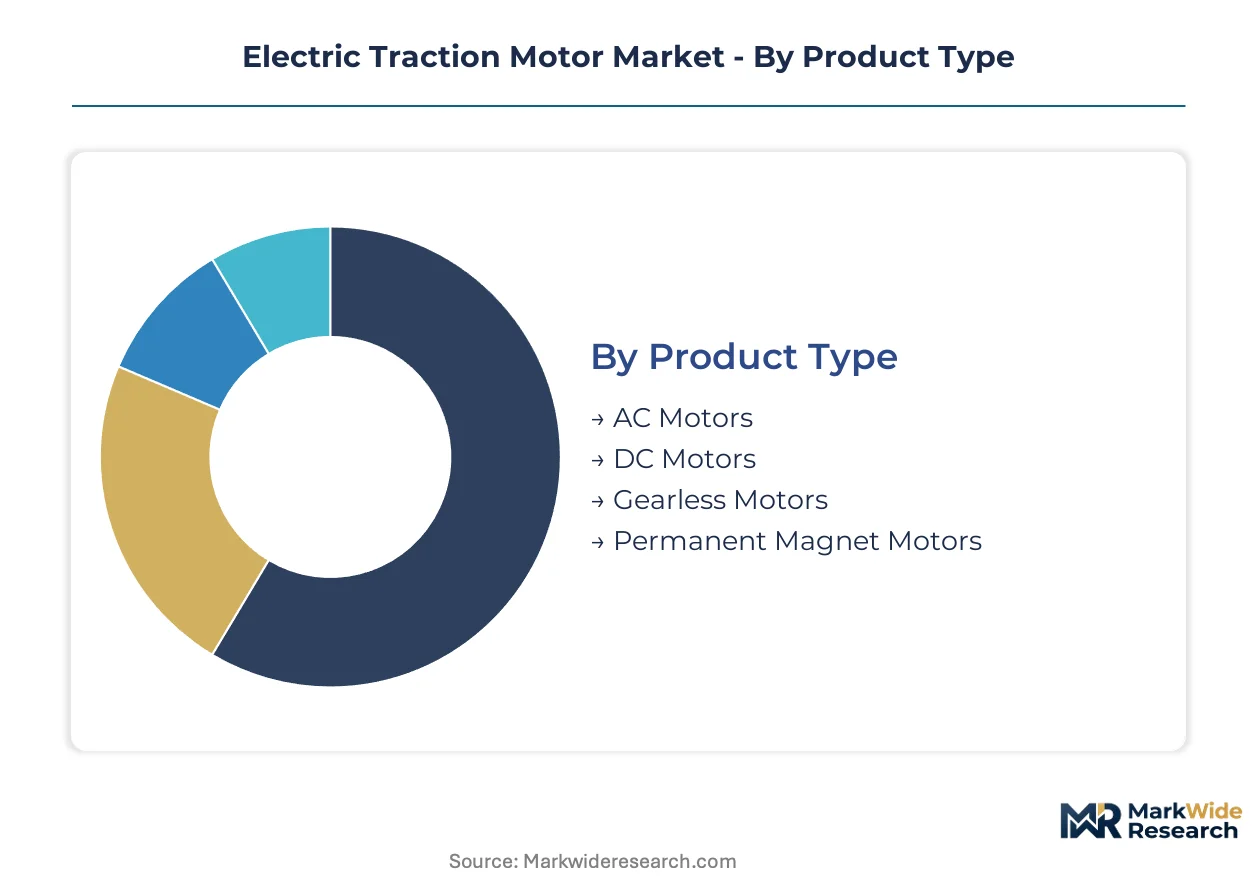
Segmentation in the electric traction motor market reveals how procurement priorities diverge across power density requirements, cooling constraints, and duty cycle intensity. Buyers optimize motor selection against route electrification status, tunnel noise regulations, and fleet electrification timelines rather than upfront cost alone.
Product Type:
Buyers differentiate primarily by efficiency targets and maintenance access constraints, with premium transit operators prioritizing power density while freight operators favor field-serviceable architectures.
- AC Motors:Robust squirrel-cage induction designs dominate freight locomotive retrofits where maintenance simplicity outweighs peak efficiency. Demand concentrates in Indian Railways electrification programs and North American heavy-duty truck conversions, driven by EPA Phase 3 GHG compliance deadlines and the absence of rare earth supply exposure.
- Permanent Magnet Motors:Neodymium-doped rotor architectures deliver power densities above 5 kW/kg with efficiencies exceeding 95%. Chinese high-speed rail procurement and European metro tunnel retrofits absorb the majority of volume, constrained by dysprosium price volatility and REACH substance restrictions on winding encapsulants.
- DC Motors:Commutator-based designs persist in legacy fleet refurbishment contracts where controller compatibility limits technology migration. Indian and Southeast Asian urban operators maintain procurement for mid-life vehicle extensions.
- Gearless Motors:Direct-drive configurations eliminate transmission losses and acoustic emissions in tunnel environments. São Paulo and Cairo metro authorities specify these for underground line modernization, trading higher motor mass against reduced trackside maintenance.
AC motors lead volumes today; permanent magnet motors are gaining share fastest.
End User:
End-use segmentation tracks infrastructure electrification maturity, with captive rail networks advancing faster than dispersed road fleets.
- Railways:Intercity and high-speed platforms demand 25kV AC traction systems with liquid-cooled stator windings. European Green Deal transport protocols and Indian Railways' electrification targets lock in multi-year procurement schedules for synchronous motor suppliers.
- Electric Buses:Low-floor urban transit vehicles require compact, high-torque motors with integrated reduction gearboxes. Chinese domestic suppliers and Nidec Corporation anchor Asian supply chains, with procurement accelerating under MIIT dual carbon standards.
- Trams:Street-running light rail operates at lower voltages with priority on regenerative braking efficiency. European manufacturers favor permanent magnet synchronous systems for weight-constrained low-floor designs.
- Industrial Vehicles:Mining haul trucks and port cargo handlers impose severe thermal cycling on traction systems. Off-road duty cycles favor induction motor durability over peak efficiency optimization.
Railways dominate procurement value; electric buses show the steepest expansion trajectory.
Technology:
Technology selection hinges on magnet supply security versus efficiency optimization, with emerging architectures threatening permanent magnet dominance in cost-sensitive segments.
- Induction:Magnet-free rotor construction eliminates rare earth exposure and simplifies high-temperature operation. Freight operators in Germany and the United States specify these for heavy-haul electrification where thermal margin exceeds efficiency priorities.
- Synchronous:Field-oriented control enables precise torque response for high-speed rail adhesion management. CRRC and Siemens sustain technology leadership through proprietary rotor position sensing and inverter integration.
- Brushless:Electronic commutation eliminates wear components for extended maintenance intervals. Compact variants from Nidec Corporation serve Asian electric bus and urban transit vehicle production.
- Switched Reluctance:Salient-pole rotor designs operate without permanent magnets or rotor windings. University spinouts and Tier 2 suppliers advance these architectures for bus and light rail applications where magnet cost volatility threatens contract economics.
Synchronous systems anchor premium applications; switched reluctance is climbing fastest among emerging alternatives.
Application:
Application segmentation reflects duty cycle severity, with continuous high-speed operation demanding fundamentally different thermal management than intermittent stop-start patterns.
- Urban Transit:Metro and suburban rail systems prioritize acoustic emissions reduction and regenerative braking capture. Gearless permanent magnet configurations displace traditional geared drives in tunnel environments, eliminating transmission losses.
- Freight Transport:Heavy-haul locomotives and electric trucks require sustained torque output across extended gradients. Induction motor architectures retain preference for maintenance accessibility in remote rail corridors and long-haul trucking routes.
- Off-Road Equipment:Mining and construction vehicles impose shock loading and contamination exposure. Sealed liquid-cooled designs with laminated silicon steel cores withstand abrasive environments where air-cooled alternatives fail.
- Heavy Machinery:Port cranes and industrial forklifts demand intermittent high-torque bursts with rapid thermal recovery. Specialized brushless motors with direct evaporative cooling loops address F-Gas Regulation constraints on synthetic refrigerants.
Urban transit commands the largest installed base; freight transport is expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as producers migrate toward jurisdictions offering magnet recycling infrastructure and streamlined electrification procurement timelines. Cost-of-compliance gaps between REACH-regulated Europe and China's integrated rare earth supply chain concentrate investment decisions.
China
Domestic high-speed rail expansion and electric bus fleet mandates absorb the majority of permanent magnet traction system output. MIIT dual carbon standards lock in multi-year procurement contracts for synchronous motor suppliers. CRRC anchors production in Changzhou and Qingdao, feeding both domestic networks and export markets across Southeast Asia.
Germany
Intercity rail electrification and freight locomotive retrofits sustain demand for 25kV AC induction systems. EU Green Deal transport protocols and F-Gas Regulation thresholds on cooling systems force thermal management redesigns. Siemens and Alstom concentrate development in Munich and Berlin, accelerating in-house low-GWP coolant validation.
United States
EPA Phase 3 GHG standards for heavy-duty trucks compress diesel-to-electric conversion timelines. Freight operators in California and Texas specify AC induction architectures to avoid rare earth supply exposure. Manufacturing clusters in Michigan and Ohio specialize in high-torque systems for long-haul electrification.
India
Indian Railways' electrification targets create captive demand for 25kV AC traction systems with localization mandates favoring joint ventures. BIS certification requirements and PLI scheme incentives attract component suppliers to Gujarat and Tamil Nadu. Chennai and Bengaluru host emerging motor winding facilities serving domestic metro procurement.
Japan
Urban transit vehicle exports and compact traction motor specialization sustain niche manufacturing. METI technology roadmaps prioritize magnet-free architectures for supply security. Nidec Corporation anchors production in Kyoto, supplying brushless systems to Asian electric bus assemblers.
Electric Traction Motor Market Vendor Landscape
Chinese producers anchor the scale-driven tier; European specialists hold the premium synchronous segment through heritage rail expertise. The market structure concentrates around integrated system suppliers with captive magnet sourcing or recycling partnerships. Three archetypes dominate: state-backed rail conglomerates with vertical manufacturing control, diversified industrial electrification houses, and compact motor specialists serving urban transit niches. Competitive moves center on magnet recycling infrastructure partnerships and silicon carbide inverter integration to compress power electronics volume.
Within the diversified industrial tier, Siemens and ABB exemplify European heritage positioning, while CRRC represents state-coordinated scale advantages. Nidec Corporation occupies a distinct specialist position among compact brushless motor fabricators. These anchors illustrate how geographic origin and corporate structure shape strategic options: German AG-format industrials leverage certification depth, Chinese state-linked entities exploit supply chain integration, and Japanese Co., Ltd. structures optimize for component density in space-constrained applications.
| Leading Market Players |
|---|
| Siemens |
| ABB |
| CRRC |
| Nidec Corporation |
| Bosch |
| Alstom |
| Mitsubishi Electric |
| Toshiba Corporation |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation thresholds on synthetic refrigerants gate qualified supply for liquid-cooled traction systems and premium-tier pricing access, forcing motor suppliers to absorb qualification costs or cede high-speed rail contracts to in-house coolant developers.
Pricing Analysis
Distributor margins for traction motor systems compress as OEMs consolidate procurement through direct long-term offtake contracts. Pricing stratifies across permanent magnet synchronous, induction, and emerging switched reluctance tiers, with differentiation driven by IEC 60349 certification grade and volume scale commitments. Cost compression in induction architectures intensifies because freight operators prioritize rare earth supply security over peak efficiency. Electric bus fleet operators exhibit highest price sensitivity; intercity rail procurement teams show lowest.
Supply Chain Analysis
Regional distribution centers in Changzhou, Munich, and Detroit anchor hub-and-spoke patterns for motor component logistics. Manufacturing concentrates in China, Germany, and the United States. Rare earth magnet feedstock draws from Southern Chinese processing hubs; silicon steel laminations rest on Japanese and Korean mill capacity. Single-source vulnerability in dysprosium terbium supply threatens permanent magnet contract economics. Distribution runs through captive rail OEM integration and Tier 1 supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric traction motor market functions as a regulatory compounder, with EPA Phase 3 GHG standards and EU Green Deal transport protocols locking in multi-year procurement schedules that compound demand visibility for qualified suppliers.
For Market Incumbents: Deepen magnet recycling partnerships and silicon carbide inverter integration to defend against switched reluctance entrants threatening cost-sensitive bus segments. Anchor capacity in Changzhou or Qingdao to maintain CRRC-aligned supply chain access. Certification investment in REACH-compliant winding encapsulants preserves European rail contract eligibility. For New Entrants and Emerging Players: Freight operators in North American heavy-duty trucking represent an underserved buyer archetype seeking magnet-free AC induction architectures. Penetrable white space sits in Indian Railways joint ventures with localization mandates and Polish motor remanufacturing specialists capturing aftermarket volume. Go-to-market through predictive maintenance service contracts rather than hardware-only positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among compact brushless motor fabricators with Asian electric bus supply relationships. Long-term viability hinges on magnet-free technology roadmaps and thermal management IP. Acquisition targets should show captive rare earth sourcing or hydrometallurgical recovery partnerships. Watch switched reluctance motor qualification timelines as inflection signal for permanent magnet demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure Partnership | European hydrometallurgical facilities reduce virgin rare earth dependence for permanent magnet suppliers. |
| Silicon Carbide Inverter Integration | Siemens and Alstom adoption cuts converter cabinet size by 40% for 25kV AC intercity systems. |
| Joint Venture Localization | Indian Railways mandates favor domestic component partnerships in Gujarat and Tamil Nadu. |
| Predictive Maintenance Platform | Digital twin convergence enables performance-guaranteed service contracts shifting revenue from hardware. |
| Low-GWP Coolant Development | In-house dielectric fluid validation avoids F-Gas Regulation supply chain exposure in German and French rail. |
Methodological Framework
Bottom-up railway and electric bus fleet modeling reconciled against top-down magnet supply and inverter production tracking forms the analytical core. Primary interviews with traction motor procurement directors, thermal management engineers, rail operator maintenance heads, and rare earth supply specialists combined with secondary validation from IEC standards documentation, EPA regulatory filings, EU Green Deal protocol texts, and MIIT dual carbon policy releases.
Historical trendline analysis across installed base expansion, electrification program announcements, and technology substitution patterns informed the projection framework. Segmentation dimensions modeled include motor architecture, cooling system type, end-use application, voltage class, and regional regulatory cluster. CAGRs derived from compound growth trajectory fitting against policy-mandated fleet conversion timelines and supplier capacity expansion announcements. Forecast inputs incorporated REACH substance restriction phase-in schedules and F-Gas Regulation threshold evolution.
Underlying measurement precision varies by segment; permanent magnet motor forecasts carry tighter precision than emerging switched reluctance alternatives. Forecasts reflect assumptions around rare earth price stability and qualification timeline adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
US Solar E-Bike Market
Electric Motor
Global Hub Motors Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
E-Bike Motor Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Automotive ABS Motor Market
Electric Motor
UAE Electric Motor Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Global Automotive Onboard Charger Market