
 Electronic Dance Music (EDM) Market | 2026-2036
Electronic Dance Music (EDM) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Dance Music (EDM) Market Foresight
Festival promoters is collapsing the distance between underground raves and mainstream concert economics as ticket buyers shift from casual club-goers toward dedicated festival enthusiasts. Spinnin' Records leverages its Amsterdam headquarters to dominate European distribution pipelines. Armada Music anchors its catalog depth across trance and progressive house, sustaining artist loyalty through long-term licensing deals.
Electronic dance music comprises synthesized rhythmic compositions typically produced at 120–150 BPM using digital audio workstations, sequencers, and sample-based production, designed primarily for live DJ performance and dance-floor consumption. House and techno subgenres occupy the deepest catalog pools and command the most consistent streaming volumes, while dubstep and drum and bass concentrate in younger Gen Z demographics with faster growth trajectories but narrower monetization paths. Distribution through streaming services now leads all channels, though vinyl retains outsized margin contribution among collector segments.
The US Copyright Office and performing rights organizations including ASCAP and BMI shape royalty collection frameworks that determine artist compensation structures across American markets. The EU's Copyright Directive Article 17 imposes platform liability rules that alter how streaming services negotiate licensing with European labels and producers. Stakeholders must monitor how fragmented national copyright enforcement interacts with borderless digital distribution to assess which territorial markets offer sustainable revenue extraction.
Market Dynamics
Streaming platform royalty frameworks are compressing artist revenue per stream while festival promoters expand production budgets to capture rebounding live attendance, creating a bifurcated value capture structure between recorded and performance revenue channels.
Growth Catalysts
- Festival Infrastructure Investment:Dedicated festival enthusiasts are driving ticket premiumization across the Netherlands and United Kingdom, where established club circuits anchor year-round consumption patterns.
- EU Copyright Directive Article 17:Platform liability rules are reshaping licensing negotiations between European labels and streaming services, strengthening producer bargaining positions in territorial markets.
- Digital Audio Workstation Proliferation:Cloud-based production tools are lowering entry barriers for bedroom producers in secondary cities, expanding the creator base beyond traditional studio hubs.
Market Restraints
- Royalty Rate Compression:Per-stream payouts from dominant platforms have stagnated below sustainable thresholds for mid-tier artists, forcing reliance on ancillary revenue streams.
- Venue Concentration Risk:Festival circuit control rests with a narrow promoter tier in the United States and Netherlands, creating gatekeeper bottlenecks for emerging acts.
- Acoustic Environment Limitations:Urban noise ordinances in dense European cities restrict after-hours operation windows for underground venues serving core demographics.
Strategic Opportunities
- Latin American Market Underpenetration:Brazil and Mexico exhibit festival attendance growth without proportional domestic label infrastructure, creating white space for catalog licensing plays.
- Immersive Audio Convergence:Spatial audio formats and visual rendering engines are enabling premium tier experiences at select Las Vegas and Ibiza residencies.
- Vinyl Collector Channel Expansion:Direct-to-consumer pressing operations are capturing margin pools abandoned by major distribution networks in collector segments.
Industry Challenges
- Mastering Engineer Talent Scarcity:Specialized loudness optimization skills for streaming platform algorithms command premium rates, constraining independent label output capacity.
- ASCAP-BMI Licensing Complexity:Fragmented performing rights collection across American venues creates compliance friction for touring artists and regional promoters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Dance Music (EDM) Market |
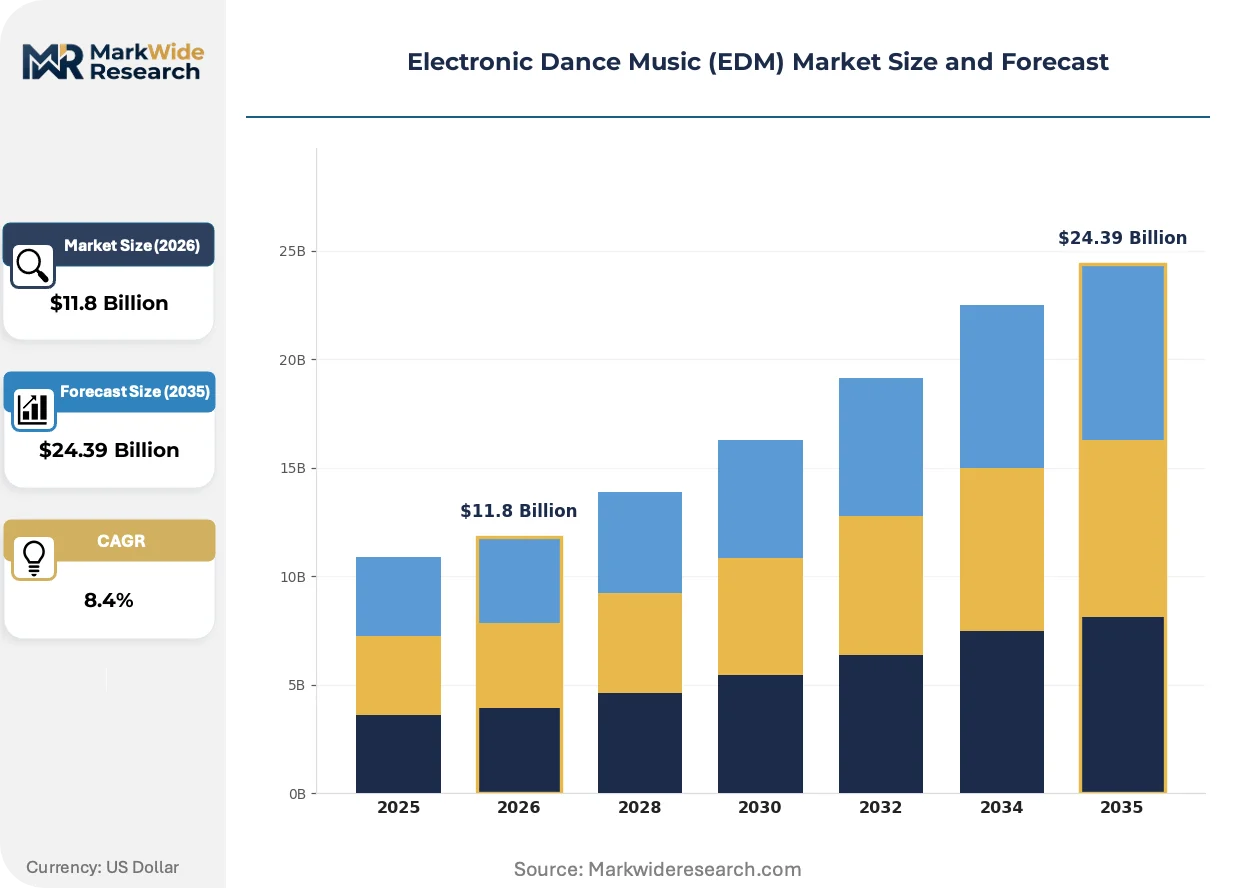
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
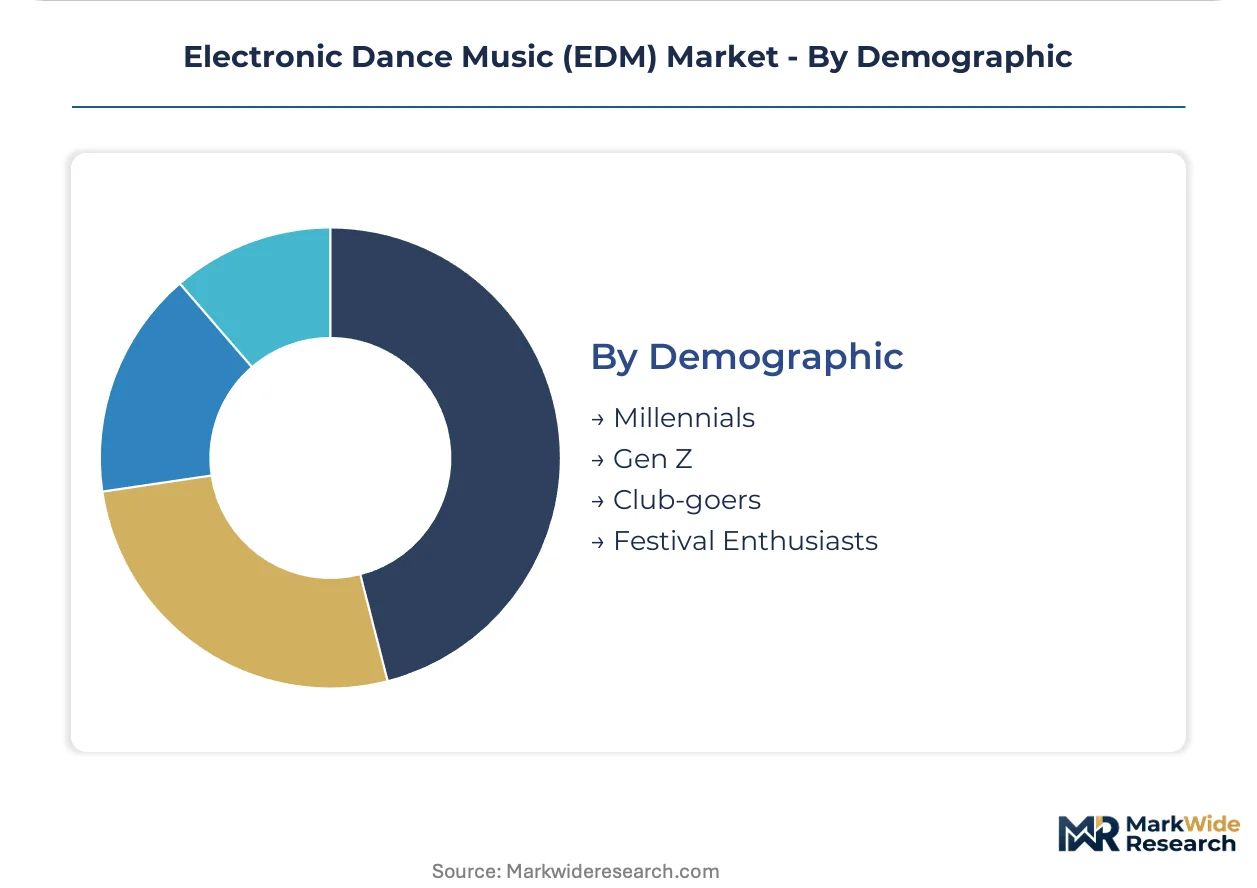
| Segmentation | Genre: House, Trance, Dubstep, Drum and Bass Event Type: Festivals, Nightclubs, Raves, Concerts Distribution Channel: Streaming Services, Digital Downloads, Vinyl, CDs Demographic: Millennials, Gen Z, Club-goers, Festival Enthusiasts |
| Companies Covered | Spinnin’ Records, Armada Music, Dirtybird Records, Defected Records, Mad Decent, Toolroom Records, Dim Mak, Revealed Recordings, Ministry of Sound, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Dance Music (EDM) Market Shifts & Advancements
Generative production tools and immersive audio formats are restructuring how electronic music is composed, distributed, and consumed across live and recorded channels.
AI-assisted composition plugins are displacing traditional sample pack workflows for emerging producers in Berlin and Los Angeles bedroom studios. These tools accelerate loop generation and harmonic matching, compressing the production timeline from weeks to days. The structural consequence is a flood of functional but homogenized content that is displacing human-curated sample libraries in entry-level market tiers.
The EU's Copyright Directive Article 17 imposes direct platform liability for unlicensed content, forcing streaming services to deploy upload filters and negotiate blanket licenses with European collective management organizations. This shifts compliance burden upstream from individual rights holders to platform operators. Independent Dutch and German labels are leveraging this leverage to extract improved revenue share terms from distributors.
Festival-goers are consolidating spending around destination events rather than distributed club nights, altering promoter booking strategies toward multi-day immersive experiences. This behavioral pivot concentrates artist fees at marquee events while starving regional venue circuits. The United States and United Kingdom exhibit the most pronounced shift, with dedicated enthusiasts prioritizing annual pilgrimage events over weekly local attendance.
Electronic Dance Music (EDM) Market Segmentation

EDM market segmentation reveals how consumption patterns fragment across production styles, venue formats, and generational cohorts. These divisions determine royalty structures, touring economics, and catalog valuation for rights holders operating across territorial markets.
Genre:
ASCAP and BMI in the United States enforce divergent mechanical royalty rates across tempo-based classifications, while EU collective management organizations apply uniform streaming tariffs regardless of subgenre categorization.
- House:Four-on-the-floor rhythms at 120-130 BPM dominate catalog depth across streaming platforms. Demand concentrates in the Netherlands and United Kingdom, where established club circuits sustain year-round consumption through resident DJ programs and warehouse venue networks.
- Trance:Synthesized arpeggios and extended breakdown structures characterize this segment's 128-140 BPM range. European festival circuits in Germany and Poland anchor live performance demand, driven by dedicated enthusiast communities that prioritize extended set formats over radio-edited durations.
- Dubstep:Half-time rhythms and aggressive bass modulations define this 140 BPM segment. UK-origin production techniques now concentrate in North American markets among younger demographics seeking high-energy live experiences.
- Drum and Bass:Fast breakbeats at 160-180 BPM with sub-bass foundations characterize this technically demanding segment. London and Bristol studio clusters sustain production expertise, though streaming penetration lags house and trance categories due to narrower playlist placement.
Established volume favors House; emerging adoption favors Dubstep.
Event Type:
Festival production budgets now exceed nightclub infrastructure investment by an order of magnitude, reshaping where artists extract maximum performance revenue per calendar date.
- Festivals:Multi-day immersive experiences with dedicated production design and camping accommodations command premium ticket tiers. Las Vegas and Miami anchor North American destination events, while Amsterdam and Boom sustain European circuit density through established promoter relationships.
- Nightclubs:Weekly programming in fixed venues supports resident artist development and genre experimentation. Berlin and London club circuits maintain global influence through extended operating hours and specialized sound system investments.
- Raves:Underground temporary events operate outside licensed venue frameworks, concentrating in industrial zones and rural locations. These gatherings sustain subgenre innovation but face enforcement pressure from municipal noise ordinances.
- Concerts:Arena and theater configurations adapt EDM performance for seated audiences, expanding demographic reach beyond core dance-floor participants. Production requirements scale with venue capacity, altering artist fee structures and technical rider complexity.
Revenue concentration tilts toward Festivals; artist development dependence remains with Nightclubs.
Distribution Channel:
Platform liability rules under EU Copyright Directive Article 17 impose differentiated compliance burdens across physical and digital channels, altering margin extraction for independent labels.
- Streaming Services:Algorithmic playlist placement determines discovery velocity and royalty accumulation for catalog releases. Per-stream payouts from dominant platforms have compressed below sustainable thresholds for mid-tier artists, forcing diversification into ancillary revenue channels.
- Digital Downloads:Lossless file formats retain niche demand among DJ professionals requiring uncompressed audio for club playback. Beatport and Traxsource anchor this declining but high-margin segment through specialized curation and genre-specific chart structures.
- Vinyl:Collector segments sustain premium pricing for limited pressings despite manufacturing lead times extending to several months. Direct-to-consumer operations capture margin pools abandoned by major distribution networks.
- CDs:Physical media consumption now concentrates in automotive and archival use cases, with minimal contribution to overall revenue extraction for new releases.
Volume leadership belongs to Streaming Services; margin preservation favors Vinyl.
Demographic:
Generational cohorts exhibit divergent spending patterns across recorded consumption, live attendance, and merchandise attachment rates.
- Millennials:Festival attendance consolidation around destination events characterizes this cohort's behavioral pivot from distributed club nights. United States and United Kingdom markets exhibit the most pronounced shift toward annual pilgrimage events.
- Gen Z:Shorter-form content consumption on video platforms precedes streaming discovery, altering artist marketing investment toward visual production. Dubstep and drum and bass subgenres concentrate in this demographic with faster growth trajectories.
- Club-goers:Weekly local attendance sustains venue circuit economics and resident artist development pipelines. Urban noise ordinances in dense European cities restrict after-hours operation windows for this core demographic.
- Festival Enthusiasts:Dedicated spending around multi-day events drives ticket premiumization across the Netherlands and United Kingdom, where established infrastructure anchors year-round consumption patterns.
Current revenue weight rests with Millennials; engagement intensity peaks among Festival Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Amsterdam-Rhine canal corridor underwrites Dutch distribution dominance, while the Channel Tunnel anchors UK-European festival circuit integration. High-speed rail links between Berlin and Munich compress artist touring logistics across German-speaking markets.
United States
Las Vegas residencies and Miami festival infrastructure drive North American performance revenue concentration. The US Copyright Office and ASCAP-BMI frameworks shape mechanical royalty collection across American markets. Los Angeles bedroom studios and Brooklyn warehouse venues anchor production and underground circuit density.
Netherlands
Amsterdam's established club infrastructure and Rotterdam port logistics sustain European distribution hub status. EU Copyright Directive Article 17 imposes platform liability rules that strengthen Dutch label bargaining positions. The Randstad cluster concentrates Spinnin' Records and Armada Music headquarters operations.
United Kingdom
London's Ministry of Sound and Bristol's drum and bass studios anchor genre-specific production expertise. The British Phonographic Industry and PRS for Music administer divergent royalty frameworks across UK markets. Manchester and Glasgow club circuits sustain regional venue density outside the capital.
Germany
Berlin's extended-hours venue licensing and Frankfurt mastering studio clusters drive technical production standards. GEMA's collective management organization enforces streaming tariffs distinct from Anglo-American models. The city's Tempelhof and Kraftwerk repurposed industrial spaces anchor underground event infrastructure.
Brazil
São Paulo festival attendance growth outpaces domestic label infrastructure development, creating catalog licensing white space. ANCINE's cultural industry incentives support live event production without proportional recorded music investment. Rio de Janeiro's beach circuit and Belo Horizonte's emerging promoter tier concentrate regional demand.
Electronic Dance Music (EDM) Market Competitive Landscape
Concentration sits with Amsterdam-headquartered majors and London-anchored independents. The vendor base stratifies across three tiers: major-affiliated imprints with streaming algorithm access, mid-tier genre specialists with festival promoter relationships, and bedroom-label operators with direct-to-fan vinyl channels. Dominant competitive moves include catalog acquisition plays and exclusive residency lockups with Las Vegas and Ibiza venues.
Among Dutch-headquartered distributors, Spinnin' Records and Armada Music occupy positions exemplifying the major-affiliated archetype, leveraging territorial licensing leverage to extract improved streaming terms. Ministry of Sound represents the UK-based specialist tier, anchoring house music curation authority through long-term compilation franchise value. These three entities illustrate how geographic clustering around Amsterdam and London correlates with distribution pipeline control.
| Leading Market Players |
|---|
| Spinnin' Records |
| Armada Music |
| Dirtybird Records |
| Defected Records |
| Mad Decent |
| Toolroom Records |
| Dim Mak |
| Revealed Recordings |
| Ministry of Sound |
| Others |
Supply & Pricing Matrix
EU Copyright Directive Article 17 gates both supply qualification and price differentiation simultaneously, forcing streaming platforms to deploy upload filters and negotiate blanket licenses before catalog access. This regulatory threshold compresses margins for distributors lacking territorial licensing leverage while amplifying pricing power for Amsterdam and London headquarters operations with established collective management relationships.
Pricing Analysis
Volume-discount tiering structures dominate festival promoter contracts, with multi-date residencies and exclusive venue lockups commanding preferential artist fee schedules. Price differentiation stems from production scale and territorial exclusivity, with Las Vegas and Ibiza residencies extracting premium positioning against regional club circuits. Cost compression in mid-tier streaming distribution is intensifying because per-stream payouts have stagnated below sustainable thresholds. Bedroom producers and independent labels exhibit highest price sensitivity, while major-affiliated imprints with algorithmic playlist access demonstrate lowest sensitivity to fee compression.
Supply Chain Analysis
The Netherlands and the United Kingdom anchor vinyl pressing and mastering studio capacity, with Amsterdam and London clusters sustaining technical production expertise for loudness-optimized streaming delivery. Raw material dependencies span acetate stock for vinyl manufacturing, cloud compute credits for digital audio workstation rendering, and specialized analog equipment for signal processing. Single-source vulnerability concentrates in Berlin and Frankfurt mastering engineer talent pools, where specialized loudness optimization skills command premium rates. Distribution runs through direct-to-consumer vinyl channels and algorithmic streaming platforms, with territorial licensing intermediaries extracting margin at territorial borders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mastering engineer scarcity and algorithmic playlist gatekeeping define capability gaps that determine competitive survival across the forecast horizon. Producers lacking specialized loudness optimization skills or platform relationship capital face systematic margin compression.
For Market Incumbents: Fortify catalog depth through exclusive long-term licensing deals with bedroom producers before EU Copyright Directive Article 17 strengthens their bargaining positions. Lock in multi-year residency contracts with Las Vegas and Ibiza venues to preempt emerging promoter competition. Prioritize backward integration into vinyl pressing operations to capture collector segment margins abandoned by major distribution networks.
For New Entrants and Emerging Players: Festival infrastructure gaps in Brazil and Mexico represent service-layer underperformance where domestic label infrastructure lags attendance growth. Target these territories with catalog licensing plays and local promoter partnerships rather than competing in saturated Amsterdam and London distribution pipelines. Deploy direct-to-fan vinyl channels as the primary go-to-market angle to bypass algorithmic streaming gatekeeping.
For Investors and Strategic Acquirers: EU Copyright Directive Article 17 enforcement reshapes the acquisition landscape toward targets with established collective management relationships and territorial licensing leverage. Long-term viability hinges on catalog ownership depth rather than transient streaming chart performance. Monitor GEMA and PRS for Music tariff negotiations as the signal indicating platform compliance cost trajectories and distributor margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalog Acquisition Play | Armada Music and Spinnin' Records demonstrate how deep trance and progressive house libraries sustain artist loyalty through recurring licensing revenue. |
| Exclusive Residency Lockup | Las Vegas and Ibiza venue contracts concentrate performance revenue at marquee events while starving regional competitor circuits. |
| Direct-to-Consumer Vinyl Channel | Limited pressing operations capture margin pools abandoned by major distribution networks in collector segments. |
| Spatial Audio Format Investment | Immersive audio convergence at select residencies enables premium tier experiences beyond standard club playback. |
| Latin American Promoter Partnership | Brazil and Mexico festival attendance growth without proportional domestic label infrastructure creates catalog licensing white space. |
Research Methodology
Initial hypotheses were tested against primary input from festival promoters, mastering engineers, streaming platform content directors, and independent label operators and refined through secondary validation. Festival promoter budget allocations, collective management organization tariff filings, and vinyl manufacturing lead time data anchored quantitative modeling. Primary stakeholder interviews with resident DJs, venue sound system technicians, and performing rights collection specialists supplied operational detail. Secondary sources included ASCAP and BMI licensing frameworks, EU Copyright Directive implementation guidance, GEMA tariff schedules, and trade data on acetate stock imports. Bottom-up artist fee structures and top-down market value estimates underwent iterative reconciliation.
Variance-decomposition framing isolated genre-specific growth trajectories, distribution channel margin extraction, and demographic spending pattern shifts across the projection horizon. Segmentation dimensions spanned production subgenre, event format, distribution channel, and generational cohort adoption intensity. CAGRs were synthesized from streaming volume curves, festival attendance rebound patterns, and vinyl collector segment pricing resilience. Industry-specific forecast inputs incorporated algorithmic playlist placement velocity and territorial licensing negotiation leverage.
Underlying assumptions cover live event attendance sustainability, platform compliance cost pass-through rates, and mastering engineer talent pool expansion, with deviation risk concentrated in municipal noise ordinance enforcement and collective management tariff renegotiation cycles. Recalibration cycles align with material shifts in EU Copyright Directive enforcement rigor and streaming platform royalty framework adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Global Free Music Making Software Market
Music
Europe Independent Artist Market
Music
Music Publishing Market
Music
Virtual Musical Instruments Market
Music
Traditional Chinese Instruments Market
Music
Global Stock Music Market
Music
Discography Market
Music
Independent Music Publishing Market
Music
Musical Groups and Artists Market
Music
Music Synthesizers Market
Music
Vinyl Records Market
Music
Global in-Store Music Service Market
Music
Asia-Pacific Independent Artist Market
Music
Music Distribution Services Market
Music
Music App Market
Music
Global Background Music Market