
 Europe Independent Artist Market | 2026-2036
Europe Independent Artist Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Independent Artist Market Insights
CE marking for digital art authentication tools is collapsing the barrier between amateur creators and commercial-grade distribution, forcing platforms to upgrade verification infrastructure. Saatchi Art leverages its curated discovery engine to sustain premium positioning for visual creators. Etsy anchors the craft-to-commerce pipeline with integrated print-on-demand logistics. Artfinder differentiates through direct artist-collector relationships that bypass traditional gallery gatekeepers.
The Europe Independent Artist Market encompasses self-directed creators who retain full copyright and distribution control across visual, sonic, and literary media, typically operating outside major label, publisher, or gallery representation contracts. These producers rely on digital file formats, blockchain provenance records, and direct-to-audience platforms to monetize original work without intermediary revenue splits. The revenue model segment shows crowdfunding and streaming royalties capturing margin pools as recurring income replaces one-off sales. Distribution through online platforms leads volume, though art galleries retain higher per-transaction value for established visual artists. Content format trends favor digital art and vinyl records as collectors seek scarcity signals in both natively digital and revived physical media.
GDPR compliance costs shape how platforms collect and monetize listener and viewer data across EU member states. The EU AI Act imposes transparency requirements on generative tools used by digital artists, affecting product standards for automated creation software. ECHA chemical safety rules under REACH govern physical merchandise production, particularly vinyl pressing and printed textiles. Stakeholders must decide whether to absorb regulatory compliance costs or pass them to creators through revised fee structures.
Market Dynamics
CE marking requirements for digital art authentication tools are compressing verification timelines across EU distribution platforms, forcing infrastructure upgrades that separate commercial-grade creators from hobbyist sellers.
Growth Catalysts
- EU AI Act transparency mandates:Automated creation software must disclose generative processes, creating competitive differentiation for compliant tool vendors serving digital artists in France and Germany.
- Blockchain provenance adoption:Collector demand for immutable ownership records drives platform integration of distributed ledger verification, particularly in high-value visual art transactions.
- Vinyl pressing revival:Manufacturing capacity expansion in Czech Republic and Poland supports independent musician merchandise strategies with tangible scarcity signaling.
Market Restraints
- GDPR compliance cost absorption:Listener data monetization restrictions elevate platform operational expenditures, squeezing margin structures for mid-tier streaming aggregators.
- Gallery representation concentration:Established visual artists in Berlin and London maintain preferential access to physical exhibition space, limiting emerging creator visibility.
- REACH chemical safety enforcement:Printed textile and vinyl production face ECHA scrutiny over phthalate and solvent content, extending material certification cycles.
Strategic Opportunities
- Portuguese and Spanish digital art underpenetration:Lisbon and Barcelona creator communities show platform adoption gaps relative to Northern European density, presenting first-mover positioning for localized discovery engines.
- CSRD sustainability reporting integration:ESG-aligned collector segments reward carbon-accounted provenance tracking, enabling premium pricing for verified low-impact production.
- Generative audio-visual convergence:Cross-format tools combining neural synthesis with interactive visual engines open immersive exhibition formats for hybrid creators.
Industry Challenges
- Smart contract audit expertise scarcity:Blockchain-native royalty distribution requires specialized legal-technical talent concentrated in Zug and London, creating recruitment bottlenecks for continental platforms.
- Legacy gallery CRM integration:Direct-to-collector platforms face friction merging provenance data with established auction house databases, fragmenting artist career documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Independent Artist Market |
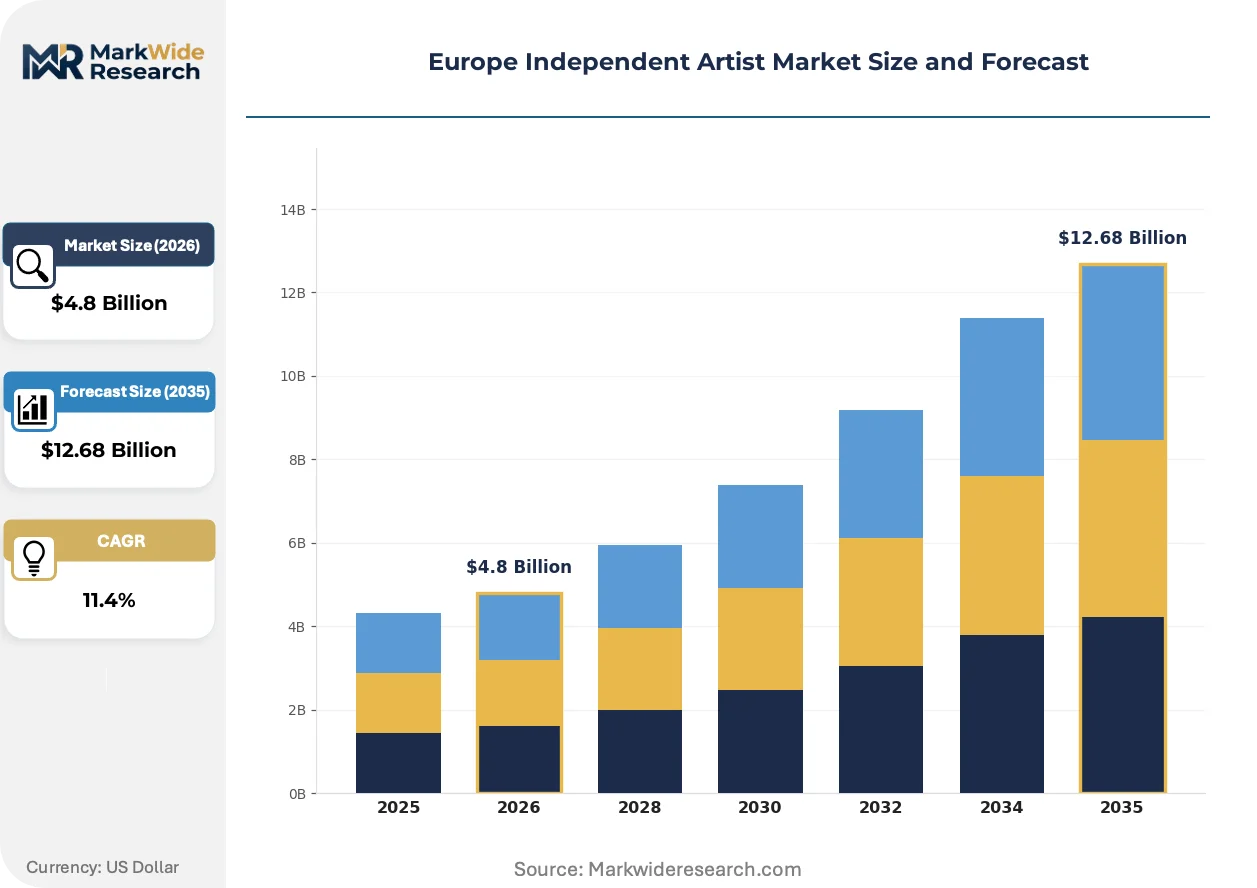
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Artist Type: Visual Artists, Musicians, Writers, Performers Distribution Channel: Online Platforms, Art Galleries, Music Festivals, Independent Bookstores Content Format: Digital Art, Vinyl Records, E-Books, Live Performances Revenue Model: Crowdfunding, Merchandise Sales, Streaming Royalties, Sponsorships |
| Companies Covered | Saatchi Art, Artsy, Artfinder, Etsy, Society6, Sadie Coles HQ, Thaddaeus Ropac, Kamel Mennour, Massimo De Carlo, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Independent Artist Market Trends and Innovations
Generative tooling and regulatory transparency frameworks are restructuring how independent creators establish authenticity and capture recurring revenue streams across European markets.
Neural audio synthesis is decomposing traditional studio production hierarchies by enabling single-operator composition workflows. Bedroom producers in Stockholm and Amsterdam adopt these tools at accelerating velocity, collapsing the barrier between demo and release-ready material. The technology is decomposing geographic clustering advantages that previously concentrated professional sound engineering in London and Berlin.
GDPR Article 22 automated decision-making restrictions constrain algorithmic curation engines deployed by streaming platforms. French CNIL enforcement actions against opaque recommendation systems force disclosure of ranking logic, compelling platforms to expose weighting factors that previously privileged major label catalog. Independent musicians in Paris and Lyon gain marginal visibility as transparency mandates dilute incumbency effects.
Collector procurement patterns favor direct artist relationships over intermediary-heavy acquisition channels. Artfinder-style platforms and Instagram-native discovery displace traditional gallery walk-ins for emerging visual artists in Milan and Vienna. This channel rotation concentrates in markets where physical gallery density lags collector household formation, particularly in Central European capitals.
Europe Independent Artist Market Segmentation
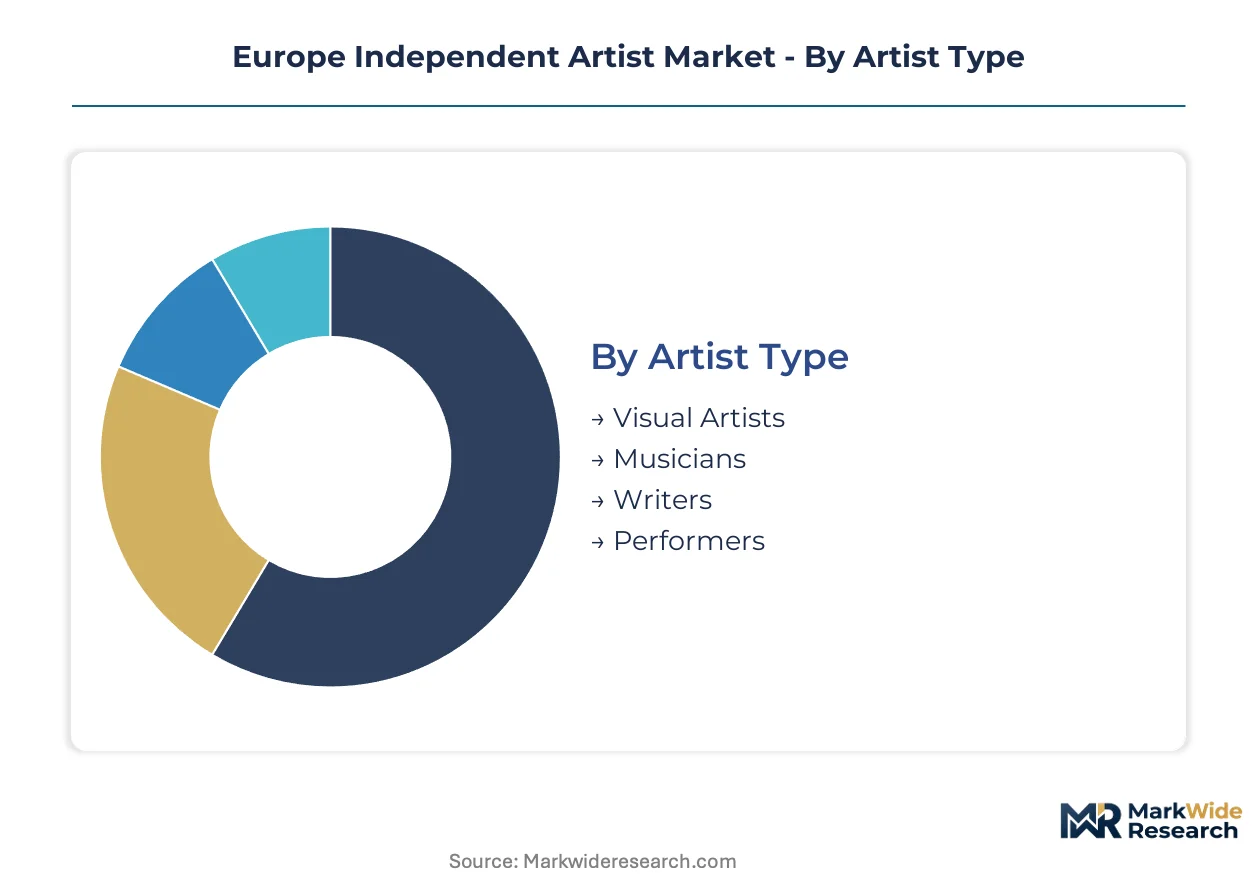
Segmentation in the Europe Independent Artist Market reveals how creator economics fragment across distribution control, format preferences, and revenue predictability. These divisions expose where platform infrastructure investments concentrate and where regulatory compliance costs bite deepest.
Artist Type:
Visual artists and musicians dominate export-led revenue flows, while writers and performers cluster in domestic consumption patterns.
- Visual Artists:Painters, sculptors, and digital creators leverage blockchain provenance tools to authenticate work for cross-border sales. Demand concentrates in Berlin and London gallery clusters where CE-marked authentication infrastructure enables commercial-grade distribution beyond local markets.
- Musicians:Independent producers retain full copyright through direct-to-audience platforms, with streaming royalties replacing label advances. Stockholm and Amsterdam bedroom producers deploy neural synthesis tools to collapse traditional studio hierarchies and accelerate release velocity.
- Writers:Self-published authors operate through e-book aggregators and print-on-demand logistics, serving niche genre readerships with limited translation investment.
- Performers:Theater and dance practitioners rely on live venue relationships and festival circuits, with revenue tied to physical presence and constrained by geographic touring radius.
Visual artists hold the largest share; momentum sits with musicians as streaming infrastructure matures.
Distribution Channel:
Channel selection determines margin capture, with direct platforms extracting less intermediary toll than legacy gatekeepers.
- Online Platforms:Digital marketplaces and streaming aggregators enable global reach without physical infrastructure. GDPR compliance costs elevate operational expenditures for mid-tier platforms serving French and German creator bases.
- Art Galleries:Physical exhibition spaces in Milan and Vienna maintain higher per-transaction value for established visual artists. Gallery representation concentration in Berlin and London limits emerging creator visibility.
- Music Festivals:Live event circuits provide merchandise revenue and audience discovery for independent musicians. Czech Republic and Poland vinyl pressing capacity supports tangible scarcity signaling at festival stalls.
- Independent Bookstores:Curated physical retail offers discoverability for literary creators outside algorithmic recommendation engines. Lisbon and Barcelona show platform adoption gaps relative to Northern European density.
Online platforms command volume leadership; galleries retain value concentration.
Content Format:
Format economics split between natively digital scarcity and revived physical media signaling.
- Digital Art:NFT-native and blockchain-verified creations enable immutable ownership records for collectors. EU AI Act transparency mandates reshape how generative tools authenticate automated creation processes.
- Vinyl Records:Physical music media revival concentrates manufacturing in Central European pressing plants. ECHA REACH chemical safety rules govern phthalate content in vinyl production, extending material certification cycles.
- E-Books:Digital literary distribution minimizes marginal production cost but faces discoverability challenges against platform algorithm opacity.
- Live Performances:Unrecorded ephemeral experiences command premium pricing for exclusive access, with revenue concentrated in metropolitan cultural capitals.
Digital art captures investment attention; vinyl demonstrates steepest expansion trajectory among physical formats.
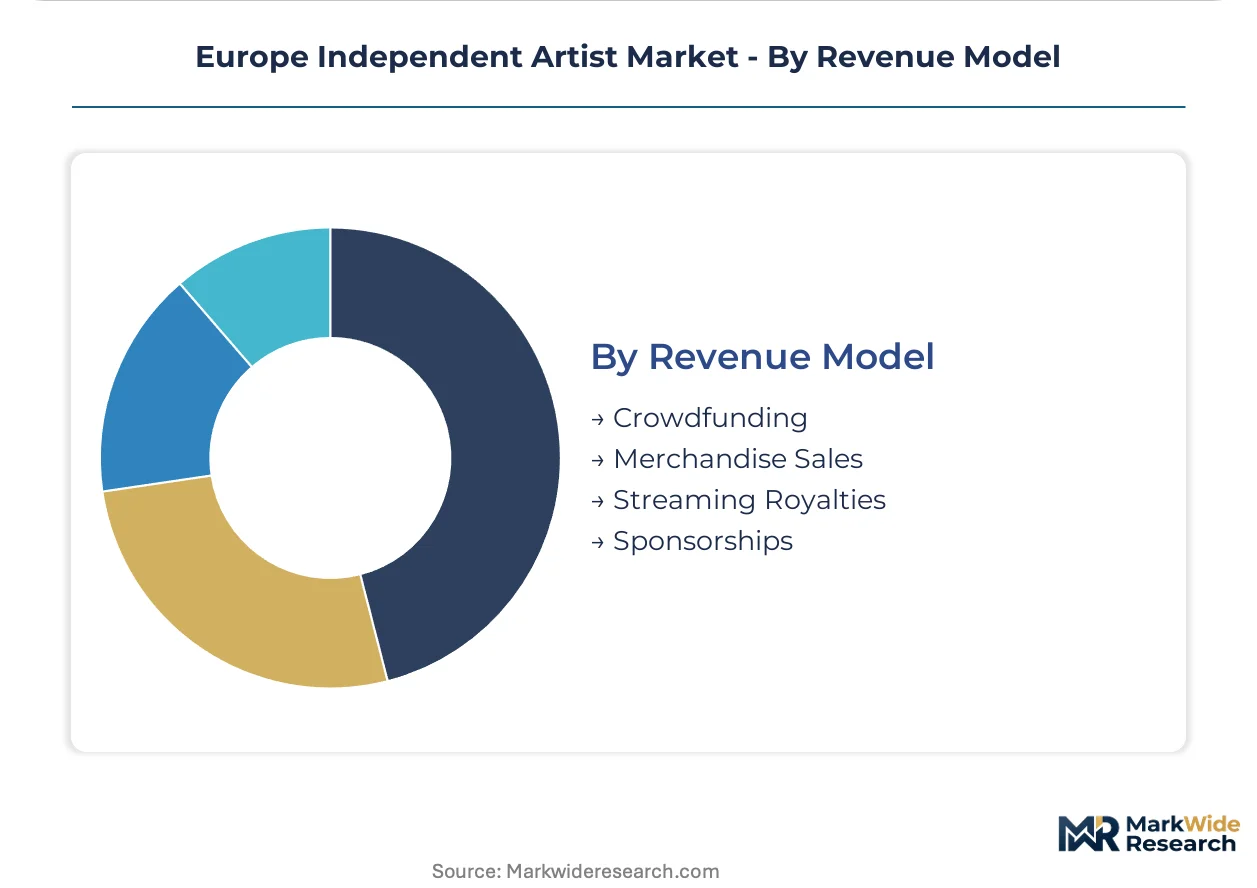
Revenue Model:
Revenue predictability separates recurring income streams from one-off transaction dependency.
- Crowdfunding:Patronage platforms enable project-specific financing with direct audience commitment. Portuguese and Spanish creator communities show underpenetration relative to Northern European platform density.
- Merchandise Sales:Branded physical goods extend artist revenue beyond core creative output. CSRD sustainability reporting integration enables premium pricing for carbon-accounted production chains.
- Streaming Royalties:Fractional per-play payments accumulate through volume, with GDPR Article 22 restrictions forcing algorithmic curation transparency that dilutes major label incumbency.
- Sponsorships:Brand alignment deals require audience demographic proof, favoring creators with established platform analytics access.
Streaming royalties anchor recurring revenue; crowdfunding gains share fastest among emerging creators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act transparency mandates and national cultural funding programs are redistributing creator activity across member states, with regulatory compliance costs and infrastructure density determining competitive positioning for independent artists.
Germany
Berlin's gallery clusters and Munich's digital music hubs anchor visual artist and musician concentrations respectively. GDPR enforcement by state data protection authorities elevates platform operational costs for mid-tier aggregators serving Bavarian and North Rhine-Westphalian creator bases. Leipzig's emerging art scene benefits from lower studio rents and state-level cultural subsidies that attract Polish and Czech cross-border talent.
United Kingdom
London's established gallery representation networks maintain preferential access to physical exhibition space for established visual artists. The UK's divergence from EU AI Act timelines creates regulatory friction for generative tool vendors serving cross-border creators. Manchester and Glasgow bedroom producer communities exploit neural synthesis tools to bypass traditional studio hierarchies concentrated in the capital.
France
Paris and Lyon independent musicians gain marginal visibility as CNIL enforcement actions force streaming platforms to disclose algorithmic curation weighting factors. The country's national pharmaceutical regulator framework does not apply here; instead, ANSM oversees product safety while CNIL governs data protection for creator platforms. Marseille's underdeveloped gallery infrastructure relative to collector household formation creates channel rotation opportunities for direct-to-collector platforms.
Italy
Milan's fashion-adjacent visual art market and Rome's independent music circuits split creator economics between premium merchandise signaling and streaming volume accumulation. ECHA REACH chemical safety rules govern vinyl pressing operations in Turin manufacturing zones, extending material certification cycles for independent musician merchandise strategies. Venice's biennial infrastructure concentrates high-value transaction liquidity for established visual artists.
Spain
Barcelona and Madrid creator communities show platform adoption gaps relative to Northern European density, presenting first-mover positioning for localized discovery engines. The country's national data protection authority enforces GDPR Article 22 restrictions on algorithmic curation transparency. Seville's flamenco heritage circuits remain underpenetrated by digital distribution infrastructure relative to acoustic music tourism demand.
Europe Independent Artist Market Competitive Landscape
Listed leaders compete with private specialists across authentication infrastructure and direct-to-creator platform economics. The vendor base separates into three tiers: curated discovery engines commanding premium positioning, craft-to-commerce pipelines with integrated logistics, and direct artist-collector relationship platforms bypassing traditional gatekeepers. Dominant competitive moves include CE marking compliance investments for authentication tools and blockchain provenance integration for high-value visual art transactions.
Within the curated discovery tier, Saatchi Art and Artsy exemplify premium positioning archetypes that sustain artist visibility through selective curation algorithms. Artfinder occupies a position representing direct relationship models that fragment traditional gallery gatekeeping. Among craft-to-commerce specialists, Etsy anchors mass-market creator monetization with print-on-demand logistics integration. These three company structures—Artfinder's private specialist model, Etsy's public marketplace scale, and Saatchi Art's curated premium approach—represent the competitive geometry compressing margins for mid-tier platform entrants.
| Leading Market Players |
|---|
| Saatchi Art |
| Artsy |
| Artfinder |
| Etsy |
| Society6 |
| Sadie Coles HQ |
| Thaddaeus Ropac |
| Kamel Mennour |
| Massimo De Carlo |
| Others |
Pricing and Supply Chain Analysis
CE marking requirements for digital art authentication tools gate both supply qualification and price differentiation simultaneously, forcing platforms to absorb compliance costs or tier service levels based on verification infrastructure investment.
Pricing Analysis
Certification level creates the primary spread between commercial-grade and hobbyist creator tiers. Three-tier pricing structure across premium, standard, and economy levels reflects authentication depth, with CE-marked provenance tools commanding premium positioning. Price differentiation stems from blockchain verification integration and GDPR compliance infrastructure depth. Pricing pressure stems from mid-tier platform margin compression as GDPR operational costs escalate. Emerging visual artists in Central European markets show highest price sensitivity; established Berlin and London gallery-represented creators demonstrate lowest.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp corridors elevates inbound logistics costs for vinyl pressing raw materials and gallery exhibition hardware. Manufacturing concentration centers on Czech Republic and Poland for vinyl production, Germany for authentication hardware, and Netherlands for platform server infrastructure. Raw material dependencies include PVC compounds, rare earth elements for display technology, and cloud compute capacity. Single-source vulnerability sits with blockchain oracle services concentrated in Zug and London. Distribution runs through direct-to-creator platforms for volume, with specialized logistics partners handling high-value physical artwork.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in this market hinge on interoperability between authentication infrastructure and creator monetization tools, with EU AI Act compliance timelines forcing ecosystem consolidation decisions.
For Market Incumbents: Secure blockchain provenance integration partnerships before smart contract audit talent scarcity deepens. Lock in CE marking certification pathways for authentication tools to preempt regulatory displacement. Defend against neural synthesis tool vendors eroding traditional studio service margins by embedding generative capabilities into existing creator workflows.
For New Entrants and Emerging Players: Lead with localized discovery engines targeting Portuguese and Spanish creator communities where platform density lags Northern Europe. Exploit underpenetration in Barcelona and Lisbon visual art markets through direct artist-collector relationship models. Deploy CSRD-aligned carbon accounting as a go-to-market wedge for ESG-conscious collector segments.
For Investors and Strategic Acquirers: EU AI Act transparency mandates reshape the acquisition landscape by elevating compliant tool vendors above opaque competitors. Five-to-ten year viability favors platforms with integrated authentication-logistics-provenance stacks. Target acquisition archetypes include mid-tier streaming aggregators with GDPR-compliant data infrastructure. Watch CNIL enforcement patterns against algorithmic opacity as an inflection signal for independent musician visibility gains.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Certification Pathway | Unlocks commercial-grade distribution for authentication tool vendors serving German gallery clusters. |
| Blockchain Provenance Integration | Enables immutable ownership records that satisfy collector demand in high-value visual art transactions. |
| GDPR-Compliant Data Infrastructure | Reduces operational cost exposure for mid-tier platforms serving French and German creator bases. |
| Neural Synthesis Capability Embed | Collapses studio production hierarchies for Stockholm and Amsterdam bedroom producers. |
| CSRD-Aligned Carbon Accounting | Captures premium pricing from ESG-conscious collectors seeking verified low-impact production chains. |
Research Methodology
The analysis maps visual art authentication, music streaming monetization, digital provenance tools, and creator platform economics, each validated through platform operators, gallery directors, independent musicians, and regulatory affairs specialists. Primary interviews with CTOs at streaming aggregators, procurement leads at vinyl pressing plants, and compliance officers at marketplace platforms combined with secondary validation against ECHA REACH filings, CNIL enforcement records, EU AI Act implementation guidance, and customs data for vinyl raw material flows. Bottom-up creator enumeration triangulated against top-down platform revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include artist type, distribution channel, content format, and revenue model, with regional regulatory cluster as an industry-specific overlay. CAGRs derived from trend extrapolation of streaming royalty growth, vinyl pressing capacity expansion, and digital art transaction velocity. Forecast inputs incorporated GDPR compliance cost trajectories and EU AI Act implementation timelines without specific year anchoring.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of transparency mandates, stable blockchain infrastructure costs, and continued collector preference for scarcity signaling would require recalibration. Forecasts reflect assumptions about platform adoption curves and authentication technology maturation. Specific risks that could revise projections include ECHA chemical safety rule expansion, major label litigation against algorithmic transparency, and smart contract security breaches. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Music Publishing Market
Music
Music App Market
Music
Virtual Musical Instruments Market
Music
Electronic Dance Music (EDM) Market
Music
Vinyl Records Market
Music
Music Production Software Market
Music
Independent Music Publishing Market
Music
Global in-Store Music Service Market
Music
Music Distribution Services Market
Music
Asia-Pacific Independent Artist Market
Music
Global Background Music Market
Music
Traditional Chinese Instruments Market
Music
Music Synthesizers Market
Music
United States Live Music Market
Music
Musical Groups and Artists Market
Music
Global Stock Music Market