
 Global in-Store Music Service Market | 2026-2036
Global in-Store Music Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global in-Store Music Service Market Outlook
Software-defined playlist curation is decoupling content delivery from proprietary hardware bundles, letting retailers source music independently of legacy installation contracts. Mood Media Corporation leverages its installed base of in-venue audio hardware to sustain recurring licensing relationships with franchise operators. Spotify Technology S.A. competes through API-first architecture that lets hospitality brands embed streaming directly into mobile ordering and loyalty applications. Soundtrack Your Brand AB specializes in rights-cleared catalogs designed for commercial environments, avoiding the liability gaps that consumer-facing platforms create for business subscribers.
In-store music services encompass the licensed delivery of audio content to commercial premises, typically distributed via IP-based streaming protocols with bitrate specifications ranging from 128 kbps to 320 kbps and integrated through cloud-managed endpoints that synchronize playback across multiple zones. These systems function primarily to reinforce brand identity, regulate customer dwell time, and mask operational noise in public-facing environments. Background music within the service type dimension retains the largest revenue footprint due to its ubiquity across retail and hospitality formats, while custom playlists capture expanding margin pools as chains invest in sonic differentiation. Streaming services anchor the technology segment through scalable deployment, though digital signage convergence is gaining traction where audio-visual coordination matters for promotional timing.
FCC guidelines on internet radio royalty rates, EU copyright directives governing platform liability for commercial use, and ASCAP/BMI consent decrees in the United States collectively shape licensing costs and legal exposure for providers serving business customers. These frameworks determine whether platforms must secure direct mechanical rights or rely on statutory licenses, directly affecting pricing architecture and market entry barriers. Stakeholders must track evolving collective bargaining agreements and territorial rights fragmentation as streaming volumes shift from consumer to commercial accounts.
Market Dynamics
Software-defined playlist curation is severing the historical link between audio content delivery and proprietary hardware bundles, forcing incumbent providers to unbundle service layers that were previously locked into multi-year installation contracts.
Growth Catalysts
- EU Copyright Directive Article 17:Platform liability provisions are compelling commercial streaming providers to secure direct mechanical rights, creating compliant licensing frameworks that attract risk-averse franchise operators.
- Specialty coffee chains:This buyer segment is expanding procurement of curated audio environments to differentiate customer experience and extend dwell time in premium retail formats.
- IP-based streaming protocols:Cloud-managed endpoints with zone synchronization capabilities are reducing deployment friction for multi-location retail networks.
Market Restraints
- Collective rights fragmentation:Territorial variations in ASCAP, BMI, and SESAC licensing requirements create administrative burden and cost unpredictability for cross-border operators.
- Bitrate infrastructure costs:Sustained 320 kbps streaming across multiple zones consumes substantial bandwidth, elevating operational expenditure for venues in markets with limited fiber penetration.
- Consent decree uncertainty:Ongoing judicial review of ASCAP and BMI rate-setting mechanisms in the United States introduces pricing volatility that complicates long-term contract structuring.
Strategic Opportunities
- Digital signage convergence:Audio-visual coordination for promotional timing represents underexploited white space where music services can embed into broader retail media networks.
- Mobile application integration:Hospitality brands are embedding streaming APIs directly into loyalty and ordering platforms, creating stickier vendor relationships.
- Rights-cleared catalog specialization:Purpose-built commercial libraries that preempt liability gaps in consumer-facing platforms offer defensible positioning against generalist competitors.
Industry Challenges
- Cross-zone synchronization latency:Achieving sub-50 millisecond audio alignment across distributed endpoints requires specialized network engineering that strains mid-market provider capabilities.
- Mechanical rights verification:Confirming publisher-level clearances for background music deployments demands legal infrastructure that smaller operators struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in-Store Music Service Market |
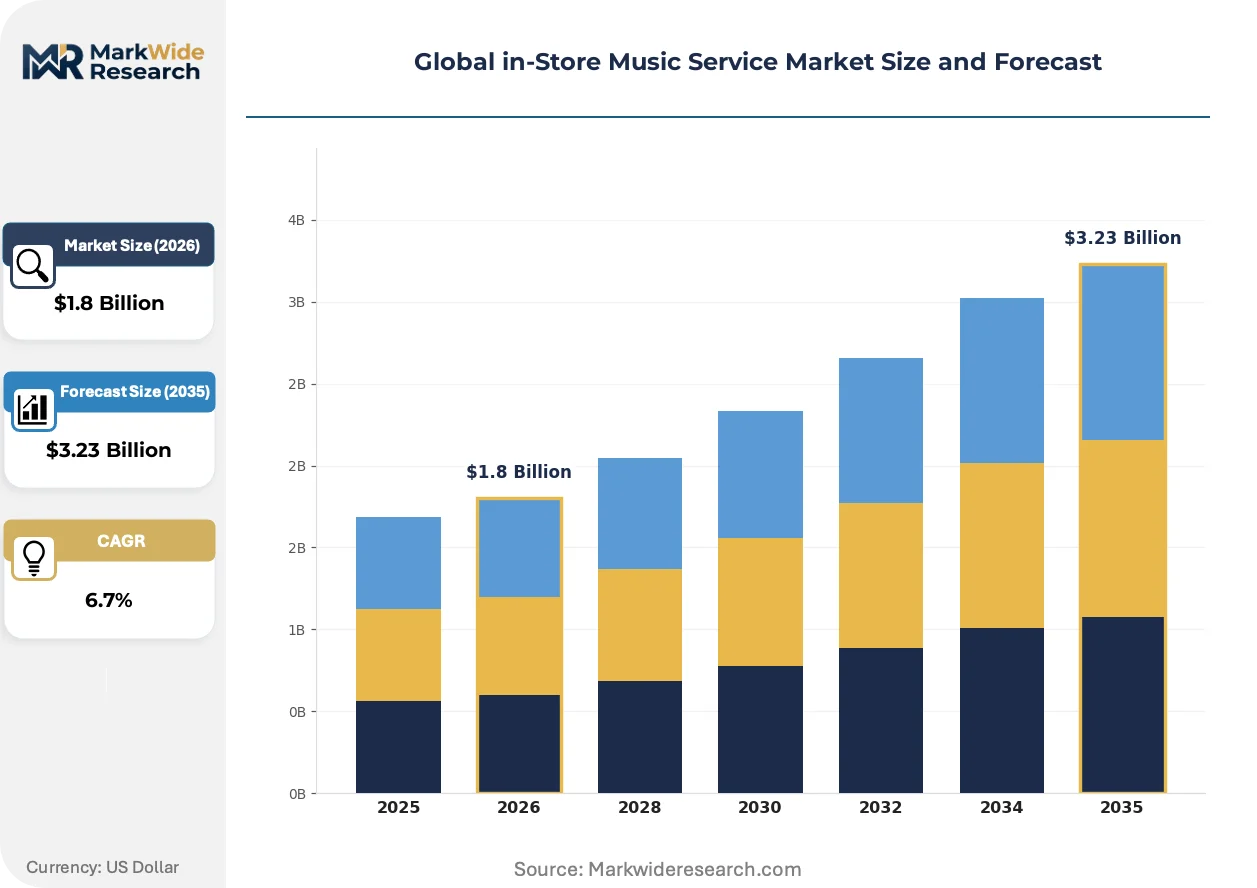
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Background Music, Custom Playlists, Jukebox Services, Licensing Solutions End User: Retail Stores, Restaurants, Hotels, Cafes Technology: Streaming Services, Digital Signage, Audio Systems, Mobile Applications Distribution Channel: Direct Sales, Resellers, Online Platforms, Partnerships |
| Companies Covered | Mood Media Corporation, Spotify Technology S.A., PlayNetwork, Inc., Soundtrack Your Brand AB, Pandora for Business, SiriusXM Holdings Inc., Cloud Cover Music, TouchTunes Music Corporation, Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in-Store Music Service Market Strategic Shifts
Artificial intelligence is penetrating playlist curation workflows, compressing the timeline between brand brief and deployment-ready audio environments while raising questions about creative control and sonic authenticity.
Machine learning-driven mood classification is automating the translation of brand guidelines into tempo, key, and genre parameters that previously required human music supervisors. Quick-service restaurant chains with standardized formats across hundreds of locations are adopting these tools most aggressively. The technology is automating the elimination of manual curation bottlenecks that constrained scaling for mid-tier retail accounts.
The EU Copyright Directive's Article 17 provisions are reshaping platform liability frameworks for commercial streaming, requiring direct licensing relationships with rights holders rather than reliance on safe harbor protections. This regulatory architecture elevates compliance costs for generalist streaming providers while creating structural advantage for specialists with pre-negotiated publisher agreements. Franchise retail networks operating across multiple EU member states face the steepest adaptation burden as they reconcile national implementation variations.
Subscription models are displacing perpetual licensing arrangements as the dominant commercial relationship structure, unbundling hardware ownership from content access and compressing switching costs for retail buyers. Hospitality groups with seasonal footprint variations are driving this transition, preferring operational expenditure treatment and deployment flexibility. This pattern is most pronounced in the United States, where franchise standardization protocols facilitate rapid vendor rotation across store networks.
Global in-Store Music Service Market Segmentation
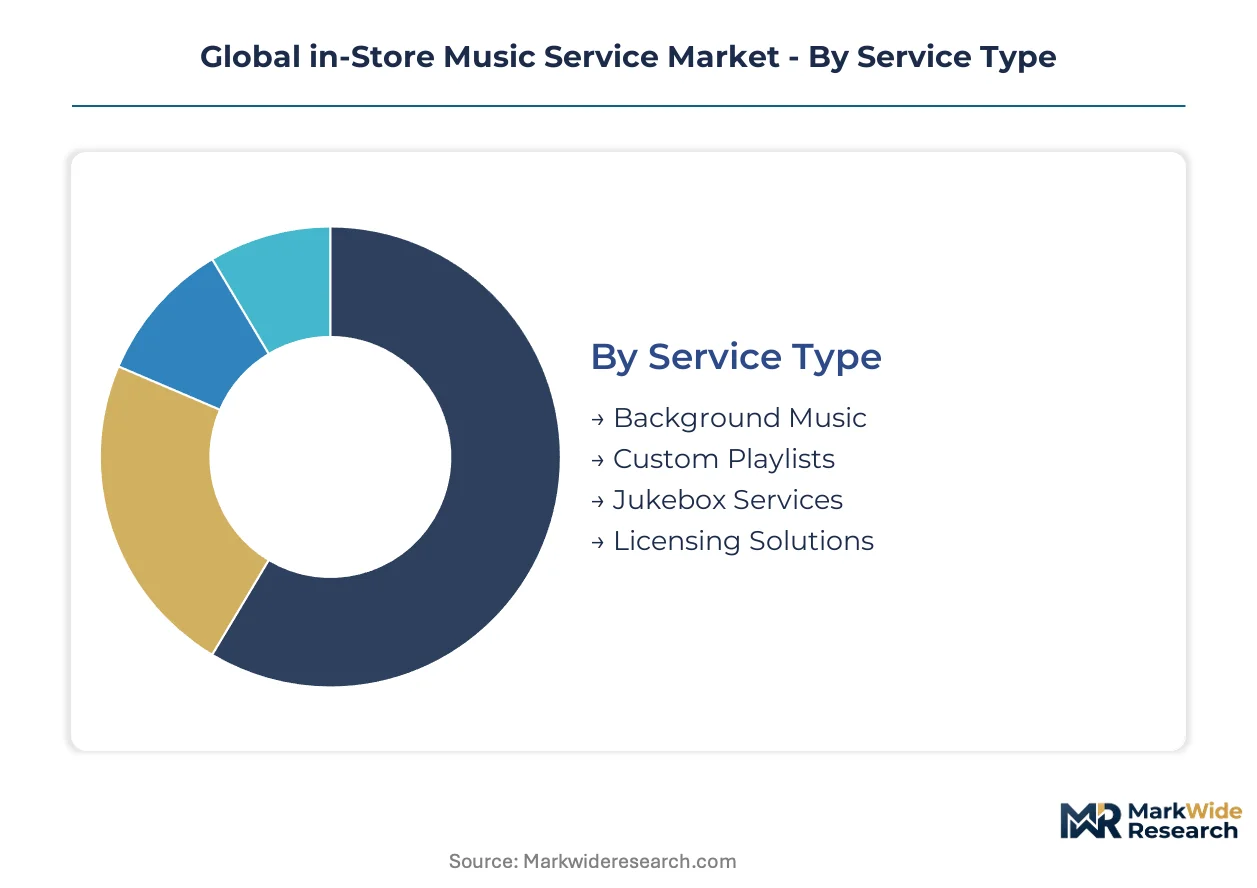
Segmentation in the in-store music service market reveals how procurement priorities diverge across venue types and technical deployment models. Buyers weigh licensing risk tolerance against sonic customization needs, while technology choices determine integration complexity with existing retail infrastructure.
Service Type:
Franchise operators select service tiers based on brand consistency requirements and legal exposure appetite.
- Background Music:Continuous audio streams at 128-320 kbps deliver standardized playlists through cloud-managed endpoints. Demand concentrates in United States big-box retail networks where FCC compliance and ASCAP rate certainty outweigh customization needs.
- Custom Playlists:Bespoke curation aligned to brand guidelines, tempo mapping, and dwell-time objectives. Specialty coffee chains in Germany and France are expanding procurement fastest as they compete on third-place experience differentiation.
- Jukebox Services:Customer-controlled selection interfaces for hospitality venues seeking participatory entertainment.
- Licensing Solutions:Direct mechanical rights procurement bypassing statutory license frameworks, critical for EU Copyright Directive Article 17 compliance.
Background Music leads on scale; Custom Playlists leads on momentum.
End User:
Operational noise masking versus brand identity reinforcement drives divergent technical specifications across venue categories.
- Retail Stores:Multi-zone synchronization for consistent brand atmosphere across floor plans. United States franchise networks standardize vendor selection through corporate procurement protocols.
- Restaurants:Tempo-calibrated audio regulating table turnover rates. Full-service chains in Italy and Spain are adopting mood-classification algorithms fastest.
- Hotels:Property-wide audio zoning spanning lobbies, elevators, spas, and guest rooms.
- Cafes:Premium audio environments extending customer dwell time in high-margin formats.
Retail Stores dominates contract volume; Cafes shows steepest expansion trajectory.
Technology:
Integration depth with existing venue systems determines deployment friction and switching costs.
- Streaming Services:IP-based delivery with API architectures enabling loyalty app embedding. Hospitality groups in United Kingdom prefer operational expenditure models with seasonal flexibility.
- Digital Signage:Audio-visual convergence for promotional timing coordination. Netherlands retail media networks are piloting combined deployments fastest.
- Audio Systems:Proprietary hardware bundles with zone control capabilities.
- Mobile Applications:Direct-to-consumer streaming integration within branded ordering platforms.
Streaming Services anchors revenue; Digital Signage gains share fastest.
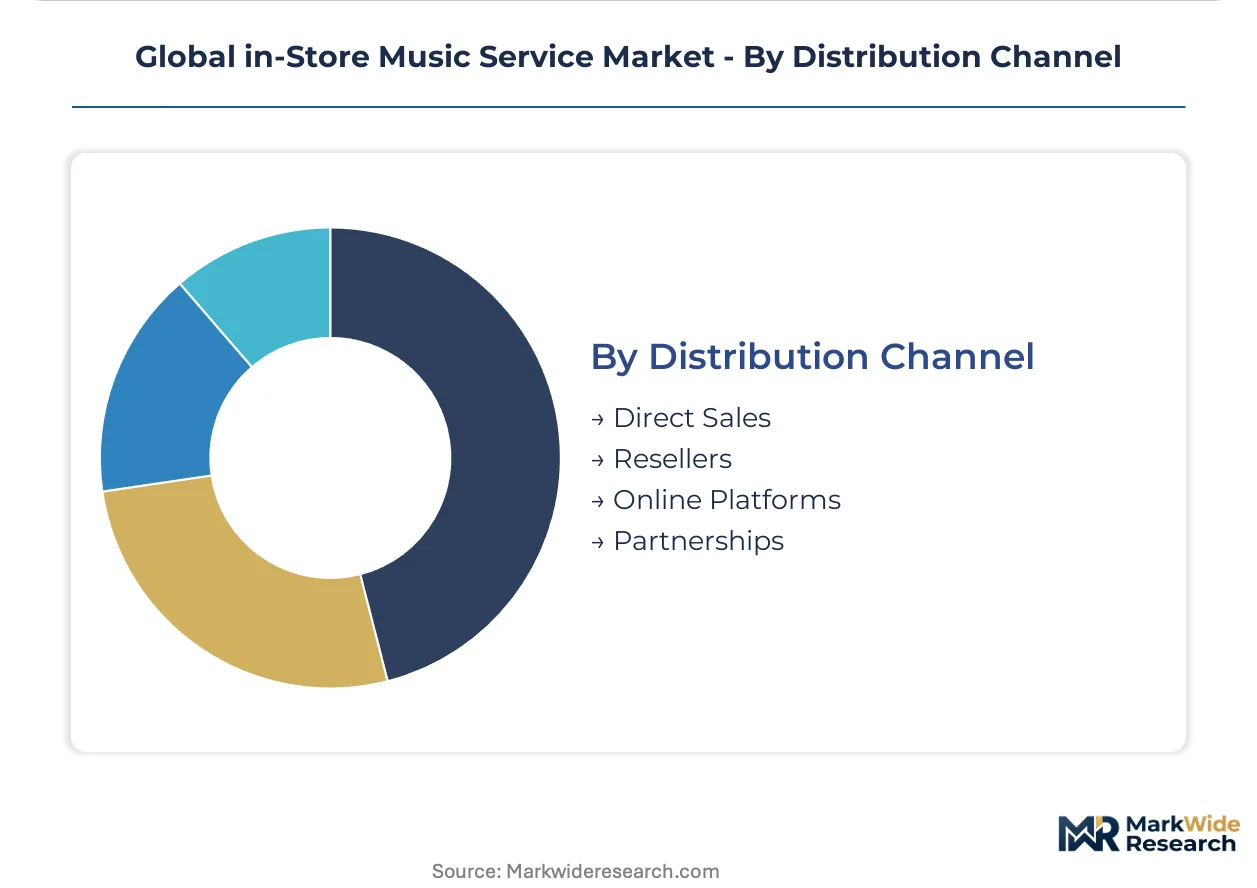
Distribution Channel:
Contract structure and relationship economics shape channel selection for multi-location deployments.
- Direct Sales:Enterprise relationships with franchise headquarters for standardized rollouts. United States-based QSR chains favor this channel for rate negotiation leverage.
- Resellers:Local installation and support networks reducing deployment friction in fragmented markets.
- Online Platforms:Self-service provisioning for independent operators with limited technical requirements.
- Partnerships:Embedded distribution through POS providers, property management systems, or audio hardware OEMs.
Direct Sales captures largest deal size; Partnerships scales most efficiently.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States franchise standardization contrasts with Germany's rights-holder direct licensing complexity, illustrating how regulatory architecture shapes commercial music deployment patterns across developed markets.
United States
Franchise retail networks drive vendor standardization through corporate procurement protocols that prioritize ASCAP and BMI rate certainty. FCC guidelines on internet radio royalty rates establish the baseline cost structure for commercial streaming providers. Multi-location QSR chains in Texas and California represent the densest concentration of cloud-managed audio endpoints.
Germany
Specialty coffee chains in Berlin and Munich procure bespoke audio environments to extend customer dwell time in premium third-place formats. The EU Copyright Directive's Article 17 implementation requires direct mechanical rights negotiations, elevating compliance costs for generalist platforms. Rights-cleared catalog specialists concentrate in Hamburg's media cluster.
United Kingdom
Hospitality groups prefer operational expenditure models with seasonal flexibility, accelerating subscription displacement of perpetual licenses. API-first streaming architectures embed into London-based loyalty and mobile ordering platforms. Manchester and Birmingham retail media networks pilot audio-visual convergence for promotional timing.
France
Full-service restaurant chains adopt mood-classification algorithms to regulate table turnover rates through tempo-calibrated audio. Territorial implementation variations of EU copyright provisions create administrative burden for cross-border operators. Parisian hospitality technology clusters drive demand for zone-synchronized property-wide audio systems.
Netherlands
Retail media networks pioneer combined digital signage and audio deployments faster than neighboring markets. Amsterdam-based hospitality groups leverage IP-based streaming protocols with cloud-managed endpoints for multi-zone synchronization. Eindhoven's technology corridor supplies network engineering talent for sub-50 millisecond latency audio alignment.
Global in-Store Music Service Market Competitive Environment
Top-tier vendors anchor enterprise franchise relationships, while mid-tier specialists compete on rights-cleared catalog depth and deployment flexibility. The market exhibits tiered concentration where installed hardware bases sustain recurring licensing revenue against API-first challengers. Three archetypes dominate: legacy hardware-software bundlers, streaming-native platform providers, and rights-specialist pure-plays. Competitive moves center on unbundling service layers from proprietary hardware and embedding streaming APIs into third-party retail systems.
Among North American incumbents, Mood Media Corporation exemplifies the hardware-anchored archetype through its installed base of in-venue audio endpoints. Spotify Technology S.A. occupies the platform-native position with architecture designed for hospitality application embedding. Soundtrack Your Brand AB represents the rights-specialist category with purpose-built commercial catalogs that preempt liability gaps. These three anchors illustrate the strategic divergence between physical infrastructure control, software integration depth, and regulatory risk mitigation as competitive vectors.
| Leading Market Players |
|---|
| Mood Media Corporation |
| Spotify Technology S.A. |
| PlayNetwork, Inc. |
| Soundtrack Your Brand AB |
| Pandora for Business |
| SiriusXM Holdings Inc. |
| Cloud Cover Music |
| TouchTunes Music Corporation |
| Apple Inc. |
| Others |
Value Chain & Pricing Dynamics
Franchise retail networks in the United States anchor procurement volume and compress pricing power toward standardized subscription tiers, while EU Copyright Directive compliance costs elevate entry thresholds for cross-border operators. This buyer concentration rewards providers with pre-negotiated mechanical rights and penalizes generalist platforms facing liability exposure.
Pricing Analysis
Capacity additions in cloud infrastructure hubs are reshaping price floors for streaming delivery, enabling mid-market entrants to undercut legacy hardware-software bundles. Three-tier pricing structure across premium, standard, and economy levels differentiates by zone count, bitrate quality, and rights-clearance depth. Cost compression in the standard tier intensifies because API-first architectures reduce deployment overhead. Quick-service restaurant chains exhibit highest price sensitivity due to thin operating margins, while luxury hospitality groups prioritize liability indemnification over unit cost.
Supply Chain Analysis
Network engineering talent pools in Eindhoven, Amsterdam, and Berlin constrain scaling velocity for latency-sensitive zone synchronization deployments. Content licensing draws from rights-holder clusters in Hamburg, London, and Los Angeles, with mechanical clearance workflows resting on publisher-direct relationships. Single-source vulnerability concentrates in cloud-managed endpoint firmware providers. Distribution runs through direct enterprise sales for franchise headquarters, supplemented by reseller networks in fragmented European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where specialty coffee chains and premium hospitality groups are shifting procurement toward rights-cleared catalogs with direct publisher agreements, rewarding compliance infrastructure over raw scale.
For Market Incumbents: Anticipate API-first challengers embedding streaming into loyalty platforms by accelerating unbundling of hardware from content subscriptions. Franchise operators' vendor rotation protocols threaten installed-base revenue; defend through deeper integration with point-of-sale and property management systems. Vertical integration into cloud-managed endpoint manufacturing preserves margin control against commodity hardware competition. For New Entrants and Emerging Players: Digital signage integrators represent the most penetrable channel partner type for audio-visual convergence plays. White space concentrates in Netherlands retail media networks and United Kingdom hospitality groups seeking seasonal subscription flexibility. Target mid-tier restaurant chains in Italy and Spain with tempo-calibration algorithms as the entry wedge, bypassing saturated United States franchise procurement. For Investors and Strategic Acquirers: Private equity firms with retail technology portfolios are the most active acquirer in this space, drawn by recurring revenue visibility and unbundling-driven consolidation opportunities. Long-term viability hinges on regulatory compliance infrastructure rather than catalog scale alone. Watch EU member state implementation variations of Article 17 as the inflection signal—accelerated enforcement timelines would compress valuation multiples for generalist platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Rights-Cleared Catalog Expansion | Direct publisher agreements in Hamburg and London preempt Article 17 liability gaps for franchise operators. |
| API-First Architecture Deployment | Spotify's hospitality embedding model enables loyalty app integration that raises switching costs. |
| Cloud-Managed Endpoint Manufacturing | In-house production of zone-synchronization hardware reduces dependency on Eindhoven engineering clusters. |
| Digital Signage Convergence | Netherlands retail media pilots demonstrate audio-visual coordination for promotional timing. |
| Seasonal Subscription Flexibility | United Kingdom hospitality groups prefer operational expenditure models supporting footprint variation. |
Study Parameters
Direct dialogue with franchise procurement directors, hospitality technology officers, music licensing attorneys, cloud infrastructure architects, and retail media network operators grounded qualitative assessment, cross-referenced with FCC docket filings, EU Copyright Directive implementation texts, ASCAP rate court documents, and franchise disclosure filings. Bottom-up endpoint deployment estimates triangulated against top-down licensing revenue flows.
Segmentation outputs across service type, end user, technology, and distribution channel dimensions informed projections across the analysis window. CAGRs derived from licensing volume trajectories, cloud endpoint shipment patterns, and franchise expansion schedules. Model inputs incorporated bitrate infrastructure cost curves and territorial rights fragmentation indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ASCAP/BMI consent decree revisions and EU member state enforcement divergence. Assumptions reflect current regulatory architecture and franchise standardization protocols. Material deviation in mechanical rights clearance timelines or cloud infrastructure cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Traditional Music Market
Music
Independent Music Publishing Market
Music
Global Free Music Making Software Market
Music
United States Live Music Market
Music
Virtual Musical Instruments Market
Music
Global Background Music Market
Music
Traditional Chinese Instruments Market
Music
Music Production Software Market
Music
Musical Groups and Artists Market
Music
Music App Market
Music
Asia-Pacific Independent Artist Market
Music
Music Publishing Market
Music
Discography Market
Music
Music Synthesizers Market
Music
Music Distribution Services Market
Music
Vinyl Records Market