
 Europe Arts Promoter Market | 2026-2036
Europe Arts Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Arts Promoter Market Insights
Digital streaming platforms is recalibrating how live arts promoters monetize audience attention and allocate production budgets. Art Basel leverages its exhibition infrastructure to anchor premium visual arts programming across multiple European capitals. Sotheby's sustains competitive positioning through integrated private sales channels that parallel its auction operations. Christie's differentiates by cultivating digital-native collector segments through online viewing rooms and curated digital art platforms.
An arts promoter functions as a specialized intermediary that designs, finances, and executes cultural events across theater, visual arts, music, and dance disciplines, typically operating through commission-based, fee-for-service, retainer, or project-based engagement models. The role encompasses talent booking, marketing services, sponsorship procurement, and full event management, with production specifications varying by venue capacity, technical rider complexity, and digital hybridization requirements. Talent booking and event management command the deepest margin pools due to recurring artist relationships and scalable production templates, while marketing services and sponsorships represent faster-growing segments as brands seek measurable cultural association metrics. Music and visual arts programming generates disproportionate revenue concentration relative to theater and dance, reflecting broader audience addressability and sponsorship compatibility.
The EU Creative Europe programme, national cultural ministries in France and Germany, and the UK's Arts Council shape funding accessibility and content eligibility criteria for promoters seeking public co-financing. GDPR compliance requirements and emerging EU AI Act provisions on algorithmic content recommendation are recalibrating how promoters deploy data-driven audience targeting and personalized programming tools. Stakeholders must monitor evolving national recovery funding mechanisms and digital platform content licensing frameworks to calibrate investment in hybrid physical-virtual production capabilities.
Market Dynamics
Hybrid physical-virtual production infrastructure is compressing venue capacity constraints across metropolitan France, Germany, and the United Kingdom, enabling promoters to monetize single events through multiple distribution channels simultaneously.
Growth Catalysts
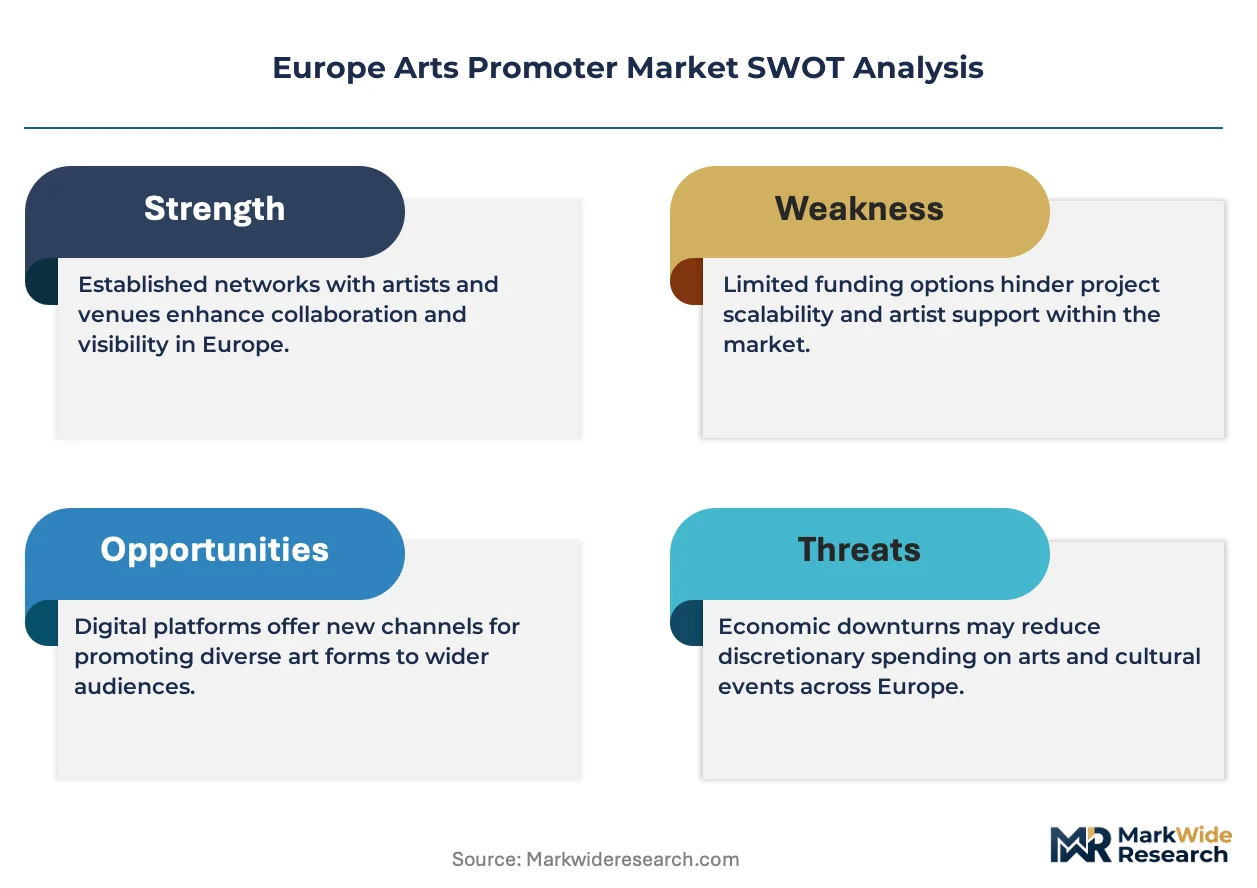
- EU Creative Europe programme:Public co-financing mechanisms expand promoter capabilities for cross-border touring circuits and collaborative production networks.
- Corporate patronage:Brand investment in experiential music and immersive visual arts sectors deepens sponsorship pools within London, Paris, and Berlin metropolitan clusters.
- Digital hybridization:Streaming platform partnerships create secondary revenue streams from live cultural programming without cannibalizing in-person attendance.
Market Restraints
- GDPR compliance costs:Data-driven audience targeting and personalized programming tools require substantial legal and technical infrastructure investment.
- Venue supply concentration:Premium theater and concert hall availability clusters in capital cities, constraining touring economics for secondary markets.
- Talent booking inflation:Recurring artist relationships command escalating guarantee structures, compressing margin pools for mid-tier promoters.
Strategic Opportunities
- Emerging EU AI Act provisions:Algorithmic content recommendation frameworks create first-mover advantages for promoters investing in compliant personalization engines.
- Immersive visual arts expansion:Underpenetrated museum and gallery partnerships in Milan, Madrid, and Amsterdam offer white-space for experiential programming.
- National digital arts infrastructure:France and Germany's public investment in virtual production facilities lowers capital barriers for hybrid event experimentation.
Industry Challenges
- Technical rider complexity:Scalable production templates struggle to accommodate artist-specific digital hybridization requirements without customization overhead.
- Sponsorship metric standardization:Brands demand measurable cultural association data that lacks industry-wide certification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Arts Promoter Market |
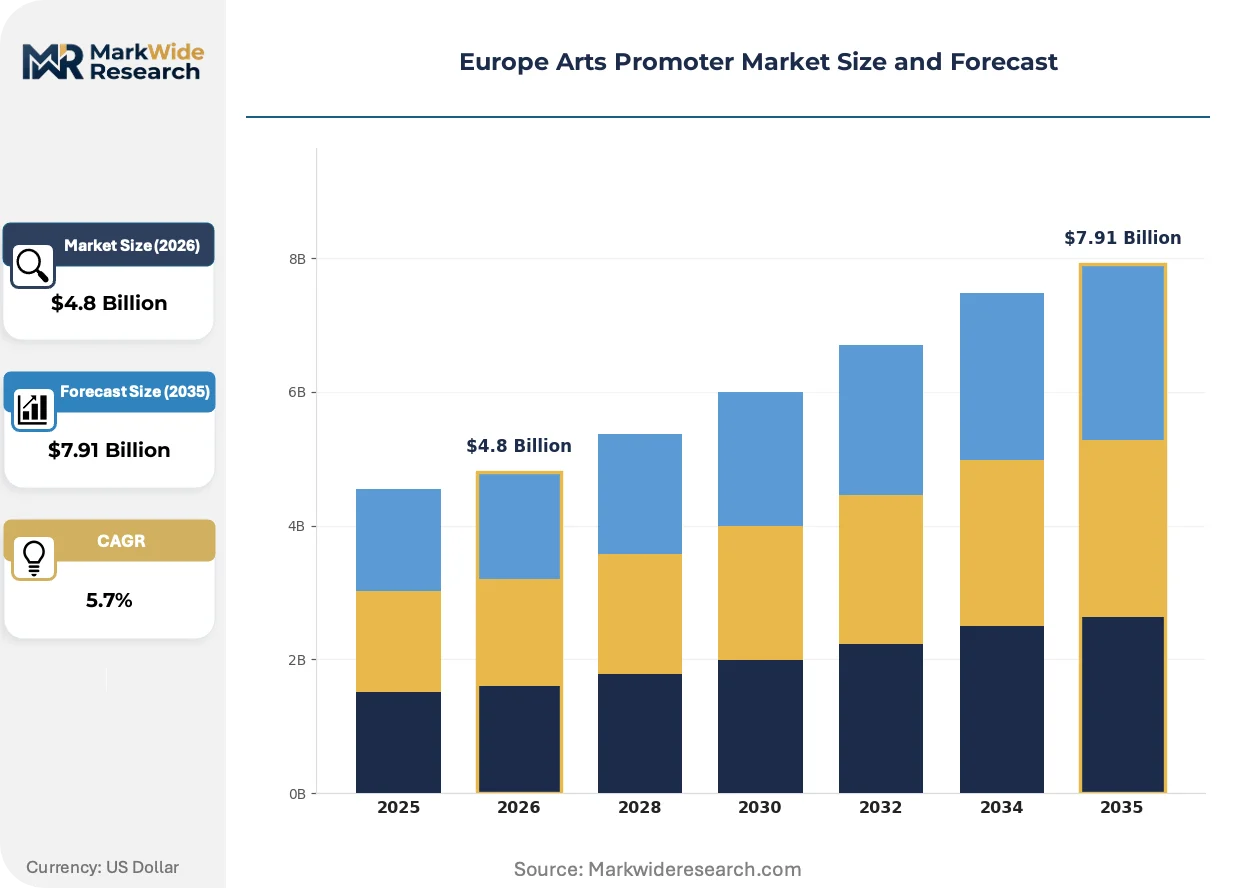
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Management, Talent Booking, Marketing Services, Sponsorships Client Type: Corporations, Schools, Non-Profits, Individuals Art Form: Theater, Visual Arts, Music, Dance Engagement Model: Commission-Based, Fee-For-Service, Retainer, Project-Based |
| Companies Covered | The Art Wolf, Europe's Art, Artshead, Marshall Art, Art Basel, Perrotin, Sotheby's, MTArt Agency, Christie's, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Arts Promoter Market Trends and Innovations
Live arts distribution is fragmenting across synchronous streaming, asynchronous on-demand, and physical attendance layers, forcing promoters to rebuild production workflows around multi-channel monetization rather than single-event economics.
Extended reality production suites are converging with traditional stage design workflows. Promoters in the United Kingdom and Germany deploy volumetric capture and real-time rendering for hybrid concerts. This technology convergence is compressing the technical rehearsal window while expanding addressable audience beyond venue capacity.
The EU AI Act's algorithmic transparency requirements are recalibrating how promoters deploy recommendation engines for personalized programming. Compliance investments concentrate in French and German markets where national regulators interpret provisions most stringently. Smaller promoters face disproportionate adaptation costs relative to integrated platform operators.
Audience attention is fragmenting across short-form content platforms, forcing promoters to unbundle traditional subscription models. Metropolitan France sees fastest adoption of micropayment access for individual performances rather than season passes. Younger demographics in London and Paris drive this behavioral shift, prioritizing flexibility over loyalty commitments.
Europe Arts Promoter Market Segmentation
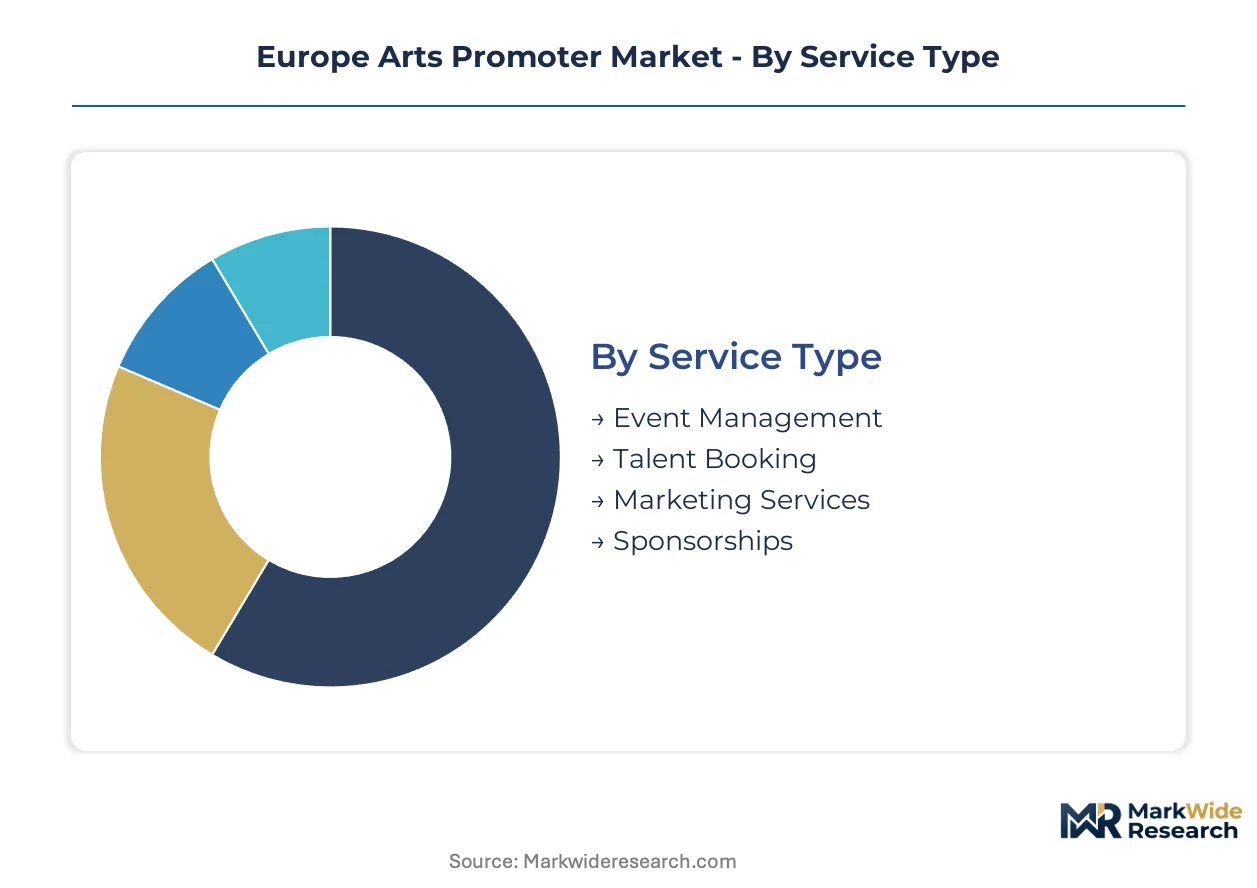
Arts promoters configure service portfolios around client risk tolerance and production complexity. Segment boundaries blur as hybrid physical-virtual delivery forces retooling of engagement terms and art form specialization.
Service Type:
Upgrade cycles accelerate as streaming infrastructure demands new technical competencies from established service lines.
- Event Management:Encompasses venue logistics, production coordination, and on-site execution for live programming. Demand concentrates in London and Paris metropolitan clusters where corporate clients require seamless hybrid delivery for shareholder and employee events. GDPR-compliant attendee data management now consumes 15-20% of planning budgets.
- Talent Booking:Secures artist agreements, negotiates guarantee structures, and manages contractual riders. Recurring relationships with German electronic music producers and French contemporary visual artists command premium positioning. Escalating guarantee inflation compresses margins for mid-tier promoters without multi-year artist development pipelines.
- Marketing Services:Audience development, campaign execution, and ticket sales optimization across digital and traditional channels.
- Sponsorships:Brand partnership procurement, activation design, and cultural association metric reporting.
Event Management sits at the top of the volume ranking, with Marketing Services climbing the fastest.
Client Type:
Cost tier differentiation separates enterprise procurement departments from discretionary household spending patterns.
- Corporations:Multinational headquarters in Frankfurt, Amsterdam, and Zurich drive demand for experiential programming supporting brand activation and executive retreats. Procurement teams increasingly require carbon accounting for touring productions and diversity metrics for artist lineups.
- Schools:Educational institutions commission curriculum-integrated performances and student workshop series.
- Non-Profits:Museums, foundations, and cultural trusts fund mission-aligned programming with restricted grant capital.
- Individuals:Private collectors and family offices commission bespoke visual arts experiences and intimate music programming.
Corporations anchor the highest absolute spend, while Individuals demonstrate the steepest expansion trajectory in private commissioning.
Art Form:
Application context determines technical infrastructure requirements and sponsorship compatibility.
- Music:Spans classical orchestral touring through electronic music festivals and emerging artist showcases. UK and German promoters dominate volume through established festival circuits, though French immersive audio-visual productions gain share fastest.
- Visual Arts:Exhibition curation, installation commissioning, and private view programming for galleries and non-traditional venues. Milan and Madrid museum partnerships remain underpenetrated relative to London and Paris saturation.
- Theater:Dramatic and performance art productions requiring specialized venue relationships and longer development cycles.
- Dance:Contemporary and classical movement programming with distinct touring economics and technical rider profiles.
Music commands the deepest revenue pools, with Visual Arts gaining share fastest through immersive and digital-native formats.
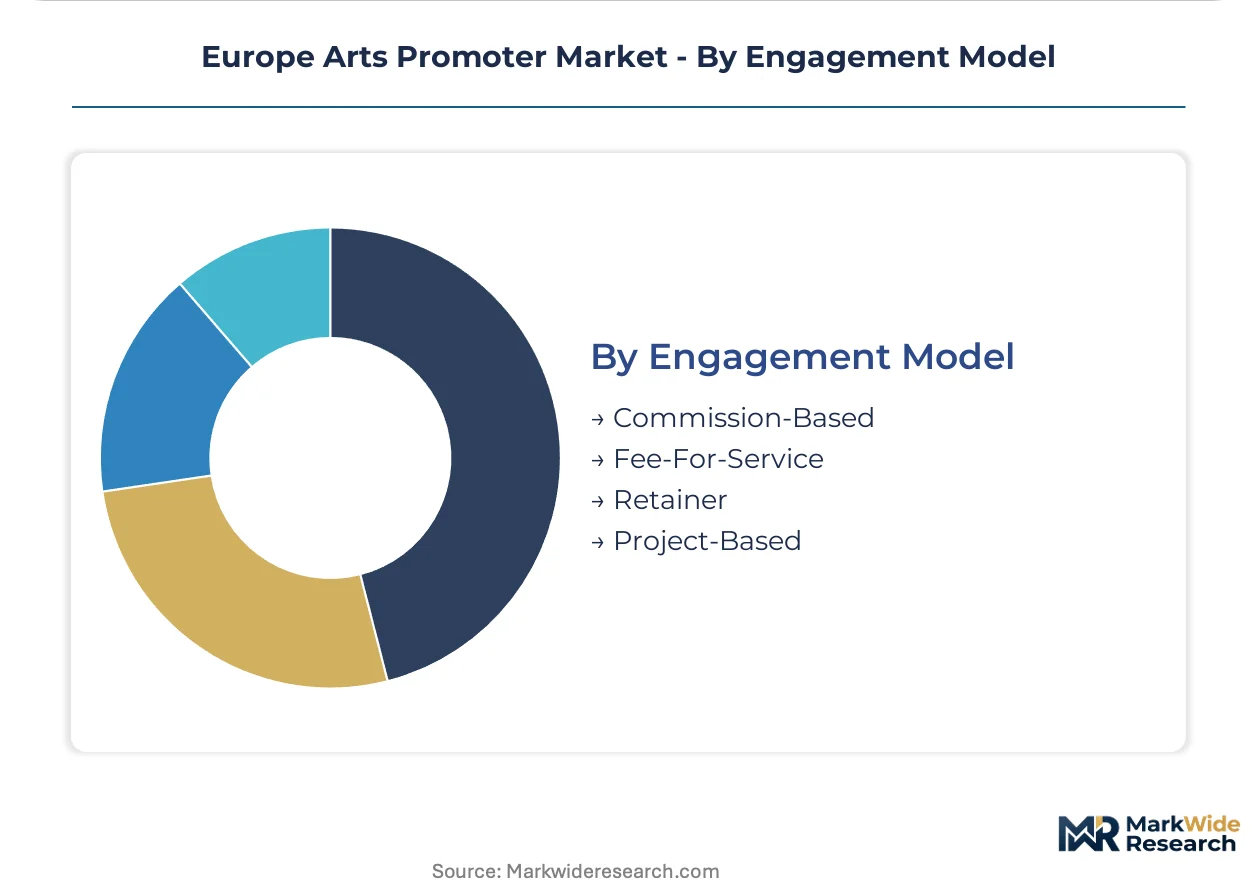
Engagement Model:
Margin structure varies with payment timing risk and relationship duration.
- Commission-Based:Percentage of ticket sales or transaction value aligns promoter incentives with event commercial performance. Concentrates in UK music and theater sectors where box office transparency supports trust-based partnerships.
- Fee-For-Service:Fixed pricing for defined deliverables transfers production risk to clients. Preferred by German corporate clients seeking budget certainty for recurring cultural programming.
- Retainer:Ongoing monthly or annual contracts for continuous advisory and programming services.
- Project-Based:Scoped engagements for single productions or limited series with defined milestones.
Commission-Based structures dominate transaction volume, with Retainer models expanding most quickly among institutional clients seeking strategic cultural partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan London anchors European arts promoter activity through corporate patronage density and hybrid production infrastructure. The United Kingdom, Germany, France, Italy, and the Netherlands concentrate the deepest promoter capabilities and sponsor spending pools.
United Kingdom
Corporate experiential programming and private collector commissioning drive promoter demand across Greater London and Manchester. Arts Council England recovery funding shapes eligibility for public co-financing of touring productions. The Southbank Centre cluster hosts the densest concentration of hybrid physical-virtual music and visual arts events.
Germany
Electronic music festivals and museum-integrated immersive exhibitions command promoter investment in Berlin and Hamburg. Federal cultural ministry funding through Kulturstiftung des Bundes expands cross-border touring circuit capabilities. The Rhine-Ruhr metropolitan region generates sustained demand for corporate cultural programming and brand activation events.
France
Immersive audio-visual productions and contemporary visual arts curation concentrate promoter resources in Paris and Lyon. Ministère de la Culture grants and regional digital arts infrastructure investments lower capital barriers for hybrid experimentation. The Île-de-France cluster leads European adoption of volumetric capture technology for live music distribution.
Italy
Milan museum partnerships and Venice Biennale-aligned programming create white-space opportunities for visual arts promoters. MiBACT (Ministero della Cultura) funding mechanisms support international exhibition touring circuits. The Lombardy region exhibits fastest-growing corporate commissioning of bespoke private view experiences.
Netherlands
Amsterdam's gallery district and Rotterdam's experimental venue network attract promoter specialization in digital-native visual arts. Mondriaan Fonds and national cultural ministry co-financing enables cross-disciplinary production experimentation. The Randstad conurbation concentrates sponsor demand for sustainability-metric-compliant cultural programming.
Europe Arts Promoter Market Competitive Landscape
Global majors compete with regional champions across auction house networks and exhibition infrastructure. The market structure tiers into integrated platform operators, specialized agency boutiques, and heritage auction houses. Three archetypes dominate: technology-forward hybrid producers, relationship-driven talent agencies, and capital-intensive exhibition anchoring operations. Consolidation concentrates through strategic venue partnerships and digital platform licensing arrangements.
Within the heritage auction tier, Sotheby's and Christie's occupy positions as integrated private sales and digital viewing room operators. Art Basel anchors the exhibition infrastructure archetype through multi-capital programming. MTArt Agency exemplifies the talent relationship model with artist development pipelines. These entities represent distinct competitive positioning strategies rather than direct substitutes.
| Leading Market Players |
|---|
| The Art Wolf |
| Europe's Art |
| Artshead |
| Marshall Art |
| Art Basel |
| Perrotin |
| Sotheby's |
| MTArt Agency |
| Christie's |
| Others |
Pricing and Supply Chain Analysis
Corporate procurement departments in Frankfurt, Amsterdam, and Zurich anchor pricing power for experiential programming, driving fee-for-service contracts that transfer production risk to promoters while demanding carbon accounting and diversity metrics as non-negotiable contract terms.
Pricing Analysis
Input-cost pass-through from escalating artist guarantee structures and GDPR-compliant data infrastructure compresses margins for mid-tier promoters without multi-year artist development pipelines. Three-tier pricing structure across premium immersive productions, standard touring circuits, and economy digital-access tiers differentiates service levels. Pricing pressure stems from talent booking inflation as recurring relationships command escalating guarantees. Corporate clients exhibit lowest price sensitivity due to procurement budget certainty, while individual private collectors demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for hybrid production infrastructure mandate promoters qualify multiple volumetric capture studios and real-time rendering facilities across the United Kingdom, Germany, and France. Raw material dependencies center on specialized audiovisual equipment, proprietary streaming platform licenses, and certified technical crew pools. Single-source vulnerability concentrates in premium venue availability within London, Paris, and Berlin metropolitan clusters. Distribution runs through synchronous streaming partnerships, asynchronous on-demand platforms, and physical venue networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Arts Promoter Market represents a late-cycle quality story as corporate patronage shifts toward immersive visual arts and experiential music programming with measurable cultural association metrics.
For Market Incumbents: Hedge against talent booking inflation by cultivating multi-year artist development pipelines and securing exclusive regional touring rights with German electronic music producers and French contemporary visual artists. Backward integration into hybrid production infrastructure lowers capital barriers as France and Germany expand public investment in virtual production facilities. For New Entrants and Emerging Players: The price-point gap between premium immersive productions and economy digital-access tiers opens white-space for mid-market positioning in Milan, Madrid, and Amsterdam museum partnerships. Underpenetrated visual arts programming in Lombardy and Veneto regions offers fastest addressable expansion. Go-to-market through sustainability-metric-compliant corporate cultural programming addresses procurement team requirements in the Randstad conurbation. For Investors and Strategic Acquirers: Heritage auction houses with integrated private sales channels are the most active acquirer in this space, consolidating exhibition infrastructure and digital viewing room capabilities. Long-term viability hinges on hybrid physical-virtual production scalability across European metropolitan clusters. Target acquisition archetype: specialized talent agencies with established artist relationships and scalable production templates. Signal to watch: EU AI Act enforcement patterns on algorithmic content recommendation as compliance investment concentration indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Production Infrastructure Investment | Volumetric capture deployment in Île-de-France expands addressable audience beyond venue capacity constraints. |
| Artist Development Pipeline Expansion | Multi-year agreements with German electronic music producers secure recurring revenue and margin protection. |
| Corporate Sponsorship Metric Standardization | Certified cultural association data addresses brand procurement requirements in London and Paris clusters. |
| GDPR-Compliant Personalization Engine | Algorithmic transparency investment creates first-mover positioning under EU AI Act French and German interpretations. |
| Museum Partnership Network Extension | Milan and Madrid gallery collaborations unlock underpenetrated immersive visual arts white-space. |
Research Methodology
Direct dialogue with arts promoter executives, corporate cultural procurement managers, museum partnership directors, and streaming platform licensing specialists grounded qualitative insights. Secondary validation drew from EU Creative Europe programme disclosures, national cultural ministry funding allocations, Arts Council England recovery documentation, and GDPR enforcement patterns. Bottom-up segmentation modeling triangulated with top-down macroeconomic scenario analysis.
Market size and growth trajectory outputs across the analysis window reflect econometric modeling of service type, client type, art form, and engagement model dimensions. CAGRs derived from historical spending pattern analysis projected through hybridization adoption curves and corporate patronage intensity indices. Forecast inputs incorporated EU AI Act implementation timelines and national digital arts infrastructure investment schedules.
Caveats apply where regulatory enforcement divergence across France, Germany, and the United Kingdom could materially shift compliance cost assumptions. Deviation in corporate experiential programming budgets or talent guarantee inflation trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Stage and Scenery Equipment Market
Media and Entertainment
Ebook Publishing Platform Market
Media and Entertainment
Qatar OOH and DOOH Market
Media and Entertainment
Video Streaming Market
Media and Entertainment
Advertising Services Market
Media and Entertainment
Gaming Simulation Market
Media and Entertainment
Global Advertising Agency Software Market
Media and Entertainment
Music App Market
Media and Entertainment
Internet Advertising Market
Media and Entertainment
Hong Kong OOH and DOOH Market
Media and Entertainment
Japan OOH and DOOH Market
Media and Entertainment
United Kingdom Webtoons Market
Media and Entertainment
Sports Broadcasting Technology Market
Media and Entertainment
Broadcasting and Cable TV Market
Media and Entertainment
Electronic Dance Music (EDM) Market
Media and Entertainment
Events Market