
 Global Free Music Making Software Market | 2026-2036
Global Free Music Making Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Free Music Making Software Market Foresight
The EU AI Act is hardening liability frameworks for generative music tools, forcing developers to restructure cost-of-entry models for European users. BandLab leverages its social-first platform architecture to sustain creator retention across Southeast Asian markets. Apple anchors premium-tier user acquisition through GarageBand's tight iOS integration, while Spotify competes by bundling Soundtrap within its broader audio ecosystem.
Free music making software comprises browser-based and native applications that enable audio recording, MIDI sequencing, virtual instrument hosting, and multi-track mixing without licensing fees, typically operating through freemium monetization or hardware-tied distribution. Digital Audio Workstation variants dominate functional depth, yet Loop-Based Software captures the fastest user onboarding due to lowered skill barriers. Education applications are deepening institutional penetration as K-12 programs in South Korea and Germany adopt browser-native tools, while Content Creation segments concentrate margin pools through creator-economy monetization pathways.
FCC guidelines on digital platform transparency intersect with GDPR data-processing requirements to shape how free tools collect and monetize user audio data. Japan's METI has initiated standards consultation for AI-generated music disclosure, directly impacting product roadmaps for generative entrants like Suno. Stakeholders must monitor whether emerging copyright frameworks for AI training data will trigger geographic fragmentation in feature availability.
Market Dynamics
Cloud-native architectures are compressing hardware barriers to entry while browser-based delivery models expand the addressable user base beyond traditional DAW purchasers. This structural shift is redistributing competitive advantage from incumbent software vendors toward platform-native and social-first entrants.
Growth Catalysts
- EU AI Act:The liability framework for generative music tools is forcing developers to restructure cost-of-entry models, accelerating freemium adoption across European markets as compliance costs push premium features behind paywalls.
- Loop-Based Software:Lowered skill barriers in browser-native sequencing tools are capturing first-time users who abandon complex Digital Audio Workstation interfaces, expanding the total creator pool.
- South Korea:K-12 music education infrastructure is institutionalizing browser-native production tools, creating pipeline demand that sustains engagement through university and independent creator stages.
Market Restraints
- GDPR-FCC intersection:Audio data collection and monetization face dual transparency requirements that increase compliance overhead for free-tier business models.
- AI training data copyright:Emerging frameworks for generative model training permissions threaten geographic fragmentation in feature availability, limiting rollout scope.
- Hardware-tied distribution:Premium native applications remain anchored to iOS and macOS ecosystems, constraining cross-platform functionality for browser-competitive entrants.
Strategic Opportunities
- Southeast Asia:Social-first platform architectures demonstrate sustained creator retention in underpenetrated markets where mobile-first production dominates.
- Content Creation monetization:Creator-economy pathways for bedroom producers and independent musicians concentrate margin pools beyond traditional software licensing.
- METI consultation:Japan's standards development for AI-generated music disclosure creates first-mover advantage for compliant product roadmaps ahead of mandatory requirements.
Industry Challenges
- Generative audio IP:Training data licensing complexity and output ownership disputes create legal uncertainty that delays feature deployment.
- Cross-platform integration:Legacy Digital Audio Workstation file formats and plugin architectures resist seamless migration to browser-native environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Free Music Making Software Market |
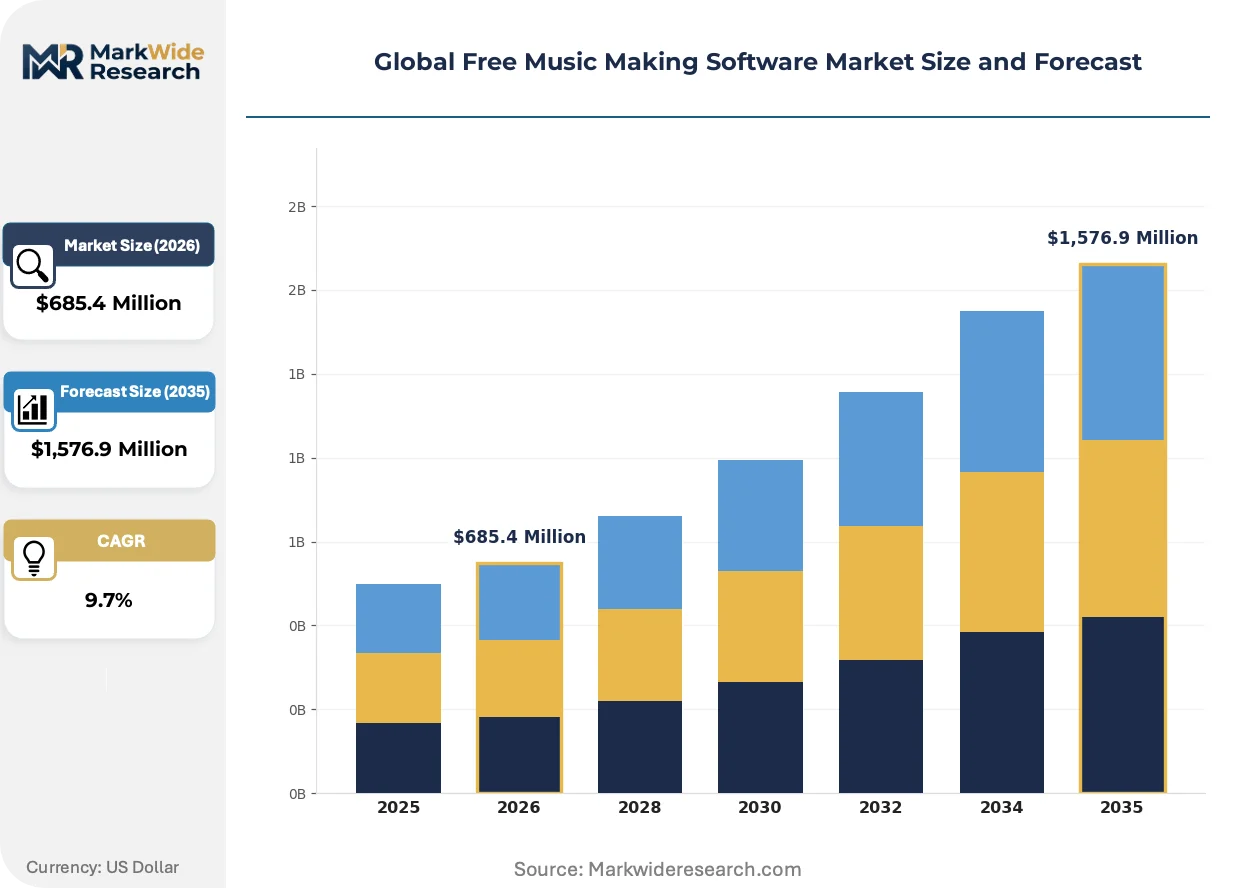
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Software Type: Digital Audio Workstation, Beat Maker, Loop-Based Software, Synthesizer Software, Sequencer Platform: Windows, macOS, Linux, iOS, Android Application: Content Creation, Music Production, Education, Live Performance, Sound Design User Category: Amateur Musicians, Music Producers, Educators, Hobbyists, Sound Engineers |
| Companies Covered | Tracktion (Waveform Free), LMMS, Spotify (Soundtrap), Soundation, Amped Studio, BandLab, Audiotool, Apple (GarageBand), Suno, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Free Music Making Software Market Shifts & Advancements
Generative AI is compressing production timelines while social distribution platforms reshape how creators monetize output. Three convergent forces are restructuring competitive positioning across the value chain.
Neural audio synthesis is integrating latent diffusion models for stem separation and melodic generation directly into browser-based workstations. Bedroom producers and independent musicians are adopting these tools at accelerating velocity as latency improvements enable real-time manipulation. The technology is integrating generative layers that collapse the traditional composition-recording-mixing sequence into simultaneous workflows.
The EU AI Act's risk classification system is imposing documentation and human oversight requirements on generative music features deployed in European markets. Developers must restructure model training disclosures and output labeling to maintain freemium distribution access. Education and Content Creation segments face divergent compliance timelines, with institutional procurement requiring earlier certification than consumer channels.
Creator-economy monetization is shifting procurement from perpetual licenses toward platform-embedded revenue shares. Distribution channels that bundle production tools with audience access are displacing standalone software purchases among emerging musicians. South Korea and Germany exhibit the strongest concentration of this behavior, where streaming platform integration drives tool selection.
Global Free Music Making Software Market Segmentation
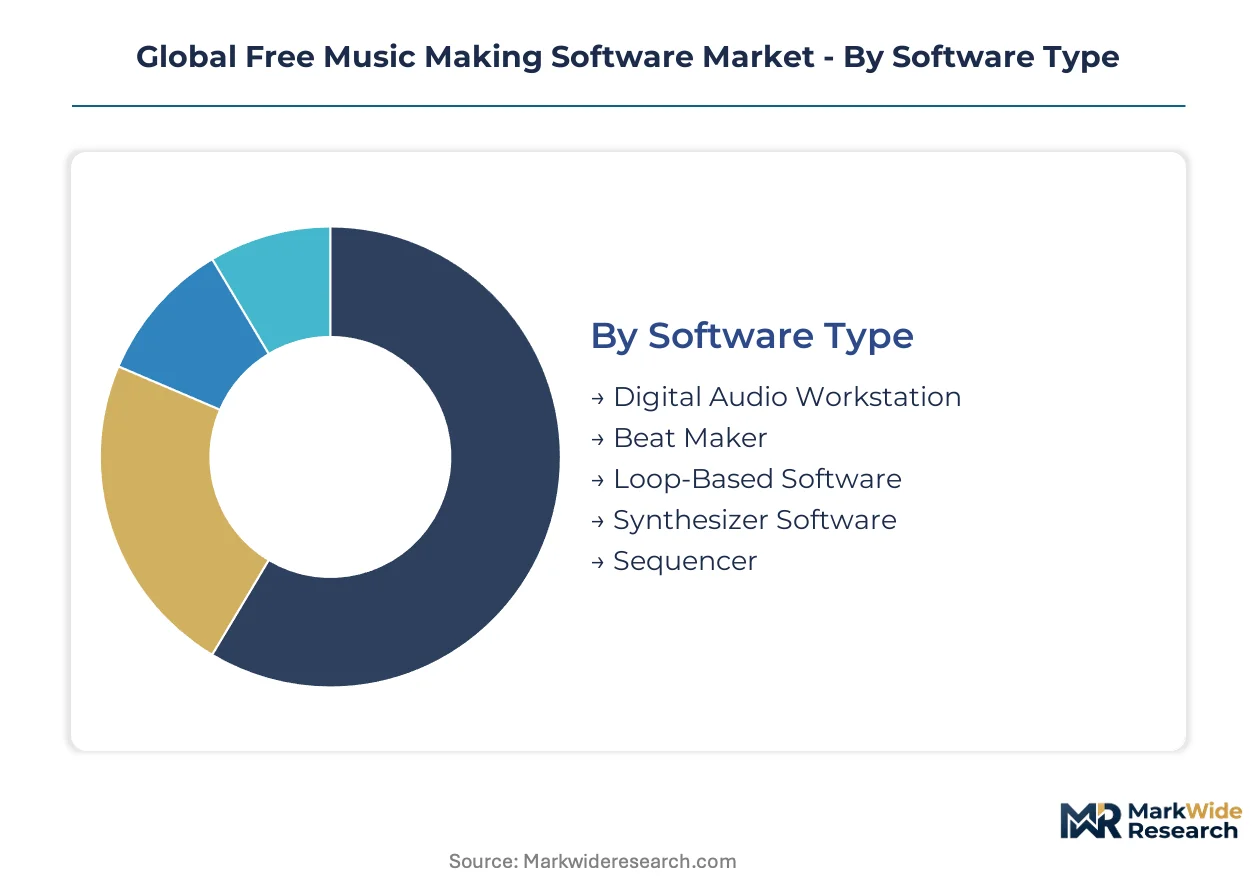
Segmentation in free music making software reveals how functional depth, platform accessibility, and user sophistication intersect to shape adoption patterns. Browser-native delivery has collapsed traditional boundaries between amateur and professional tooling, redistributing competitive advantage across integration architectures rather than feature checklists alone.
Software Type:
Standalone Digital Audio Workstations anchor professional-grade workflows with full plugin hosting and multi-track mixing, while embedded loop-based tools compress learning curves through pre-arranged harmonic and rhythmic frameworks.
- Digital Audio Workstation:Comprehensive multi-track environments supporting VST/AU plugin architectures, stem-level mixing, and third-party hardware integration. Demand concentrates among bedroom producers in Germany and the United States where Soundtrap and GarageBand bundle with distribution platforms. The EU AI Act's documentation requirements for generative features are forcing freemium restructuring in European deployments.
- Loop-Based Software:Browser-native sequencing interfaces with drag-and-drop harmonic matching and tempo-synced sample libraries. South Korean K-12 programs institutionalize these tools, creating pipeline demand that sustains through university and independent creator stages. BandLab's social-first architecture demonstrates sustained retention in Southeast Asian mobile-first markets.
- Beat Maker:Grid-based drum programming with sample slicing and pattern variation tools.
- Synthesizer Software:Virtual analog and wavetable engines with modulation matrices and preset ecosystems.
- Sequencer:MIDI-centric composition tools emphasizing piano-roll editing and automation curves.
Volume placements concentrate in Digital Audio Workstation deployments; the steepest expansion trajectory belongs to Loop-Based Software.
Platform:
Cost tier stratification separates hardware-tied native applications from zero-install browser delivery, with monetization models diverging sharply across ecosystem boundaries.
- iOS:Tight hardware-software integration through Apple's audio stack delivers sub-10ms latency for real-time monitoring. GarageBand anchors premium-tier acquisition in North American and Japanese markets where iPhone penetration supports creator-economy monetization pathways.
- Android:Fragmented audio driver implementations historically constrained professional use, yet Samsung's partnership with Steinberg and Google's Oboe library improvements are compressing latency gaps in South Korean and Indian deployments.
- Windows:Legacy ASIO driver support maintains entrenched position among institutional music technology programs.
- macOS:Core Audio integration preserves dominance in professional studio environments with established plugin investments.
- Linux:Open-source DAWs serve privacy-conscious users and educational institutions with constrained licensing budgets.
Revenue concentration remains with iOS and macOS through hardware-tied distribution; Android gains share fastest where mobile-first production dominates emerging markets.
Application:
Maturity gradients separate established content creation workflows from emerging education and live performance deployments where institutional procurement cycles reshape vendor economics.
- Content Creation:Platform-embedded production tools bundled with streaming distribution and audience analytics. Spotify's Soundtrap integration and YouTube's creator studio partnerships concentrate margin pools in Germany and South Korea where creator-economy monetization drives tool selection over standalone feature comparisons.
- Education:Browser-native tools with classroom management dashboards and curriculum-aligned lesson libraries. South Korea's national music education standards and Germany's federal K-12 technology grants institutionalize procurement at scale, creating multi-year engagement pipelines.
- Music Production:Traditional composition-to-mastering workflows for commercial release.
- Live Performance:Low-latency playback and scene-triggering for stage deployment.
- Sound Design:Foley libraries, synthesis experimentation, and spatial audio tools for media post-production.
Procurement volume clusters in Content Creation through platform bundling; Education climbs fastest as institutional certification requirements accelerate browser-native adoption.
User Category:
Customer type stratification maps directly to monetization depth, with hobbyist-to-professional transitions representing the critical retention threshold for freemium business models.
- Amateur Musicians:First-time creators prioritizing immediate output over technical control, typically aging 13-24 and accessing tools through social platform referrals. Southeast Asian markets exhibit highest conversion velocity from loop-based experimentation to distribution-integrated workflows.
- Music Producers:Semi-professional and professional creators monetizing through streaming, sync licensing, or commissioned work. GDPR-FCC transparency requirements for audio data collection increase compliance overhead for free-tier retention strategies targeting this segment.
- Hobbyists:Non-monetizing creators with sporadic engagement and high churn sensitivity.
- Educators:Institutional purchasers requiring administrative controls and curriculum alignment.
- Sound Engineers:Technical specialists demanding precise monitoring and export standards.
User volume concentrates among Hobbyists; Music Producers deliver the highest lifetime value expansion as freemium conversion rates improve with embedded distribution access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Digital Media City tax incentives concentrate creator-economy infrastructure, drawing platform developers and music technology startups into clustered innovation zones across South Korea.
United States
Los Angeles and Nashville anchor content-creation demand through streaming platform headquarters and sync licensing networks. FCC guidelines on digital platform transparency intersect with state-level privacy statutes to reshape how free tools collect user audio data. Austin's emerging music technology cluster attracts browser-native developers seeking proximity to creator-economy monetization pathways.
Germany
Berlin's electronic music heritage sustains institutional demand for professional-grade production tools in educational and commercial contexts. Federal K-12 technology grants under the DigitalPakt Schule program institutionalize browser-native software procurement at scale. Hamburg's media port district concentrates post-production studios adopting hybrid cloud-native workflows.
South Korea
Seoul Capital Area dominates through K-12 national music education standards mandating browser-based production tool integration. METI consultation frameworks for AI-generated music disclosure influence adjacent regulatory thinking across Northeast Asian markets. Busan's digital content valley incubates mobile-first production startups targeting Southeast Asian export markets.
Japan
Tokyo's dense network of independent musicians and bedroom producers generates sustained freemium conversion demand. METI's standards consultation for AI-generated music disclosure creates compliance lead-time advantages for developers with established product roadmaps. Osaka's music technology district hosts legacy hardware manufacturers transitioning toward software-subscription hybrid models.
United Kingdom
London's creator-economy density drives platform-embedded tool adoption through streaming and distribution bundling. GDPR data-processing requirements impose dual transparency obligations on audio data monetization strategies. Manchester's music education cluster experiments with institutional licensing models for cloud-native production suites.
Global Free Music Making Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Platform-native technology giants leverage ecosystem integration to anchor premium-tier user acquisition, while browser-first entrants capture volume through lowered hardware barriers. Three strategic archetypes dominate: hardware-tied distribution players, social-first platform operators, and generative-AI-native entrants. Competitive moves concentrate on bundling production tools with distribution access and restructuring freemium tiers to absorb compliance cost inflation.
Within the hardware-tied tier, Apple exemplifies ecosystem-anchored positioning through tight iOS integration. Spotify occupies a platform-bundling archetype, embedding production capabilities within broader audio service architectures. BandLab represents the social-first specialist model, leveraging community architecture to sustain creator retention in mobile-first markets. These three anchors illustrate how integration depth, rather than feature breadth alone, determines competitive positioning.
| Leading Market Players |
|---|
| Tracktion (Waveform Free) |
| LMMS |
| Spotify (Soundtrap) |
| Soundation |
| Amped Studio |
| BandLab |
| Audiotool |
| Apple (GarageBand) |
| Suno |
| Others |
Supply & Pricing Matrix
Cloud compute pricing indices from AWS, Azure, and Google Cloud Platform cascade through freemium software tiers, compressing margins for browser-native entrants while hardware-tied distribution preserves premium positioning for ecosystem-anchored players.
Pricing Analysis
Short lead-time provisioning commands premium rates in cloud-hosted audio processing, while spot capacity utilization enables zero-cost entry tiers. Freemium SaaS-tiered structures dominate, with price differentiation hinging on generative AI feature access and export quality tiers. Pricing pressure stems from EU AI Act compliance costs forcing feature paywalling. Bedroom producers exhibit highest price sensitivity; institutional education buyers demonstrate lowest sensitivity due to grant-funded procurement.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan Semiconductor Manufacturing Company for AI inference chip supply to generative audio startups. Cloud infrastructure concentrates in the United States, Ireland, and Singapore; open-source audio libraries and pretrained model weights constitute critical inputs. Tariff exposure on Chinese-manufactured consumer audio interfaces threatens hardware bundle economics. Distribution runs through platform app stores and direct browser delivery, with mobile storefronts extracting substantial revenue shares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act constructs a cost-of-compliance moat that favors incumbents with established documentation infrastructure and human oversight protocols, raising effective barriers for undercapitalized generative entrants.
For Market Incumbents: Anchor defensive positioning through backward integration into cloud infrastructure and preemptive certification investment for EU AI Act high-risk system classification. Social-first platform architectures and browser-native delivery models represent the primary substitution threat from BandLab and similar entrants; vertical integration into distribution channels preserves creator retention economics. For New Entrants and Emerging Players: Capture white-space opportunity in Southeast Asian mobile-first markets where social platform embedding outperforms standalone feature competition. South Korean K-12 education procurement and German federal technology grants represent the most penetrable institutional segments; browser-native classroom management dashboards offer the decisive go-to-market angle against legacy Windows-tied competitors. For Investors and Strategic Acquirers: The window for entry favors compliant generative-AI-native specialists with established METI-aligned disclosure roadmaps. Long-term viability centers on platform-embedded revenue share models displacing perpetual licensing. Monitor Japan METI consultation outcomes as the critical inflection signal for geographic feature availability fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Spotify's Soundtrap bundling concentrates creator-economy margin pools in Germany and South Korea. |
| Geographic Expansion | Seoul Digital Media City tax incentives draw browser-native developers into clustered innovation zones. |
| Product Launch | GarageBand's iOS integration anchors premium-tier acquisition in North American and Japanese markets. |
| Strategic Partnership | Samsung's Steinberg partnership compresses Android latency gaps in South Korean deployments. |
| Acquisition of Specialist Firm | Social-first architectures from Southeast Asian targets sustain retention in mobile-first creator markets. |
Research Methodology
Independent corroboration across product roadmap disclosures, regulatory filing annotations, and cloud infrastructure spend reports underwrites the qualitative findings. Primary interviews engaged platform engineering leads, music education procurement officers, creator-economy monetization strategists, and intellectual property counsel at generative audio startups. Secondary validation drew from SEC filings, EU AI Act implementation guidance, METI standards consultation documents, and hyperscaler capex disclosures. Bottom-up user adoption modeling triangulated against top-down addressable market sizing.
Comparable-period anchoring calibrated the projection horizon against historical freemium conversion trajectories and institutional procurement cycle patterns. The analytical framework segmented across deployment model, user sophistication tier, application vertical, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating network effects and compliance cost pass-through assumptions. Forecast inputs included K-12 technology grant allocation trends and creator-economy platform revenue share evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI training data copyright framework emergence and generative audio output ownership litigation. Deviation in EU AI Act enforcement intensity or METI mandatory disclosure timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Music App Market
Music
Electronic Dance Music (EDM) Market
Music
Virtual Musical Instruments Market
Music
Asia-Pacific Independent Artist Market
Music
Music Publishing Market
Music
Traditional Music Market
Music
Global in-Store Music Service Market
Music
Vinyl Records Market
Music
Music Distribution Services Market
Music
Traditional Chinese Instruments Market
Music
Independent Music Publishing Market
Music
Music Synthesizers Market
Music
Global Background Music Market
Music
Europe Independent Artist Market
Music
Music Production Software Market
Music
Discography Market