
 Asia-Pacific Independent Artist Market | 2026-2036
Asia-Pacific Independent Artist Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Independent Artist Market Analysis
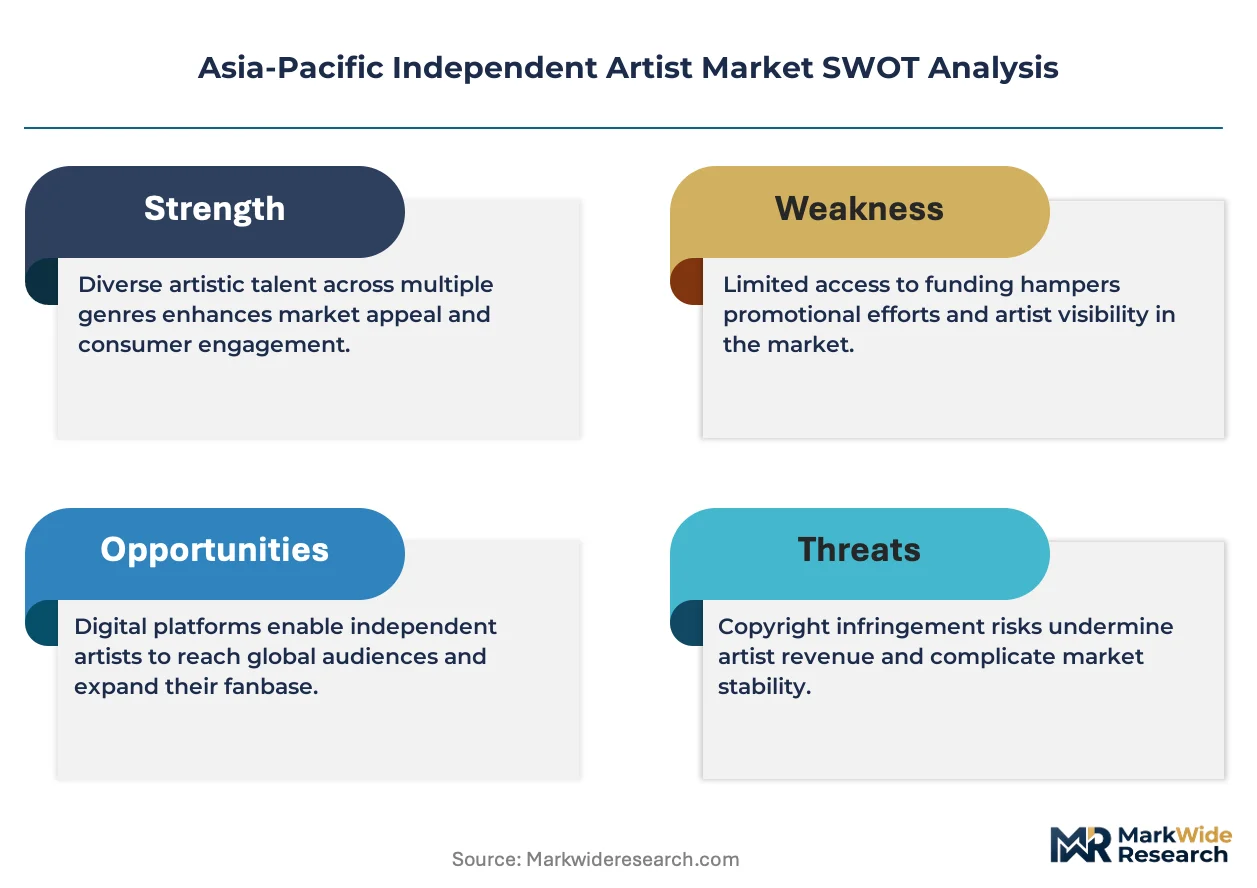
ISO 19650 certification for digital asset management is unwinding competitive barriers for independent artists seeking institutional credibility. Artsy leverages its auction aggregation technology to sustain North American-Asian cross-border sales volume. Singulart anchors European collector access into Southeast Asian creator networks. Sotheby's competes through private-treatment consignment structures that bypass traditional gallery representation.
The Asia-Pacific Independent Artist sector encompasses self-representing creators operating outside major gallery systems, producing original works across physical and digital media for direct or platform-mediated commercial exchange. Digital Art segments now incorporate blockchain-verified provenance and smart-contract royalty automation as standard functional parameters. Paintings retains the largest revenue pool across artwork medium categories, though Photography segments show accelerating margin compression from AI generation tools. Online Platforms dominate distribution channel value capture, while Art Fairs concentrate high-margin transactions through curated scarcity and experiential buyer engagement.
India's BIS digital content standards, Australia's resale royalty regulations administered by Copyright Agency, and Japan's METI creative industry export frameworks collectively shape market access conditions for independent practitioners. TRAI's digital platform governance in India further constrains cross-border payment architectures that artists depend upon for international sales. Stakeholders must monitor evolving copyright treatment of AI-assisted works across multiple national regimes.
Market Dynamics
Platform-mediated distribution is compressing traditional gallery gatekeeping power across Asia-Pacific independent art markets. Streaming algorithms and blockchain provenance systems now determine visibility and valuation for self-representing creators.
Growth Catalysts
- India's PLI Scheme for Creative Industries:Production-linked incentives are redirecting domestic manufacturing capacity toward art supply chains and digital content infrastructure.
- Blockchain Provenance Verification:Smart-contract royalty automation is embedding resale revenue streams directly into digital and physical artwork transactions.
- Corporate Collection Expansion:Technology sector headquarters in Singapore and Sydney are establishing dedicated acquisition budgets for emerging independent practitioners.
Market Restraints
- TRAI Cross-Border Payment Constraints:India's digital platform governance is fragmenting international sales architectures that artists depend upon for overseas transactions.
- AI Generation Margin Compression:Photography segments face structural price erosion as generative tools flood markets with synthetic imagery.
- Gallery Network Concentration:Australia's physical exhibition infrastructure remains geographically concentrated in Melbourne and Sydney metropolitan corridors.
Strategic Opportunities
- ISO 19650 Certification Pathways:Digital asset management standardization is opening institutional credibility channels previously reserved for represented artists.
- Japan's METI Creative Export Frameworks:Government-backed internationalization programs are subsidizing independent creator participation in European and North American fairs.
- Virtual Exhibition Infrastructure:Spatial computing platforms are enabling direct collector engagement without physical gallery intermediation.
Industry Challenges
- Copyright Agency Resale Royalty Administration:Australia's fragmented collection mechanisms create cash-flow delays for artists navigating multiple jurisdictions.
- AI-Assisted Work Classification:Evolving national copyright regimes lack consistent treatment of machine-collaborative creation, exposing practitioners to litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Independent Artist Market |
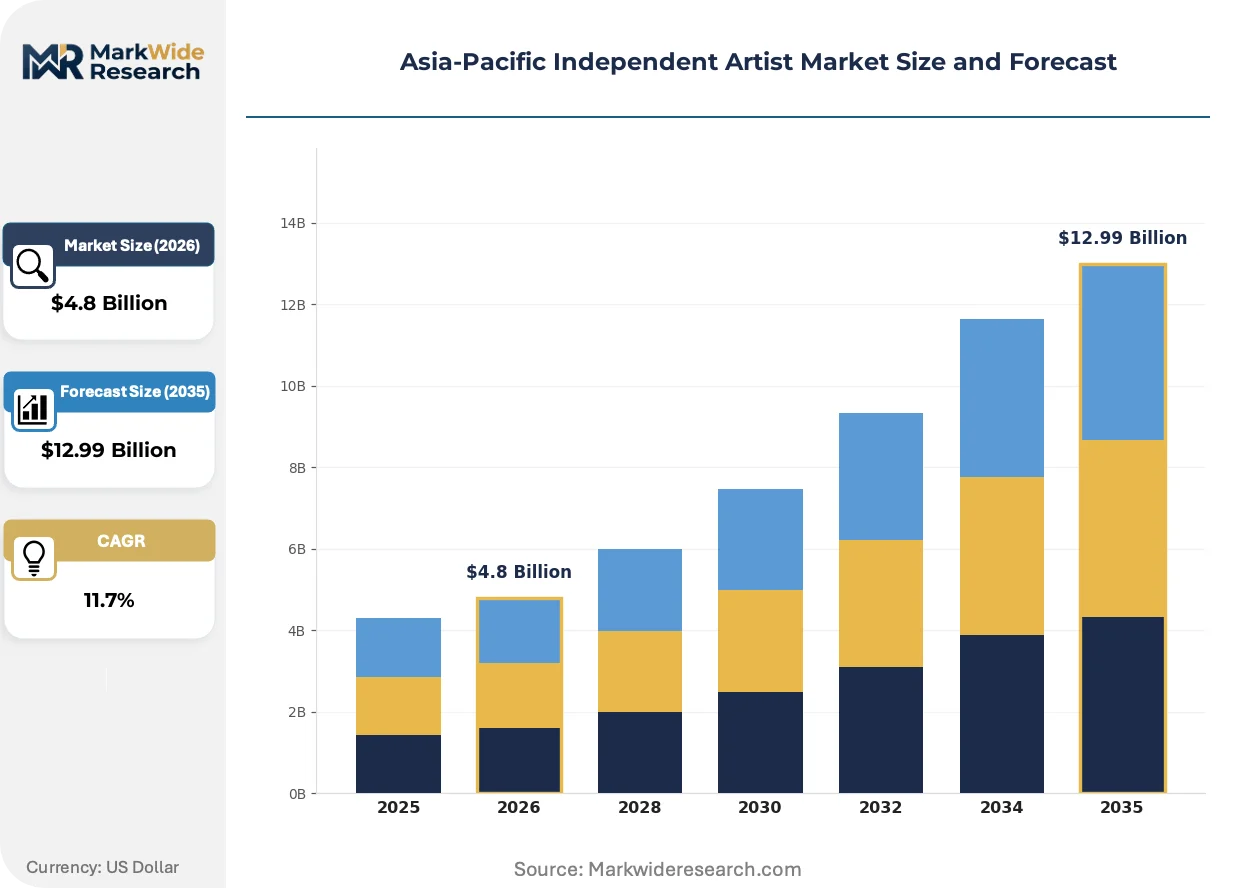
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Online Platforms, Art Fairs, Galleries, Festivals Artwork Medium: Paintings, Sculptures, Photography, Digital Art Customer Segment: Collectibles, Interior Designers, Corporates, Art Enthusiasts Sales Channel: Direct Sales, Auctions, eCommerce, Consignment |
| Companies Covered | Art Stage Singapore, Hong Kong Art Basel, Tokyo Art Fair, Jakarta Contemporary Art and Design Fair, Singapore Art Museum, Artsy, Singulart, Etsy, Sotheby's, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Independent Artist Market Emerging Trajectories
Digital verification technologies are redefining authenticity standards while regulatory frameworks struggle to keep pace with machine-generated creative output. Collector behavior is fragmenting across platform-native and traditional acquisition channels.
Blockchain-based provenance systems with embedded smart contracts are displacing paper-based certificate-of-authenticity models that dominated physical art transactions. Institutional buyers in Australia's gallery networks and Japan's digital collector communities are adopting these verification layers at accelerating velocity. The displacement is compressing due-diligence timelines while expanding secondary-market royalty capture for creators.
Australia's resale royalty regulations administered by Copyright Agency are mandating percentage payments on secondary transactions exceeding specific thresholds. The framework is forcing platform operators to build automated tracking and distribution infrastructure. Digital art segments with blockchain-native provenance are adapting most rapidly, while physical painting markets face implementation friction.
Direct-to-collector platform engagement is fragmenting traditional gallery representation structures across Southeast Asian creator networks. Emerging artists in Indonesia and the Philippines are bypassing physical exhibition circuits entirely, building collector bases through algorithmic discovery and social proof metrics. Japan's metropolitan collector communities exhibit the highest platform-native purchasing velocity, while Australian buyers maintain hybrid acquisition patterns across digital and physical channels.
Asia-Pacific Independent Artist Market Segmentation
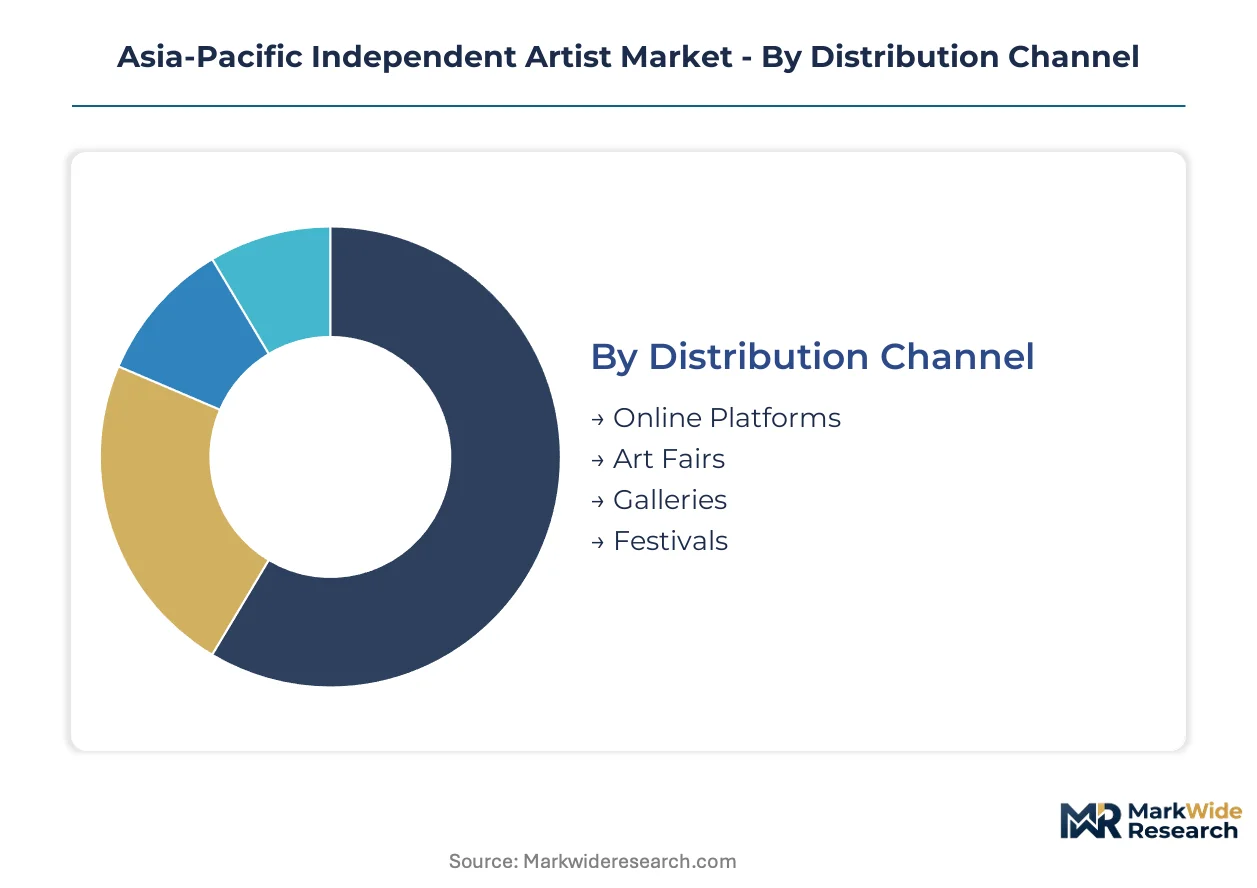
Segmentation in the Asia-Pacific Independent Artist Market reveals how platform infrastructure and buyer behavior fragment revenue capture across creator networks. Each dimension exposes different margin vulnerabilities and growth vectors for self-representing practitioners.
Distribution Channel:
Margin pools concentrate where curation algorithms and physical scarcity create pricing power for independent creators.
- Online Platforms:Algorithmic discovery systems aggregate demand across dispersed collector bases, compressing traditional gallery gatekeeping. Singapore-based technology sector headquarters and Sydney corporate buyers drive acquisition volume through platform-native interfaces. TRAI's cross-border payment constraints fragment international transaction architectures that artists depend upon for overseas sales.
- Art Fairs:Curated scarcity and experiential buyer engagement concentrate high-margin transactions through temporary physical presence. Japan's METI creative export frameworks subsidize independent creator participation in European and North American fair circuits, accelerating internationalization velocity for platform-agnostic practitioners.
- Galleries:Australia's physical exhibition infrastructure remains geographically concentrated in Melbourne and Sydney metropolitan corridors, limiting rural creator access to institutional credibility channels.
- Festivals:Seasonal demand spikes in Indonesia and the Philippines create cash-flow volatility for creators without diversified channel presence.
The dominant share belongs to Online Platforms, while Art Fairs is closing the gap fastest.
Artwork Medium:
Technology adoption curves determine where authentication infrastructure unlocks premium pricing for independent practitioners.
- Paintings:Traditional pigment-on-surface works retain the largest revenue pool across medium categories, though Australia's Copyright Agency resale royalty administration creates implementation friction for secondary-market tracking. Melbourne and Sydney gallery networks anchor physical painting demand.
- Digital Art:Blockchain-verified provenance and smart-contract royalty automation function as standard parameters, enabling direct secondary-market revenue capture. Japan's digital collector communities exhibit the highest platform-native purchasing velocity for blockchain-native works.
- Photography:AI generation tools flood markets with synthetic imagery, compressing margins for traditional photographic practitioners across Southeast Asian creator networks.
- Sculptures:Physical logistics constraints limit cross-border transaction frequency for three-dimensional works, concentrating demand in Australia's metropolitan gallery corridors.
Paintings commands the established revenue base, with Digital Art expanding most quickly through authentication infrastructure.
Customer Segment:
Procurement sophistication varies sharply between institutional buyers and individual collectors across the region.
- Corporates:Technology sector headquarters in Singapore and Sydney establish dedicated acquisition budgets for emerging independent practitioners, driving volume through direct commissioning relationships.
- Interior Designers:Australia's gallery networks and Japan's digital collector communities serve as primary sourcing channels for specification-driven procurement.
- Collectibles:Speculative buyers concentrate in blockchain-verified digital art segments, leveraging smart-contract royalty automation for portfolio diversification.
- Art Enthusiasts:Algorithmic discovery on online platforms fragments traditional collector education pathways for emerging practitioners in Indonesia and the Philippines.
Corporates anchor institutional demand volume, while Interior Designers is gaining share fastest through specification influence.
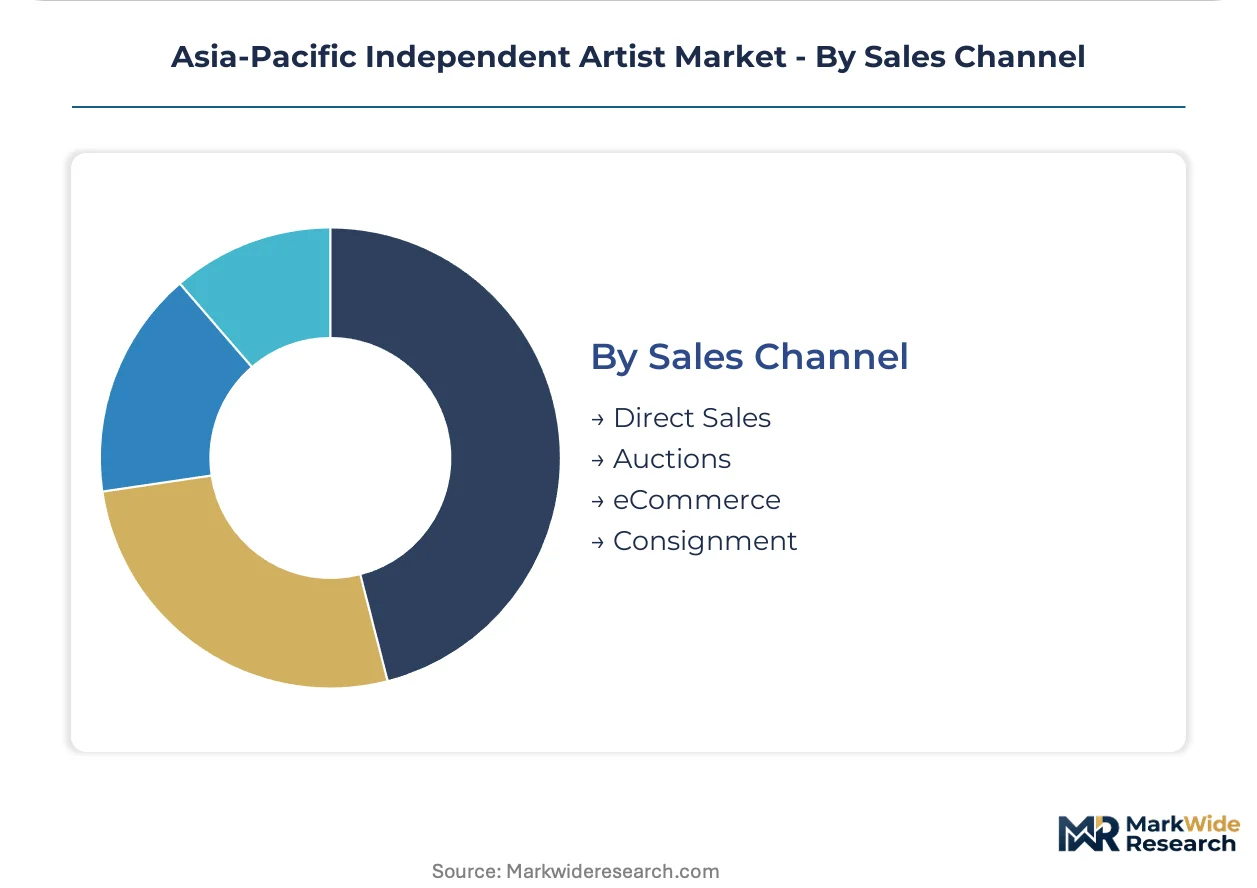
Sales Channel:
Intermediation structures determine how pricing power distributes between creators and platform operators.
- Direct Sales:Spatial computing platforms enable direct collector engagement without physical gallery intermediation, compressing commission structures for self-representing artists.
- eCommerce:India's BIS digital content standards and TRAI platform governance constrain cross-border payment architectures that artists depend upon for international sales.
- Auctions:Artsy's auction aggregation technology sustains North American-Asian cross-border sales volume for established independent practitioners.
- Consignment:Sotheby's private-treatment consignment structures bypass traditional gallery representation, opening institutional credibility channels for unrepresented creators.
eCommerce holds the broadest reach, with Direct Sales climbing the fastest through virtual exhibition infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for creative industries redirects domestic manufacturing capacity toward art supply chains and digital content infrastructure. Australia's resale royalty framework administered by Copyright Agency mandates percentage payments on secondary transactions. Japan's METI creative industry export frameworks subsidize independent creator participation in international fair circuits.
Australia
Corporate buyers at Sydney and Melbourne technology sector headquarters establish dedicated acquisition budgets for emerging independent practitioners. Copyright Agency administers resale royalty regulations that force platform operators to build automated tracking infrastructure. Physical gallery networks concentrate in Melbourne and Sydney metropolitan corridors, limiting rural creator access to institutional credibility channels.
Japan
Digital art collector communities exhibit the highest platform-native purchasing velocity for blockchain-native works. METI creative industry export frameworks subsidize independent creator participation in European and North American fairs. Tokyo Art Fair anchors physical exhibition demand while spatial computing platforms enable direct collector engagement without gallery intermediation.
India
Production-linked incentives redirect domestic manufacturing capacity toward art supply chains and digital content infrastructure. TRAI's digital platform governance fragments international sales architectures that artists depend upon for overseas transactions. BIS digital content standards constrain cross-border payment architectures for platform-mediated distribution.
Singapore
Technology sector headquarters drive acquisition volume through platform-native interfaces for corporate art collections. Art Stage Singapore concentrates high-margin transactions through curated scarcity and experiential buyer engagement. The city-state anchors Southeast Asian creator network access into European and North American collector bases.
Indonesia
Jakarta Contemporary Art and Design Fair creates seasonal demand spikes that generate cash-flow volatility for creators without diversified channel presence. Emerging artists bypass physical exhibition circuits entirely, building collector bases through algorithmic discovery and social proof metrics. Platform-native engagement fragments traditional gallery representation structures across Southeast Asian creator networks.
Asia-Pacific Independent Artist Market Vendor Landscape
Player mix skews toward platform-mediated aggregators and legacy auction houses adapting to direct-to-collector engagement. Market structure fragments across online discovery engines, physical fair operators, and hybrid consignment services. Three archetypes dominate: algorithmic marketplace operators, experiential fair organizers, and private-treatment consignment specialists. Competitive moves concentrate on auction aggregation technology deployment and virtual exhibition infrastructure expansion.
Within the platform-mediated tier, Artsy and Singulart represent algorithmic discovery engines sustaining cross-border sales volume. Artsy anchors North American-Asian transaction corridors through auction aggregation technology. Singulart occupies a position facilitating European collector access into Southeast Asian creator networks. Sotheby's exemplifies the legacy auction house archetype adapting through private-treatment consignment structures that bypass traditional gallery representation. These three entities sit within a competitive set where authentication infrastructure and direct collector engagement capabilities determine positioning.
| Leading Market Players |
|---|
| Art Stage Singapore |
| Hong Kong Art Basel |
| Tokyo Art Fair |
| Jakarta Contemporary Art and Design Fair |
| Singapore Art Museum |
| Artsy |
| Singulart |
| Etsy |
| Sotheby's |
| Others |
Supply Flow & Price Mechanics
ISO 19650 certification for digital asset management gates both supply qualification and price differentiation simultaneously, separating platform operators capable of institutional-grade provenance infrastructure from commodity marketplace entrants while compressing margins for uncertified intermediaries.
Pricing Analysis
Certification level (ISO 19650-grade) creates the primary spread between premium platform operators and basic marketplace entrants. Three-tier pricing structure across premium, standard, and economy levels reflects authentication infrastructure depth, with blockchain-native provenance commanding premium placement. Cost compression in photography segments is intensifying because AI generation tools flood markets with synthetic imagery. Corporate buyers at Singapore technology sector headquarters exhibit lowest price sensitivity, while emerging collectors in Indonesia and the Philippines drive volume at economy tiers.
Supply Chain Analysis
Just-in-time inventory preferences dominate digital art segments where blockchain-verified provenance enables immediate transfer, while physical painting markets favor strategic stockpiling through Australia's Melbourne and Sydney gallery corridors. Raw material dependencies center on pigment supply chains, canvas manufacturing, and digital storage infrastructure. Geographic supply concentration rests on India for art supply manufacturing, Japan for digital exhibition technology, and Australia for physical gallery infrastructure. Single-source vulnerability sits with concentrated blockchain infrastructure providers. Distribution runs through platform-native interfaces for digital segments and curated fair circuits for physical works.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward platform-native corporate collectors as technology sector headquarters consolidate acquisition budgets, fragmenting traditional gallery gatekeeping across Asia-Pacific independent art markets.
For Market Incumbents: Secure blockchain provenance infrastructure as a defensive moat against algorithmic marketplace entrants. Invest in ISO 19650 certification to maintain institutional credibility channels threatened by direct-to-collector spatial computing platforms. Lock in exclusive consignment relationships with Australia's Copyright Agency resale royalty framework to preempt margin compression from automated tracking competitors. For New Entrants and Emerging Players: Differentiate on AI-assisted work classification expertise as copyright regimes fragment across jurisdictions. Target Indonesia and Philippines creator networks where algorithmic discovery has lowest penetration among Southeast Asian markets. Pursue METI-subsidized fair participation as a go-to-market angle for Japanese digital collector community access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed platform operators holding Artsy-type auction aggregation technology. Five-to-ten-year viability hinges on authentication infrastructure ownership rather than transaction volume capture. Watch for Copyright Agency resale royalty enforcement intensity as an inflection indicator for platform operator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Infrastructure Deployment | Smart-contract royalty automation embeds resale revenue directly into secondary transactions. |
| ISO 19650 Certification Investment | Digital asset management standardization opens institutional credibility channels for unrepresented artists. |
| METI Creative Export Program Participation | Government-backed subsidies accelerate international fair circuit access for independent creators. |
| Virtual Exhibition Platform Integration | Spatial computing enables direct collector engagement bypassing traditional gallery intermediation. |
| Copyright Agency Royalty Tracking Partnership | Automated resale payment infrastructure addresses Australia's fragmented collection mechanisms. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of platform transaction data, regulatory filings, and fair circuit participation records. Interviews with independent artists, gallery operators, corporate art procurement officers, and blockchain platform engineers informed demand-side and supply-side dynamics. Secondary sources include Copyright Agency resale royalty reports, METI creative industry export documentation, and TRAI digital platform governance circulars. Bottom-up artist revenue estimates triangulate against top-down platform transaction aggregation.
Segmentation dimensions modeled include distribution channel, artwork medium, customer segment, and sales channel across the analysis window. CAGRs derive from trend extrapolation of platform-mediated transaction growth and corporate collection expansion rates. Industry-specific forecast inputs incorporate PLI scheme uptake velocity in India and METI subsidy allocation trajectories in Japan.
Material uncertainties — regulatory treatment of AI-assisted works, TRAI cross-border payment rule evolution, and Copyright Agency enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about certification adoption curves and platform infrastructure investment continuity. Revision becomes warranted when AI generation tool penetration in photography segments crosses thresholds that trigger gallery network restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Vinyl Records Market
Music
Global Free Music Making Software Market
Music
Europe Independent Artist Market
Music
Virtual Musical Instruments Market
Music
Global in-Store Music Service Market
Music
Music App Market
Music
Traditional Chinese Instruments Market
Music
Music Synthesizers Market
Music
United States Live Music Market
Music
Electronic Dance Music (EDM) Market
Music
Traditional Music Market
Music
Music Publishing Market
Music
Discography Market
Music
Global Background Music Market
Music
Music Distribution Services Market
Music
Music Production Software Market