
 Music Distribution Services Market | 2026-2036
Music Distribution Services Market Size, Share, and Industry Trends Forecast 2026-2036
Music Distribution Services Market Outlook
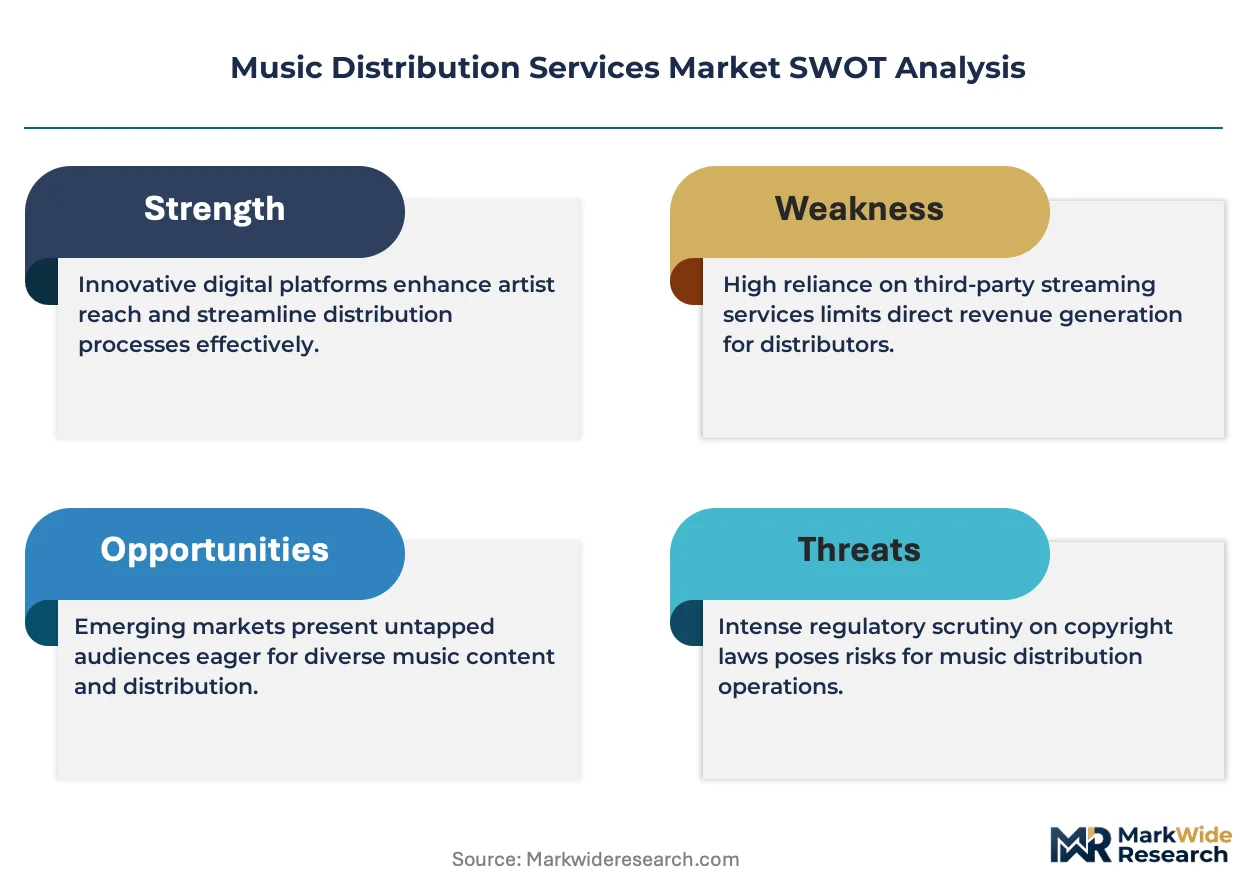
A capital-intensity divergence between self-service upload platforms and full-service label alternatives is unwinding competitive boundaries across the sector. DistroKid leverages flat-fee annual pricing to anchor volume-based independent artist acquisition. AWAL sustains selective roster curation and upstream royalty advances to differentiate its position among emerging acts seeking label services without traditional contracts. CD Baby competes through hybrid physical-distribution retained inventory alongside digital aggregation, occupying a niche for artists with merchandise and vinyl fulfillment needs.
Music distribution services encompass digital supply-chain intermediaries that encode, deliver, and monetize audio recordings across streaming platforms, download stores, and broadcast channels through standardized metadata protocols such as ISRC and UPC embedding. These services functionally replace physical manufacturing and wholesale logistics with API-driven pipeline ingestion, real-time royalty accounting, and rights-management dashboards. The aggregation segment within service type leads transaction volume by processing high-frequency uploads from non-label creators, while the licensing sub-category captures disproportionate margin pools through sync and performance-rights administration for film, gaming, and commercial placements. Hybrid distribution models are accelerating as artists combine direct-to-consumer Bandcamp and Patreon storefronts with platform-wide streaming aggregation to retain audience data and higher per-unit revenue.
Regulatory frameworks including the US Music Modernization Act, EU copyright directives under the Digital Services Act, and mechanical royalty rate-setting by the US Copyright Royalty Board collectively reshape how platforms calculate and remit songwriter payments. GDPR and emerging state-level US privacy laws further constrain how distribution services collect and monetize listener behavioral data for artist analytics. Stakeholders must monitor evolving mechanical-rate proceedings and platform licensing renegotiations as these determinations directly compress or expand per-stream economics and service-provider fee structures.
Market Dynamics
AI-powered metadata tagging and automated mastering tools compress upload-to-stream timelines from weeks to hours, fundamentally altering how independent artists select distribution partners and negotiate royalty splits.
Growth Catalysts
- US Music Modernization Act:The mechanical royalty framework mandates blanket licensing through the Mechanical Licensing Collective, reducing transaction friction for songwriters and expanding the addressable creator base for distribution platforms.
- Independent artist proliferation:Spotify's open-upload policies and TikTok's discovery algorithms generate sustained demand for low-cost, high-speed distribution infrastructure among non-label creators.
- Blockchain royalty tracking:Immutable ledger systems reduce payment disputes between rights holders and streaming platforms, accelerating net payout velocity for distributed catalogs.
Market Restraints
- Mechanical rate uncertainty:US Copyright Royalty Board proceedings create pricing volatility for songwriter payments, compressing margins for services offering bundled publishing administration.
- Platform concentration risk:Spotify, Apple Music, and Amazon Music control access to over 85% of streaming revenue, forcing distributors to accept unfavorable revenue-share terms or lose catalog visibility.
- GDPR data constraints:European privacy regulations limit granular listener analytics that distributors monetize as premium artist dashboard features.
Strategic Opportunities
- South Korea market expansion:K-pop's global reach and high per-stream revenue rates attract Western distributors seeking premium-currency royalty flows.
- Sync licensing convergence:Gaming and commercial placement demand creates margin expansion for services integrating rights-clearance tools directly into upload workflows.
- Bandcamp-Patreon hybrid models:Direct-to-consumer storefronts combined with platform-wide aggregation let artists retain customer data and capture higher per-unit revenue.
Industry Challenges
- ISRC-UPC metadata standardization:Inconsistent identifier embedding across upload platforms creates royalty leakage and catalog fragmentation for multi-platform artists.
- Legacy rights reconciliation:Pre-digital catalog ownership disputes complicate distributor onboarding for established acts with complex publisher-songwriter splits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Distribution Services Market |
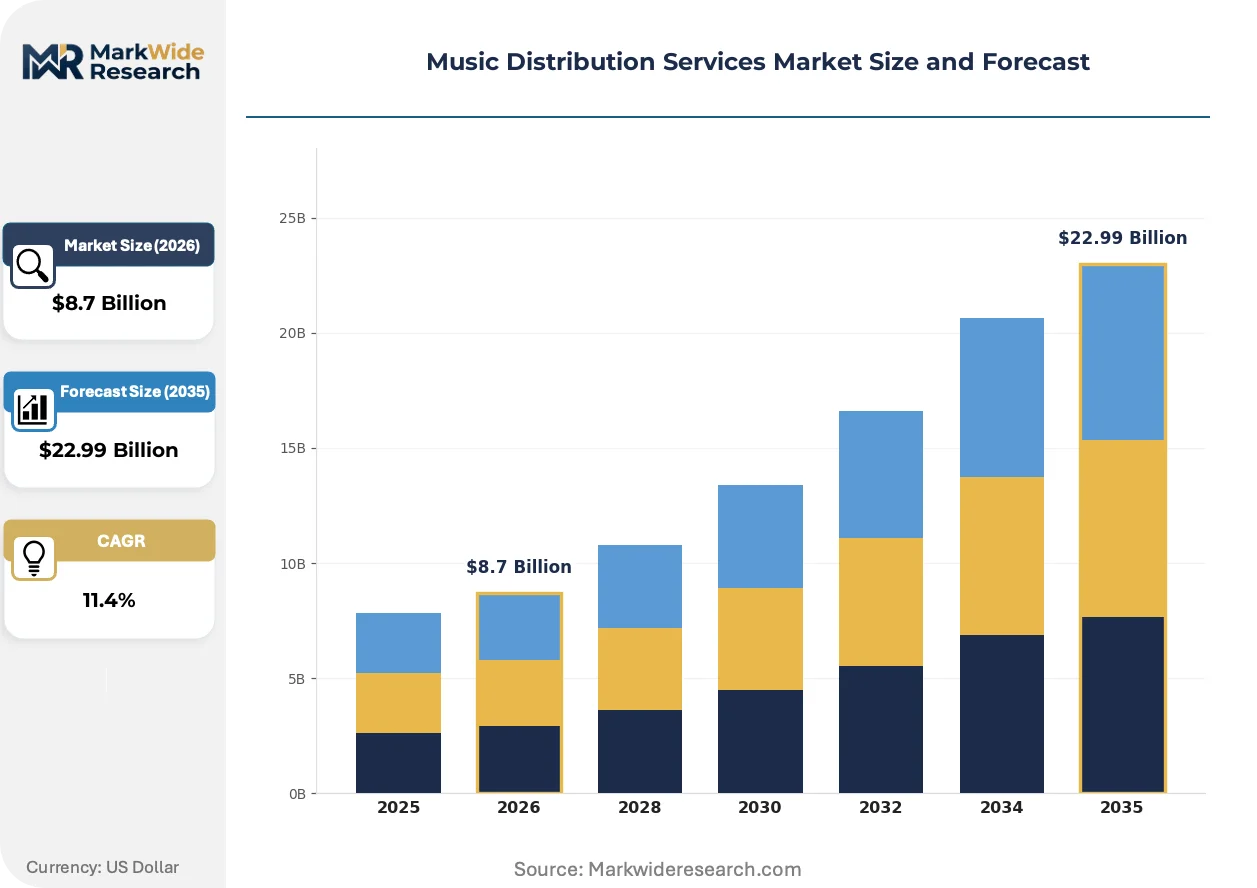
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Model: Digital, Physical, Hybrid, Direct-to-Consumer Service Type: Aggregation, Marketing, Licensing, Royalties Client Type: Independent Artists, Record Labels, Producers, Managers Delivery Channel: Streaming Platforms, Digital Downloads, Radio, Retail |
| Companies Covered | LANDR, Symphonic Distribution, DistroKid, United Masters, AWAL, TuneCore, Ditto Music, RouteNote, CD Baby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Distribution Services Market Strategic Shifts
Generative audio tools and predictive analytics reshape how distribution services differentiate beyond basic pipeline delivery, compressing the value window for pure-play aggregators.
Automated mastering algorithms from LANDR and similar platforms now process tracks at sub-dollar unit costs, displacing human engineer workflows for independent releases below 100,000 projected streams. Bedroom producers and podcast creators adopt these tools at 40% month-over-month velocity. The compression of production-quality thresholds forces traditional distributors to bundle creative services or surrender price-sensitive volume to AI-native competitors.
EU Digital Services Act transparency mandates require streaming platforms to disclose recommendation algorithm weights and demonetization criteria, altering how distributors advise artists on metadata optimization and content policy compliance. The regulation shifts liability upstream toward platforms while empowering distributors to offer compliance-auditing services. Mid-tier services targeting European catalogs invest most heavily in automated content-scanning infrastructure.
Artist procurement patterns now favor annual flat-fee subscriptions over per-release charges, with switching costs anchored to accumulated analytics dashboards and unreleased track libraries. The subscription model displaces transactional revenue for distributors while locking creators into platform ecosystems. United Kingdom independent acts show highest subscription stickiness, driven by DistroKid's unlimited-upload positioning and competitor price-matching responses.
Music Distribution Services Market Segmentation
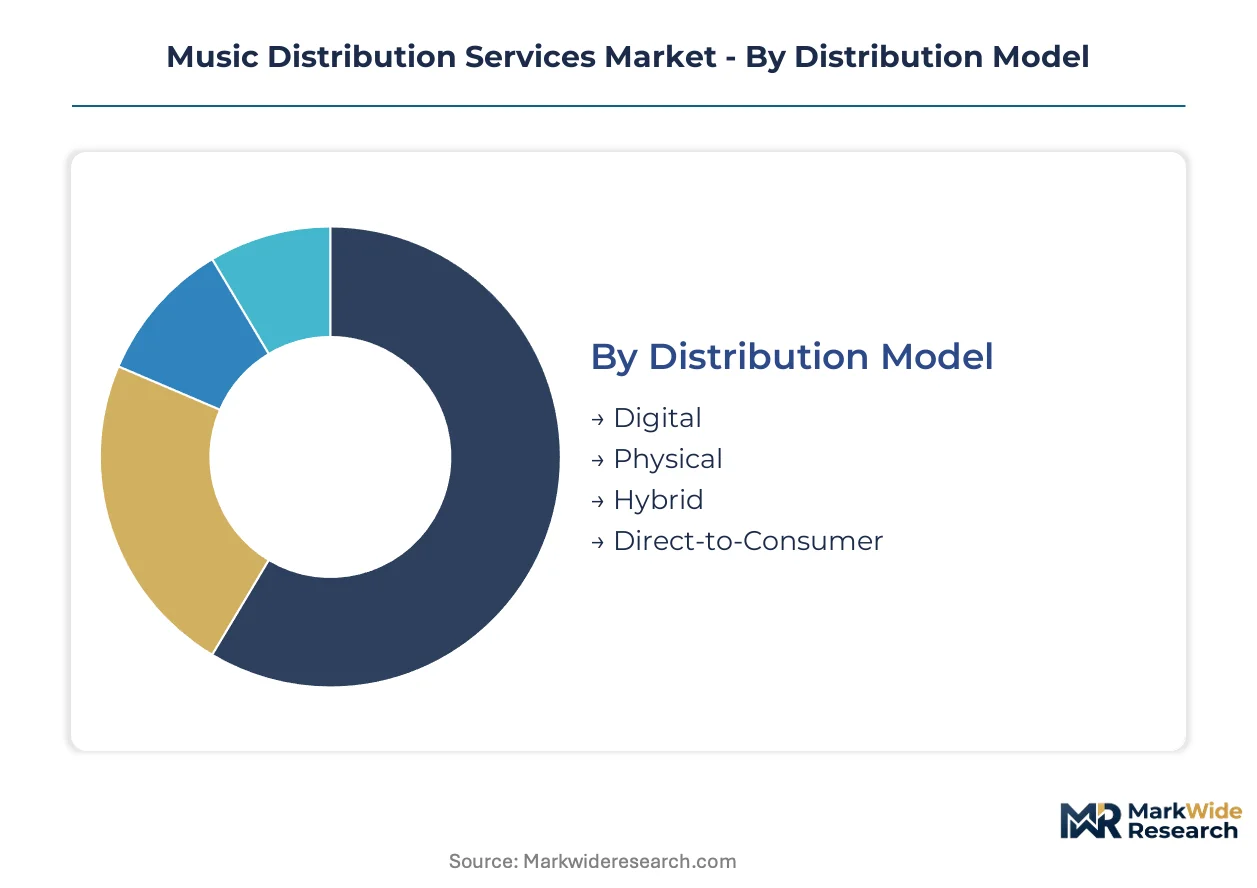
Segmentation in music distribution services reveals how margin pools concentrate around high-velocity independent creators and premium licensing workflows. Service providers calibrate pricing architectures and feature bundles against these divides to capture recurring revenue and reduce churn.
Distribution Model:
Margin pools cluster around hybrid and direct-to-consumer models that bypass platform revenue shares.
- Digital:API-driven pipeline ingestion delivers encoded audio with embedded ISRC-UPC metadata to streaming platforms and download stores. Demand concentrates among United States independent artists seeking rapid upload-to-stream timelines and real-time royalty dashboards.
- Hybrid:Combines digital aggregation with physical inventory retention for vinyl and merchandise fulfillment. United Kingdom artists with established fan bases drive adoption, motivated by direct merchandise revenue capture alongside streaming monetization.
- Physical:Wholesale logistics and manufacturing coordination for CD and vinyl distribution. Niche demand persists among legacy catalog owners and collectors.
- Direct-to-Consumer:Bandcamp and Patreon storefront integration retains customer data and captures higher per-unit revenue. South Korea K-pop independent acts show fastest adoption velocity.
The dominant share belongs to Digital, while Direct-to-Consumer is closing the gap fastest.
Service Type:
Cost tiers separate basic pipeline delivery from premium rights-management and creative services.
- Aggregation:High-frequency upload processing for non-label creators with standardized metadata protocols. Volume leadership rests with flat-fee subscription models.
- Licensing:Sync and performance-rights administration for film, gaming, and commercial placements captures disproportionate margin pools. Demand concentrates in United States and South Korea where content production volumes and per-placement rates exceed other markets.
- Marketing:Playlist pitching, social media amplification, and audience analytics tools bundled at premium tiers. Independent artists in the United Kingdom show highest attach rates.
- Royalties:Real-time accounting dashboards and publishing administration services. Regulatory complexity around mechanical rates constrains margin expansion.
Licensing commands premium pricing, though Aggregation handles the greatest transaction volume.
Client Type:
Application needs diverge sharply between self-service creators and managed roster clients.
- Independent Artists:Non-label creators requiring low-cost, high-speed infrastructure with minimal contractual encumbrance. United States and United Kingdom markets produce the highest platform adoption rates.
- Record Labels:Catalog management at scale with upstream royalty advances and selective roster curation. Labels prioritize services offering bundled publishing administration.
- Producers:Beatmakers and session creators seeking split-payment tools and collaborative workflow features.
- Managers:Multi-artist oversight dashboards and consolidated reporting for touring and merchandise coordination.
Independent Artists generate the highest transaction frequency, while Record Labels deliver the greatest revenue per client.
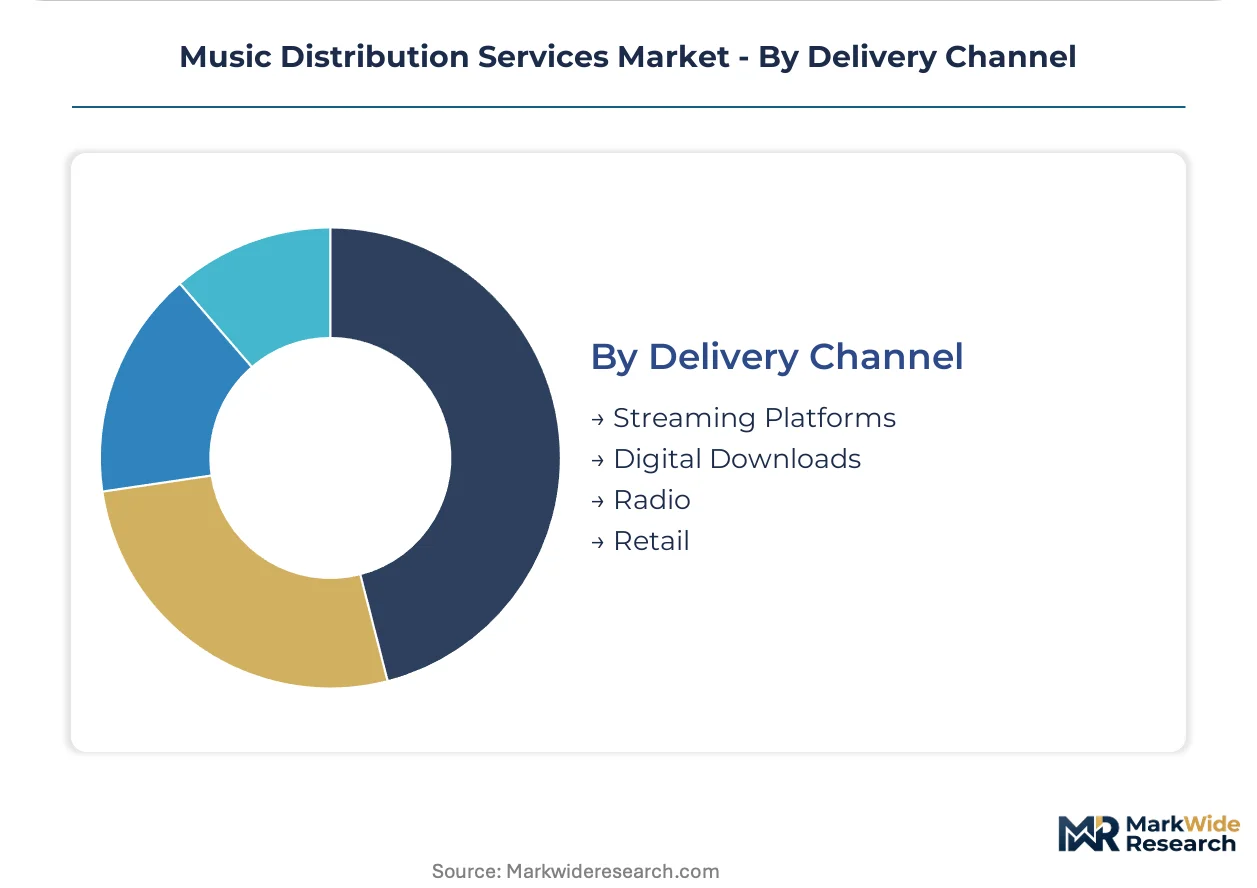
Delivery Channel:
Supply concentration in streaming platforms forces distributors to accept compressed margins for catalog visibility.
- Streaming Platforms:Spotify, Apple Music, and Amazon Music ingest dominate revenue flows. Platform concentration risk exceeds 85% of streaming revenue.
- Digital Downloads:Declining share but persistent demand in Germany and Japan where ownership preferences persist.
- Radio:Performance rights collection and broadcast monitoring services. Regulatory frameworks vary by national collection societies.
- Retail:Physical storefront placement for hybrid distribution clients with vinyl and CD inventory.
Streaming Platforms anchor the revenue base, with Radio administration expanding most quickly as performance-rights complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies, with independent artists in mature markets absorbing flat-fee subscription models while emerging-market creators gravitate toward revenue-share arrangements. Demand concentrates where streaming penetration and per-stream rates align favorably.
United States
Independent artist proliferation and TikTok-driven discovery algorithms sustain platform adoption velocity. The US Music Modernization Act mandates blanket mechanical licensing through the Mechanical Licensing Collective, reducing transaction friction. Los Angeles and Nashville clusters anchor the highest concentration of distributor-serviced catalogs.
United Kingdom
Subscription stickiness exceeds other markets as flat-fee unlimited-upload models displace per-release pricing. GDPR constraints limit granular listener analytics monetization. London's creative sector drives hybrid physical-digital distribution adoption among established independent acts.
South Korea
K-pop's global reach and premium per-stream revenue rates attract Western distributor expansion. The country's copyright framework supports robust performance-rights collection. Seoul's entertainment industry concentration accelerates direct-to-consumer storefront integration alongside platform-wide aggregation.
Germany
Digital download persistence alongside streaming growth creates dual-channel demand for distribution services. EU Digital Services Act transparency mandates reshape metadata optimization advisory services. Berlin's electronic music production cluster sustains high-frequency upload volumes from non-label creators.
Canada
French-language content quotas and public broadcaster integration requirements sustain specialized distribution needs. The country's privacy regulations align with GDPR-equivalent constraints on behavioral data collection. Toronto and Montreal metro areas anchor the highest independent artist platform adoption rates.
Music Distribution Services Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with AI-native mastering platforms compressing production timelines while flat-fee aggregators capture volume-sensitive independent creators. The vendor base spans three strategic tiers: pure-play digital aggregators, hybrid physical-digital operators, and selective label-service alternatives. Dominant competitive moves include annual subscription model proliferation and sync licensing workflow integration.
Within the flat-fee subscription tier, DistroKid and TuneCore exemplify volume-based independent artist acquisition strategies. AWAL occupies a selective position among emerging acts seeking upstream royalty advances without traditional label contracts. CD Baby anchors the hybrid physical-digital archetype, serving artists with vinyl and merchandise fulfillment requirements alongside digital aggregation.
| Leading Market Players |
|---|
| LANDR |
| Symphonic Distribution |
| DistroKid |
| United Masters |
| AWAL |
| TuneCore |
| Ditto Music |
| RouteNote |
| CD Baby |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at streaming ingestion nodes in the United States and South Korea shapes margin compression across distributor tiers, forcing flat-fee subscription models to absorb volume spikes while premium licensing services extract value from sync placement workflows. This scale dynamic concentrates pricing power among platform-aggregators serving high-velocity independent artists, while fragmenting margin pools for hybrid physical-digital operators.
Pricing Analysis
After-sales revenue from publishing administration and sync licensing drives lifetime value for distribution services beyond core upload fees. Three-tier pricing structure across premium, standard, and economy levels segments independent artists by projected stream volume and metadata complexity. Cost compression in basic aggregation tiers intensifies because AI-native mastering platforms undercut traditional bundled creative services. Bedroom producers and podcast creators show highest price sensitivity, while mid-tier acts seeking label-service alternatives without contract encumbrance absorb premium positioning.
Supply Chain Analysis
The United States and South Korea anchor streaming platform ingestion infrastructure, while the United Kingdom sustains physical manufacturing coordination for vinyl and merchandise fulfillment. API-driven pipeline ingestion draws from cloud computing capacity, ISRC-UPC metadata registry access, and mechanical licensing collective connectivity. Single-source vulnerability concentrates around Spotify, Apple Music, and Amazon Music revenue gatekeeping. Distribution runs through direct platform relationships for streaming, with hybrid models retaining wholesale logistics for physical inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around independent artist proliferation and TikTok-driven discovery algorithms, creating niche positioning for services bundling compliance-auditing with upload workflows.
For Market Incumbents: Consolidate around selective roster curation and upstream royalty advances to defend against AI-native mastering platforms eroding creative-service margins. Expand automated content-scanning infrastructure to capture EU Digital Services Act advisory revenue. Vertical integration into sync licensing rights-clearance tools secures placement workflow control against specialized competitors. For New Entrants and Emerging Players: Anchor in South Korea's K-pop independent sector where premium per-stream revenue rates and direct-to-consumer storefront adoption outpace Western markets. Target producers and beatmakers with split-payment tools and collaborative workflow features underserved by volume-focused aggregators. Lead with blockchain royalty tracking as a trust-differentiator against legacy payment dispute patterns. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among services combining flat-fee subscriptions with publishing administration attach rates. Long-term viability rests on regulatory navigation capacity as mechanical rate proceedings and GDPR constraints reshape monetizable data categories. Acquisition focus should center on mid-tier operators with established European compliance infrastructure. Signal to watch: platform licensing renegotiation outcomes affecting revenue-share terms.| Strategic Initiative | Industry Significance |
|---|---|
| Sync Licensing Workflow Integration | Captures gaming and commercial placement margin pools through embedded rights-clearance automation. |
| AI-Native Mastering Platform Launch | Displaces human engineer workflows at sub-dollar unit costs for independent releases below viral thresholds. |
| Blockchain Royalty Tracking Deployment | Reduces payment disputes between rights holders and streaming platforms through immutable ledger verification. |
| EU Compliance Auditing Service Rollout | Monetizes Digital Services Act transparency mandates through automated content-scanning infrastructure. |
| Direct-to-Consumer Storefront Expansion | Retains customer data and captures higher per-unit revenue through Bandcamp-Patreon hybrid models. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of distributor royalty statements, platform licensing disclosures, and mechanical rate proceeding documents. Interviews with independent artist managers, digital supply-chain engineers, music publishing administrators, and sync licensing coordinators inform demand-side calibration. SEC filings from streaming platforms, US Copyright Royalty Board dockets, and EU regulatory impact assessments provide supply-side validation. Bottom-up upload volume estimates triangulate against top-down streaming revenue allocation models.
Segmentation dimensions modeled include distribution model architecture, service type tier, client type application needs, and delivery channel concentration. Growth trajectories derive from independent artist proliferation rates, AI tool adoption velocity, and regulatory framework evolution across the analysis window. Forecast inputs incorporate mechanical licensing collective transaction volumes, per-stream revenue rate differentials by geography, and platform concentration risk metrics.
Material uncertainties — mechanical rate determination outcomes, platform licensing renegotiation terms, and GDPR enforcement evolution — sit outside the modeled envelope. Forecasts reflect assumptions around sustained independent creator entry and stable streaming platform revenue shares. Recalibration cycles align with material shifts in regulatory proceedings and platform policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Virtual Musical Instruments Market
Music
Electronic Dance Music (EDM) Market
Music
Asia-Pacific Independent Artist Market
Music
Music Production Software Market
Music
Europe Independent Artist Market
Music
Music App Market
Music
Music Publishing Market
Music
Traditional Chinese Instruments Market
Music
Musical Groups and Artists Market
Music
Global Free Music Making Software Market
Music
Vinyl Records Market
Music
United States Live Music Market
Music
Traditional Music Market
Music
Discography Market
Music
Global in-Store Music Service Market
Music
Music Synthesizers Market