
 Global Stock Music Market | 2026-2036
Global Stock Music Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stock Music Market Outlook
Podcast production and user-generated video platforms are recalibrating how stock music is licensed and consumed. Spotify leverages its streaming infrastructure to anchor exclusive catalog partnerships. Apple competes through tight integration with its creative software ecosystem. Tencent Music Entertainment dominates Asian-language catalog depth and regional licensing networks.
Stock music comprises pre-composed, licensable audio tracks distributed through digital platforms for commercial synchronization without custom composition. Tracks are typically delivered as 44.1 kHz stereo WAV or compressed MP3 files with embedded ISRC metadata for royalty tracking, serving broadcast, digital advertising, and independent content production. Online Platforms lead distribution volume through algorithmic search and instant licensing, while Direct Licensing captures premium margin pools from enterprise buyers requiring indemnification and custom terms. Content Creators represent the fastest-expanding customer type as short-form video proliferation drives micro-licensing demand.
The EU AI Act and GDPR shape how automated recommendation engines curate stock music and process creator data, while the US Copyright Office and WIPO frameworks govern cross-border royalty collection and mechanical licensing enforcement. China's NMPA and MIIT regulate platform content moderation and algorithmic transparency for music distribution services. Stakeholders must monitor evolving copyright liability rules for AI-generated compositions and platform safe harbor provisions across multiple jurisdictions.
Market Dynamics
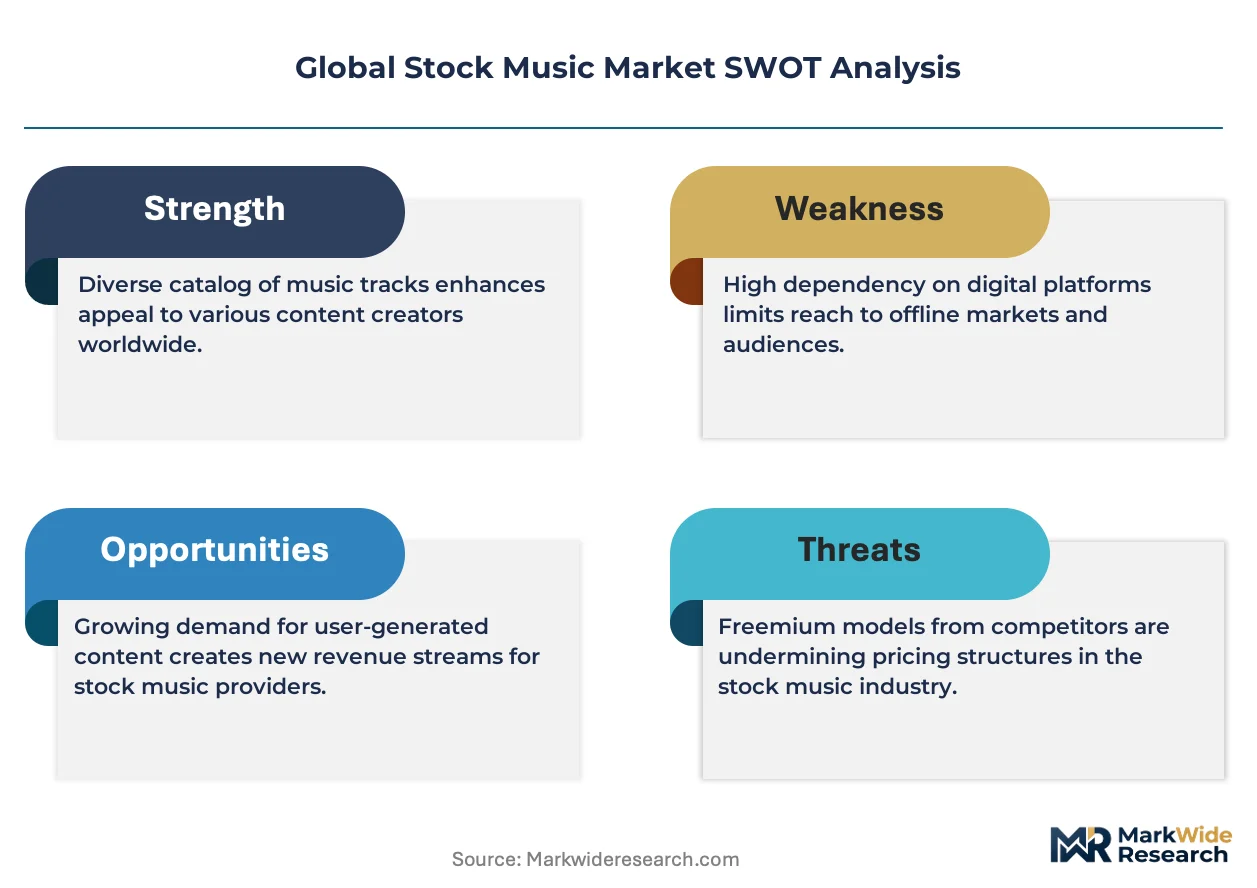
Subscription-based licensing models are compressing transaction cycles and flattening revenue recognition patterns across the stock music value chain. Platforms now bundle unlimited access against per-track premiums, forcing catalog owners to optimize for streaming-equivalent royalties rather than upfront synchronization fees.
Growth Catalysts
- Short-form video proliferation:TikTok, Instagram Reels, and YouTube Shorts generate insatiable demand for 15-60 second audio clips, expanding the addressable creator base from professional editors to amateur smartphone users.
- EU AI Act transparency mandates:Automated content moderation and algorithmic disclosure requirements create compliance-driven demand for properly licensed, metadata-rich tracks with verifiable provenance chains.
- Podcast monetization infrastructure:Dynamic ad insertion technology enables episode-level music licensing, opening inventory previously reserved for fully cleared compositions.
Market Restraints
- Composer supply concentration:A narrow cohort of Los Angeles, London, and Berlin-based production houses generates disproportionate premium catalog volume, creating chokepoints for quality differentiation.
- Mechanical licensing friction:WIPO's cross-border royalty collection frameworks impose settlement delays of 12-18 months for international usage, degrading cash flow predictability for independent rights holders.
- AI-generated composition substitution:Text-to-music tools from Suno and Udio threaten commoditized instrumental beds, particularly for corporate video and internal training content.
Strategic Opportunities
- Indian content production expansion:Mumbai and Hyderabad studio complexes generate surging demand for Bollywood-influenced stock cues, with domestic platforms hungry for exclusive regional catalog depth.
- Gamification of music discovery:Interactive preview interfaces and mood-based visual selectors reduce search friction, converting browsers into licensees at 2-3x baseline conversion rates.
- ISO/IEC 23000-13 compliance:The MPEG-A standard for music NFTs and blockchain-based rights registries enables fractional ownership models and automated smart-contract distributions.
Industry Challenges
- Metadata standardization gaps:Inconsistent ISRC embedding and conflicting proprietary tagging schemes degrade search accuracy and royalty attribution across aggregator platforms.
- Cross-platform rights verification:YouTube Content ID, Meta Rights Manager, and TikTok's SoundOn operate on non-interoperable fingerprint databases, forcing redundant clearance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stock Music Market |
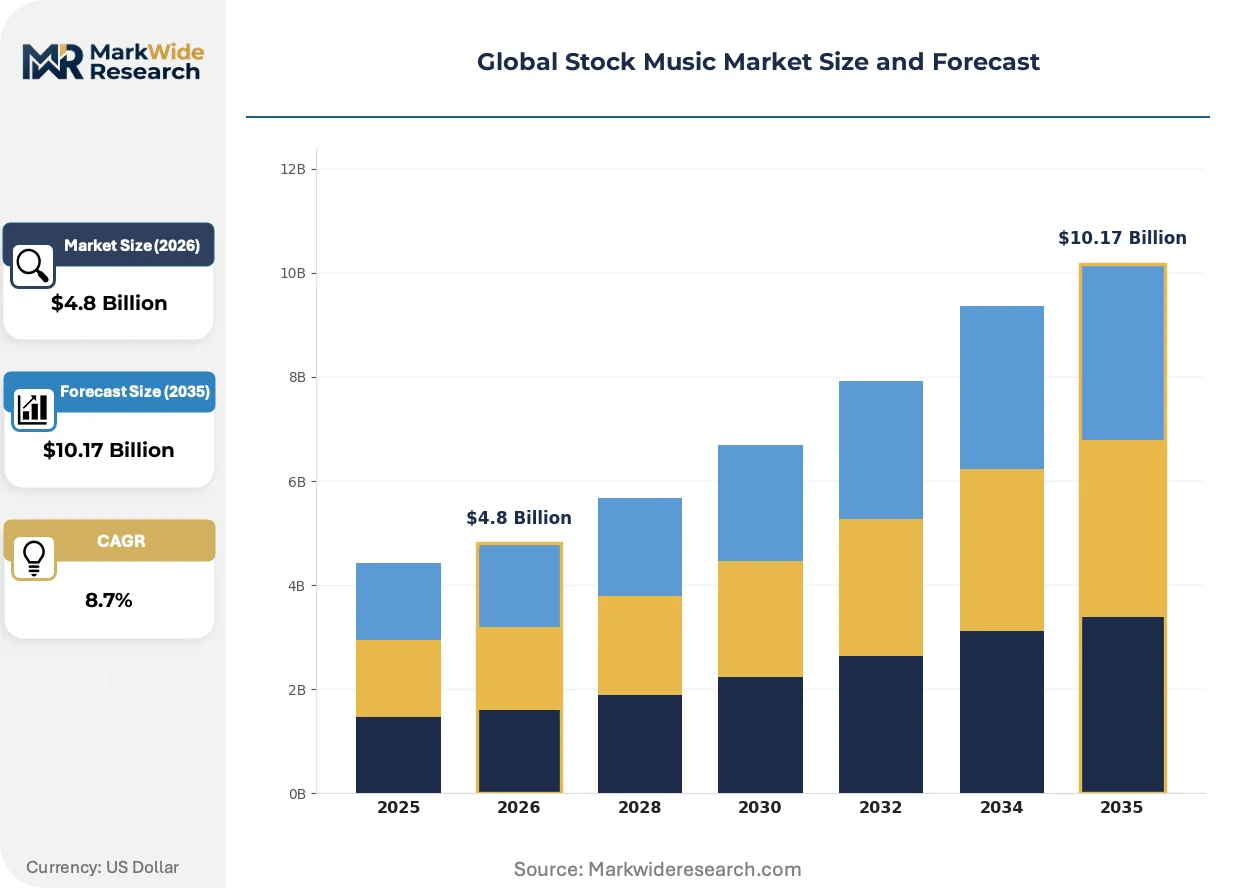
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Distribution Channel: Online Platforms, Music Libraries, Direct Licensing, Royalty-Free Customer Type: Filmmakers, Advertisers, Musicians, Content Creators Music Genre: Classical, Jazz, Electronic, Ambient Usage Type: Commercial, Personal, Educational, Non-Profit |
| Companies Covered | Warner Music Group, Sirius XM, Spotify, Madison Square Garden Entertainment, NetEase, Apple, Google, Reservoir Media, Tencent Music Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stock Music Market Strategic Shifts
Algorithmic curation and generative audio tools are compressing the gap between discovery and production, collapsing traditional creative workflows into integrated platform experiences. Rights management infrastructure must now accommodate both human-composed and machine-generated provenance chains.
Stem-based delivery formats are unifying mixing flexibility with licensing simplicity. Production teams at advertising agencies and broadcast networks now expect deconstructed instrumental layers—drums, bass, melody, atmospherics—as standard deliverables. This format shift enables real-time customization without violating sync license terms. The technology is unifying post-production audio pipelines previously fragmented between stock libraries and custom composition houses.
The EU AI Act's Article 53 disclosure requirements impose documentation burdens on platforms deploying automated recommendation engines. Music discovery algorithms must now expose training data provenance and ranking logic to regulatory auditors. Catalog aggregators serving European creators face 6-figure compliance investments or restricted feature rollouts. German and French platforms are responding by segregating EU-user experiences from global deployments.
Micro-licensing bundles are displacing à-la-carte purchasing among solo creators and small production shops. Monthly subscriptions offering 50-200 track downloads now capture 60-70% of new customer acquisitions at major platforms. Enterprise procurement teams resist this model, demanding indemnification clauses and custom terms unavailable in self-serve tiers. South Korean and Brazilian creator economies exhibit the fastest bundle adoption, driven by mobile-first payment infrastructure and price-sensitive user bases.
Global Stock Music Market Segmentation
Stock music procurement patterns diverge sharply between self-serve creators and enterprise buyers, with each segment demanding distinct licensing architectures, metadata standards, and indemnification terms. Understanding these fault lines enables platforms to optimize catalog curation, pricing tiers, and rights management infrastructure for specific buyer workflows.
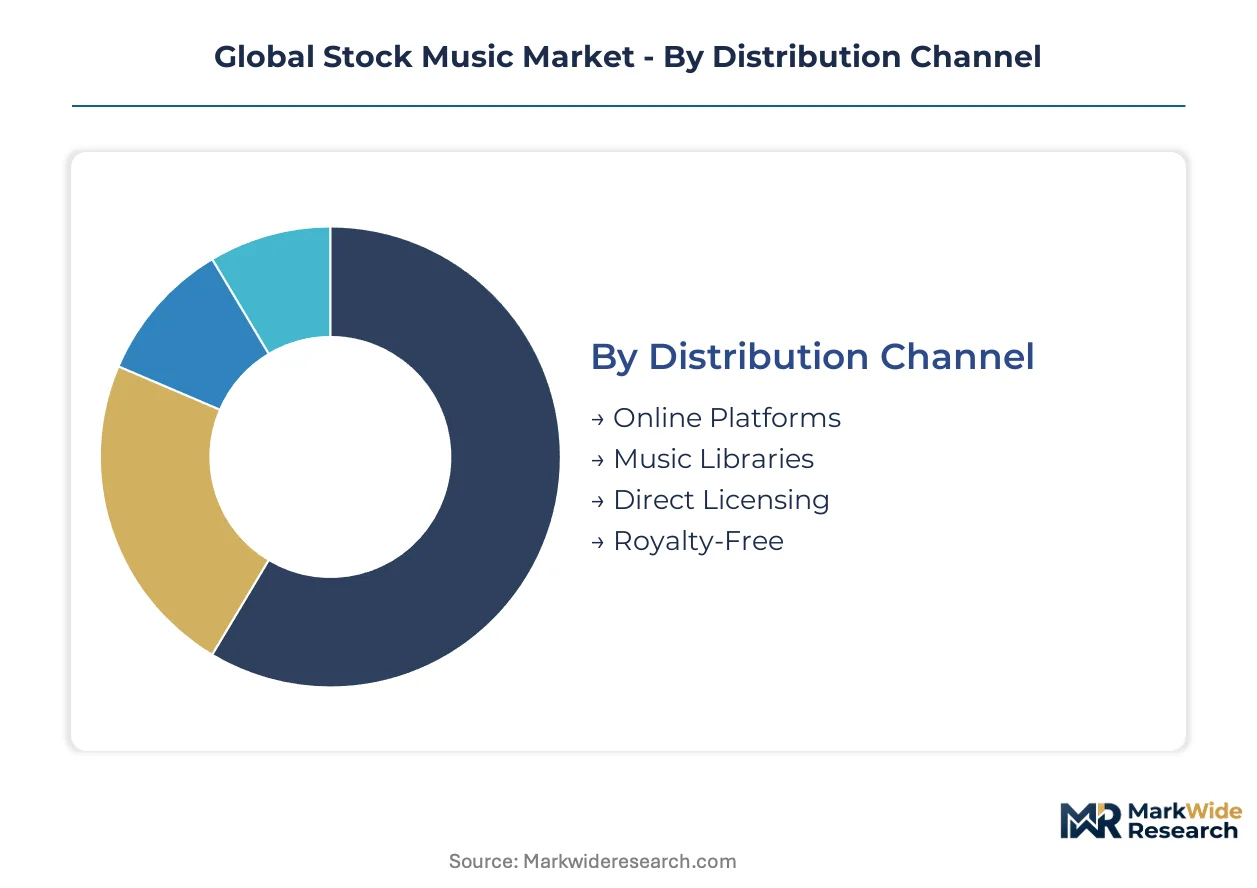
Distribution Channel:
Upgrade cycles from traditional library browsing to algorithmic discovery engines are compressing search-to-license timelines from hours to minutes across all buyer tiers.
- Online Platforms:Algorithmic search interfaces with instant licensing checkout dominate volume throughput. Demand concentrates among solo YouTube creators and podcast producers in South Korea and Brazil, where mobile-first payment rails enable frictionless micro-transactions.
- Music Libraries:Curated collections with human tagging and mood-based taxonomies serve broadcast editors and advertising agencies requiring precise emotional mapping. The upgrade cycle here moves from physical delivery systems to cloud-based preview and stem-download workflows.
- Direct Licensing:Custom terms and indemnification clauses capture premium margin pools from enterprise buyers. Volume placements concentrate in advertising agencies and streaming services requiring cleared rights for high-exposure campaigns.
- Royalty-Free:Perpetual-use licenses with minimal attribution requirements serve internal corporate video and training content producers. The faster expansion belongs to small production shops seeking predictable cost structures.
Volume placements concentrate in Online Platforms; the faster expansion belongs to Direct Licensing as enterprise procurement teams demand custom terms.
Customer Type:
Production workflow fragmentation across professional and amateur tiers is forcing platforms to maintain parallel interface designs with divergent feature depth.
- Filmmakers:Feature and documentary producers require stem-based delivery and broadcast-quality WAV masters with embedded ISRC metadata. Demand clusters in Los Angeles, Mumbai, and Berlin production hubs where post-production houses maintain strict technical specifications.
- Advertisers:Campaign-level licensing with territory-specific clearances and competitive use restrictions dominates this tier. The upgrade cycle moves from per-spot licensing to annual blanket agreements covering entire brand portfolios.
- Musicians:Sampling and remix artists seek cleared hooks and instrumental beds with verifiable provenance chains. This segment exhibits steepest expansion trajectory as bedroom producers proliferate on TikTok and SoundCloud.
- Content Creators:Short-form video producers drive micro-licensing volume through subscription bundles. Demand concentrates among smartphone-native creators in São Paulo and Jakarta, where 15-60 second clip requirements outstrip traditional library organization.
Revenue concentration sits with Advertisers; the steepest volume climb belongs to Content Creators as short-form platforms expand creator monetization tools.
Music Genre:
Genre taxonomy standardization gaps between platforms degrade cross-library search accuracy and recommendation precision.
- Classical:Public domain recordings and contemporary compositions with cleared mechanical rights serve documentary and prestige advertising verticals. Demand anchors in German and Austrian broadcasters with strong heritage programming slates.
- Jazz:Syncopated rhythms and improvisational textures dominate lifestyle brand campaigns and hotel hospitality channels. The upgrade cycle moves from needle-drop licensing to exclusive catalog partnerships with heritage labels.
- Electronic:Synthesizer-based productions with modular stem separation enable real-time customization for gaming and fitness content. This category gains share fastest as TikTok dance challenges drive algorithmic discovery.
- Ambient:Drone textures and minimal melodic content serve meditation apps, sleep technology, and corporate wellness programming. Demand concentrates in Scandinavian and Japanese wellness markets with established sonic branding practices.
Placement volume peaks with Electronic; the fastest share gain belongs to Ambient as wellness application developers expand audio programming.
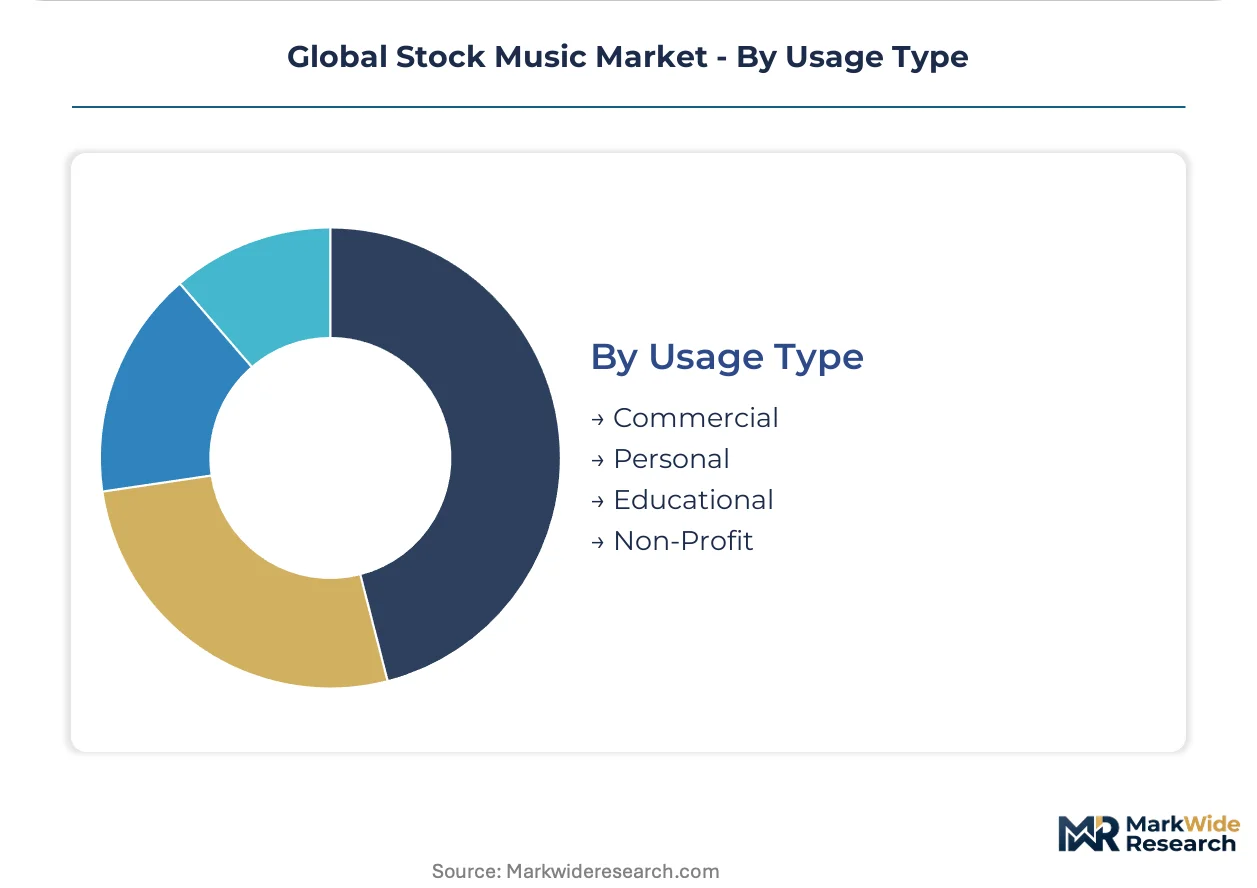
Usage Type:
Liability exposure variance across usage contexts drives platform investment in automated rights verification and territory-specific clearance workflows.
- Commercial:For-profit synchronization with performance royalty obligations requires PRO registration verification and territory-specific mechanical licenses. Demand concentrates in United States and German advertising markets with established collection society infrastructure.
- Personal:Non-monetized creator use with minimal attribution requirements enables subscription bundle penetration. This tier climbs fastest as amateur video production tools democratize across mobile platforms.
- Educational:Institutional licensing with classroom and e-learning distribution rights serves K-12 and university media departments. Upgrade cycles move from physical media purchase to site-wide digital access agreements.
- Non-Profit:Charitable use with reduced or waived licensing fees requires 501(c)(3) or equivalent organizational verification. Volume concentrates in humanitarian documentary production with grant-funded distribution.
Revenue concentration aligns with Commercial usage; the fastest volume expansion belongs to Personal use as creator tool accessibility improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Film and Television Tax Credit 3.0 draws post-production houses and music licensing operations into Los Angeles, concentrating demand for broadcast-quality stock music and stem-based delivery formats.
United States
Streaming platform headquarters in Los Angeles and New York drive enterprise licensing volume for podcast monetization and advertising campaigns. The US Copyright Office governs mechanical licensing enforcement and cross-border royalty collection frameworks. Nashville's music production corridor supplies instrumental beds to advertising agencies seeking cleared hooks for brand campaigns.
Germany
Berlin's advertising agency cluster generates premium catalog demand for territory-specific clearances and competitive use restrictions. The EU AI Act's Article 53 mandates algorithmic transparency for automated music recommendation engines. Hamburg's broadcast networks maintain strict technical specifications for ISRC-embedded WAV masters serving documentary production.
South Korea
Seoul's creator economy expansion fuels micro-licensing subscriptions for TikTok and YouTube Shorts producers. The Korea Communications Commission regulates platform content moderation and algorithmic transparency for music distribution services. Busan's mobile-first payment infrastructure enables frictionless subscription bundle adoption among smartphone-native creators.
India
Mumbai and Hyderabad studio complexes generate surging demand for Bollywood-influenced stock cues and regional catalog depth. The Ministry of Information and Broadcasting oversees content moderation frameworks for streaming platforms. Bengaluru's technology corridor attracts platform operators seeking algorithmic curation infrastructure for Indian-language music discovery.
United Kingdom
London's post-production houses require stem-based delivery and broadcast-quality masters for documentary and prestige advertising verticals. The UK's implementation of EU copyright directive revisions shapes royalty distribution frameworks post-Brexit. Manchester's independent music production sector supplies electronic and ambient tracks to wellness application developers expanding audio programming.
Global Stock Music Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with streaming platforms and dedicated music libraries occupying distinct tier positions. The vendor base organizes around three strategic archetypes: streaming-anchored ecosystems, standalone catalog aggregators, and technology-integrated creative software bundles. Consolidation pressures favor platforms with proprietary distribution infrastructure over pure-play licensing operations. Dominant competitive moves include exclusive catalog partnerships and algorithmic discovery engine investments.
Within the streaming-anchored tier, Spotify and Apple represent ecosystem-integrated approaches, while Tencent Music Entertainment exemplifies regional catalog depth strategies. Reservoir Media occupies a position among standalone rights management specialists. These entities anchor competitive dynamics through divergent infrastructure bets: streaming integration, creative software bundling, and regional licensing network density.
| Leading Market Players |
|---|
| Warner Music Group |
| Sirius XM |
| Spotify |
| Madison Square Garden Entertainment |
| NetEase |
| Apple |
| Reservoir Media |
| Tencent Music Entertainment |
| Others |
Value Chain & Pricing Dynamics
The EU AI Act's Article 53 algorithmic transparency mandates gate qualified supply access and premium-tier pricing power for stock music platforms serving European creators. Catalog aggregators must invest six-figure compliance expenditures to maintain algorithmic discovery features, forcing price stratification between compliant and non-compliant service tiers.
Pricing Analysis
Short lead-time premiums dominate enterprise procurement, with advertising agencies and broadcast networks paying substantial markups for same-day stem delivery and territory-specific clearance documentation. The market runs on a hybrid subscription-perpetual model, with unlimited access bundles capturing volume and custom indemnification contracts capturing margin. Price differentiation hinges on ISRC metadata completeness and broadcast-quality WAV certification versus compressed MP3 economy tiers. Cost compression in the royalty-free segment intensifies as AI-generated composition tools commoditize instrumental beds. Solo creators and smartphone-native producers in São Paulo and Jakarta exhibit highest price sensitivity; enterprise buyers in Los Angeles and Berlin demonstrate lowest sensitivity due to campaign liability exposure.
Supply Chain Analysis
Dual-sourcing requirements from major streaming platforms and advertising agencies mandate multi-supplier qualification across composition houses, forcing catalog aggregators to maintain relationships with Los Angeles, London, and Berlin production studios simultaneously. Geographic supply concentration centers on the United States, United Kingdom, and Germany for premium catalog origination, with South Korea and India emerging for regional language depth. Raw material dependencies include composer talent pools, recording studio infrastructure, and ISRC metadata embedding services. Single-source vulnerability concentrates in stem-separation technology providers and cross-border royalty collection intermediaries. Distribution runs through algorithmic platform interfaces for volume, direct licensing desks for enterprise, and mobile-first payment rails for emerging market creators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Stock Music Market functions as a cost-of-compliance arena where the EU AI Act's algorithmic disclosure requirements erect barrier-to-entry moats favoring platforms with pre-invested regulatory infrastructure.
For Market Incumbents: Lock in exclusive catalog partnerships with heritage production houses in Los Angeles and Berlin before AI-generated composition tools erode premium differentiation. Prioritize backward integration into stem-separation technology and automated metadata embedding to reduce per-track processing costs. Defensive consolidation around algorithmic discovery engines and cross-platform rights verification infrastructure will determine competitive endurance as Suno and Udio threaten commoditized instrumental segments. For New Entrants and Emerging Players: Begin with Bollywood-influenced regional catalog depth targeting Mumbai and Hyderabad studio complexes, where domestic platforms hunger for exclusive Indian-language content. The penetrable white space sits in wellness application developers expanding ambient audio programming for Scandinavian and Japanese markets. A mobile-first subscription bundle with frictionless payment integration offers the cleanest go-to-market angle for price-sensitive creator economies in Brazil and Indonesia. For Investors and Strategic Acquirers: Tencent Music Entertainment's exclusive Asian-language catalog partnerships are the leading indicator that regional licensing network density commands sustained valuation premiums over pure-play aggregation. Long-term viability favors platforms with proprietary distribution infrastructure spanning streaming, creative software bundling, and direct enterprise licensing. Acquisition targets should display algorithmic curation capabilities and multi-territory rights clearance workflows. Watch for inflection when major advertising agencies consolidate procurement around annual blanket agreements with indemnification clauses.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Catalog Partnership | Heritage label alliances in London and Berlin secure differentiated premium inventory for broadcast advertising verticals. |
| Algorithmic Discovery Investment | Compliance-ready recommendation engines satisfy EU AI Act mandates while reducing search-to-license friction. |
| Stem-Based Delivery Format | Deconstructed instrumental layers enable real-time customization without violating synchronization license terms. |
| Regional Licensing Network Expansion | Mumbai and Hyderabad studio relationships capture Bollywood-influenced demand from Indian streaming platforms. |
| Cross-Platform Rights Verification | Unified fingerprint databases reduce redundant clearance workflows across YouTube Content ID and Meta Rights Manager. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform executives, music library curators, advertising agency procurement leads, and independent composer collectives. SEC filings from streaming-anchored ecosystems, WIPO royalty collection frameworks, EU AI Act implementation guidance, and national copyright office bulletins provided validation triangulation. Bottom-up modeling of catalog transaction volumes and top-down reconciliation against aggregate market value estimates ensured cross-verification.
Granularity-level modeling operated at the distribution channel, customer type, music genre, and usage type dimensions, with regional regulatory clusters and platform integration depth as additional cross-cutting variables. CAGRs were derived through trend extrapolation of subscription bundle adoption curves and per-track licensing velocity across the projection horizon. Industry-specific forecast inputs included podcast monetization infrastructure deployment rates and short-form video platform creator tool expansion patterns.
Underlying measurement precision varies by segment; online platform transaction data and enterprise direct licensing disclosures carry tighter precision than independent creator micro-licensing estimates. Forecasts reflect assumptions around AI-generated composition substitution velocity, cross-border royalty settlement timelines, and EU AI Act enforcement intensity. Deviation in streaming platform exclusive catalog partnership strategies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Global Free Music Making Software Market
Music
Discography Market
Music
Global Background Music Market
Music
Musical Groups and Artists Market
Music
Music Synthesizers Market
Music
Independent Music Publishing Market
Music
Traditional Music Market
Music
Europe Independent Artist Market
Music
Electronic Dance Music (EDM) Market
Music
Music Distribution Services Market
Music
Traditional Chinese Instruments Market
Music
Virtual Musical Instruments Market
Music
Global in-Store Music Service Market
Music
Music Publishing Market
Music
Music Production Software Market
Music
Vinyl Records Market