
 Music App Market | 2026-2036
Music App Market Size, Share, and Industry Trends Forecast 2026-2036
Music App Market Outlook
AI-generated synthetic audio is expanding its footprint in music production pipelines, compressing traditional studio costs and democratizing composition tools. Spotify leverages its podcast-to-music bundling architecture to sustain subscriber retention across price-sensitive tiers. Apple Music anchors its competitive stance through spatial audio codec integration and hardware-software lock-in across iOS devices. Tencent Music dominates China through social entertainment features that extend beyond passive streaming into virtual gifting and live performance monetization.
A music app constitutes a software application that delivers audio content through real-time streaming protocols, progressive download caching, or hybrid peer-assisted distribution, typically operating at bitrates between 128 kbps and 320 kbps AAC or Ogg Vorbis compression. Its primary commercial purpose centers on licensed content aggregation, personalized recommendation algorithm deployment, and recurring revenue capture through subscription billing or programmatic advertising insertion. Streaming services command the largest revenue pool within service type segmentation, while ad-supported tiers absorb the bulk of emerging market user acquisition despite thinner per-user economics. The freemium pricing model functions as the dominant onboarding funnel, converting free listeners into paid subscribers through feature gating and audio quality tiering.
The European Union's Digital Services Act and GDPR impose algorithmic transparency and data portability obligations that reshape how music apps process listener behavior for recommendation engines. The United States Copyright Royalty Board and China's National Copyright Administration independently set mechanical and performance royalty rates that directly determine platform cost structures and artist payout frameworks. Stakeholders must monitor evolving AI training data licensing regimes as generative models ingest copyrighted catalogs without established compensation mechanics.
Market Dynamics
AI-generated audio watermarking is compressing royalty attribution timelines while fragmenting platform cost structures across divergent national copyright frameworks.
Growth Catalysts
- Creator Economy Platforms:Self-service distribution tools empower independent musicians and podcast producers to bypass traditional label gatekeepers. Upload volume from non-professional creators multiplies catalog depth without proportional A&R overhead.
- GDPR Algorithmic Transparency Mandates:European listener data portability rules force recommendation engine refinement that improves discovery precision. Platforms invest in explainable AI to maintain EU market access.
- Spatial Audio Codecs:Object-based immersive audio formats differentiate premium subscription tiers. Hardware-software codec integration locks high-fidelity listeners into ecosystem-specific hardware purchases.
Market Restraints
- Mechanical Royalty Rate Volatility:US Copyright Royalty Board proceedings create multi-year payout uncertainty. Platform cost models strain under retroactive rate adjustments.
- Three-Label Licensing Concentration:Universal, Sony, and Warner control master recording rights for the majority of streaming catalogs. Negotiation leverage tilts toward rights holders in renewal cycles.
- Freemium Conversion Ceilings:Ad-supported tier economics cap per-user revenue in price-sensitive demographics. Emerging market ARPU remains structurally compressed against content acquisition costs.
Strategic Opportunities
- Brazil Social Entertainment Integration:Virtual gifting and live performance monetization models proven in China adapt to Latin American creator-fan relationship norms. Platforms localize tipping mechanics for regional payment infrastructure.
- AI Training Data Licensing Regimes:Generative model ingestion of copyrighted catalogs creates demand for new rights-clearance frameworks. Early movers in structured licensing capture recurring revenue from model developers.
- Podcast-to-Music Bundling Architecture:Audio content category convergence reduces subscriber churn through diversified consumption. Bundled retention mechanics outperform single-format loyalty programs.
Industry Challenges
- Synthetic Audio Attribution Complexity:Deepfake detection and provenance verification strain existing content identification systems. Platform trust-and-safety teams lack standardized tooling for generative audio flagging.
- Cross-Border Royalty Collection Fragmentation:Performing rights organizations operate non-interoperable databases across national jurisdictions. Songwriter payout latency extends to 12-18 months for international performances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music App Market |
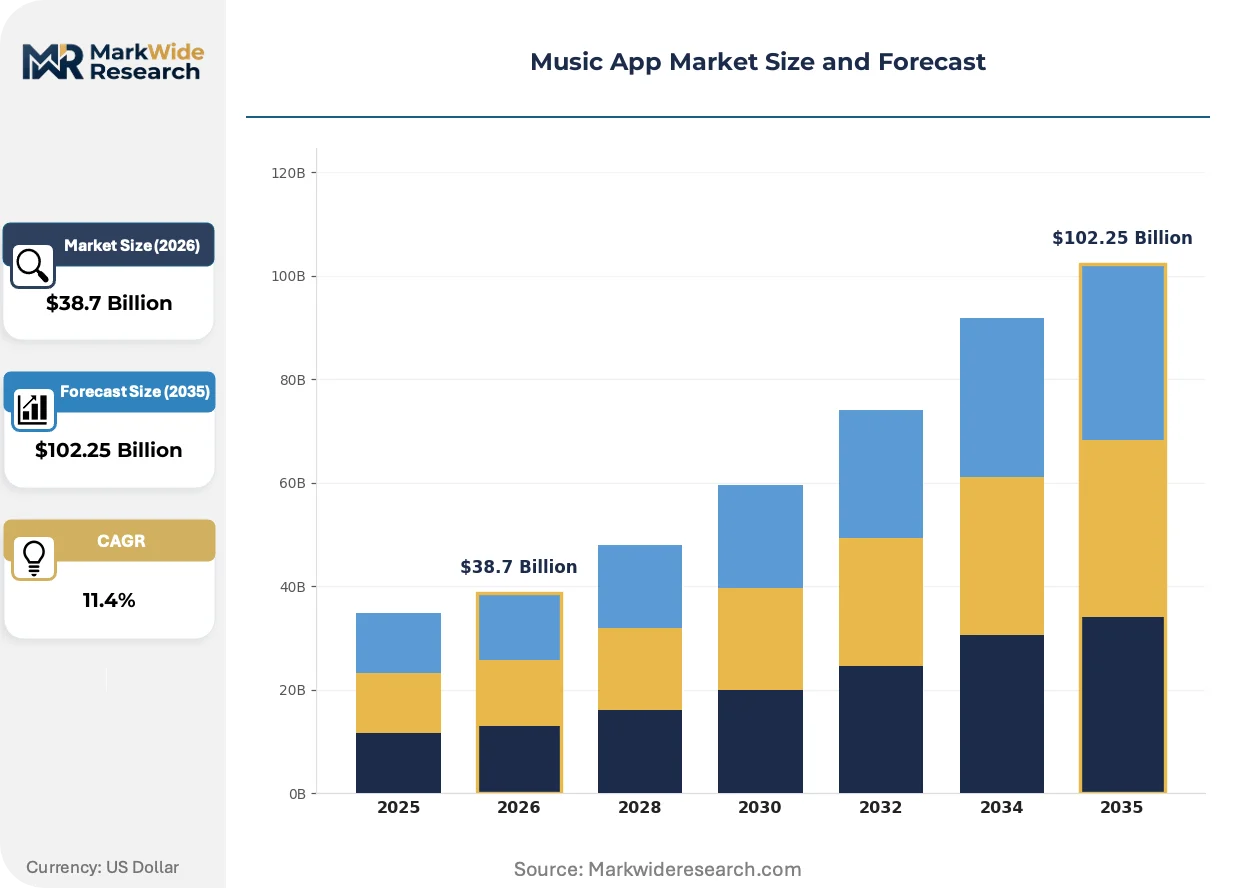
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Streaming, Download, Radio, Live Concerts User Type: Individual Users, Families, Students, Professionals Pricing Model: Subscription, Freemium, One-Time Purchase, Ad-Supported Platform: iOS, Android, Windows, Web |
| Companies Covered | Spotify, Apple Music, Amazon Music, YouTube Music, Tencent Music, NetEase, Tidal, Deezer, SoundCloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music App Market Strategic Shifts
Generative audio tools are collapsing traditional production timelines while regulatory pressure on algorithmic transparency intensifies across major streaming jurisdictions.
Neural audio synthesis is expanding into mainstream composition workflows. Bedroom producers and mid-tier artists deploy text-to-music interfaces to generate stem layers and arrangement variations. Studio rental demand compresses as cloud-based generative tools substitute for acoustic tracking sessions.
EU AI Act transparency requirements reshape recommendation engine documentation obligations. Music platforms must disclose ranking parameters and provide user-facing controls for personalization intensity. German and French regulators lead enforcement, with penalty structures scaling to platform revenue percentage.
Listener subscription behavior fragments across audio content categories rather than consolidating under single-format loyalty. Podcast completion rates predict music subscription retention more reliably than genre affinity alone. Platforms in the United States and Brazil report higher lifetime value from cross-category engagers than music-only subscribers.
Music App Market Segmentation
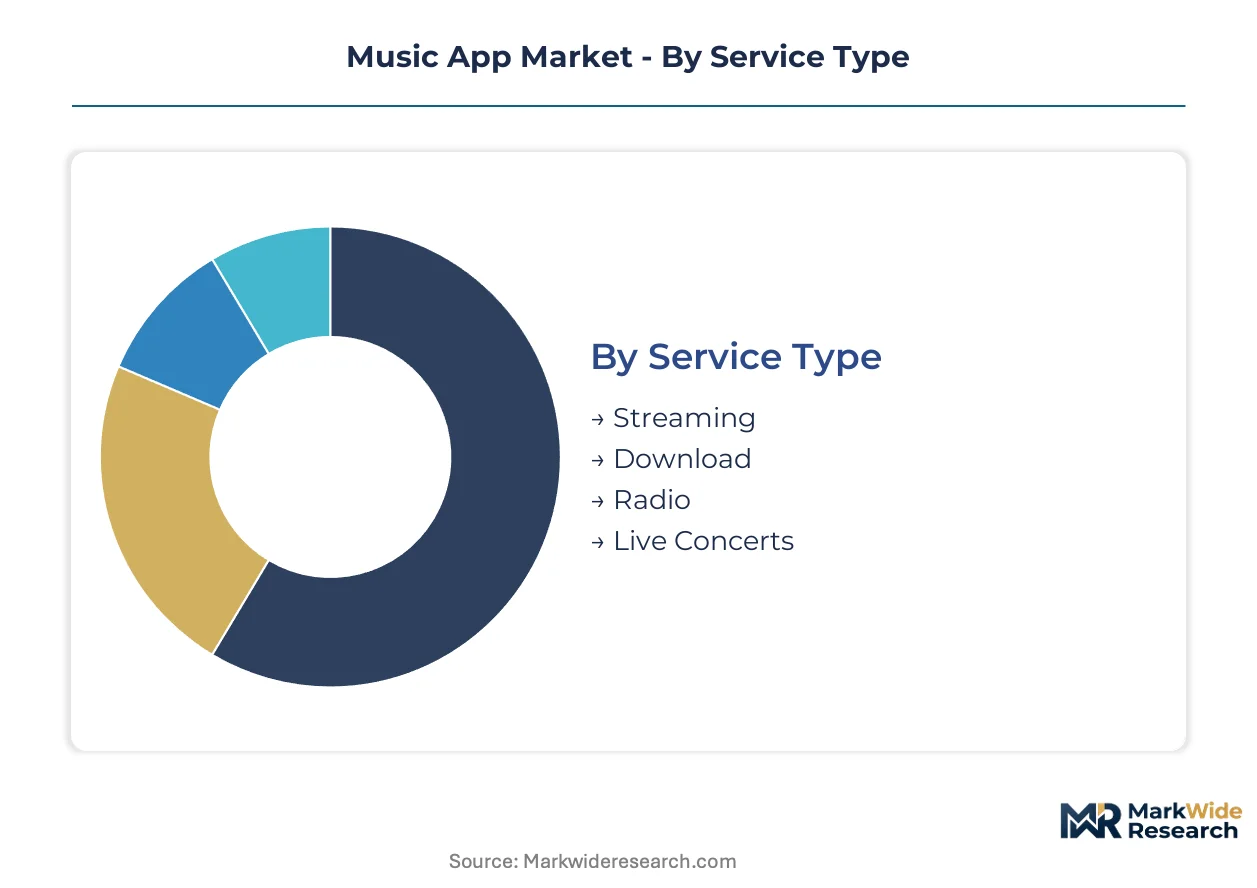
Music app segmentation reveals how platform economics fragment across consumption modes and payment willingness. Each dimension exposes distinct margin profiles and technical requirements that shape competitive positioning.
Service Type:
Standalone streaming dominates consumer mindshare while embedded audio experiences penetrate automotive and smart home ecosystems.
- Streaming:Real-time audio delivery via adaptive bitrate protocols operates between 128-320 kbps. Demand concentrates in the United States and Brazil where 5G infrastructure supports uninterrupted mobile consumption. Platforms monetize through tiered subscription gating and programmatic ad insertion.
- Download:Progressive caching enables offline playback through encrypted local storage. Demand clusters among commuters in bandwidth-constrained geographies and premium subscribers seeking ownership permanence. Rights management overhead elevates platform cost structures relative to streaming.
- Radio:Algorithmic and human-curated linear audio streams with limited skip functionality. Lean-back consumption patterns support higher ad load tolerance.
- Live Concerts:Real-time virtual performance broadcasting with integrated tipping and merchandise commerce. Social entertainment monetization models from China adapt to Latin American creator economies.
Volume placements concentrate in Streaming; the faster expansion belongs to Live Concerts.
User Type:
Cost tier differentiation separates high-ARPU households from price-sensitive single users and credential-verified academic segments.
- Individual Users:Single-account subscribers represent the baseline revenue unit across all pricing tiers. Personalization algorithms optimize for solo listening patterns without household conflict resolution.
- Families:Multi-profile household plans with parental content filtering and usage dashboards. Demand concentrates in the United States where family plan ARPU exceeds individual subscription value despite account sharing.
- Students:Credential-verified academic discount tiers with eligibility verification through enrollment databases. Platforms accept compressed margins for early habit formation and lifetime value capture.
- Professionals:Commercial licensing tiers for business background music and venue public performance rights. Compliance requirements elevate pricing above consumer tiers.
Revenue concentration sits with Individual Users; the steepest expansion trajectory belongs to Families.
Pricing Model:
Margin structure varies dramatically between recurring subscription capture and advertising-supported user acquisition economics.
- Subscription:Recurring monthly or annual billing with feature gating across audio quality and offline access. The United States and China sustain premium tier penetration above emerging market baselines.
- Freemium:Tiered onboarding funnel converting free listeners through skip limits and audio quality restrictions. Ad-supported tier economics cap per-user revenue in price-sensitive demographics.
- One-Time Purchase:Permanent digital ownership models for album downloads and permanent library access. Niche demand persists among audiophile collectors.
- Ad-Supported:Programmatic audio and display advertising insertion with limited skip functionality. Emerging market user acquisition depends on this tier despite structurally compressed ARPU.
Subscriber volume concentrates in Subscription; the fastest share gain belongs to Freemium.
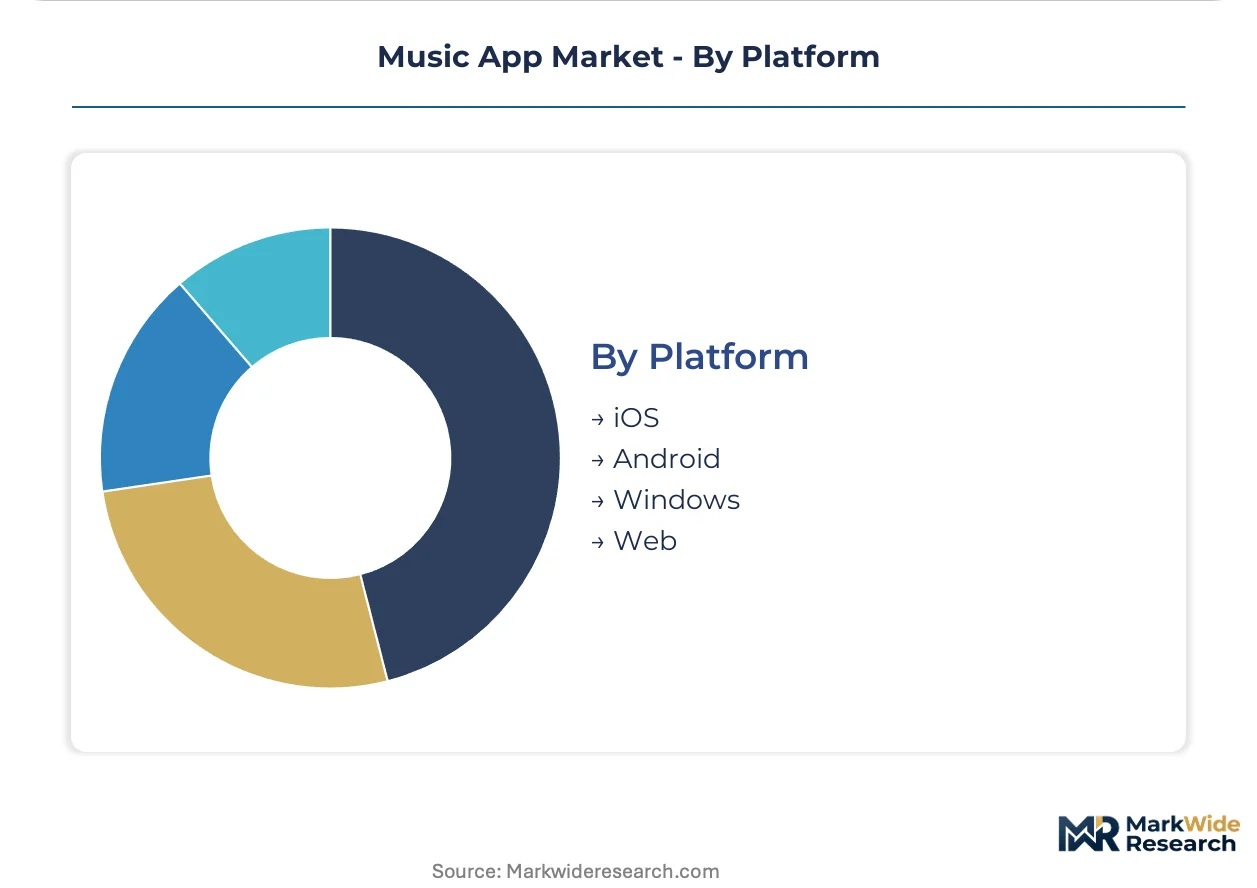
Platform:
Hardware-software integration depth separates ecosystem-captive deployments from cross-platform accessibility.
- iOS:Native applications leveraging spatial audio codec integration and hardware-software lock-in. Premium subscriber concentration exceeds Android counterparts.
- Android:Fragmented device compatibility across manufacturer-specific audio processing variations. Emerging market penetration dominates due to hardware accessibility.
- Windows:Desktop-native applications targeting professional audio production workflows and high-fidelity external DAC utilization.
- Web:Browser-based streaming without installation requirements. Corporate firewall compatibility and temporary access scenarios sustain niche utility.
User volume concentrates in Android; the fastest expansion belongs to iOS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, China, and Brazil, reflecting divergent platform monetization maturity across streaming ecosystems.
United States
Spotify and Apple Music command premium subscriber bases through podcast-to-music bundling and spatial audio codec integration. The US Copyright Royalty Board sets mechanical and performance royalty rates that strain platform cost structures during renewal cycles. Los Angeles and Nashville anchor music production clusters where independent musicians leverage creator economy distribution tools.
China
Tencent Music and NetEase dominate through social entertainment features extending into virtual gifting and live performance monetization. The National Copyright Administration establishes mechanical royalty frameworks that diverge from Western collection societies. Beijing and Shanghai concentrate AI-generated audio development labs where watermarking technology reshapes royalty attribution.
Brazil
Ad-supported tiers absorb price-sensitive user acquisition despite structurally compressed ARPU relative to North American baselines. ANVISA regulates consumer protection frameworks applicable to digital subscription billing. São Paulo anchors Latin America's creator economy expansion where localized tipping mechanics adapt Chinese social entertainment models.
Germany
GDPR algorithmic transparency mandates force recommendation engine refinement through explainable AI investments. The KBA and federal data protection authorities enforce EU AI Act documentation obligations scaling to platform revenue percentage. Berlin clusters audio technology startups developing neural synthesis tools for bedroom producers.
Japan
Spatial audio adoption concentrates among high-fidelity listeners locked into hardware-software ecosystems through premium tier gating. METI oversees digital content distribution frameworks affecting cross-border licensing negotiations. Tokyo anchors Asia-Pacific headquarters for major streaming platforms coordinating regional catalog aggregation.
Music App Market Competitive Environment
Strategic bundling dominates the current landscape as platforms diversify beyond single-format audio delivery. The vendor base organizes around three tiers: global scale operators with hundred-million subscriber bases, regional specialists capturing social entertainment monetization, and niche audiophile services differentiating through lossless codec quality. Two strategic archetypes predominate: hardware-software ecosystem integrators leveraging device lock-in, and creator economy platforms lowering distribution barriers for independent musicians. Competitive moves concentrate on podcast-to-music bundling architecture and AI training data licensing regime development.
Within the global scale tier, Spotify AB and Apple Inc. exemplify divergent ecosystem strategies. Tencent Music Entertainment Group anchors the regional specialist archetype through social entertainment feature integration. These three entities represent the dominant competitive positions without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Spotify |
| Apple Music |
| Amazon Music |
| YouTube Music |
| Tencent Music |
| NetEase |
| Tidal |
| Deezer |
| SoundCloud |
| Others |
Value Chain & Pricing Dynamics
Individual users in the United States and China concentrate subscription purchasing power, anchoring freemium-to-premium conversion economics across streaming platforms. This buyer concentration shapes tiered pricing architectures that extract maximum lifetime value from high-ARPU households while subsidizing emerging market acquisition.
Pricing Analysis
Volume concentrates in ad-supported freemium tiers while margins accrue to premium subscribers. Three-tier pricing structure across premium, standard, and economy levels segments users by audio quality, offline access, and skip functionality. Price differentiation hinges on spatial audio codec certification and household multi-profile bundling. Pricing pressure stems from mechanical royalty rate volatility set by the US Copyright Royalty Board, compressing platform margins in renewal cycles. Students and emerging market individual users exhibit highest price sensitivity; family plan subscribers in the United States show lowest elasticity.
Supply Chain Analysis
Content licensing certification from major rights holders gates platform catalog depth and geographic availability. Master recording rights concentrate in the United States, United Kingdom, and Sweden through major label headquarters and independent distributor networks. Cloud infrastructure and CDN delivery networks draw from hyperscaler capacity in the United States, Ireland, and Singapore. Supply chain risk centers on single-source vulnerability in three-label licensing concentration. Distribution runs through app store ecosystems and direct-to-consumer web channels with carrier billing integration in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
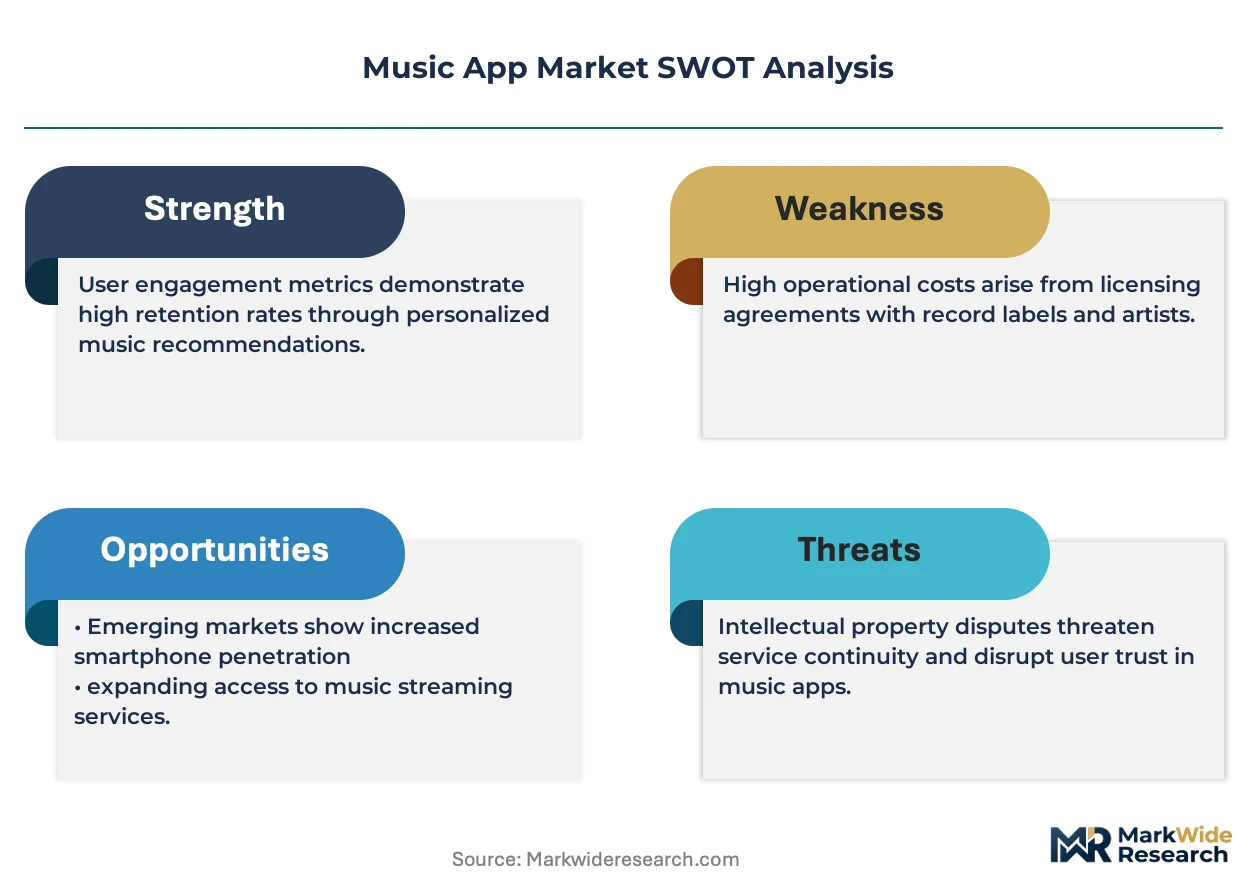
Licensed content acquisition capacity constrains platform expansion, with three-label negotiation leverage propping subscription pricing power. Mechanical royalty rate uncertainty amplifies supply-side bottlenecks.
For Market Incumbents: Deepen podcast-to-music bundling architecture to diversify retention mechanics beyond single-format loyalty. Invest in explainable AI systems to satisfy GDPR algorithmic transparency mandates and preempt EU AI Act enforcement. Acquire AI-generated audio watermarking capabilities to capture emerging training data licensing revenue streams. Consolidate spatial audio codec integration to reinforce hardware-software ecosystem lock-in against Android-based challengers. For New Entrants and Emerging Players: Independent musicians and podcast creators represent the most penetrable creator segment, underserved by major platform A&R overhead. Target Brazil's social entertainment monetization gap with localized virtual gifting mechanics adapted from Chinese models. Pursue white-label B2B licensing for commercial background music in hospitality and retail verticals. Partner with telecom carriers in bandwidth-constrained geographies to bundle zero-rated streaming tiers. For Investors and Strategic Acquirers: The window for entry favors creator economy infrastructure specialists with proprietary distribution tools and direct artist relationships. Long-term viability hinges on capturing recurring revenue from AI training data licensing rather than per-stream royalty arbitrage. Monitor US Copyright Royalty Board proceedings as the critical inflection signal for platform cost structure compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Training Data Licensing Framework | Structured rights-clearance from copyrighted catalogs generates recurring revenue from generative model developers. |
| Spatial Audio Codec Integration | Object-based immersive formats differentiate premium tiers and lock high-fidelity listeners into ecosystem-specific hardware. |
| Podcast-to-Music Bundling Architecture | Cross-category content convergence reduces subscriber churn through diversified consumption patterns. |
| Social Entertainment Localization | Virtual gifting mechanics adapted to Brazil's creator-fan relationships unlock Latin American monetization. |
| Explainable AI Investment | Algorithmic transparency documentation satisfies EU AI Act obligations and improves discovery precision. |
Study Parameters
Independent corroboration across streaming platform executives, independent musician collectives, and performing rights organization administrators underwrites the qualitative findings. Primary fieldwork engaged platform monetization leads, label licensing directors, podcast network operators, and regulatory affairs specialists across the United States, China, Germany, and Brazil. Secondary validation drew from SEC filings, EU regulatory submissions, copyright board dockets, and app store revenue disclosures. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from trade associations and national copyright administrations.
Comparable-period anchoring linked historical streaming adoption curves to current penetration baselines across the analysis window. Segmentation modeling spanned service type, user archetype, pricing tier, and platform ecosystem dimensions. CAGRs derived from subscriber growth trajectories, ARPU evolution, and content cost inflation assumptions. Industry-specific inputs included mechanical royalty rate proceedings, 5G infrastructure deployment timelines, and creator economy platform upload velocity metrics.
Caveats apply where US Copyright Royalty Board rate adjustments, EU AI Act enforcement intensity, or generative audio copyright litigation could materially shift the outlook. Forecasts reflect assumptions around freemium conversion rates and emerging market payment infrastructure maturation. A model refresh is warranted upon material change in three-label licensing negotiation outcomes or AI training data regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Virtual Musical Instruments Market
Music
Global Background Music Market
Music
Independent Music Publishing Market
Music
Global in-Store Music Service Market
Music
Music Production Software Market
Music
United States Live Music Market
Music
Music Distribution Services Market
Music
Europe Independent Artist Market
Music
Electronic Dance Music (EDM) Market
Music
Vinyl Records Market
Music
Music Publishing Market
Music
Global Free Music Making Software Market
Music
Musical Groups and Artists Market
Music
Traditional Music Market
Music
Discography Market
Music
Global Stock Music Market