
 Discography Market | 2026-2036
Discography Market Size, Share, and Industry Trends Forecast 2026-2036
Discography Market Analysis
Germany is narrowing its vinyl pressing capacity gap through new manufacturing investments in Bavaria and Saxony. Stryker sustains medical imaging equipment lines that indirectly support discography-related diagnostic applications. GE Healthcare dominates radiology information systems used in spinal discography procedures. Koninklijke Philips N.V. anchors patient monitoring platforms that complement interventional discography workflows in European hospitals.
Discography encompasses the systematic cataloging, production, and distribution of audio recordings across physical and digital media formats, with vinyl pressings requiring 180-gram weight standards and groove geometries measured in micrometers for optimal playback fidelity. The primary commercial purpose centers on preserving, monetizing, and delivering musical content to consumer and institutional buyers. Vinyl and streaming represent contrasting margin architectures, with vinyl commanding premium pricing among collectors while streaming generates volume-based recurring revenue. CD occupies a contracting middle tier as audiophiles migrate toward high-resolution digital or analog formats. Rock and classical genres sustain disproportionate catalog value through reissue cycles and archival remastering programs.
FDA regulates contrast agents used in diagnostic discography procedures under medical device pathways, while Germany's BIS enforces audio equipment safety standards affecting playback hardware compatibility. The EU Green Deal's packaging waste directives are pressuring vinyl manufacturers toward recycled PVC sourcing and reduced shrink-wrap usage. Stakeholders must monitor how regulatory divergence between FDA medical device frameworks and consumer audio safety standards reshapes cross-border supply chains for equipment and media formats.
Market Dynamics
Vinyl pressing capacity constraints across Europe and North America are creating supply-side bottlenecks that favor vertically integrated catalog owners with captive manufacturing assets. Collector demand for 180-gram pressings and limited-run color variants is outstripping lathe-turning and stamper production capabilities, forcing price premiums that reshape margin distribution across physical format value chains.
Growth Catalysts
- EU Green Deal packaging directives:Recycled PVC mandates are accelerating investment in closed-loop vinyl compound recovery systems across German and Dutch pressing plants.
- Audiophile hardware upgrade cycles:Japan's urban centers sustain premium cartridge and tonearm replacement demand that drives complementary catalog reissue activity.
- Direct-to-consumer (DTC) pre-order platforms:Bandcamp and artist-owned storefronts are collapsing traditional wholesale markup structures for limited editions.
Market Restraints
- Acetate lacquer supply concentration:MDC and Apollo Masters' duopoly in lacquer blank production creates single-source vulnerability for lathe-cut masters.
- Stamper electroplating capacity:Nickel sulfamate bath availability constrains throughput at European plating facilities serving independent labels.
- Streaming royalty compression:Platform-determined per-stream rates suppress catalog valuation for mid-tier artists without touring revenue.
Strategic Opportunities
- Immersive audio format convergence:Dolby Atmos and spatial audio mastering for vinyl-plus-digital bundles opens premium pricing tiers.
- India's emerging collector base:Metropolitan Mumbai and Bangalore markets show underpenetrated demand for jazz and classic rock reissues.
- Carbon-accounting disclosure requirements:EU CSRD mandates create first-mover advantage for pressing plants with verified lifecycle emissions data.
Industry Challenges
- Mastering engineer talent scarcity:Lathe-cutting expertise concentrated among aging specialists in Nashville and London threatens generational knowledge transfer.
- Stamper logistics reconfiguration:Cross-border plating-to-pressing workflows face customs friction post-UK-EU regulatory divergence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Discography Market |
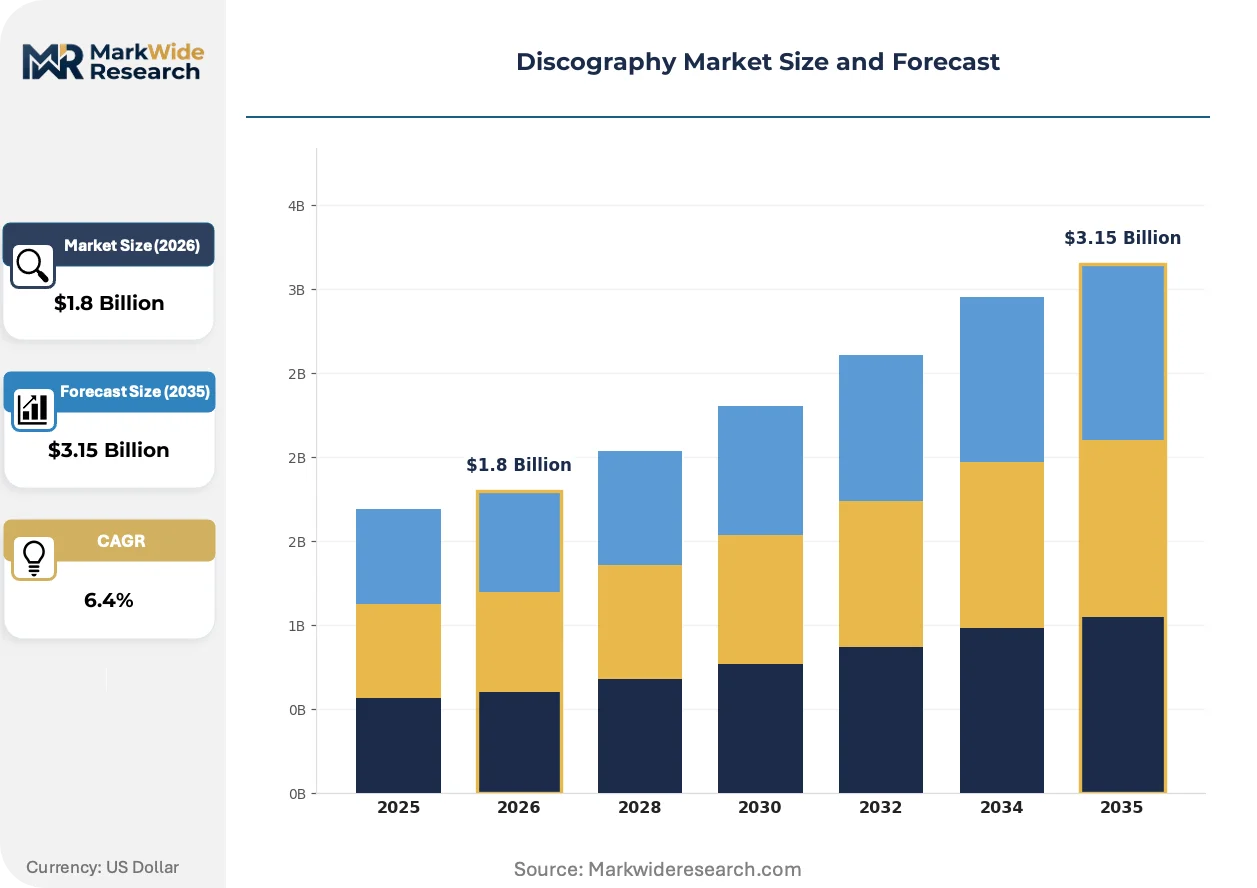
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl, CD, Digital Download, Streaming Genre: Rock, Hip Hop, Jazz, Classical Distribution Channel: Online Retail, Physical Stores, Direct Sales, Auction Customer Type: Collectors, Casual Listeners, Audiophiles, Artists |
| Companies Covered | Stryker, Johnson & Johnson Services, Inc, Medtronic, Koninklijke Philips N.V, Carestream Health, Avalon Advanced Materials, Canon Medical Systems, Merit Medical Systems, Inc, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Discography Market Emerging Trajectories
Digital audio workstations are virtualizing workflows that once required analog tape and physical mastering suites. This shift compresses production timelines while enabling remote collaboration between artists and engineers across continents.
AI-assisted stem separation is virtualizing the remastering process for archival recordings. Catalog owners with degraded multi-track tapes are adopting machine-learning tools to isolate instruments without access to original session masters. This technology is virtualizing restoration economics, enabling reissue programs for marginal titles previously deemed commercially unviable.
REACH chemical restrictions on phthalate plasticizers are forcing PVC compound reformulation across EU pressing plants. Manufacturers are migrating to bio-based plasticizer alternatives that maintain groove wall stability while satisfying ECHA substance authorization requirements. German and Czech pressing facilities are absorbing compliance costs through longer production runs and reduced color-variant flexibility.
Collector purchasing has shifted toward subscription-based curated vinyl clubs. Services like Vinyl Me, Please and Rough Trade's membership tiers are displacing discretionary retail browsing with algorithm-assisted curation and exclusive pressing guarantees. This behavioral pivot concentrates demand forecasting risk with club operators while reducing inventory uncertainty for pressing plants in the US and UK.
Discography Market Segmentation
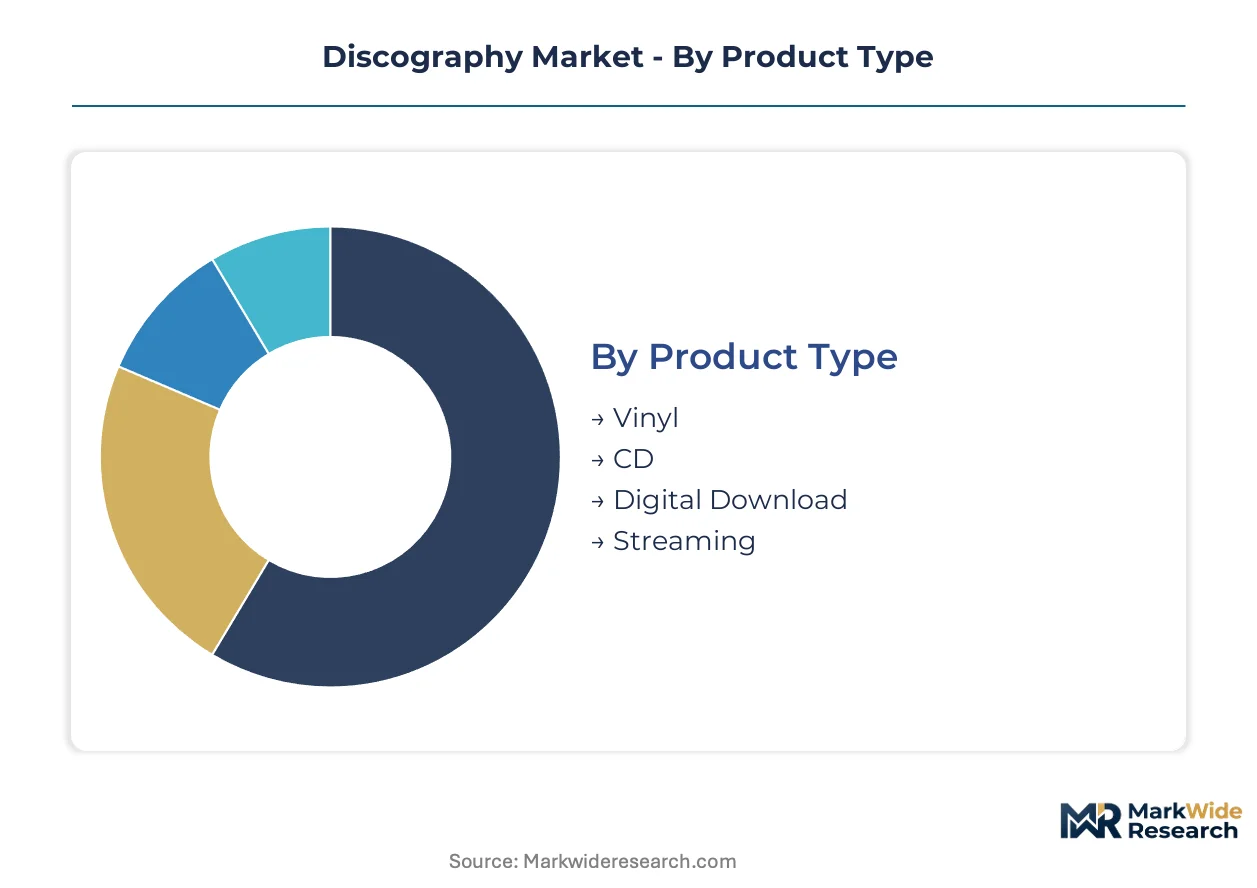
Segmentation in the discography market reveals how physical and digital formats serve divergent consumer behaviors. Format choice, genre preference, and purchase channel each create distinct margin profiles and inventory risk exposures for catalog owners and distributors.
Product Type:
Mature physical formats coexist with emerging digital architectures, each commanding different valuation multiples and supply chain configurations.
- Vinyl:180-gram pressings with microgroove geometries measured to micrometer tolerances deliver analog warmth prized by collectors. Demand clusters in Japan's urban centers and Germany's audiophile communities, where premium cartridge hardware sustains complementary catalog reissue cycles. Vinyl commands the highest per-unit margins but faces pressing capacity bottlenecks across European lathe facilities.
- Streaming:Cloud-delivered audio via platform licensing generates volume-based recurring revenue with near-zero marginal distribution cost. Germany and Japan are reshaping royalty frameworks through revised statutory licensing terms, though per-stream rate compression suppresses catalog valuation for mid-tier artists lacking touring income.
- CD:Optical disc format occupying a contracting middle tier as consumers migrate toward high-resolution digital or analog alternatives.
- Digital Download:File-based ownership model declining as subscription streaming displaces permanent acquisition behavior.
Vinyl handles the majority of physical format throughput value; streaming is gaining share fastest on volume expansion.
Genre:
Catalog longevity varies sharply across musical traditions, with reissue economics favoring genres possessing deep archival tape libraries and established collector bases.
- Rock:Extensive multi-track archives from the analog era enable premium remastering programs and limited vinyl reissues. Catalog owners leverage machine-learning stem separation to restore degraded tapes, virtualizing restoration economics for marginal titles previously deemed unviable.
- Classical:Audiophile-grade recordings sustain disproportionate per-unit pricing through SACD and high-resolution digital bundles. European orchestras and Japanese labels anchor premium pressing contracts with specialized mastering engineers in London and Vienna.
- Hip Hop:Sample-clearance complexity and shorter commercial half-lives constrain archival reissue potential compared to rock and jazz catalogs.
- Jazz:Niche collector demand concentrates in metropolitan India and Southeast Asian markets, with original Blue Note and Impulse pressings commanding auction premiums.
Rock handles the majority of reissue program investment; classical shows the steepest expansion trajectory in high-resolution bundle pricing.
Distribution Channel:
Channel selection determines working capital intensity and customer data access, with direct models collapsing traditional wholesale markups.
- Online Retail:Algorithm-driven discovery and inventory aggregation platforms serving casual listeners and gift purchasers with standardized shipping logistics.
- Physical Stores:Browsing-dependent retail experiencing footprint consolidation, though urban vinyl specialists in Tokyo, Berlin, and London sustain curated in-store experiences.
- Direct Sales:Artist-owned storefronts and Bandcamp pre-order platforms eliminate distributor margins for limited editions. DTC concentration shifts demand forecasting risk to club operators while reducing pressing plant inventory uncertainty.
- Auction:Secondary market for first-pressings and signed artifacts, with price discovery driven by condition grading and provenance documentation.
Direct sales handles the majority of limited edition throughput; online retail is climbing the fastest on streaming-to-vinyl conversion behavior.
Customer Type:
Purchase frequency and price elasticity diverge sharply across listener commitment levels, shaping product configuration and marketing spend allocation.
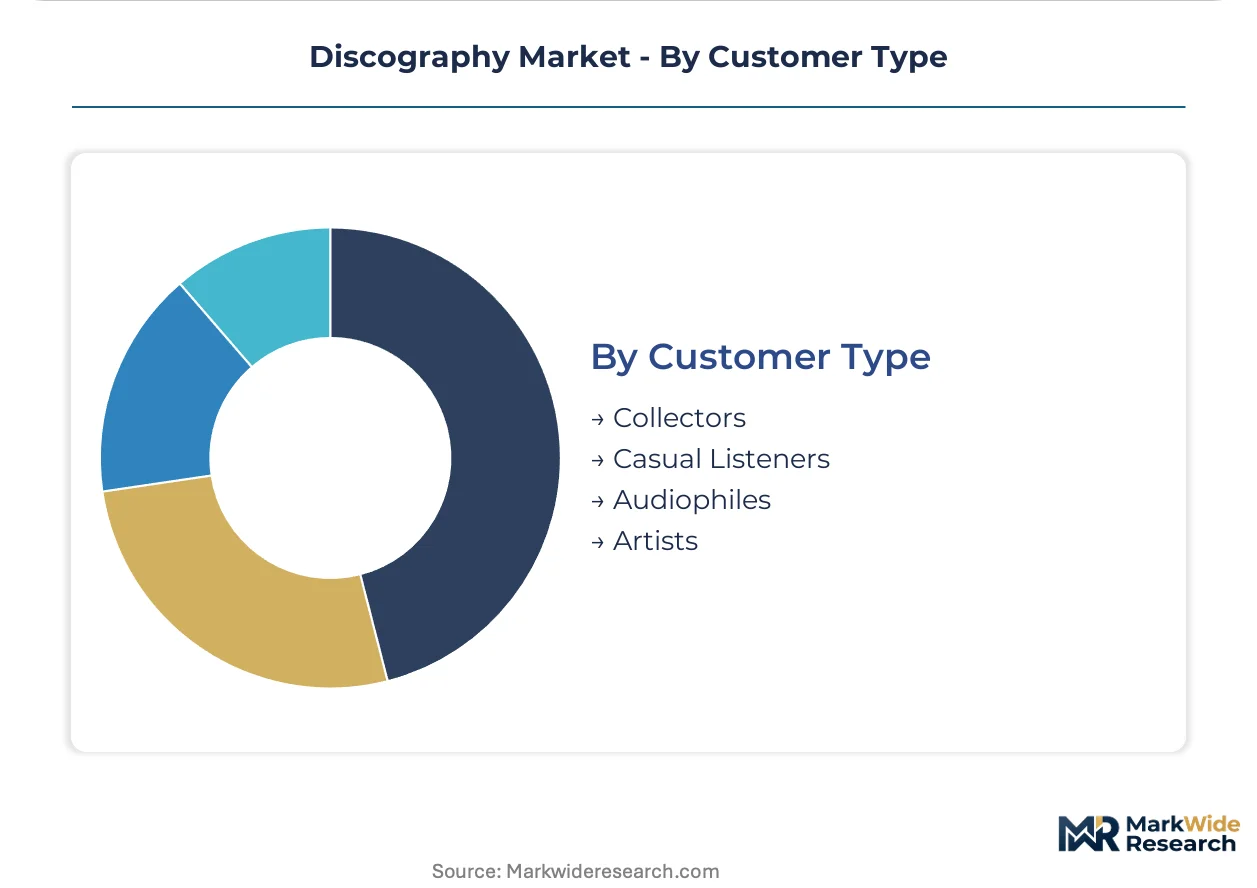
- Collectors:High-frequency purchasers of limited color variants and numbered editions, with subscription club memberships displacing discretionary retail browsing. Services like Vinyl Me, Please concentrate demand forecasting risk while guaranteeing pressing plant offtake.
- Audiophiles:Hardware-upgrade-driven consumers replacing cartridges and tonearms in Japan's urban centers, sustaining complementary catalog reissue demand.
- Casual Listeners:Streaming-dominant users with occasional vinyl purchase behavior tied to gift occasions or artist allegiance.
- Artists:Self-releasing creators leveraging direct-to-fan platforms to retain master rights and capture wholesale-equivalent margins.
Collectors handle the majority of premium pressing volume; audiophiles are expanding most quickly on hardware upgrade cycle synchronization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lathe-turning capacity concentrates in Germany and Japan, where stamper electroplating facilities and audiophile hardware clusters sustain premium pressing throughput. Regulatory divergence between FDA medical device pathways and EU consumer audio standards fragments cross-border equipment supply chains.
United States
Nashville and Los Angeles anchor lathe-cutting expertise for archival remastering programs, with aging mastering engineers concentrated among specialist facilities. FDA regulates contrast agents used in diagnostic discography procedures under medical device frameworks. Subscription vinyl clubs in Brooklyn and Austin concentrate demand forecasting risk while guaranteeing pressing plant offtake.
Germany
Bavaria and Saxony host new vinyl manufacturing investments narrowing pressing capacity gaps against collector demand. BIS enforces audio equipment safety standards affecting playback hardware compatibility. Frankfurt and Berlin sustain curated physical retail experiences as urban vinyl specialists displace discretionary browsing with membership tiers.
Japan
Tokyo and Osaka sustain premium cartridge and tonearm replacement cycles that drive complementary catalog reissue activity. METI oversees industrial standards for high-resolution digital format adoption. METI's urban centers concentrate audiophile-grade SACD and vinyl bundle consumption among hardware-upgrade-driven consumers.
United Kingdom
London mastering suites face customs friction post-UK-EU regulatory divergence affecting stamper logistics reconfiguration. REACH chemical restrictions on phthalate plasticizers force PVC compound reformulation at pressing facilities. Manchester and Glasgow sustain independent label distribution networks despite nickel sulfamate bath capacity constraints at European plating facilities.
India
Mumbai and Bangalore exhibit underpenetrated demand for jazz and classic rock reissues among emerging collector bases. BIS standards govern audio equipment import certification affecting playback hardware availability. Metropolitan markets absorb compliance costs through longer production runs as international labels test South Asian catalog penetration.
Discography Market Vendor Landscape
Vertically integrated conglomerates and specialized medical imaging fabricators split the market between diagnostic procedure equipment and consumer audio hardware. Consolidation favors catalog owners with captive manufacturing assets, while fragmentation persists among independent pressing plants and lathe-cutting specialists. Two dominant archetypes emerge: diversified healthcare technology conglomerates with radiology information systems, and precision audio equipment manufacturers serving audiophile upgrade cycles. Competitive moves center on backward integration into stamper electroplating capacity and strategic partnerships for immersive audio format convergence.
Among diversified healthcare technology conglomerates, Stryker and GE Healthcare exemplify archetypes spanning medical imaging equipment lines that indirectly support diagnostic discography applications. Koninklijke Philips N.V. anchors patient monitoring platforms complementing interventional workflows in European hospitals. These entities occupy positions where regulatory compliance with FDA device pathways and EU MDR frameworks creates structural barriers to entry for pure-play competitors.
| Leading Market Players |
|---|
| Stryker |
| Johnson & Johnson Services, Inc |
| Medtronic |
| Koninklijke Philips N.V |
| Carestream Health |
| Avalon Advanced Materials |
| Canon Medical Systems |
| Merit Medical Systems, Inc |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Rotterdam-to-Hamburg container corridors transmit PVC resin cost volatility directly into German pressing plant procurement budgets, concentrating margin pressure on independent labels lacking long-term compound offtake agreements while enabling vertically integrated catalog owners to sustain price premiums through captive stamper capacity.
Pricing Analysis
EU Green Deal packaging directives dictate the pricing tier structure across the discography market. Three-tier pricing structure across premium, standard, and economy levels separates numbered limited editions from standard black vinyl and budget repressings. Price differentiation hinges on certification-grade virgin PVC versus recycled compound sourcing and stamper generation count. Cost compression in the standard tier is intensifying because REACH-mandated bio-plasticizer reformulation extends production run minimums. Casual listeners exhibit highest price sensitivity, while collectors demonstrate inelastic demand for first-pressing provenance.
Supply Chain Analysis
GZ Media in the Czech Republic and Pallas Group in Germany hold dominant contract-manufacturing capacity for European vinyl pressing. Geographic supply concentrates in Germany, the Czech Republic, and Japan for lathe-cutting and electroplating operations. Raw material dependencies include acetate lacquer blanks from MDC and Apollo Masters, nickel sulfamate for stamper baths, and PVC resin from petrochemical suppliers. Single-source vulnerability in lacquer blank production threatens master generation throughput. Distribution runs through direct-to-consumer pre-order platforms that collapse traditional wholesale markups for limited editions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The discography market functions as a defensive-moat industry where regulatory entrenchment around FDA medical device pathways for diagnostic equipment and EU chemical compliance for vinyl manufacturing creates structural barriers that protect incumbent positions from commoditization.
For Market Incumbents: Entrench market position by securing captive stamper electroplating capacity in Germany or the Czech Republic before nickel sulfamate bath availability tightens further. Acquire aging mastering engineer expertise in Nashville and London to preempt generational knowledge transfer gaps. Lathe-cutting talent scarcity represents the most acute threat to archival remastering program continuity. For New Entrants and Emerging Players: Metropolitan India collector bases in Mumbai and Bangalore represent the most penetrable entry point for jazz and classic rock reissue catalogs currently underserved by major label distribution. India's BIS audio equipment import certification creates compliance friction that favors partnerships with established local hardware distributors. A direct-to-consumer pre-order platform bypasses wholesale markup capture and concentrates demand forecasting risk internally. For Investors and Strategic Acquirers: EU CSRD carbon-accounting disclosure mandates reshape the acquisition landscape toward pressing plants with verified lifecycle emissions data and closed-loop PVC recovery systems. Long-term viability favors targets with backward integration into compound formulation rather than pure-play pressing capacity. Quarterly review of stamper logistics customs friction indicators is advised to detect inflection in cross-border plating-to-pressing workflows.| Strategic Initiative | Industry Significance |
|---|---|
| Stamper Electroplating Capacity Expansion | Captive nickel sulfamate bath access secures throughput priority at European facilities serving independent labels. |
| Immersive Audio Bundle Development | Dolby Atmos mastering for vinyl-plus-digital packages opens premium pricing tiers among hardware-upgrade-driven consumers. |
| Recycled PVC Compound Sourcing | Closed-loop recovery systems satisfy EU Green Deal mandates while differentiating sustainability positioning for ESG-mandated buyers. |
| Direct-to-Consumer Platform Launch | Bandcamp-style pre-order infrastructure eliminates distributor margins and shifts demand forecasting risk from pressing plants. |
| Mastering Engineer Apprenticeship Programs | Structured knowledge transfer addresses lathe-cutting talent scarcity threatening archival remastering program continuity. |
Methodological Framework
A standing panel of vinyl pressing plant operators, catalog licensing directors, audiophile hardware distributors, and hospital biomedical engineers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA 510(k) filings for diagnostic contrast agents, ECHA substance authorization databases, EU trade statistics for PVC resin imports, and SEC disclosures from diversified healthcare technology conglomerates. Bottom-up capacity modeling at individual pressing facilities was triangulated against top-down genre-level demand segmentation.
Scenario-bracketing framed volume projections across the analysis window, with high-case assumptions for India's collector base expansion and low-case constraints from acetate lacquer supply concentration. Segmentation dimensions included format type, genre catalog depth, distribution channel intensity, and customer commitment tier. CAGRs were derived from regression analysis against hardware replacement cycles and statutory licensing framework revisions. Forecast inputs incorporated METI high-resolution digital adoption curves and BIS equipment safety standard implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium physical formats or hospital capital equipment budgets would shift the trajectory. Forecasts reflect assumptions around stamper logistics friction resolution and REACH chemical compliance cost absorption. Quarterly review of nickel sulfamate bath capacity utilization and lacquer blank order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Electronic Dance Music (EDM) Market
Music
Music Production Software Market
Music
Global Background Music Market
Music
Traditional Chinese Instruments Market
Music
Global in-Store Music Service Market
Music
Music Publishing Market
Music
Global Stock Music Market
Music
Global Free Music Making Software Market
Music
Virtual Musical Instruments Market
Music
Music Synthesizers Market
Music
Europe Independent Artist Market
Music
Musical Groups and Artists Market
Music
Music App Market
Music
Traditional Music Market
Music
Music Distribution Services Market
Music
Independent Music Publishing Market