
 Music Synthesizers Market | 2026-2036
Music Synthesizers Market Size, Share, and Industry Trends Forecast 2026-2036
Music Synthesizers Market Outlook
REACH compliance is broadening the cost-of-entry calculus for European synthesizer manufacturers by restricting certain flame retardants and plasticizers in electronic enclosures. Moog Music Inc. leverages its vertically integrated domestic manufacturing to navigate material substitution requirements without disrupting legacy product lines. Roland Corporation anchors its competitive position through deep R&D investment in low-power DSP architectures that preempt regulatory thresholds. Yamaha Corporation dominates professional keyboard synthesis through channel control across Japanese music retailers and North American direct-to-consumer platforms.
Music synthesizers are electronic instruments that generate audio signals through controlled voltage oscillators, digital signal processors, or software algorithms, typically operating across 20 Hz to 20 kHz frequency ranges with polyphony counts from 4 to 128 voices, designed for composition, performance, and sound design in commercial and artistic settings. Analog synthesizers occupy the premium tier where component scarcity and hand-calibrated circuitry sustain margin pools despite constrained production volumes. Software synthesizers are capturing share fastest among independent producers who prioritize portability and DAW integration over hardware ownership. Educational institutions represent an emerging demand node as university music technology programs expand enrollment and require institutional procurement of subtractive and FM synthesis platforms.
The EU's Ecodesign Directive and RoHS framework constrain material choices and standby power profiles for synthesizers sold across member states, while the FCC's Part 15 emissions standards govern electromagnetic compatibility for all electronic instruments marketed in the United States. Japan's METI enforces Top Runner standards that progressively tighten energy efficiency benchmarks for consumer electronics including musical instruments. Stakeholders must monitor whether emerging right-to-repair legislation in multiple jurisdictions forces design changes to modular architectures and firmware accessibility.
Market Dynamics
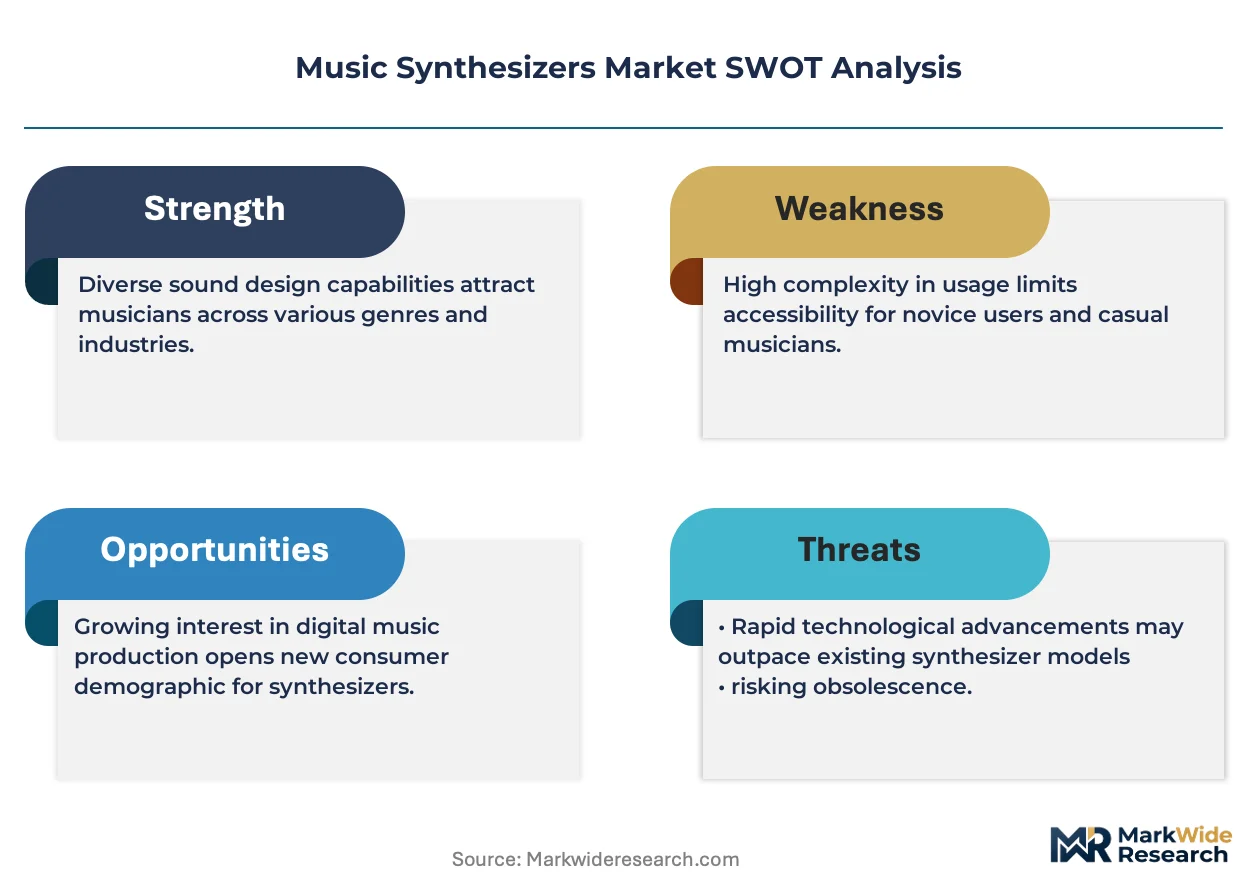
The music synthesizers market is experiencing a fundamental tension between analog scarcity economics and digital democratization, as boutique component shortages sustain premium hardware margins while software emulation compresses entry barriers for independent producers.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits for energy-related products are accelerating hardware refresh cycles in German electronic music production studios.
- University music technology programs:Institutional procurement of subtractive and FM synthesis platforms is expanding enrollment-driven demand across North American and European higher education.
- Tokyo's dense retailer network:Japan's concentration of electronic instrument retailers and live performance venues sustains premium analog synthesizer sales velocity unmatched elsewhere.
Market Restraints
- Discrete component scarcity:Voltage-controlled oscillators and matched transistor pairs face allocation constraints from specialty semiconductor foundries.
- REACH compliance costs:Flame retardant and plasticizer restrictions in electronic enclosures broaden cost-of-entry calculus for European manufacturers.
- Software substitution:DAW-integrated virtual instruments displace hardware purchases among portability-prioritizing independent producers.
Strategic Opportunities
- Educational institutional procurement:University music technology programs represent underpenetrated demand nodes requiring subtractive and FM synthesis platforms.
- Right-to-repair legislation:Emerging firmware accessibility mandates in multiple jurisdictions create openings for modular architecture specialists.
- Low-power DSP convergence:Integration of energy-efficient digital signal processing with analog signal paths addresses regulatory thresholds while preserving tonal character.
Industry Challenges
- Analog circuit calibration expertise:Hand-tuning voltage-controlled filters and envelope generators requires specialized technician skills in diminishing supply.
- Material certification timelines:REACH-substituted enclosure compounds demand extended validation cycles before production ramp.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Synthesizers Market |
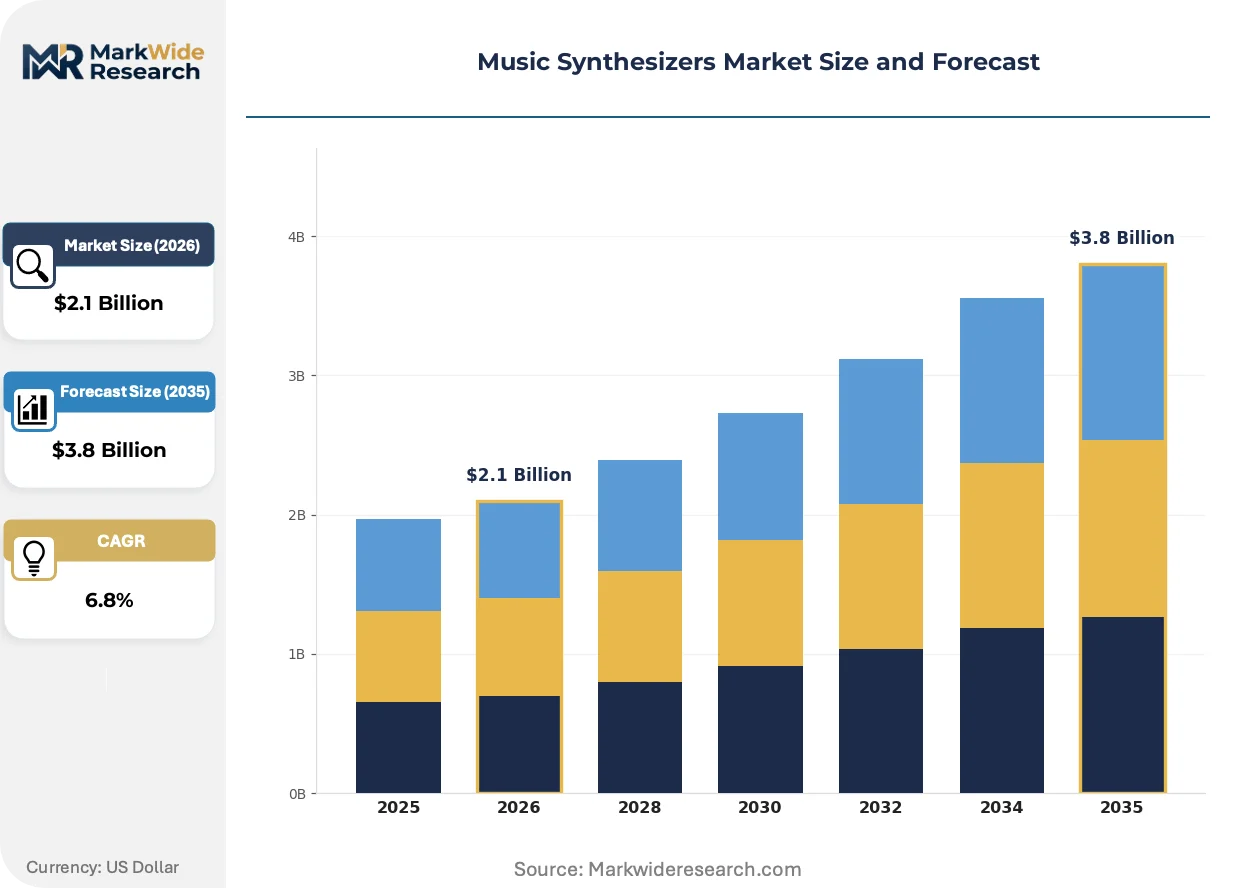
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Synthesizers, Digital Synthesizers, Modular Synthesizers, Software Synthesizers End User: Musicians, Sound Designers, Composers, Educational Institutions Technology: Subtractive Synthesis, Additive Synthesis, FM Synthesis, Granular Synthesis Distribution Channel: Online Retailers, Music Stores, Direct Sales, Distributors |
| Companies Covered | Moog Music Inc., Arturia, Yamaha Corporation, inMusic, Inc., Behringer, Roland Corporation, Casio Computer Co., Ltd., Native Instruments GmbH, Korg Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Synthesizers Market Strategic Shifts
Generative algorithm integration is compressing traditional sound design workflows, while regulatory pressure on standby power and material composition forces hardware architecture reinvention across all price tiers.
AI-assisted patch generation is automating timbral exploration for producers who previously relied on manual parameter twiddling. Bedroom studios and independent electronic musicians are adopting these tools fastest, drawn by immediate DAW integration. This capability is automating the sound design labor that once differentiated professional synthesists from amateurs, compressing the value of traditional programming expertise.
Japan's METI Top Runner standards are progressively tightening energy efficiency benchmarks for consumer electronics including musical instruments. Manufacturers must now engineer low-power DSP architectures that preempt regulatory thresholds before they become mandatory. Professional keyboard synthesis lines face the steepest redesign requirements, as these products combine the highest voice counts with the longest typical usage sessions.
Direct-to-consumer platforms are disintermediating traditional music retailer networks that once controlled synthesizer distribution. North American buyers increasingly research and purchase hardware through manufacturer websites and specialized online communities, bypassing brick-and-mortar showrooms. This channel shift is most visible in modular synthesizer segments, where component-level purchases favor detailed technical documentation over in-person demonstration.
Music Synthesizers Market Segmentation
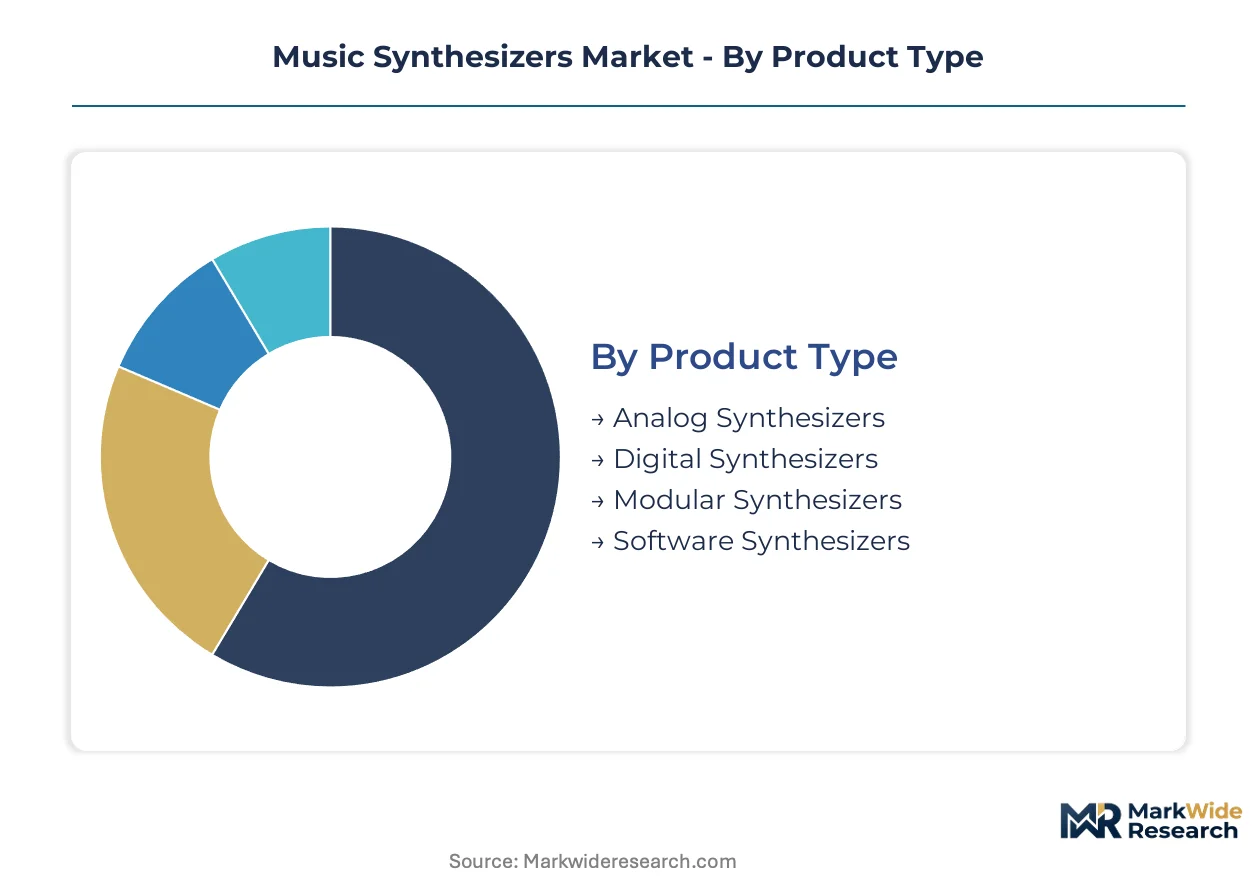
Synthesizer segmentation reveals divergent margin structures across hardware and software paradigms. Voltage-controlled architectures command premium pricing through component scarcity, while algorithmic platforms scale without physical constraints. Understanding these tiered economics guides resource allocation across R&D portfolios and channel investments.
Product Type:
Customization intensity spans from hand-calibrated analog circuits to mass-deployed software licenses, with hardware occupying the premium tier and code-based solutions driving volume penetration.
- Analog Synthesizers:Voltage-controlled oscillators and filters built from discrete components deliver harmonically rich timbres through continuous signal paths. Demand concentrates in Japan's Tokyo-Osaka corridor where collector culture and live performance traditions sustain premium pricing despite constrained production volumes. Matched transistor pairs and rare capacitors face allocation pressure from specialty semiconductor foundries.
- Software Synthesizers:Algorithmic sound generation runs as plug-ins within digital audio workstations, eliminating hardware ownership barriers. Independent producers across Germany's electronic music studios adopt these platforms fastest, prioritizing portability and DAW integration over physical instrument investment. Zero marginal replication costs enable aggressive pricing against hardware alternatives.
- Digital Synthesizers:Fixed-architecture hardware employing digital signal processors for wavetable and sample-based synthesis occupies the mid-market tier.
- Modular Synthesizers:User-configurable systems of discrete function modules—oscillators, filters, envelopes—demand technical literacy and reward experimental signal routing.
Leading the category by volume: Software Synthesizers. Growing fastest: Modular Synthesizers.
End User:
Customer sophistication ranges from institutional procurement committees to individual creators optimizing personal workflows, with divergent purchasing criteria across these poles.
- Musicians:Live performers and studio recording artists prioritize tactile interface reliability and sonic immediacy. Tokyo's dense network of electronic instrument retailers sustains hands-on evaluation culture unmatched elsewhere, with performers testing polyphony response and envelope character before purchase.
- Educational Institutions:University music technology programs require subtractive and FM synthesis platforms for curriculum delivery. North American higher education procurement is expanding enrollment-driven demand, with institutional buyers negotiating site licenses and maintenance agreements absent from consumer transactions.
- Sound Designers:Film, game, and media professionals seek spectral manipulation depth and automation compatibility.
- Composers:Orchestral and electronic score creators demand integrated sequencing and expansive patch libraries.
Dominating procurement value: Educational Institutions. Expanding most quickly: Sound Designers.
Technology:
Signal generation architectures differ fundamentally in computational requirements and timbral results, shaping hardware-software allocation decisions.
- Subtractive Synthesis:Filtering harmonically rich waveforms to sculpt timbre remains the pedagogical foundation and performance standard. German electronic music production studios anchor demand for voltage-controlled implementations, with the EU's Ecodesign Directive tightening standby power limits and accelerating hardware refresh cycles toward efficient digital emulations.
- FM Synthesis:Frequency modulation of one oscillator by another creates complex spectra from minimal computational resources. Yamaha Corporation's historical dominance in professional keyboard synthesis stems from deep R&D investment in low-power DSP architectures that preempt regulatory thresholds while preserving signature timbral character.
- Additive Synthesis:Summing sine wave partials to construct waveforms demands substantial processing power for real-time operation.
- Granular Synthesis:Microsound sample manipulation generates evolving textures through time-stretching and cloud formation algorithms.
Installed base leader: Subtractive Synthesis. Gaining share fastest: Granular Synthesis.
Distribution Channel:
Channel economics reflect the tension between technical consultation requirements and price transparency preferences across customer segments.
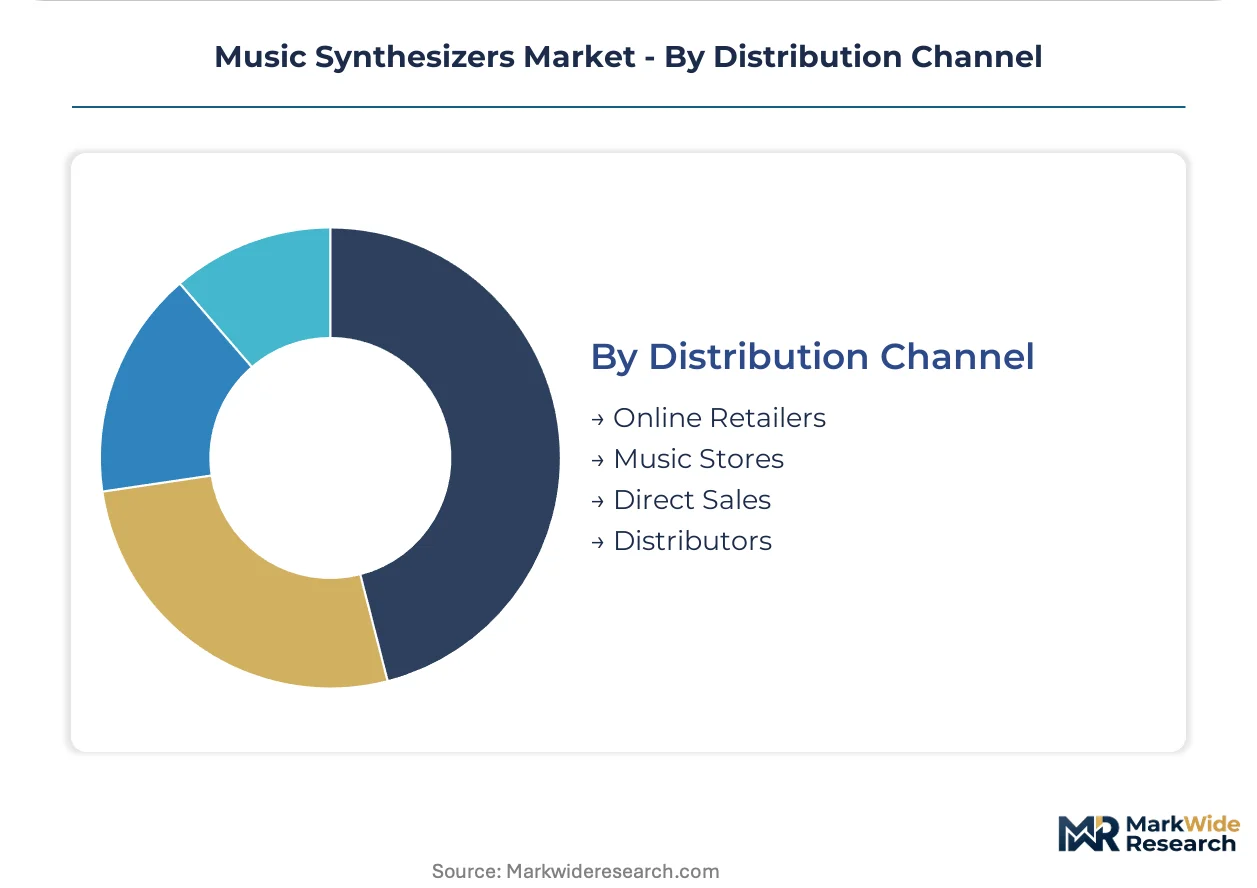
- Music Stores:Brick-and-mortar showrooms enable tactile evaluation of keybed action, knob torque, and display visibility. Japan's metropolitan retailer networks sustain this channel through cultural attachment to in-person instrument selection, particularly for analog synthesizers where component variance demands individual audition.
- Online Retailers:Specialized e-commerce platforms and generalist marketplaces disintermediate traditional distribution, favoring standardized products with comprehensive documentation. North American direct-to-consumer platforms are capturing modular synthesizer segments where component-level purchases reward detailed technical specifications over demonstration.
- Direct Sales:Manufacturer-controlled channels capture margin and customer data, particularly for premium tier releases.
- Distributors:Regional intermediaries manage logistics and localization for mid-market brands lacking captive infrastructure.
Highest transaction volume: Online Retailers. Steepest expansion trajectory: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's designation of electronic musical instruments under METI Top Runner standards has concentrated manufacturing investment in Kanto prefecture special zones. Germany's Ecodesign Directive implementation zones in Bavaria and Baden-Württemberg are accelerating hardware refresh demand. United States FCC Part 15 enforcement corridors in California and Texas shape electromagnetic compatibility investment patterns.
United States
FCC Part 15 emissions standards govern electromagnetic compatibility for all electronic instruments marketed domestically. Bedroom producers and independent electronic musicians in Los Angeles and Austin drive software synthesizer adoption through DAW-integrated workflows. Direct-to-consumer platforms disintermediate traditional retailer networks, with modular synthesizer segments favoring detailed technical documentation over in-person demonstration.
Germany
The EU's Ecodesign for Energy-Related Products Directive tightens standby power limits and accelerates hardware refresh cycles in Berlin and Hamburg electronic music production studios. REACH compliance restricts flame retardants and plasticizers in electronic enclosures, broadening cost-of-entry calculus for domestic manufacturers. Bavarian engineering clusters specialize in voltage-controlled filter calibration expertise for boutique analog production.
Japan
METI Top Runner standards progressively tighten energy efficiency benchmarks for consumer electronics including musical instruments. Tokyo's dense network of electronic instrument retailers and live performance venues sustains premium analog synthesizer sales velocity unmatched elsewhere. Osaka-Kobe manufacturing corridors anchor professional keyboard synthesis production with deep R&D investment in low-power DSP architectures.
United Kingdom
RoHS framework constraints on material choices and standby power profiles affect synthesizers sold across member state supply chains. London's concentration of media composition studios and university music technology programs drives institutional procurement of subtractive and FM synthesis platforms. Manchester and Bristol electronic music scenes sustain demand for modular synthesizer configurations through specialized retailer networks.
South Korea
MFDS alignment with international electromagnetic compatibility standards facilitates export-oriented manufacturing. Seoul's K-pop production studios and game audio houses drive demand for granular synthesis and spectral manipulation capabilities. Busan-Ulsan industrial corridors support component sourcing for digital signal processor integration in mid-market hardware lines.
Music Synthesizers Market Competitive Environment
Japanese producers anchor the professional tier; European specialists hold the boutique analog segment. The vendor base stratifies across three distinct tiers: multinational electronics conglomerates with captive semiconductor fabrication, mid-scale hardware specialists with regional manufacturing footprints, and software-native platforms with zero marginal distribution costs. Dominant competitive moves include backward integration into specialty component supply and direct-to-consumer channel capture.
Within the heritage analog tier, Moog Music Inc. and Roland Corporation exemplify vertically integrated domestic manufacturing approaches that navigate material substitution requirements. Yamaha Corporation occupies a position spanning professional keyboard synthesis through channel control across Japanese retailers and North American direct platforms. Arturia and Native Instruments GmbH represent the software-native archetype, compressing entry barriers through algorithmic platforms that prioritize DAW integration.
| Leading Market Players |
|---|
| Moog Music Inc. |
| Arturia |
| Yamaha Corporation |
| inMusic, Inc. |
| Behringer |
| Roland Corporation |
| Casio Computer Co., Ltd. |
| Native Instruments GmbH |
| Korg Inc. |
| Others |
Value Chain & Pricing Dynamics
University procurement committees and independent producers anchor divergent pricing models across the synthesizer market, with institutional buyers negotiating site licenses while individual creators absorb spot-market premiums for scarce analog components.
Pricing Analysis
Short lead-time premiums dominate analog synthesizer transactions, with matched transistor pairs and rare capacitors commanding immediate-payment pricing from Tokyo's dense retailer network. Three-tier pricing structure across premium, standard, and economy levels separates hand-calibrated voltage-controlled architectures from mass-produced digital implementations and software licenses. Cost compression in the analog tier intensifies because specialty semiconductor foundries ration discrete component allocation. Educational institutions exhibit lowest price sensitivity through negotiated maintenance agreements, while bedroom producers face highest sensitivity to hardware ownership barriers.
Supply Chain Analysis
Discrete component supply rests on Japanese specialty semiconductor foundries, German precision engineering clusters, and Chinese PCB fabrication facilities. Voltage-controlled oscillators, matched transistor pairs, and flame-retardant enclosure compounds constitute critical input dependencies. Single-source vulnerability concentrates in boutique analog component fabrication where hand-tuning expertise resides with diminishing technician pools. Distribution runs through direct-to-consumer platforms for modular segments, while brick-and-mortar retailer networks sustain hands-on evaluation culture in Japan's metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU's REACH framework erects a compliance moat that favors incumbent manufacturers with established material certification pathways and captive substitution R&D.
For Market Incumbents: Cement defensive positioning through backward integration into specialty semiconductor supply and preemptive low-power DSP architecture investment. Software-native platforms threaten hardware margins through zero-marginal-replication economics. Channel control across Japanese retailer networks and North American direct platforms remains the priority lever for professional keyboard synthesis lines. For New Entrants and Emerging Players: University music technology programs represent the most penetrable demand node, with enrollment-driven procurement expanding across North American and European higher education. Modular synthesizer configurations offer white-space entry through firmware accessibility positioning ahead of right-to-repair legislation. Go-to-market execution favors DAW-integrated algorithmic platforms that compress hardware ownership barriers for independent producers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated analog specialists with captive component supply and hand-calibration expertise. Long-term viability hinges on regulatory preemption capabilities across Ecodesign and REACH frameworks. Watch METI Top Runner standard progression as the inflection signal for professional keyboard synthesis redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Supply | Captive sourcing of matched transistor pairs insulates Moog and Roland from foundry allocation constraints. |
| Low-Power DSP Architecture Investment | Yamaha's R&D preempts METI Top Runner thresholds while preserving signature FM timbral character. |
| Educational Institutional Procurement Program | Site license negotiations with North American universities expand enrollment-driven subtractive synthesis demand. |
| Direct-to-Consumer Platform Expansion | Manufacturer-controlled channels capture margin and customer data in modular synthesizer segments. |
| Firmware Accessibility Repositioning | Modular architecture specialists align with emerging right-to-repair mandates across multiple jurisdictions. |
Study Parameters
SEC filings, customs trade records, and METI energy efficiency disclosures formed the secondary backbone, cross-referenced with primary interviews across synthesizer R&D directors, university procurement managers, electronic music retailers, and specialty semiconductor foundry engineers. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across hardware and software paradigms.
Analytical lens combined bottom-up voice-count and polyphony specifications with top-down regulatory framework impacts across the projection horizon. Segmentation dimensions modeled include product type, end-user sophistication, signal generation technology, and distribution channel economics. CAGRs derived from installed base evolution and replacement cycle compression. Forecast inputs incorporated REACH substitution timelines and METI Top Runner threshold progression.
Revisions become necessary when specialty semiconductor foundry allocation shifts, right-to-repair legislation accelerates, or generative algorithm capabilities displace traditional sound design labor faster than projected. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Musical Groups and Artists Market
Music
Electronic Dance Music (EDM) Market
Music
Independent Music Publishing Market
Music
Global Free Music Making Software Market
Music
Discography Market
Music
Global Background Music Market
Music
Traditional Music Market
Music
Music App Market
Music
Music Publishing Market
Music
Music Production Software Market
Music
Traditional Chinese Instruments Market
Music
Global Stock Music Market
Music
United States Live Music Market
Music
Europe Independent Artist Market
Music
Vinyl Records Market
Music
Virtual Musical Instruments Market