
 Musical Groups and Artists Market | 2026-2036
Musical Groups and Artists Market Size, Share, and Industry Trends Forecast 2026-2036
Musical Groups and Artists Market Insights
Market Context
ISO 9001 certification for quality management in live event production is reorganizing which promoters and artist management firms qualify for major venue contracts and festival partnerships. Universal Music Group leverages its vertically integrated recorded music and publishing divisions to control catalog licensing across film, advertising, and gaming synchronization. Live Nation Entertainment anchors North American touring infrastructure through its combined ticketing and venue management operations, while Warner Music Group competes via specialized artist development programs targeting emerging genre territories.
Technical Definition and Segment Structure
Musical groups and artists comprise organized performers who create, record, and distribute original compositions across analog and digital formats, typically employing multi-track recording systems with 24-bit/96kHz resolution standards for commercial release. Their primary commercial purpose spans direct-to-consumer entertainment consumption, brand synchronization licensing, and experiential live performance delivery. Pop and hip-hop genres capture disproportionate streaming volume and merchandising velocity, while the digital streaming channel concentrates subscriber revenue and algorithmic discovery mechanisms that disproportionately elevate established artist status tiers over emerging independents.
Regulatory Framework and Outlook
The US Copyright Office and European Union copyright directives under the Digital Single Market framework govern mechanical and performance royalty structures, while the US Federal Trade Commission monitors ticketing transparency and secondary market disclosure requirements. These regulatory layers shape artist compensation models, platform licensing obligations, and consumer pricing visibility across distribution channels. Stakeholders must monitor evolving mechanical royalty rate proceedings and emerging state-level ticketing legislation that could restructure venue-promoter-artist revenue splits.
Market Dynamics
Digital distribution rights frameworks are tightening across major jurisdictions, forcing live event promoters and streaming platforms to renegotiate artist compensation structures and catalog licensing terms. This regulatory compression is reshaping how revenue flows between creators, intermediaries, and end consumers.
Growth Catalysts
- EU Copyright Directive Article 17:Platform liability rules for user-uploaded content are strengthening artist royalty claims across European streaming markets, redirecting revenue toward rights holders.
- Immersive live production technologies:Spatial audio and extended reality staging systems are expanding per-ticket revenue potential at major venue installations.
- Catalog monetization infrastructure:Secondary markets for music publishing rights are deepening liquidity for legacy artist estates and songwriter catalogs.
Market Restraints
- Mechanical royalty rate uncertainty:US Copyright Royalty Board proceedings are freezing long-term licensing investment decisions across streaming and physical formats.
- Venue operator concentration:North American live event infrastructure is controlled by a limited set of integrated promoter-venue operators, constraining independent artist touring economics.
- Synchronization licensing fragmentation:Territory-by-territory clearance requirements are extending turnaround times for brand and gaming placements.
Strategic Opportunities
- Latin American streaming penetration:Brazil and Mexico are exhibiting subscriber growth trajectories that outpace mature markets, creating first-mover advantages for localized artist development.
- Generative AI tooling:Machine learning production assistants are compressing demo-to-release timelines for independent artists operating outside traditional label structures.
- Federal live event tax incentives:US infrastructure legislation contains provisions for cultural venue modernization that could reduce capital requirements for regional touring circuits.
Industry Challenges
- Mastering engineer scarcity:Commercial release standards for immersive audio formats are outpacing qualified technician supply, creating bottlenecks for independent releases.
- Legacy contract reconciliation:Pre-digital era recording agreements are generating disputes over streaming royalty allocation and termination rights.
- Cross-platform data integration:Artists and managers face fragmented analytics across streaming, ticketing, and merchandise systems, complicating audience development decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Musical Groups and Artists Market |
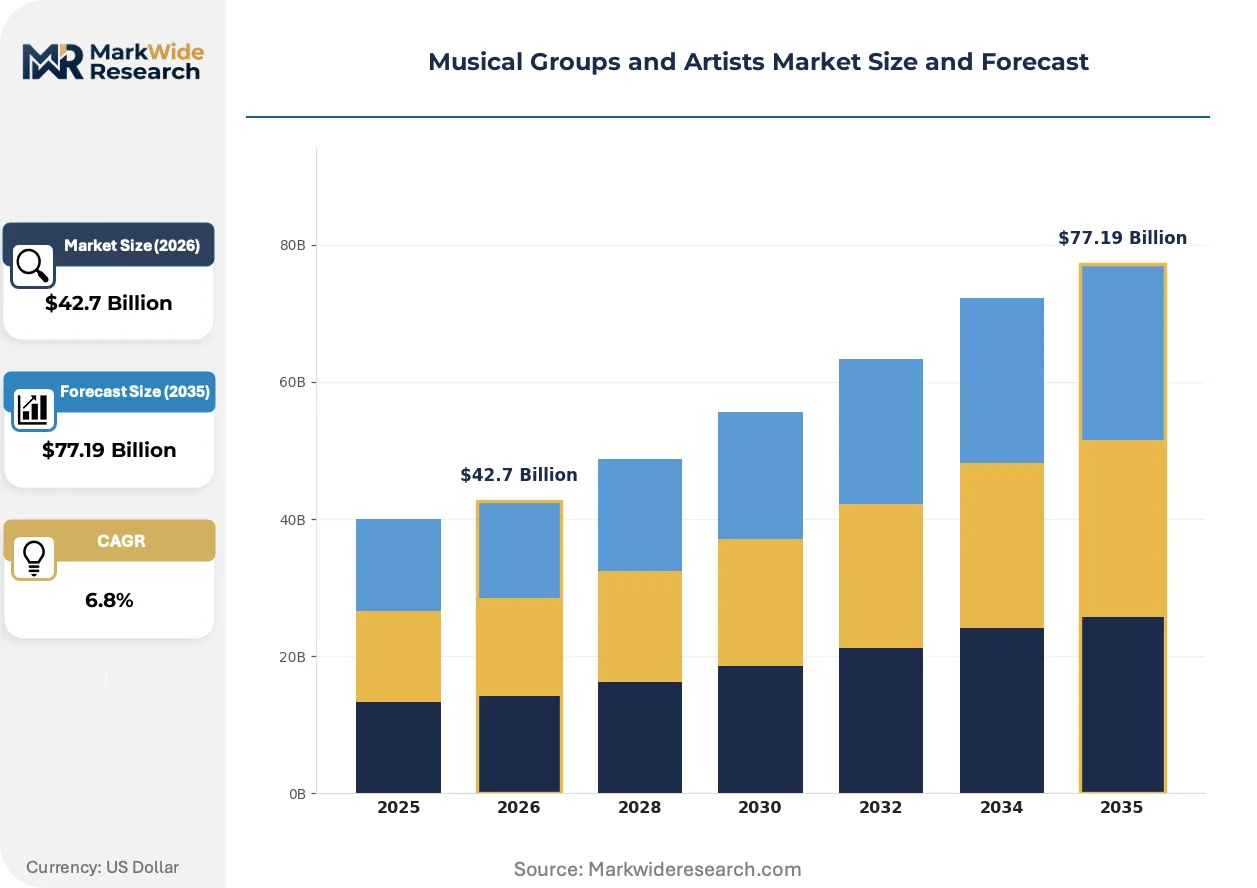
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Genre: Pop, Rock, Hip-Hop, Jazz Performance Type: Solo Artists, Duos, Bands, Collaborations Distribution Channel: Digital Streaming, Physical Sales, Concerts, Merchandising Artist Status: Independent, Major Label, Emerging, Established |
| Companies Covered | Universal Music Group, Sony Music Entertainment, Warner Music Group, BMG Rights Management GmbH, Live Nation Entertainment, Kobalt Music Group, The Orchard, Concord Music Group, AEG Presents, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Musical Groups and Artists Market Trends and Innovations
Algorithmic curation systems are redistributing discovery power from traditional gatekeepers toward platform-controlled recommendation engines, altering how emerging artists build audience equity and how catalogs retain long-term value.
Spatial audio production workflows are fragmenting the traditional stereo mastering pipeline. Apple Music and Amazon Music are prioritizing Dolby Atmos content in their editorial programming, forcing independent studios to invest in immersive monitoring infrastructure or cede premium placement opportunities to better-capitalized competitors. The technology is fragmenting genre boundaries as producers experiment with three-dimensional sound staging that was technically impractical under prior distribution constraints.
The US Federal Trade Commission's ticketing transparency enforcement is tightening disclosure requirements for fee structures and holdback practices. Promoters must now itemize ancillary charges at initial price display, compressing the effective price discrimination window for high-demand events. This regulatory pressure is most acute in the secondary market, where platform operators are restructuring fee architectures to preempt enforcement action.
Direct-to-fan subscription models are displacing traditional album-cycle marketing for mid-tier artists. Patreon, Bandcamp, and platform-native artist subscription tools are capturing recurring revenue that previously flowed through label advance structures. This behavioral shift is most visible in electronic and hip-hop genres, where production autonomy and release frequency align with continuous content delivery expectations.
Musical Groups and Artists Market Segmentation
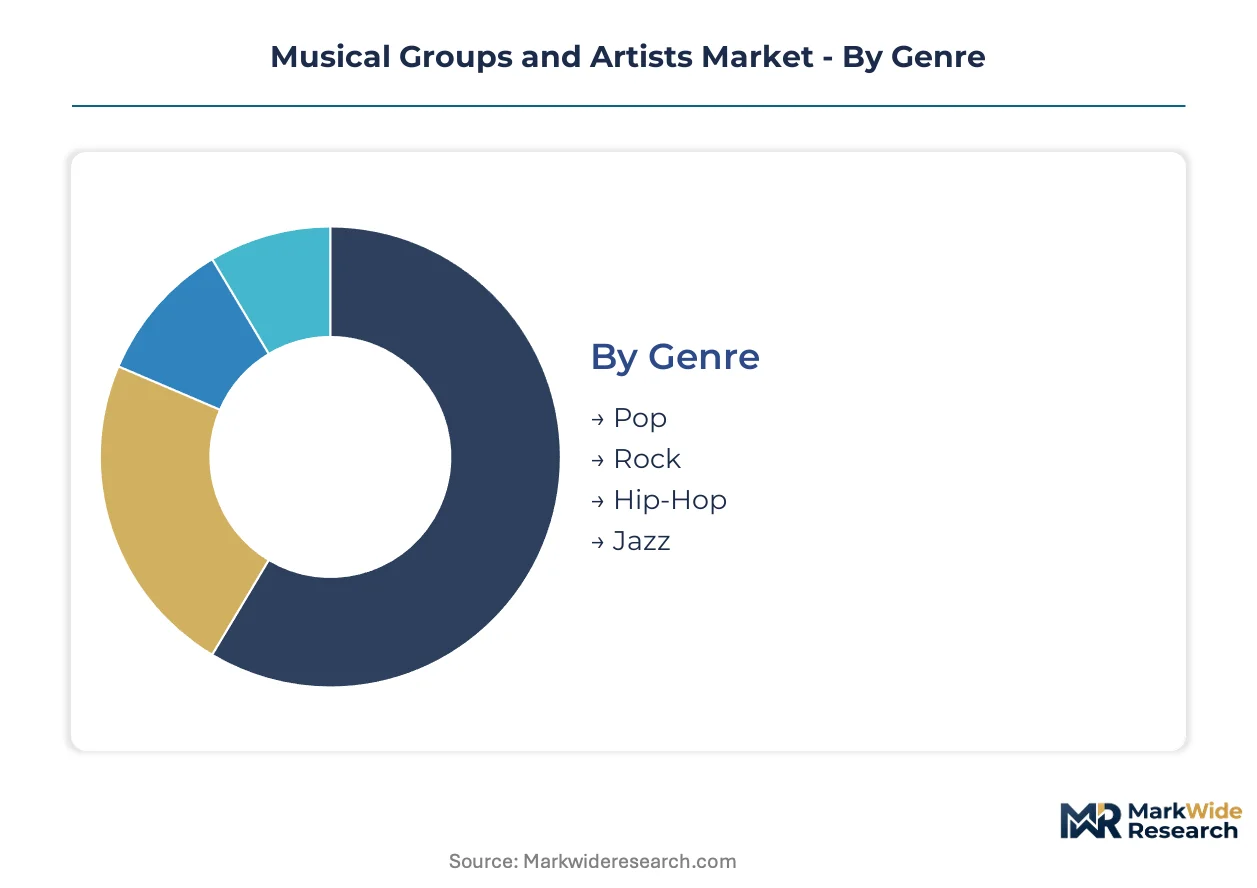
Segmentation in musical groups and artists reveals how revenue pools fragment across creative formats, commercial maturity tiers, and platform economics. Each dimension exposes different margin vulnerabilities and growth vectors for investors and operators.
Genre:
Margin concentration within genre segments tracks directly with streaming algorithm favorability and synchronization licensing rates.
- Pop:Optimized for playlist placement and short-form video synchronization. Catalogs from Los Angeles and Stockholm production clusters command premium licensing rates for brand campaigns and gaming integrations.
- Hip-Hop:Merchandising velocity and direct-to-fan subscription penetration outpace other genres. Atlanta, Chicago, and London recording ecosystems concentrate production talent and independent distribution infrastructure.
- Rock:Touring economics sustain revenue for legacy acts with established venue relationships. Festival headliner slots and catalog acquisitions by private equity funds support asset valuations for classic-era recordings.
- Jazz:Niche streaming performance offset by high-margin vinyl sales and institutional performance contracts. European festival circuits and Japanese collector markets provide geographic diversification.
The dominant share belongs to Pop, while Hip-Hop is closing the gap fastest.
Performance Type:
Revenue scalability varies sharply by ensemble size and contractual complexity.
- Solo Artists:Lowest revenue-split overhead and fastest decision velocity for release scheduling. Streaming platforms prioritize solo acts in algorithmic discovery modules due to cleaner rights clearance.
- Bands:Internal voting agreements and multi-member publishing splits complicate licensing negotiations. Long-term touring contracts and collective merchandise agreements sustain revenue stability.
- Duos:Balanced creative control with reduced coordination costs. Electronic and hip-hop production partnerships dominate this segment.
- Collaborations:Cross-label coordination requirements extend release timelines. Streaming platforms feature collaborative tracks prominently in cross-genre playlist programming.
Solo Artists capture the largest revenue pool, though Collaborations are expanding most quickly.
Distribution Channel:
Platform control over consumer relationships determines margin retention across channels.
- Digital Streaming:Subscription revenue concentrates with platform operators, while per-stream artist payouts face regulatory pressure. Spatial audio and high-resolution tiers create pricing differentiation opportunities.
- Concerts:Highest per-fan revenue capture when ticketing transparency regulations permit dynamic pricing. Venue-promoter integration controls profit allocation.
- Physical Sales:Vinyl manufacturing bottlenecks limit volume growth. Collector-grade pressings and direct-to-consumer pre-orders sustain premium pricing.
- Merchandising:Direct fulfillment relationships bypass platform intermediaries. Limited-drop strategies and artist-branded lifestyle products expand average revenue per fan.
Digital Streaming dominates volume, yet Concerts deliver superior unit economics.
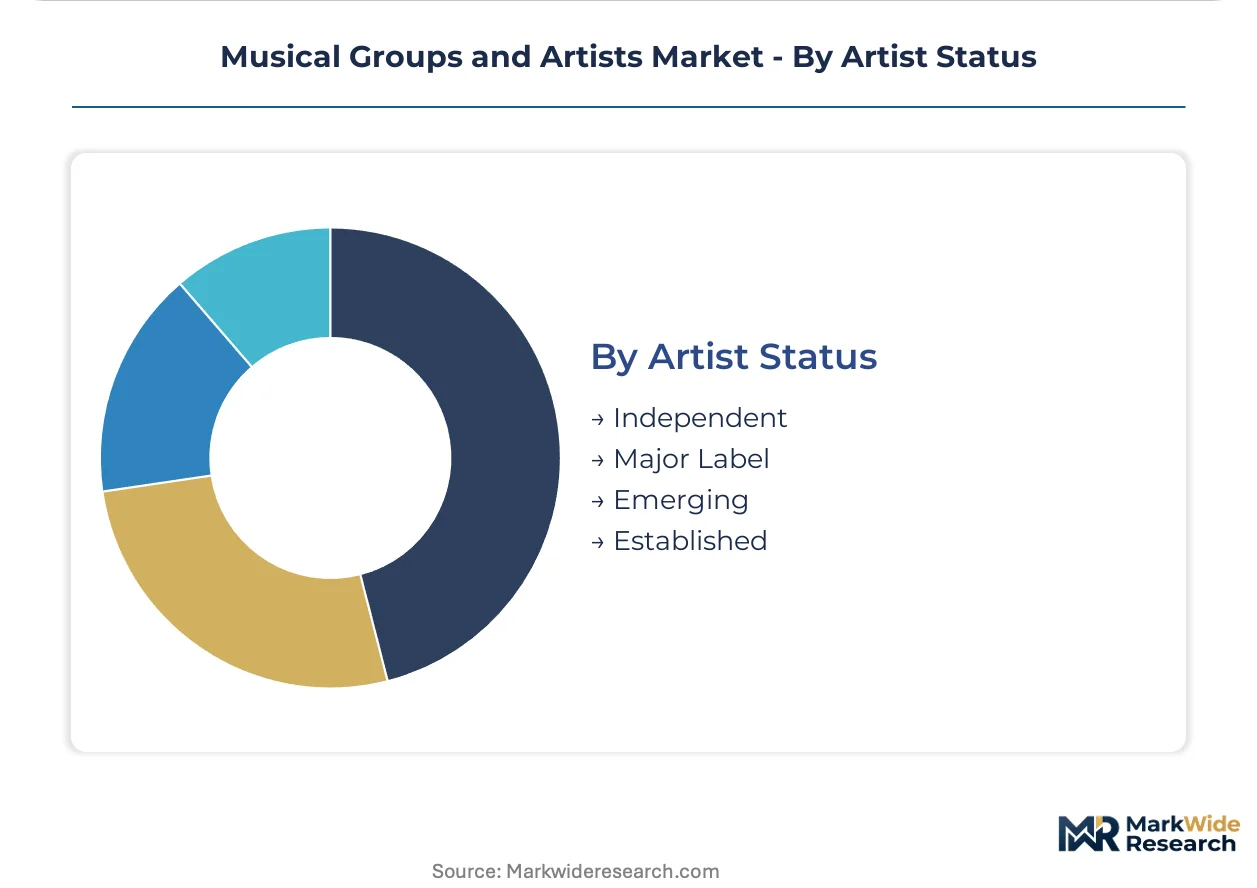
Artist Status:
Advance structures and rights ownership terms define financial outcomes across career stages.
- Major Label:Marketing infrastructure and playlist access justify revenue-sharing concessions. Catalog ownership reversion clauses determine long-term asset control.
- Independent:Full rights retention enables direct licensing and subscription revenue capture. Distribution service fees and self-funded marketing constrain growth velocity.
- Emerging:Algorithmic discovery dependency creates platform power asymmetries. Development deals and advance structures vary widely by genre and geography.
- Established:Catalog monetization and touring guarantees provide revenue predictability. Legacy contract renegotiations and termination rights disputes complicate streaming-era economics.
Major Label artists generate the largest absolute revenue, while Independent status is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Promoter-buyers and streaming platform procurement teams concentrate investment decisions in territories with established royalty collection infrastructure and high per-capita entertainment spending. Artist management firms prioritize markets with transparent rights frameworks and scalable live venue networks.
United States
Los Angeles and Nashville recording clusters anchor global catalog licensing activity, with synchronization revenue from film studios and gaming publishers driving rights-holder valuations. The US Copyright Royalty Board governs mechanical rate proceedings that directly impact streaming platform licensing costs. Atlanta's hip-hop production ecosystem and New York's integrated label-promoter operations sustain artist development velocity unmatched elsewhere.
Germany
Collecting society GEMA enforces performance rights with regulatory rigor that sustains above-average per-stream payouts for rights holders. Berlin's electronic music venue density and Hamburg's label infrastructure create self-reinforcing talent concentration. The country's Federal Cartel Office monitors Live Nation-Ticketmaster integration effects on promoter competition.
United Kingdom
London's publisher and management company clusters dominate European synchronization licensing for advertising campaigns. The Competition and Markets Authority enforces ticketing transparency rules that constrain dynamic pricing architectures. Manchester and Glasgow venue circuits provide essential touring infrastructure for mid-tier artist profitability.
Brazil
São Paulo and Rio de Janeiro streaming subscriber growth outpaces mature market saturation curves, attracting localized artist development investment from major label affiliates. ANCINE, the national cinema and audiovisual regulator, oversees music licensing in film and television productions. The southeastern state's independent distribution infrastructure reduces platform dependency for Portuguese-language releases.
Japan
Tokyo's physical retail network sustains CD and vinyl revenue streams that buffer artists against streaming payout volatility. The Agency for Cultural Affairs administers copyright term extensions and neighboring rights frameworks. Osaka's live house circuit and Fukuoka's festival infrastructure anchor domestic touring economics for genre-specific audiences.
Musical Groups and Artists Market Competitive Landscape
Player mix skews toward vertically integrated entertainment conglomerates controlling multiple revenue chain links. Three major recorded music groups anchor global catalog ownership, while specialized promoters and rights management platforms occupy tiered positions beneath. Competitive positioning hardens around exclusive artist roster control, venue-ticketing integration, and direct-to-fan subscription infrastructure. M&A activity concentrates on catalog acquisitions and emerging market distribution networks.
Among diversified entertainment groups, Universal Music Group, Sony Music Entertainment, and Warner Music Group exemplify the integrated recorded music-publishing model that dominates rights ownership and licensing negotiation leverage. Live Nation Entertainment occupies a distinct position combining promoter, venue operator, and ticketing platform functions. Specialist rights administrators like Kobalt Music Group and BMG Rights Management GmbH represent alternative structures that challenge traditional label control over royalty collection and creative financing.
| Leading Market Players |
|---|
| Universal Music Group |
| Sony Music Entertainment |
| Warner Music Group |
| BMG Rights Management GmbH |
| Live Nation Entertainment |
| Kobalt Music Group |
| The Orchard |
| Concord Music Group |
| AEG Presents |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at major label-owned mastering facilities and integrated promoter-venue networks generates scale economies that compress per-unit costs for high-volume releases while establishing price floors for independent artists lacking comparable infrastructure access. This concentration of technical and distribution capacity in Los Angeles, Nashville, and New York recording clusters simultaneously elevates catalog licensing premiums and constrains pricing flexibility for emerging acts outside major label systems.
Pricing Analysis
Cost-plus contracts with mechanical royalty indexation to US Copyright Royalty Board proceedings dominate streaming platform licensing agreements, creating pricing volatility as rate determinations pend. Three-tier pricing structure across premium immersive audio, standard resolution, and economy ad-supported tiers differentiates subscriber segments, with spatial audio capabilities commanding brand premiums through Apple Music and Amazon Music editorial placement. Pricing pressure stems from per-stream payout compression as subscriber growth saturates mature markets, with independent artists exhibiting highest price sensitivity due to self-funded marketing constraints and distribution service fee burdens.
Supply Chain Analysis
The United States, United Kingdom, and Germany anchor vinyl pressing plant capacity and spatial audio mastering infrastructure, while Taiwan and Japan concentrate semiconductor-dependent recording equipment manufacturing. Raw material dependencies include polycarbonate for physical media, rare earth elements for immersive audio hardware, and cobalt for battery systems powering mobile production rigs. Single-source vulnerability runs through Dolby Laboratories' Atmos encoding licensing, which feeds from proprietary certification requirements that constrain independent studio capacity expansion. Distribution runs through vertically integrated label-promoter networks controlling venue access and playlist editorial placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as Latin American streaming penetration accelerates and generative AI production tooling compresses demo-to-release timelines for artist development. Federal live event tax incentives in US infrastructure legislation further reduce capital barriers for regional touring circuit modernization.
For Market Incumbents: Compound catalog monetization infrastructure through secondary market publishing rights platforms and legacy artist estate acquisitions. Defend against independent distribution encroachment by tightening exclusive artist roster control and accelerating spatial audio mastering capacity additions in Atlanta and London. ISO 9001 certification investment for live event production quality management sustains venue contract qualification advantages as regulatory frameworks tighten.
For New Entrants and Emerging Players: Certification fast-track through Dolby Atmos production partnerships opens premium placement access on Apple Music and Amazon Music editorial programming. White-space targets include Portuguese-language artist development in Brazil's southeastern independent distribution corridor and direct-to-fan subscription tooling for electronic and hip-hop genres where production autonomy aligns with continuous release expectations. Go-to-market positioning centers on generative AI-assisted production workflows that compress timelines outside traditional label advance structures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors catalog-heavy rights administrators with established royalty collection infrastructure across European collecting societies and Japanese physical retail networks. Long-term viability rests on diversification across streaming, synchronization, and experiential live performance revenue streams rather than single-channel dependency. The signal to monitor is mechanical royalty rate determination outcomes from US Copyright Royalty Board proceedings, which would restructure platform licensing economics and rights-holder valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalog Acquisition | Secondary market liquidity for legacy publishing rights deepens revenue predictability through GEMA and PRS for Music collection infrastructure. |
| Spatial Audio Infrastructure Investment | Dolby Atmos mastering certification unlocks premium editorial placement on Apple Music and Amazon Music recommendation algorithms. |
| Direct-to-Fan Platform Integration | Patreon and Bandcamp subscription tooling captures recurring revenue previously flowing through label advance structures in electronic genres. |
| Latin American Distribution Network | Localized artist development in São Paulo and Rio de Janeiro exploits subscriber growth trajectories outpacing mature market saturation. |
| Live Event Tax Incentive Utilization | US infrastructure legislation provisions for cultural venue modernization reduce capital requirements for regional touring circuit expansion. |
Research Methodology
Operator-level perspectives from artist management executives, live event promoters, streaming platform licensing directors, and music publishing administrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against US Copyright Office filings, European Union Digital Single Market directive implementations, and mechanical royalty rate proceeding records from the Copyright Royalty Board. SEC 10-K disclosures from major recorded music groups, collecting society annual reports from GEMA and PRS for Music, and streaming platform subscriber metrics provided quantitative grounding. Bottom-up artist roster economics and top-down market sizing triangulated volume and value estimates.
Sensitivity analysis around regulatory rate determination timelines, streaming subscriber saturation curves, and live event capacity utilization informed the forecast framework. Segmentation dimensions modeled include genre category, artist status tier, distribution channel mix, and performance type configuration across the projection horizon. CAGRs derived from historical revenue trajectory analysis and penetration rate benchmarking against comparable entertainment sectors. Industry-specific inputs encompass synchronization licensing clearance timelines, vinyl manufacturing capacity constraints, and spatial audio adoption curves through platform editorial programming priorities.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement of ticketing transparency requirements and continued platform investment in algorithmic discovery mechanisms; material deviation in mechanical royalty rate outcomes or generative AI copyright adjudication would warrant model refresh. Recalibration cycles align with material shifts in Copyright Royalty Board proceedings, EU Copyright Directive implementation enforcement, and federal live event infrastructure incentive disbursement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Music Production Software Market
Music
Electronic Dance Music (EDM) Market
Music
Vinyl Records Market
Music
Global Background Music Market
Music
Global Stock Music Market
Music
Traditional Chinese Instruments Market
Music
Independent Music Publishing Market
Music
Music Synthesizers Market
Music
Europe Independent Artist Market
Music
Global in-Store Music Service Market
Music
United States Live Music Market
Music
Music Distribution Services Market
Music
Music Publishing Market
Music
Asia-Pacific Independent Artist Market
Music
Discography Market
Music
Traditional Music Market