
 Music Publishing Market | 2026-2036
Music Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
Music Publishing Market Intelligence
A shift from simple administration deals towards more integrated co-publishing and exclusive rights models is expanding the scope of publisher-songwriter relationships. Universal Music Publishing Group leverages its vast catalog to secure synchronization deals in film and television. Concurrently, BMG Rights Management differentiates through its artist-friendly service model, focusing on transparency. Sony Music Publishing sustains its market position through strategic catalog acquisitions and global administrative reach.
Music publishing involves the administration of musical composition copyrights to generate royalties for songwriters and composers. Its primary commercial function is to license these compositions for use and collect revenue from various sources. Performance and mechanical royalties remain foundational revenue streams, although synchronization royalties from film, TV, and advertising represent a high-value segment. Among usage platforms, streaming services are expanding most rapidly, reshaping royalty collection and distribution mechanisms.
Regulatory frameworks like the US Music Modernization Act and the EU's Directive on Copyright in the Digital Single Market are reshaping royalty collection. These rules, overseen by bodies such as the Mechanical Licensing Collective in the US, aim to improve transparency for songwriters. Navigating the evolving landscape of direct licensing versus reliance on Collective Management Organizations is now a central strategic decision for rights holders.
Market Dynamics
The central tension in music publishing is the friction between globalized digital streaming platforms and the fragmented, territory-specific nature of copyright law. This dynamic is intensified by data privacy mandates like the EU's GDPR, which add complexity to the management of royalty data across borders.
Growth Catalysts
- Video Game Licensing:The integration of commercial music into major video game franchises represents a significant and expanding revenue source for synchronization rights holders.
- South Korean Market Expansion:The global success of the South Korean music industry fuels high demand for publishing administration and creative services, concentrating value in the region.
- EU Copyright Directive:The Directive on Copyright in the Digital Single Market creates new obligations for online platforms to license content, strengthening the negotiating position of music publishers.
Market Restraints
- Royalty-Free Music Libraries:The proliferation of high-quality, low-cost royalty-free music libraries presents a substitution threat for certain use cases, particularly for smaller content creators and businesses.
- Inconsistent Global Regulations:Divergent copyright laws and royalty collection mechanisms between countries create significant administrative complexity and cost for publishers operating internationally.
- Attribution on Social Platforms:Accurately tracking and monetizing music usage within user-generated content on short-form video platforms remains a significant technical and administrative hurdle.
Strategic Opportunities
- Emerging Digital Platforms:Licensing musical works for use in emerging environments such as metaverse concerts, virtual reality experiences, and NFT-related projects offers a new frontier for monetization.
- Expansion into Growth Markets:Establishing administrative and A&R operations in high-growth music markets in Southeast Asia and Latin America provides access to new songwriter talent and catalogs.
- AI in A&R:Leveraging artificial intelligence and predictive analytics to analyze streaming data can help identify potential hit songs and emerging artists, optimizing A&R investment and strategy.
Industry Challenges
- Royalty Data Management:Processing and verifying immense volumes of usage data from thousands of global digital service providers requires sophisticated IT infrastructure and compliance with regulations like GDPR.
- Complex Sync Negotiations:Securing synchronization licenses for global advertising campaigns involves intricate negotiations over territory, media, and duration, increasing legal and administrative overhead.
- Talent and Skill Gaps:A shortage of professionals with combined expertise in music rights, data science, and technology hinders publishers' ability to fully capitalize on new analytical tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Music Publishing Market |
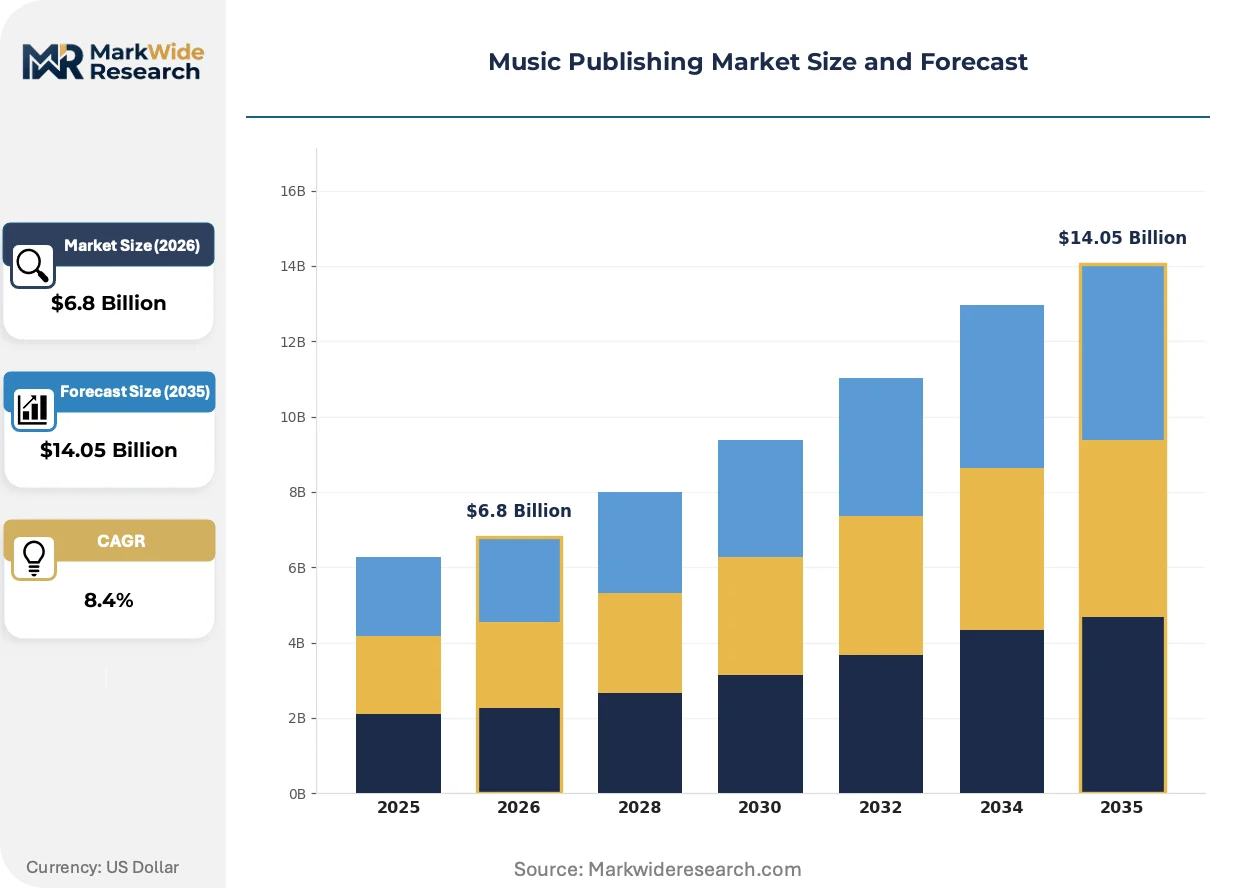
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Royalty Type: Performance, Mechanical, Synchronization, Print, Digital, Neighboring Rights Ownership Model: Exclusive Rights, Co-publishing, Administration, Sub-publishing, Direct Licensing, Collective Management Usage Platform: Broadcast, Streaming Services, Film & TV, Video Games, Live Events, Advertising Licensee Type: Record Labels, Independent Artists, Media Houses, Event Organizers, Ad Agencies, Streaming Platforms |
| Companies Covered | Kobalt Music Publishing, Concord Music Publishing, Sony Music Publishing, Downtown Music Publishing, Primary Wave Music, Universal Music Publishing Group, BMG Rights Management, Hipgnosis Songs Fund, Warner Chappell Music, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Music Publishing Market Strategic Shifts & Innovations
Digital platforms and new legislative frameworks are fundamentally altering how musical works are valued and monetized. This environment demands greater transparency and more sophisticated data management from all rights holders in the value chain, reshaping publisher-songwriter relationships.
AI-driven royalty management platforms employ audio fingerprinting and metadata analysis to track music usage across digital services. Major publishers and Collective Management Organizations are adopting these tools to process vast datasets from streaming and social media. This technology is consolidating the historically manual and error-prone process of royalty collection into a more automated and accurate system.
The United States' Music Modernization Act created the Mechanical Licensing Collective to overhaul royalty payments. Its primary industrial consequence is a new blanket licensing system for digital music providers and a publicly accessible database of musical works ownership. Independent songwriters and small publishers are most impacted, as the framework improves their ability to claim previously unmatched mechanical royalties.
Songwriters are increasingly demanding more holistic publisher relationships that extend beyond administration to include creative development and A&R support. This preference disrupts the traditional, transactional administration deal in favor of co-publishing or exclusive songwriter agreements. The trend is most pronounced in competitive creative centers like London and Nashville, where publishers function as strategic career partners.
Music Publishing Market Segmentation
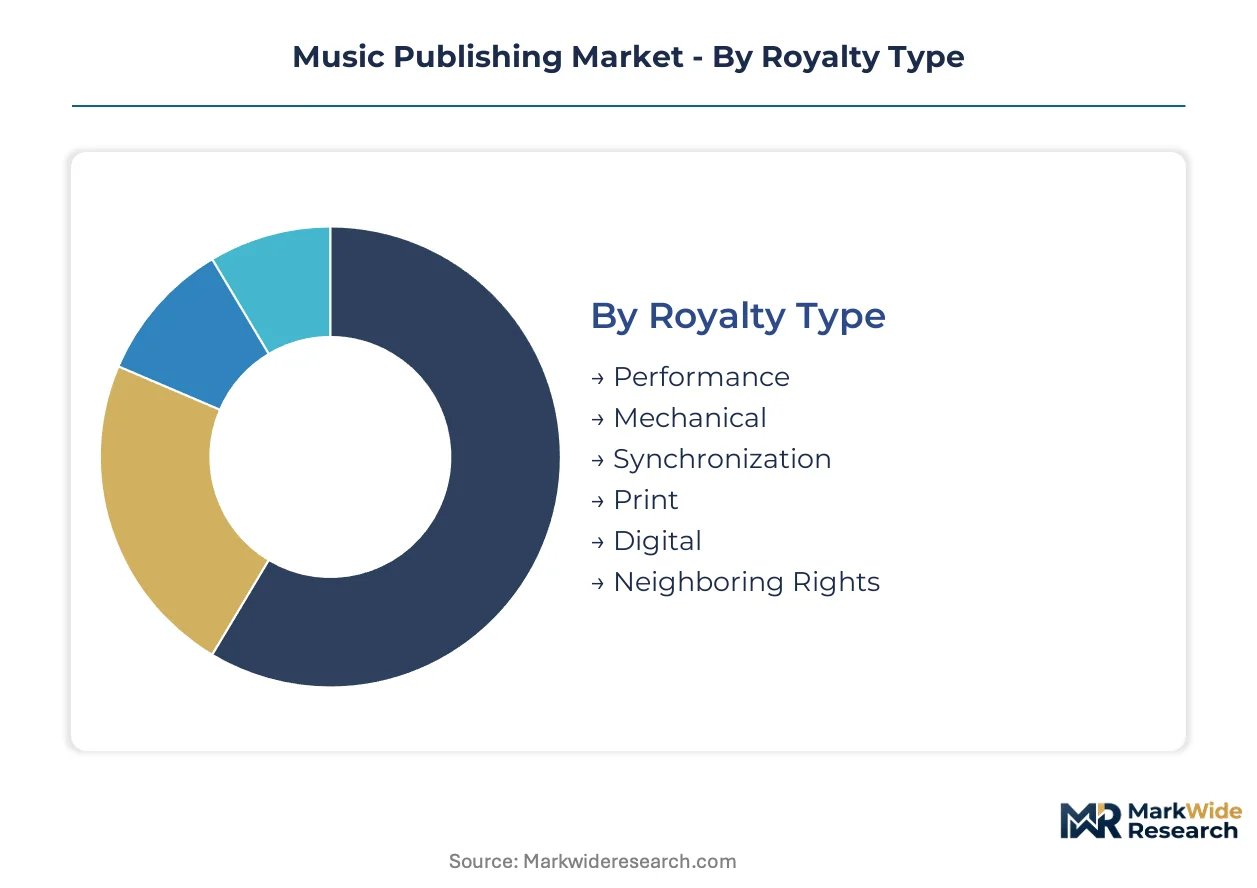
Understanding the distinct segments within the music publishing market clarifies how value is created and distributed across the industry. This granular view helps stakeholders identify specific revenue streams and strategic partnership opportunities. Analyzing these segments reveals the evolving commercial dynamics of musical compositions.
Royalty Type:
This segmentation highlights how different royalty streams are integrated into the broader music ecosystem, from direct payments for specific uses to embedded revenue within larger platforms.
- Synchronization:These royalties are generated when musical compositions are licensed for visual media, including film, television shows, advertisements, and video games. Demand concentrates in the video game sector, which increasingly integrates commercial music into major franchises.
- Digital:This category encompasses royalties derived from online uses, primarily streaming services and digital downloads, reflecting the dominant consumption method for music. Demand concentrates in streaming services, which are expanding most rapidly across global markets.
- Performance:Public performance royalties are collected when music is played in public venues, on radio, or through broadcast television, forming a foundational revenue stream for publishers.
- Mechanical:Mechanical royalties are generated from the reproduction of musical works, such as physical sales, digital downloads, and interactive streams.
- Print:Print royalties come from the sale of sheet music, songbooks, and other printed forms of musical compositions.
- Neighboring Rights:These rights pertain to the sound recording itself, typically collected by record labels and performing artists, but sometimes administered by publishers for artist-side income.
Volume placements concentrate in Performance royalties; the faster expansion belongs to Digital royalties.
Ownership Model:
This category delineates the various contractual relationships between songwriters and publishers, reflecting different levels of creative control and administrative responsibility.
- Co-publishing:Publishers acquire a share of the copyright and administration rights, often providing creative development and A&R support to songwriters. This model is gaining traction in competitive creative centers like Nashville, where publishers act as strategic career partners.
- Administration:Publishers manage the rights and collect royalties on behalf of the songwriter without acquiring a share of the copyright itself, focusing purely on administrative tasks. This model serves as a core function for managing diverse catalogs across all market segments.
- Exclusive Rights:The publisher acquires full ownership and control over the musical composition for a specified term, handling all licensing and administration.
- Direct Licensing:Songwriters or their representatives license their music directly to users, bypassing traditional publishers or collective management organizations.
- Collective Management:Rights holders delegate their rights to Collective Management Organizations (CMOs) for blanket licensing and royalty collection, particularly for performance and mechanical uses.
- Sub-publishing:Publishers license rights to local sub-publishers in foreign territories to manage local administration and collection.
The shift towards Co-publishing reflects deeper songwriter-publisher partnerships, while Administration remains a fundamental choice for efficient rights management.
Usage Platform:
This segmentation examines the specific channels through which musical compositions are consumed and monetized, indicating where publisher focus is shifting.
- Streaming Services:Digital platforms offering on-demand music access, representing the largest and most rapidly expanding segment for music consumption. Demand concentrates in established markets like the United States and emerging markets in Southeast Asia.
- Video Games:Integration of commercial music into video game soundtracks, trailers, and in-game experiences, generating significant synchronization revenue. Demand concentrates in major game development hubs, driving high-value licensing deals.
- Film & TV:Licensing music for use in motion pictures, television series, documentaries, and promotional materials, a traditional high-value synchronization source.
- Advertising:Placement of musical compositions in commercials and promotional campaigns across various media.
- Broadcast:Music usage on traditional radio and television programming, a long-standing source of performance royalties.
- Live Events:Performances of musical works in concerts, festivals, and other public gatherings, generating performance royalties.
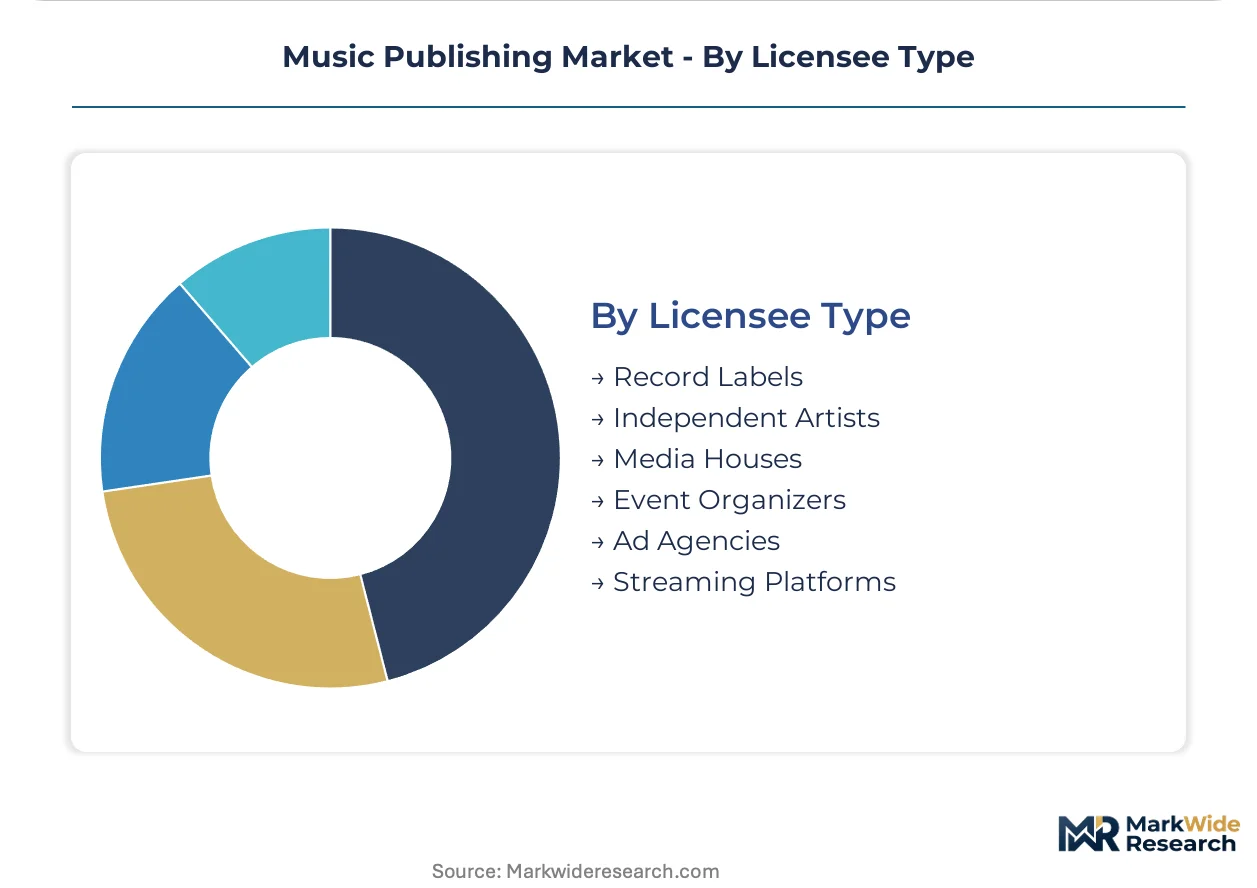
While Streaming Services continues its dominance, Video Games offers substantial high-value opportunities.
Licensee Type:
This category identifies the primary entities that license and utilize musical compositions, highlighting the diverse client base for music publishers.
- Streaming Platforms:Entities like Spotify and Apple Music that license vast catalogs of music for their subscriber and ad-supported services. Demand concentrates in regions with high digital music consumption, reshaping royalty distribution mechanisms.
- Ad Agencies:Companies that license music for use in advertising campaigns, negotiating complex synchronization deals for global brands. Demand concentrates in major advertising markets such as New York and London.
- Record Labels:Companies that produce, market, and distribute sound recordings, often requiring licenses for mechanical and synchronization uses.
- Media Houses:Broadcasters, film studios, and television networks that license music for their content production.
- Independent Artists:Self-releasing musicians who license music for their own projects or collaborate with other artists.
- Event Organizers:Entities responsible for live concerts, festivals, and public gatherings, requiring performance licenses.
The landscape is adapting to the growing influence of Streaming Platforms and the evolving needs of Ad Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's vibrant music industry anchors significant demand for publishing services across Asia. This robust creative ecosystem drives innovation in royalty collection and administration. The country's expanding cultural influence shapes global music consumption patterns.
South Korea
Demand for publishing administration and creative services in South Korea remains high due to K-Pop's global expansion. The country's Ministry of Culture, Sports and Tourism supports cultural content exports, benefiting music rights holders. Seoul functions as a central hub, attracting significant investment in music production and talent development.
United States
Streaming services and synchronization deals in film and television drive substantial revenue in the United States. The Music Modernization Act significantly improved transparency for songwriters regarding mechanical royalties. Nashville and Los Angeles are key creative centers, fostering numerous songwriter partnerships and publishing operations.
Germany
The implementation of the EU's Directive on Copyright in the Digital Single Market strengthens publisher negotiating positions in Germany. GDPR regulations add complexity to royalty data management for international operations. Berlin's vibrant music scene and media production houses contribute to consistent demand for licensing musical works.
United Kingdom
London's competitive creative centers foster holistic publisher-songwriter relationships and strong A&R support. The UK's Intellectual Property Office oversees copyright enforcement, ensuring robust protection for musical compositions. Major advertising markets in London generate high-value synchronization deals for global campaigns.
Brazil
Growth in digital music consumption and live events fuels publishing activity across Brazil. The country's national copyright laws govern the collection and distribution of performance royalties. São Paulo serves as a major music industry hub, attracting investment in new talent and administrative operations.
Music Publishing Market Key Industry Players
Global majors compete with regional champions across catalog breadth and administrative reach within the music publishing market. This industry exhibits a tiered structure, from large integrated publishers to specialized boutique firms and independent administrators. Strategic archetypes include established catalog aggregators, artist-centric service providers, and technology-driven royalty administrators. Dominant competitive moves involve strategic catalog acquisitions and forming strategic partnerships with emerging digital platforms.
Within the global major publisher archetype, Universal Music Publishing Group exemplifies extensive catalog leverage for synchronization deals. Sony Music Publishing occupies a similar position, anchoring its market presence through strategic catalog acquisitions and broad administrative capabilities. BMG Rights Management represents an artist-friendly service provider model, emphasizing transparency and direct relationships with songwriters. These entities collectively shape industry standards for rights management and monetization across diverse platforms.
| Leading Market Players |
|---|
| Kobalt Music Publishing |
| Concord Music Publishing |
| Sony Music Publishing |
| Downtown Music Publishing |
| Primary Wave Music |
| Universal Music Publishing Group |
| BMG Rights Management |
| Hipgnosis Songs Fund |
| Warner Chappell Music |
| Others |
Cost & Logistics Intelligence
Royalty administration fees, a core cost component, flow from digital service providers through Collective Management Organizations to publishers and songwriters. This intricate flow impacts the final compensation received by rights holders across various licensing tiers.
Pricing Analysis
Service-bundling in co-publishing deals provides creative development and A&R support, differentiating from pure administration contracts. The dominant pricing structure is royalty-share based, with publishers taking a percentage of collected income. Price differentiation drivers include catalog size and the level of integrated services offered to songwriters. Pricing softness stems from royalty-free music libraries, making independent artists highly price sensitive, while major film studios seek high-value synchronization.
Supply Chain Analysis
Global data management infrastructure costs represent a significant logistics challenge for publishers tracking millions of digital usages. Supply concentration for musical works administration centers in the United States and the United Kingdom, home to major publishing houses. Raw material dependencies include original musical compositions and robust metadata. Inconsistent global regulations pose a structural risk, leading to administrative overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The music publishing market is in a technology-transition phase, with AI-driven royalty management platforms replacing historically manual collection processes.
For Market Incumbents: Cement market share by investing in advanced AI for royalty data management, ensuring compliance with evolving regulations like GDPR. Diversify catalog acquisition strategies beyond traditional hits, focusing on genres with high synchronization potential in video games. A significant threat is the rise of direct licensing platforms, which bypass traditional publisher services. Leverage existing global administrative reach and deep industry relationships as a lever against new market entrants.
For New Entrants and Emerging Players: Launch via niche content strategies, targeting specific platforms like metaverse experiences or independent game developers. Focus on specialized service models offering enhanced transparency and artist-friendly terms, particularly for emerging songwriters in high-growth markets. The most penetrable segment consists of independent artists and creators seeking more agile administrative support. A key go-to-market angle involves leveraging social media influence to attract new talent and build a community-centric brand.
For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-driven administrators in fragmented European markets, where regulatory complexity creates operational challenges. Long-term viability hinges on acquiring catalogs with enduring value and integrating sophisticated data analytics capabilities. The optimal acquisition target archetype includes boutique publishers with strong genre-specific catalogs or innovative tech solutions. A signal to watch is the consolidation of smaller Collective Management Organizations, indicating increasing efficiency demands.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Royalty Administration | Automates data processing from digital platforms, improving accuracy and reducing operational costs for publishers. |
| Global Catalog Acquisition | Expands revenue streams and market presence by adding diverse musical works across multiple territories. |
| Enhanced A&R Support | Attracts top songwriting talent by offering creative development and career guidance beyond basic administration. |
| Direct Licensing Integration | Provides flexible licensing options for specific uses, catering to evolving content creator needs. |
| Metaverse Content Partnerships | Unlocks new monetization channels for musical works in emerging virtual reality and gaming environments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for market sizing and trend analysis. Primary interviews with publishing executives, songwriters, Collective Management Organization representatives, and digital platform managers provided qualitative insights. This approach combined bottom-up market estimation with top-down validation, ensuring comprehensive data triangulation. Secondary sources included copyright registries, industry financial reports, and academic studies on intellectual property.
Market dimensions such as royalty type, ownership model, usage platform, and licensee type were modeled at a granular level across the analysis window. An industry-specific dimension, regional regulatory clusters, also informed the forecast. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs included streaming subscriber growth projections and video game market expansion rates.
Regulatory shifts, technological disruption, and evolving consumer behavior are the dominant revision risks for market forecasts. These forecasts reflect assumptions about the future trajectory of digital consumption and intellectual property enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Music
Global Free Music Making Software Market
Music
Asia-Pacific Independent Artist Market
Music
Independent Music Publishing Market
Music
Europe Independent Artist Market
Music
Music Distribution Services Market
Music
Vinyl Records Market
Music
Traditional Chinese Instruments Market
Music
Global Stock Music Market
Music
United States Live Music Market
Music
Music App Market
Music
Music Production Software Market
Music
Global in-Store Music Service Market
Music
Musical Groups and Artists Market
Music
Discography Market
Music
Global Background Music Market
Music
Electronic Dance Music (EDM) Market